
 Turmeric Oleoresin Market | 2026-2036
Turmeric Oleoresin Market Size, Share, and Industry Trends Forecast 2026-2036
Turmeric Oleoresin Market Outlook
Direct procurement between extractors and end-user nutraceutical houses is rewriting traditional turmeric oleoresin distribution. Synthite Industries Ltd. leverages backward integration into Kerala turmeric farms to secure raw material consistency. Sabinsa Corporation differentiates through patented bioavailability-enhanced curcuminoid complexes. Kancor Ingredients Ltd. anchors European supply relationships with its BRC-certified extraction facility in Angamaly.
Turmeric oleoresin is a solvent-extracted concentrate containing 30-40% curcuminoids, volatile oils, and resinous matter, obtained from Curcuma longa rhizomes and standardized for color value and curcumin content. The extract serves primarily as a natural colorant and bioactive additive across food, pharmaceutical, and cosmetic matrices. Organic product type commands premium positioning as clean-label formulations displace synthetic dyes in European and North American retail channels. Dietary supplements application leads volume absorption, while food and beverage maintains steadier margin pools due to long-term supply contracts with multinational processors.
India's FSSAI mandates residual solvent limits for oleoresin extraction, compelling processors to shift from hexane toward ethanol and supercritical CO2 methods. The EU REACH framework and EFSA Novel Food evaluations govern import access for curcuminoid concentrates into European nutraceutical supply chains. Stakeholders must monitor evolving maximum residue levels for extraction solvents across multiple jurisdictions, as regulatory divergence between FDA dietary supplement guidelines and EU food additive classifications threatens to fragment product registration pathways.
Market Dynamics
India's PLI scheme for food processing and herbal products is accelerating extraction capacity expansion, while FSSAI solvent limits force processors toward ethanol and supercritical CO2 methods, compressing legacy hexane-based operations.
Growth Catalysts
- Clean-label mandates:EFSA Novel Food evaluations and EU REACH framework are tightening synthetic dye restrictions, pulling turmeric oleoresin into European nutraceutical and food additive formulations.
- Kerala-Karnataka cluster density:Raw turmeric availability overlaps with solvent extraction infrastructure in these Indian states, reducing logistics friction for curcuminoid concentrate output.
- Functional formulation pull:Dietary supplement houses are expanding direct procurement of curcumin-rich extracts, bypassing traditional distribution tiers.
Market Restraints
- Input cost volatility:Turmeric rhizome prices fluctuate with monsoon patterns in Karnataka and Tamil Nadu, squeezing processor margins during poor harvest cycles.
- Supply concentration risk:Over 70% of global oleoresin extraction capacity sits within 200 kilometers of Kochi, creating single-point vulnerability to regional climate or logistics disruption.
- Regulatory friction:Divergence between FDA dietary supplement guidelines and EU food additive classifications fragments product registration pathways, forcing dual compliance costs.
Strategic Opportunities
- Underpenetrated North American organic channel:USDA organic certification gaps in Indian extraction facilities leave premium positioning open for BRC- or FSSC 22000-certified entrants.
- Cosmetic matrix expansion:K-beauty and clean skincare brands in South Korea and Japan are testing curcuminoid complexes for anti-inflammatory topical applications.
- Supercritical CO2 technology convergence:Combining ethanol extraction with CO2 finishing is yielding solvent-free concentrates that qualify for EU organic cosmetics labeling.
Industry Challenges
- Analytical chemist scarcity:Curcuminoid standardization and residual solvent testing require HPLC-UV and GC-MS expertise that Kerala's processing clusters struggle to retain.
- Certification timeline compression:BRC and FSSC 22000 audits for European retail access demand 12-18 month preparation cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turmeric Oleoresin Market |
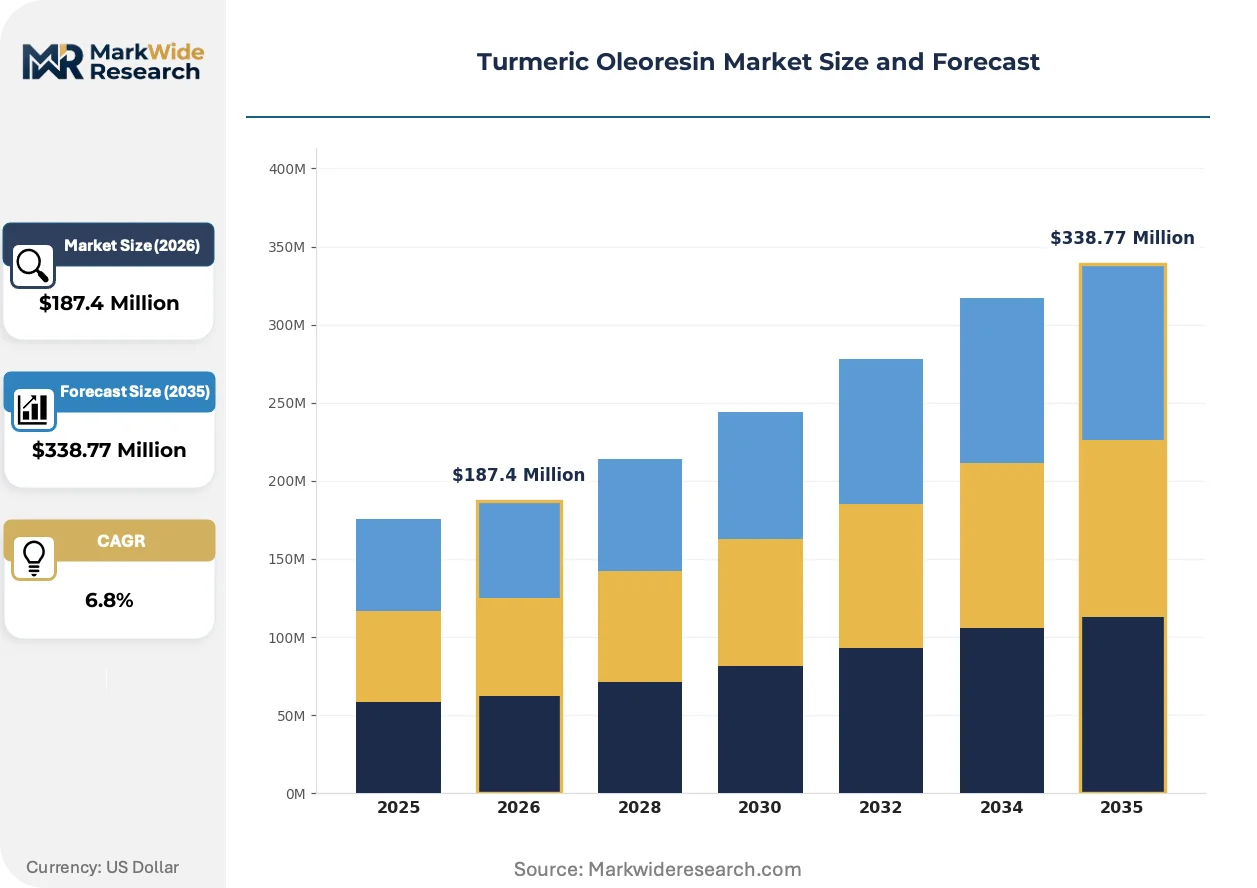
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Standardized, Food Grade, Cosmetic Grade Application: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements End User: Food Manufacturers, Cosmetic Companies, Nutraceutical Firms, Healthcare Providers Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Synthite Industries Ltd., Universal Oleoresins, Sabinsa Corporation, Kancor Ingredients Ltd., Arjuna Natural Extracts Ltd., Akay Group Ltd., Plant Lipids, MANE Kancor, OmniActive Health Technologies Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turmeric Oleoresin Market Strategic Shifts
Extraction technology and regulatory chemistry are converging to displace hexane-based methods, while procurement relationships compress traditional distribution layers and clean-label certification becomes a non-negotiable filter for market access.
Supercritical CO2 extraction systems are penetrating mid-scale Indian processors, extracting curcuminoids without residual solvent concerns. European nutraceutical houses are specifying CO2-derived concentrates in procurement contracts. Hexane-reliant infrastructure is rendering obsolete as FSSAI enforcement tightens and EU import rejections accumulate.
REACH registration requirements for curcuminoid concentrates are tightening substance documentation and safety data obligations. Indian exporters are consolidating testing partnerships with EU-based laboratories to preempt ECHA compliance gaps. Dietary supplement applications face the steepest documentation burden, while food additive classifications trigger separate EFSA evaluations.
Direct contracting between Kerala extraction facilities and North American supplement brands is displacing Mumbai-based trading houses. Long-term offtake agreements with fixed curcuminoid specifications are replacing spot market purchases. This pattern concentrates in US West Coast nutraceutical clusters where formulation houses prioritize supply chain transparency.
Turmeric Oleoresin Market Segmentation
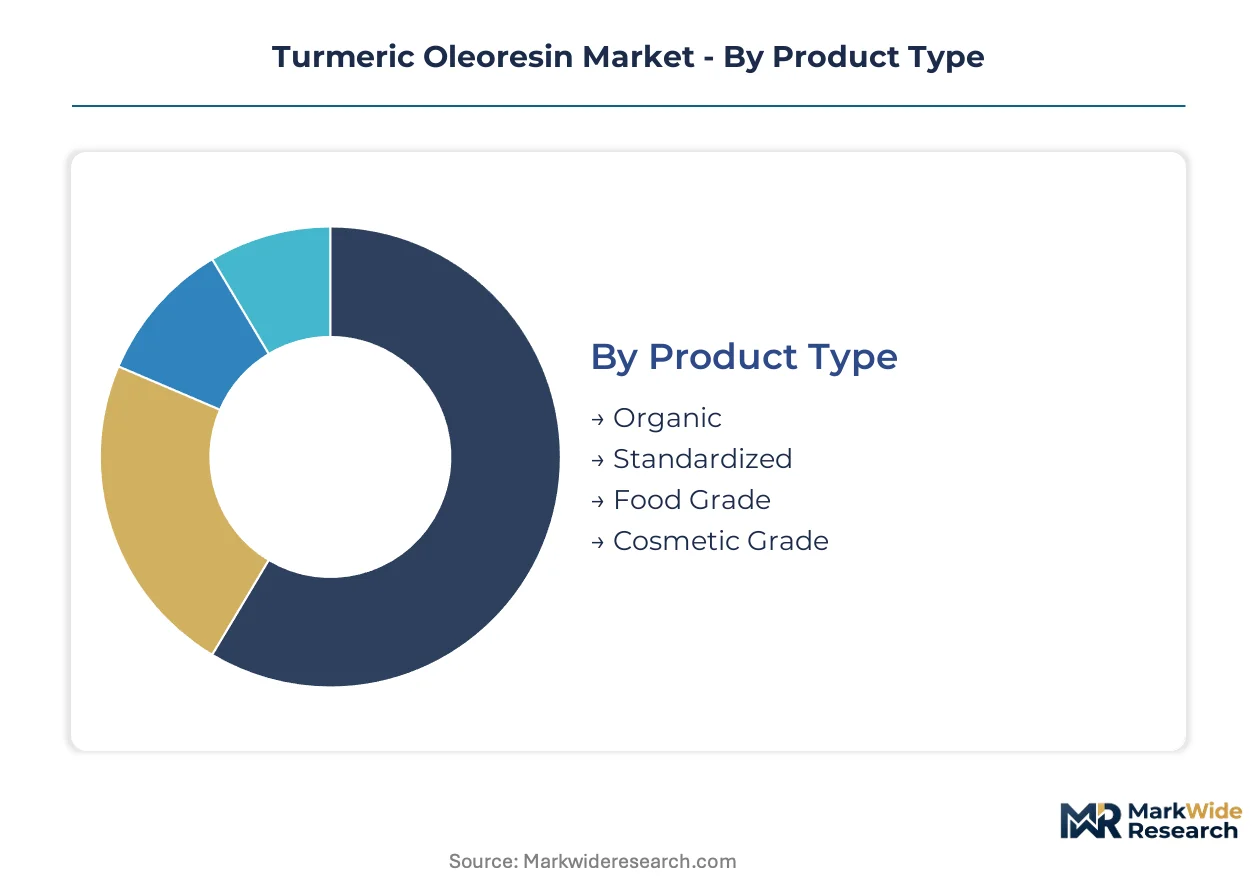
Turmeric oleoresin segmentation reflects divergent purity standards and end-use specifications. Clean-label certification tiers and extraction method choices fragment procurement patterns across food, pharmaceutical, and cosmetic channels.
Product Type:
Product differentiation tracks certification burden and extraction technology investment, with premium tiers commanding solvent-free processing and traceable farm origins.
- Organic:USDA and EU organic certification requires ethanol or supercritical CO2 extraction without synthetic pesticide residues. Kerala processors with BRC-certified facilities capture premium positioning in North American natural retail channels where clean-label mandates displace conventional alternatives.
- Standardized:Curcuminoid content fixed at 30-40% through batch blending serves pharmaceutical and nutraceutical houses requiring consistent bioactive dosing. Long-term supply contracts with European supplement manufacturers anchor volume absorption for this specification tier.
- Food Grade:Color value standardization dominates specification sheets for multinational food processors replacing synthetic dyes.
- Cosmetic Grade:Low residual solvent thresholds and heavy metal compliance enable K-beauty and clean skincare formulations.
Established volume favors Standardized; emerging adoption favors Organic.
Application:
Application segmentation maps to regulatory pathway complexity and margin structure, with pharmaceutical and supplement channels facing steepest documentation burdens.
- Dietary Supplements:Curcuminoid concentrates with enhanced bioavailability formulations drive procurement from US West Coast nutraceutical clusters. Direct contracting between Kerala extraction facilities and formulation houses is displacing traditional Mumbai-based trading tiers.
- Food & Beverage:Natural colorant demand from European processors responding to EFSA synthetic dye restrictions maintains steadier margin pools through multi-year supply agreements.
- Pharmaceuticals:CDSCO and FDA drug master file requirements limit eligible suppliers to GMP-certified extraction operations.
- Cosmetics:Anti-inflammatory topical applications in South Korea and Japan are testing curcuminoid complexes for clean beauty positioning.
Margin stability concentrates in Food & Beverage; formulation innovation concentrates in Dietary Supplements.
End User:
End user categories reflect procurement sophistication tiers, from specification-heavy nutraceutical houses to volume-driven food manufacturers.
- Nutraceutical Firms:Direct procurement of curcumin-rich extracts with fixed curcuminoid specifications and residual solvent documentation. These buyers prioritize supply chain transparency and audit-ready certification packages over spot market flexibility.
- Food Manufacturers:Long-term offtake agreements with multinational processors anchor volume absorption for standardized color value specifications.
- Cosmetic Companies:EU organic cosmetics labeling requirements are pulling solvent-free concentrates from supercritical CO2-equipped facilities.
- Healthcare Providers:Institutional procurement of standardized extracts for compounding pharmacies remains fragmented across regional distributors.
Contract sophistication favors Nutraceutical Firms; procurement scale favors Food Manufacturers.
Distribution Channel:
Channel structure is compressing as direct relationships displace intermediary layers, particularly in premium specification tiers.
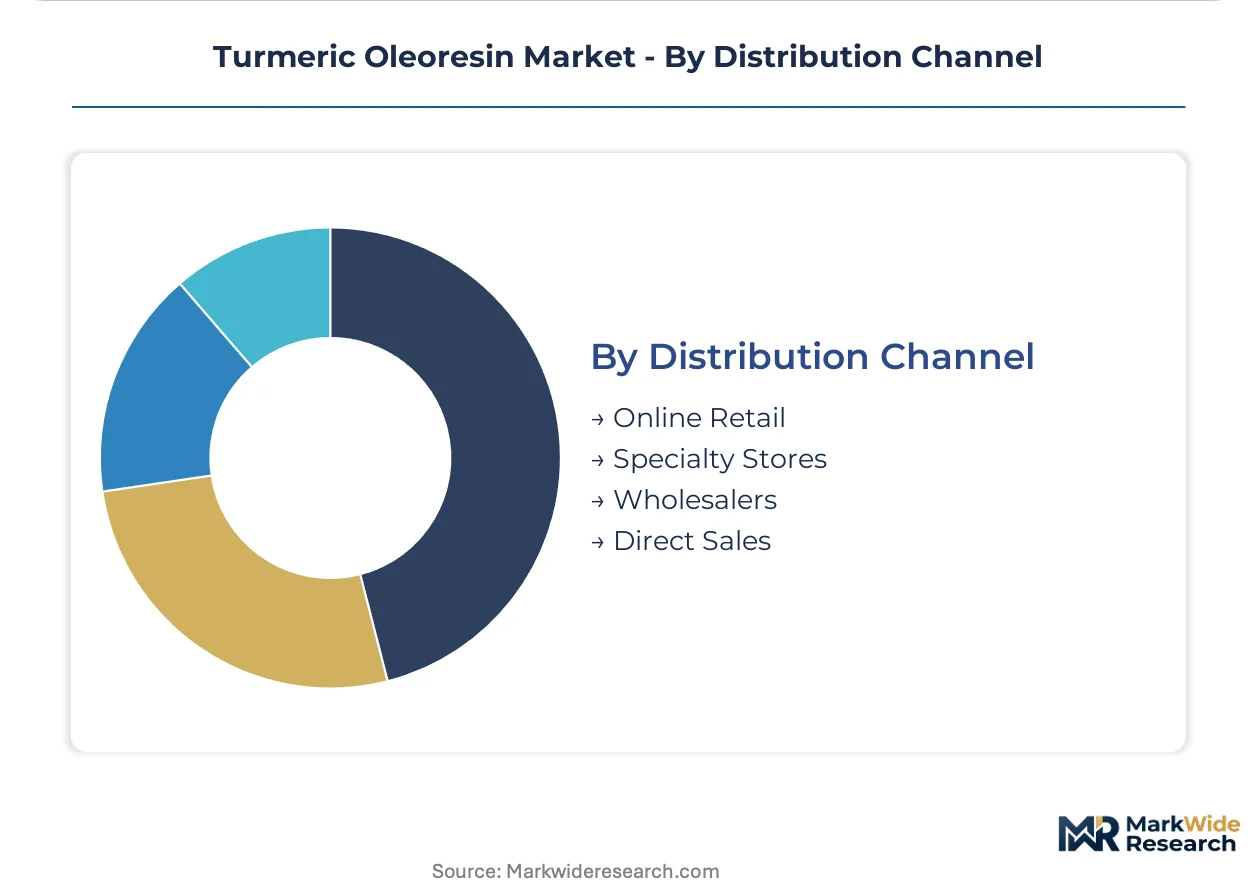
- Direct Sales:Long-term offtake agreements between Kerala extraction facilities and North American supplement brands eliminate Mumbai trading house margins. Fixed curcuminoid specifications and transparent farm-to-facility traceability command procurement preference.
- Wholesalers:Spot market purchases and smaller volume orders from regional food processors sustain this channel for conventional grade material.
- Online Retail:Branded curcuminoid supplements and small-batch cosmetic ingredients reach clean-label consumers through platform distribution.
- Specialty Stores:Natural product retailers in European and North American urban centers stock organic-certified extracts for DIY formulation customers.
Relationship depth favors Direct Sales; geographic reach favors Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Kochi anchors India's turmeric oleoresin export infrastructure, handling concentrated bulk shipments to European and North American nutraceutical buyers. Containerized cold-chain connectivity from Kerala processing clusters to Rotterdam and Hamburg underwrites just-in-time delivery contracts.
India
Kerala and Karnataka host overlapping turmeric cultivation belts and solvent extraction infrastructure. FSSAI residual solvent limits are accelerating processor migration from hexane toward ethanol and supercritical CO2 methods. The Angamaly processing corridor near Kochi concentrates BRC-certified facilities serving European supplement houses.
United States
West Coast nutraceutical formulation clusters in California and Oregon drive direct procurement of curcuminoid concentrates. FDA dietary supplement guidelines govern import documentation, diverging from EU food additive classifications. Long-term offtake agreements with Kerala extractors are displacing traditional trading intermediaries.
Germany
EFSA Novel Food evaluations and REACH registration requirements filter market access for curcuminoid concentrates. Hamburg and Rotterdam serve as entry points for Indian oleoresin shipments destined for European pharmaceutical and food additive channels. ECHA compliance documentation demands are consolidating testing partnerships with EU-based laboratories.
Japan
Tokyo and Osaka formulation houses are testing curcuminoid complexes for anti-inflammatory topical applications in K-beauty-influenced skincare. METI standards and PMDA cosmetic ingredient notifications govern import pathways. Supercritical CO2-derived concentrates qualify for premium clean beauty positioning.
South Korea
Seoul-based cosmetic brands are expanding procurement of solvent-free curcuminoid extracts for functional skincare lines. MFDS cosmetic ingredient safety assessments align with EU organic cosmetics labeling requirements. Direct supplier relationships with Indian CO2-equipped processors are shortening procurement cycles.
Turmeric Oleoresin Market Competitive Environment
On the supply side, the industry is consolidating around backward-integrated extractors with captive farm networks and certified processing infrastructure. Kerala-based operators with BRC and FSSC 22000 credentials capture premium positioning in European and North American channels. Three archetypes dominate: plantation-integrated processors controlling raw material consistency, technology-specialized firms deploying supercritical CO2 systems, and trading houses pivoting toward specification-heavy direct contracting. Capacity expansion and certification upgrading represent the dominant competitive moves, as hexane-reliant infrastructure renders obsolete.
Among Kerala-anchored plantation-integrated processors, Synthite Industries Ltd. exemplifies backward integration into turmeric cultivation belts. Sabinsa Corporation occupies a position within the technology-specialized tier, representing patent-protected bioavailability enhancement approaches. Kancor Ingredients Ltd. anchors European supply relationships through certified extraction infrastructure, sitting within the quality-certification archetype.
| Leading Market Players |
|---|
| Synthite Industries Ltd. |
| Universal Oleoresins |
| Sabinsa Corporation |
| Kancor Ingredients Ltd. |
| Arjuna Natural Extracts Ltd. |
| Akay Group Ltd. |
| Plant Lipids |
| MANE Kancor |
| OmniActive Health Technologies Ltd. |
| Others |
Value Chain & Pricing Dynamics
Kochi processing corridor capacity concentration grants Kerala extractors outsized leverage in curcuminoid concentrate negotiations. Long-term offtake agreements with North American nutraceutical houses now command premium terms over Mumbai trading intermediaries, while hexane-reliant facilities face margin compression from FSSAI solvent enforcement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BRC-certified organic CO2 extracts from conventional ethanol grades and residual hexane material. Price differentiation hinges on certification tier and curcuminoid standardization precision, with organic-certified CO2 concentrates capturing widest spreads. Cost compression in conventional grades is intensifying because FSSAI residual solvent limits are rendering legacy hexane infrastructure obsolete. Food manufacturers exhibit highest price sensitivity due to volume-scale procurement, while nutraceutical firms prioritize specification consistency over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Kerala plantation-integrated processors and Angamaly corridor extraction facilities. Geographic supply concentration centers on India, with secondary capacity in Germany and Japan for pharmaceutical-grade finishing. Raw material dependencies draw from Karnataka and Tamil Nadu turmeric belts, ethanol solvent networks, and supercritical CO2 equipment imports. Single-source vulnerability concentrates within 200 kilometers of Kochi, exposing buyers to regional climate disruption. Distribution runs through direct sales relationships displacing Mumbai-based trading tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward West Coast nutraceutical clusters as direct procurement consolidates around specification-heavy long-term contracts. Fragmentation among Mumbai trading intermediaries accelerates this consolidation.
For Market Incumbents: Build backward integration moats into Kerala turmeric cultivation belts to secure raw material consistency against monsoon-driven price volatility. Sabinsa Corporation's patent-protected bioavailability enhancement and Synthite Industries Ltd.'s captive farm networks demonstrate defensible positioning. Incumbents must accelerate supercritical CO2 capacity conversion before FSSAI enforcement renders hexane infrastructure stranded. Certification investment in BRC and FSSC 22000 credentials locks European retail access against emerging CO2-equipped competitors. For New Entrants and Emerging Players: North American organic channel underpenetration offers viable entry path for ethanol or CO2-equipped processors with USDA certification. Premium positioning in clean-label nutraceutical formulations remains accessible given certification gaps in existing Indian facilities. Cosmetic matrix expansion into South Korean and Japanese K-beauty applications presents secondary white space with lower regulatory barriers than pharmaceutical channels. Go-to-market angle should emphasize solvent-free processing and transparent farm traceability to match West Coast formulation house procurement criteria. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated processors with captive supply and long-term offtake agreements. Long-term viability across the analysis window favors technology-specialized firms deploying supercritical CO2 systems over hexane-reliant legacy assets. Acquisition target archetype: mid-scale Kerala processors with organic certification potential and underutilized CO2 capacity. Signal to watch is EFSA Novel Food evaluation backlog clearing, which would unlock European pharmaceutical channel access for compliant Indian exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Conversion | FSSAI residual solvent limits and EU import rejections are rendering hexane extraction obsolete. |
| Backward Integration into Turmeric Cultivation | Synthite Industries Ltd.'s Kerala farm networks demonstrate raw material consistency advantages. |
| BRC/FSSC 22000 Certification Investment | European retail access requires 12-18 month audit preparation cycles that delay competitor entry. |
| Direct Sales Channel Development | Long-term offtake agreements with North American supplement brands eliminate Mumbai trading margins. |
| Cosmetic Grade Expansion | South Korean and Japanese K-beauty brands are testing curcuminoid complexes for anti-inflammatory positioning. |
Study Parameters
Operator-level perspectives from extraction facility managers, nutraceutical procurement leads, Kerala plantation operators, and EFSA regulatory consultants anchored the qualitative base. Primary interviews with BRC audit specialists and supercritical CO2 equipment suppliers cross-referenced against FSSAI compliance filings, EU REACH registration databases, US FDA dietary supplement import alerts, and Indian customs trade data. Bottom-up volume estimates from Kerala processing clusters triangulated with top-down demand modeling from North American and European end-use channels.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation dimensions spanning extraction technology tier, certification grade, application channel, and geographic regulatory cluster. CAGRs derived from volume trajectory modeling anchored in Kerala capacity expansion timelines and end-user procurement pattern shifts. Industry-specific forecast inputs incorporated FSSAI enforcement intensity assumptions and EFSA Novel Food evaluation pipeline clearance rates.
Practitioners should monitor FSSAI solvent limit enforcement intensity, EFSA evaluation backlog duration, and Karnataka monsoon deviation indices for early signals of forecast revision. Quarterly review of Kerala processing cluster capacity utilization, EU import rejection rates for residual solvent violations, and North American direct procurement contract announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Onion Essential Oil Market