
 Organic Saffron Market | 2026-2036
Organic Saffron Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Saffron Market Outlook
Certified origin subscription programs is recalibrating how bulk saffron converts into recurring revenue streams. Tarvand Saffron Co. leverages direct-to-chef channels in European hospitality to sustain premium pricing for its Super Negin grades. Mehr Saffron Company anchors its competitive position through backward integration into organic crocus farming in Iran's Razavi Khorasan belt. Pure Indian Foods differentiates by controlling small-batch dehydration protocols that preserve crocin concentration for North American Ayurvedic buyers.
Organic saffron comprises the dried stigmas of Crocus sativus L. cultivated without synthetic pesticides or fertilizers, with premium grades exceeding 250 nm crocin absorbance and 30% safranal by HPLC assay. The spice functions primarily as a natural colorant, flavoring agent, and bioactive compound source across food, pharmaceutical, and cosmetic applications. Super Negin threads command the deepest margin pools due to their intact stigma structure and highest crocin retention, while pharmaceutical-grade Sargol extracts gain traction from standardized apocarotenoid demand. The hospitality end-user segment shows structural momentum as Michelin-starred kitchens adopt transparent provenance sourcing, though online retailers now capture growing volume through subscription-based replenishment models.
Iran's national standardization body enforces organic saffron grading under INSO standards, while the EU's REACH and organic regulations mandate residue testing for imported spice batches. The US FDA and USDA National Organic Program jointly govern labeling claims and import certification for American distribution. Stakeholders must monitor evolving pesticide maximum residue limits across destination markets and pre-emptively align cultivation protocols with multiple jurisdictional standards before supply commitments solidify.
Market Dynamics
Certification arbitrage between Iran's INSO standards and EU Regulation 2018/848 traceability mandates is fragmenting procurement workflows and forcing dual-track compliance investments across the value chain.
Growth Catalysts
- EU organic certification tightening:REACH residue testing requirements under EU Regulation 2018/848 are filtering non-compliant Iranian exporters and consolidating premium volume among certified cultivators in Razavi Khorasan.
- Pharmaceutical standardization:HPLC assay protocols for crocin and safranal quantification are enabling apocarotenoid-based drug formulations to displace synthetic colorants in dermatological applications.
- South Korean cosmetic demand:MFDS-registered skincare manufacturers in Seoul are specifying Super Negin grades for melanin-inhibition products, creating a high-margin pull channel distinct from food service.
Market Restraints
- Input cost volatility:Manual stigma harvesting requires 150,000 flowers per kilogram, locking labor costs to Iranian agricultural wage floors with no mechanization pathway.
- Supply concentration risk:Over 85% of certified organic cultivation clusters within Iran's Khorasan province expose buyers to sanctions-linked payment friction and logistics disruption.
- Regulatory friction:Divergent maximum residue limits between USDA National Organic Program and EU REACH create batch rejection risk at destination ports.
Strategic Opportunities
- Underpenetrated North American Ayurvedic channel:Small-batch dehydration protocols preserving crocin concentration are capturing premium positioning among integrative medicine practitioners in California and New York.
- Subscription replenishment models:Direct-to-chef platforms in European hospitality are converting bulk procurement into recurring revenue with transparent provenance documentation.
- Technology convergence:Blockchain traceability layers combined with spectroscopic origin verification are enabling real-time batch authentication for pharmaceutical buyers.
Industry Challenges
- Cultivation skill scarcity:Corm propagation expertise and organic pest management knowledge are concentrated among aging farmers in Iran's Torbat-e Heydarieh district with limited generational transfer.
- Certification timeline compression:Three-year organic conversion periods and multi-jurisdictional audit requirements delay revenue recognition for new entrants.
- Dehydration capex intensity:Controlled-temperature processing infrastructure for crocin preservation requires specialized equipment beyond traditional solar drying methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Saffron Market |
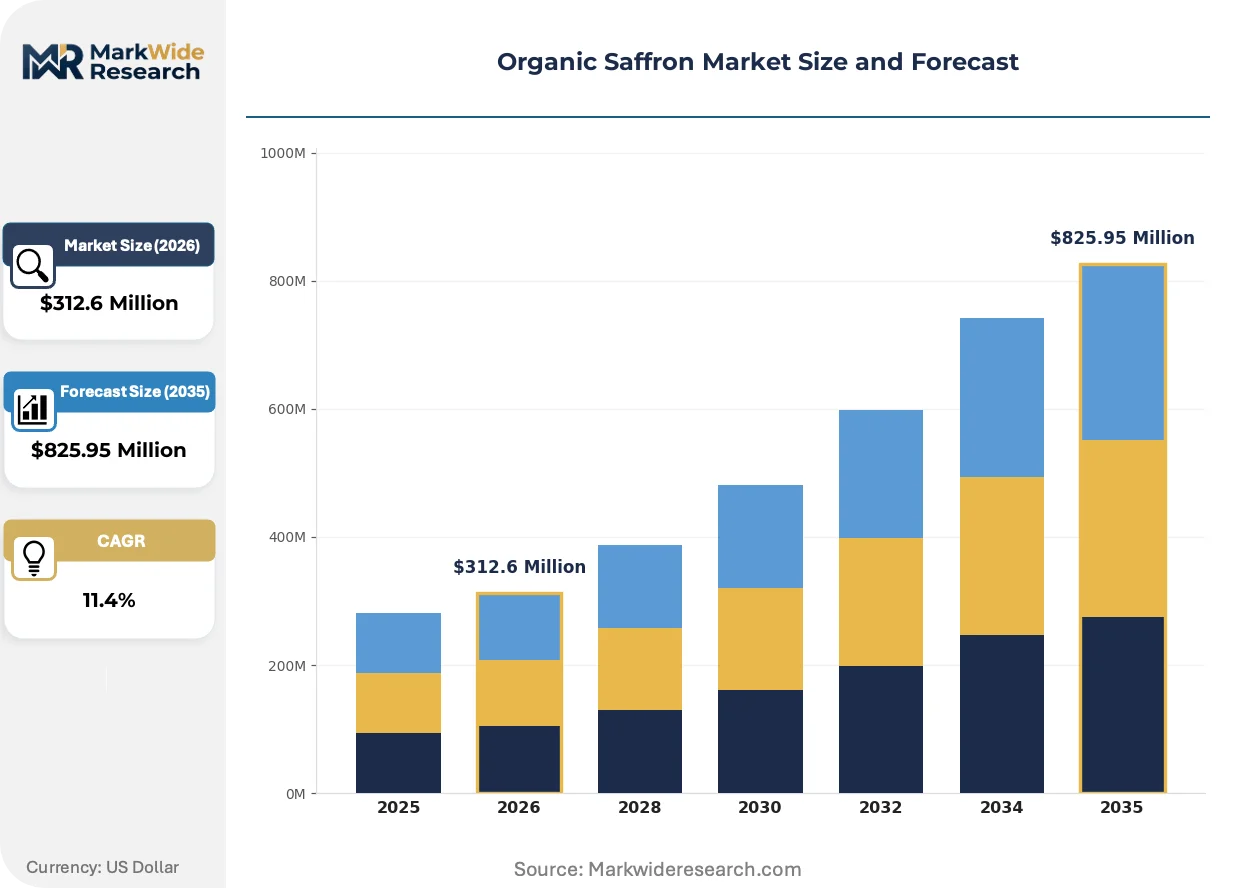
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $825.95 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Super Negin, Negin, Sargol, Pushal End User: Food Industry, Pharmaceutical, Cosmetics, Hospitality Distribution Channel: Online Retailers, Wholesalers, Supermarkets, Specialty Stores Packaging Type: Glass Jars, Tins, Sachets, Bulk Packaging |
| Companies Covered | HEA&Co (SunBrand), Tarvand Saffron Co., Esfedan Saffron Co., Pure Indian Foods, Safrante Global Company S.L.U., Flora Saffron (ATDM Co.), Mehr Saffron Company, Organic Spree, Gauhar Saffron Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Saffron Market Strategic Shifts
Spectroscopic authentication and blockchain provenance systems are displacing paper-based certification, while pharmaceutical-grade extraction protocols reshape quality benchmarks away from traditional food-service grading.
Near-infrared spectroscopy for real-time crocin quantification is absorbing quality assurance functions previously handled by laboratory HPLC analysis. European pharmaceutical manufacturers are adopting handheld devices for incoming batch verification, compressing release timelines from days to hours. This technology is absorbing margin from third-party testing laboratories while shifting liability to cultivators for pre-shipment certification.
EU Regulation 2018/848 traceability mandates are forcing batch-level digital records from field to fork. Iranian exporters must now document corm source, harvest date, and processing facility for each kilogram, with EFSA-aligned residue testing required at EU border inspection posts. Smallholder cooperatives in Khorasan are consolidating to share compliance infrastructure costs, accelerating cooperative formation.
Michelin-starred kitchens are demanding chef-facing provenance platforms with harvest-date specificity and cultivator identity disclosure. Direct sourcing contracts are displacing traditional spice merchant intermediaries in London, Paris, and Copenhagen, with subscription replenishment models capturing recurring volume. This shift is most visible in Nordic gastronomy, where Noma-alumni restaurants specify single-origin saffron with complete chain-of-custody documentation.
Organic Saffron Market Segmentation
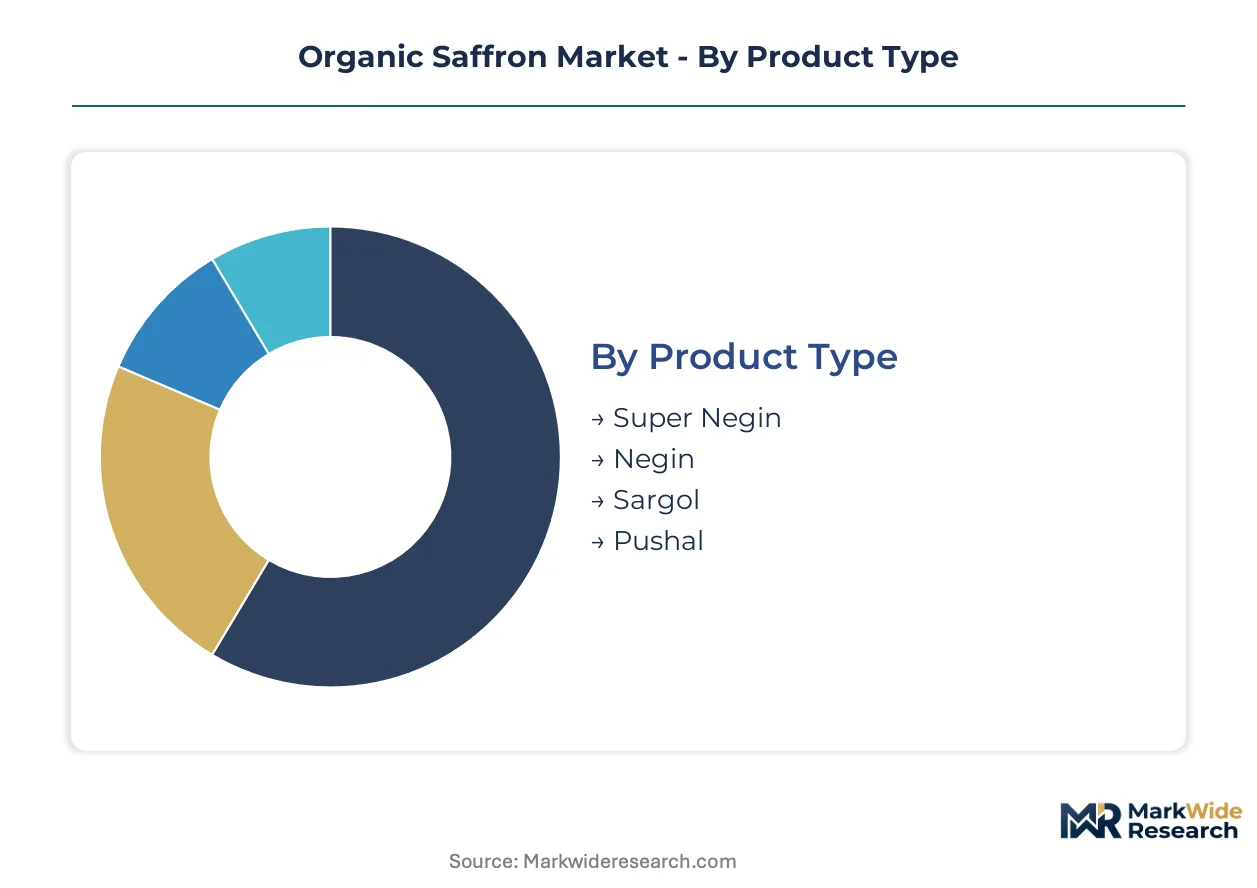
Organic saffron segmentation reflects a fundamental tension between artisanal harvest grades and industrial-scale extraction. Each dimension—product grade, end-use application, channel structure, and packaging format—carries distinct margin profiles and compliance burdens that reshape procurement strategy across buyer categories.
Product Type:
Volume flows through lower grades for food manufacturing, while premium tiers concentrate in pharmaceutical and cosmetic specifications demanding verified crocin thresholds.
- Super Negin:Intact stigmas with zero yellow style attachment and crocin absorbance exceeding 250 nm. Seoul-based MFDS-registered cosmetic manufacturers specify this grade for melanin-inhibition formulations, locking supply through annual contracts with Razavi Khorasan cooperatives.
- Negin:Near-complete stigma strands with minimal style content and safranal concentration above 20%. European hospitality procurement through chef-facing platforms prioritizes this tier for visual presentation in Michelin-starred kitchens.
- Sargol:Separated red stigma tips without style, optimized for pharmaceutical extraction where standardized apocarotenoid yield matters more than thread aesthetics.
- Pushal:Stigmas with attached yellow style, commanding lower unit economics but serving price-sensitive food industry colorant requirements.
Mature deployment sits with Sargol for pharmaceutical standardization. Newer deployment is concentrated in Super Negin for South Korean cosmetic applications.
End User:
Application-driven demand splits between commodity colorant buyers and bioactive compound specifiers with divergent certification requirements.
- Food Industry:Bulk processors of rice, confectionery, and dairy products requiring consistent color stability. REACH-aligned residue testing under EU Regulation 2018/848 filters supplier pools for European manufacturing.
- Pharmaceutical:HPLC-verified crocin and safranal quantification enables apocarotenoid-based dermatological formulations displacing synthetic alternatives. Near-infrared spectroscopy now compresses incoming batch release timelines from days to hours.
- Cosmetics:MFDS-registered manufacturers in Seoul specify Super Negin grades for premium skincare, creating a demand channel distinct from food service with distinct margin structures.
- Hospitality:Transparent provenance documentation and harvest-date specificity now standard for Nordic gastronomy procurement, with subscription replenishment models capturing recurring volume from Noma-alumni restaurants.
Established volume anchors in food industry colorant applications. Steepest expansion trajectory is visible in pharmaceutical standardization for dermatological actives.
Distribution Channel:
Channel selection determines traceability depth and margin capture, with direct platforms displacing traditional merchant intermediaries in premium tiers.
- Online Retailers:Subscription-based replenishment models with transparent provenance documentation. Blockchain-enabled batch authentication is absorbing quality assurance functions from third-party laboratories.
- Wholesalers:Traditional spice merchants facing margin compression as chef-facing platforms consolidate European hospitality volume.
- Supermarkets:Mass-market retail with limited origin disclosure, serving price-sensitive consumers without certification requirements.
- Specialty Stores:Ayurvedic practitioners in California and New York sourcing small-batch dehydrated product with preserved crocin concentration.
Longstanding procurement runs through wholesaler networks. Accelerating shift is concentrated in online retailer subscription models with embedded traceability.
Packaging Type:
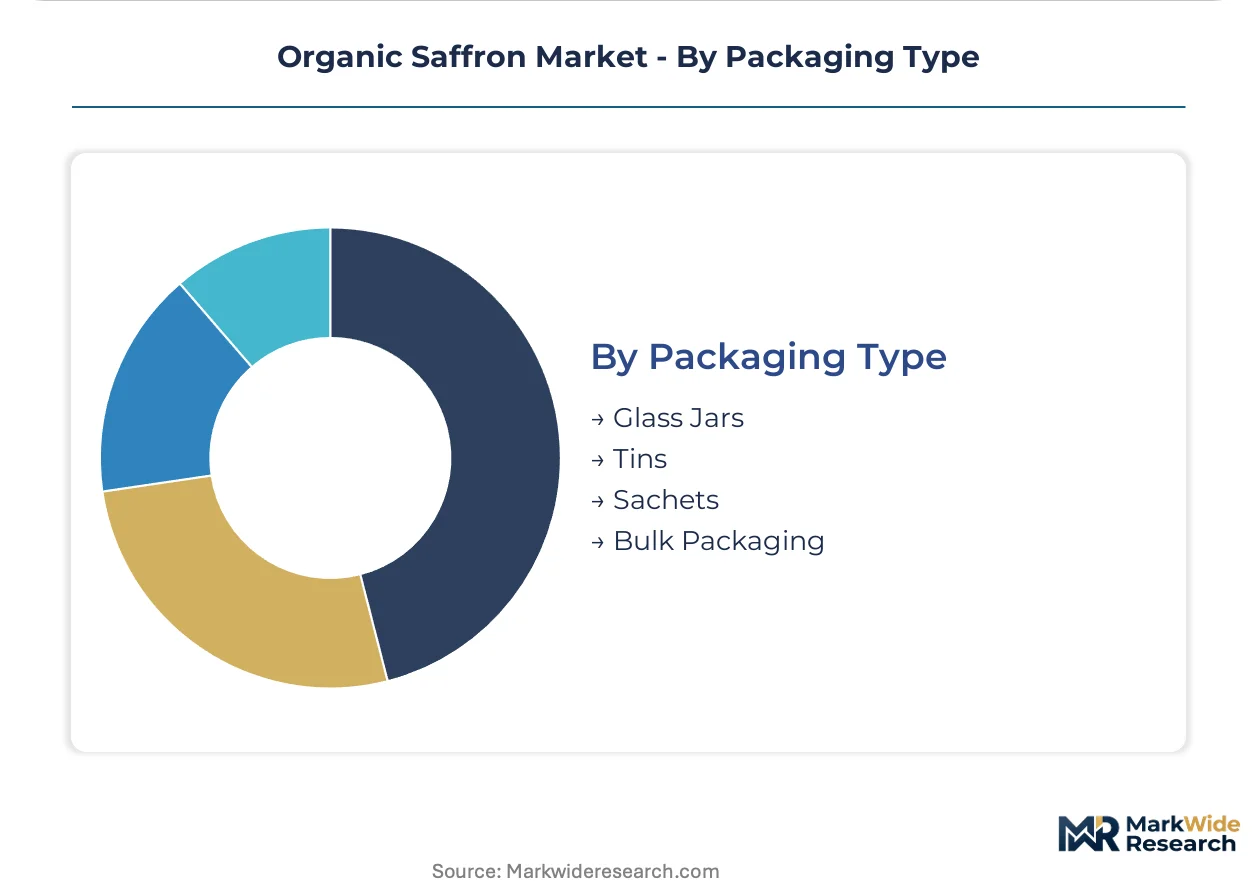
Packaging economics correlate with oxidation protection needs and end-use scale, from individual sachet convenience to pharmaceutical bulk extraction.
- Glass Jars:Premium retail presentation with UV protection for crocin preservation. European specialty retailers and North American Ayurvedic channels specify this format.
- Tins:Traditional hospitality procurement with resealable properties for kitchen inventory management.
- Sachets:Single-serve convenience for food service portion control and airline catering specifications.
- Bulk Packaging:Pharmaceutical and food industry extraction inputs where atmospheric exposure is managed through immediate processing.
Conventional preference rests with tins for hospitality inventory. Emerging specification is concentrated in glass jars for premium retail and practitioner channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iran harvests over 85% of certified organic saffron yet consumes minimal volumes domestically, while South Korea and Germany import premium grades for cosmetic and pharmaceutical processing. This production-consumption asymmetry shapes trade flows, certification requirements, and pricing power across destination markets.
Iran
Razavi Khorasan province hosts the densest concentration of certified organic crocus cultivation, with Torbat-e Heydarieh and Gonabad districts supplying Super Negin grades to Seoul-based cosmetic manufacturers. INSO standards govern domestic grading, though exporters must simultaneously satisfy EU REACH residue testing and USDA National Organic Program traceability mandates. Khorasan cooperatives are consolidating to share blockchain-enabled compliance infrastructure costs.
South Korea
MFDS-registered skincare manufacturers in Seoul specify Super Negin saffron for melanin-inhibition formulations, creating a high-margin demand channel distinct from food service. The Korean Ministry of Food and Drug Safety enforces strict import documentation for botanical actives used in functional cosmetics. Gangnam-based formulation labs now require harvest-date specificity and cultivator identity disclosure in supplier contracts.
Germany
Pharmaceutical manufacturers in Frankfurt and Leverkusen utilize HPLC-verified Sargol grades for apocarotenoid-based dermatological actives displacing synthetic colorants. ECHA's REACH framework mandates comprehensive residue testing at EU border inspection posts, filtering non-compliant Iranian batches. Bavarian extraction facilities are adopting near-infrared spectroscopy for real-time incoming batch verification.
United States
North American Ayurvedic practitioners in California and New York source small-batch dehydrated saffron with preserved crocin concentration from specialty importers. The FDA and USDA National Organic Program jointly govern labeling claims and import certification, with divergent maximum residue limits creating batch rejection risk at ports of entry. Los Angeles-based integrative medicine clinics now specify glass jar packaging with UV protection.
Spain
La Mancha cultivators compete with Iranian imports on EU Regulation 2018/848 traceability compliance rather than volume scale. The Spanish Agency for Food Safety and Nutrition enforces organic certification standards aligned with EFSA residue limits. Toledo-based cooperatives are investing in controlled-temperature dehydration infrastructure to preserve crocin concentration for pharmaceutical buyers.
Organic Saffron Market Competitive Environment
Capital-heavy producers with captive farming operations compete with asset-light traders sourcing through cooperative networks. The vendor base stratifies across three tiers: integrated cultivator-processors commanding premium pricing, regional exporters managing compliance complexity, and specialty importers serving niche practitioner channels. Consolidation pressure is mounting as dual-track certification investments favor scaled players with multi-jurisdictional audit capabilities. Cooperative formation in Khorasan and direct-to-chef platform expansion in European hospitality represent the dominant competitive moves reshaping channel control.
Among Iran-based integrated producers, Tarvand Saffron Co. and Mehr Saffron Company exemplify the backward-integrated archetype with captive organic crocus farming in Razavi Khorasan. Pure Indian Foods occupies a distinct position among North American specialty importers, representing the small-batch dehydration protocol segment serving Ayurvedic practitioner channels. These three entities anchor the competitive landscape across production concentration, compliance infrastructure, and niche channel penetration respectively.
| Leading Market Players |
|---|
| HEA&Co (SunBrand) |
| Tarvand Saffron Co. |
| Esfedan Saffron Co. |
| Pure Indian Foods |
| Safrante Global Company S.L.U. |
| Flora Saffron (ATDM Co.) |
| Mehr Saffron Company |
| Organic Spree |
| Gauhar Saffron Co. |
| Others |
Value Chain & Pricing Dynamics
Near-infrared spectroscopy deployment for real-time crocin quantification is compressing quality assurance timelines from days to hours while simultaneously shifting cost burdens upstream to cultivators and consolidating procurement power among pharmaceutical buyers with in-house verification capabilities.
Pricing Analysis
Margin tightening in Super Negin grades reflects Seoul-based MFDS-registered cosmetic manufacturers locking annual contracts with Razavi Khorasan cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade Super Negin from food-service Negin and bulk colorant Pushal. Cost-down pressure on standard grades accelerates because Iranian agricultural wage floors for manual stigma harvesting lack mechanization alternatives. Food industry buyers exhibit highest price sensitivity; cosmetic formulators show least sensitivity given melanin-inhibition product margins.
Supply Chain Analysis
Freight cost volatility from Iran through EU border inspection posts is amplifying landed price uncertainty for German pharmaceutical manufacturers. Supply concentrates in Iran, Spain, and Afghanistan for certified organic cultivation. Corm propagation stock, agricultural labor pools, and controlled-temperature dehydration equipment constitute critical input dependencies. Single-source vulnerability from over 85% Iranian production exposure creates payment friction from sanctions-linked banking restrictions. Distribution runs through cooperative networks consolidating for blockchain compliance infrastructure sharing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive organic crocus farming is emerging as the decisive competitive lever as dual-track EU and USDA certification investments favor scaled cultivator-processors over merchant intermediaries.
For Market Incumbents: Deepen upstream control over Torbat-e Heydarieh cultivation clusters to secure corm propagation expertise concentrated among aging farmer populations. Invest in spectroscopic pre-shipment verification infrastructure to absorb third-party laboratory margins. Defend against cooperative consolidation by locking multi-year offtake agreements before Khorasan smallholders achieve scale. For New Entrants and Emerging Players: EU Regulation 2018/848 traceability mandates in Germany and France open a window for Spanish La Mancha cultivators to compete on compliance proximity rather than volume scale. Target North American Ayurvedic practitioner channels in California and New York where small-batch dehydration protocols command premium positioning. Establish direct-to-chef platform relationships in Nordic gastronomy before incumbent exporters consolidate subscription replenishment models. For Investors and Strategic Acquirers: Re-rating potential sits with integrated cultivator-processors possessing multi-jurisdictional audit capabilities given pharmaceutical standardization demand for HPLC-verified apocarotenoid yields. Long-term viability hinges on securing generational transfer of organic pest management knowledge in Iran's Khorasan belt. Watch cooperative formation velocity in Razavi Khorasan as inflection indicator for supply-side consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farming | Captive crocus cultivation in Razavi Khorasan secures Super Negin supply for Seoul cosmetic manufacturers. |
| Blockchain Traceability Implementation | Batch-level digital records from field to fork satisfy EU Regulation 2018/848 mandates at border inspection posts. |
| Spectroscopic Quality Verification | Near-infrared devices for real-time crocin quantification compress pharmaceutical release timelines from days to hours. |
| Direct-to-Chef Platform Expansion | Subscription replenishment models with harvest-date specificity capture recurring volume from Nordic Michelin-starred kitchens. |
| Cooperative Consolidation | Khorasan smallholder aggregation shares compliance infrastructure costs for dual-track INSO and REACH certification. |
Study Parameters
Document review covered INSO organic grading standards, EU REACH residue testing protocols, and MFDS cosmetic ingredient regulations, complemented by interviews with Iranian cooperative managers, German pharmaceutical procurement leads, and Seoul-based skincare formulators. Secondary sources included customs trade data for saffron import flows, EFSA residue limit documentation, and USDA National Organic Program certification records. Bottom-up cultivation volume estimates from Khorasan province were triangulated against top-down pharmaceutical and cosmetic demand projections.
Historical pricing trajectories for Super Negin and Sargol grades were cross-referenced against panel input from spice merchants and extraction facility operators across the analysis window. Segmentation modeling incorporated product grade tier, end-use application split between food and pharmaceutical channels, distribution channel structure, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for certification timeline compression effects. Forecast inputs included labor cost inflation assumptions for manual harvesting and technology adoption curves for spectroscopic verification equipment.
The model assumes a particular technology adoption path for blockchain traceability layers; alternative pathways for paper-based certification persistence would alter the compliance cost outlook for smallholder cooperatives. Forecasts reflect assumptions regarding EU organic certification tightening pace and Iranian agricultural wage trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Ginger Oil Market