
 Mullein Leaf Market | 2026-2036
Mullein Leaf Market Size, Share, and Industry Trends Forecast 2026-2036
Mullein Leaf Market Outlook
Bulgarian wild-crafting cooperatives is recalibrating harvest volumes after drought stress across the Balkan range. Mountain Rose Herbs leverages direct farm partnerships to secure traceable dried leaf supply chains. Bio-Botanica Inc anchors its position through vertical integration into extraction and liquid botanical manufacturing. Nature's Answer competes via certified organic processing infrastructure in Utah.
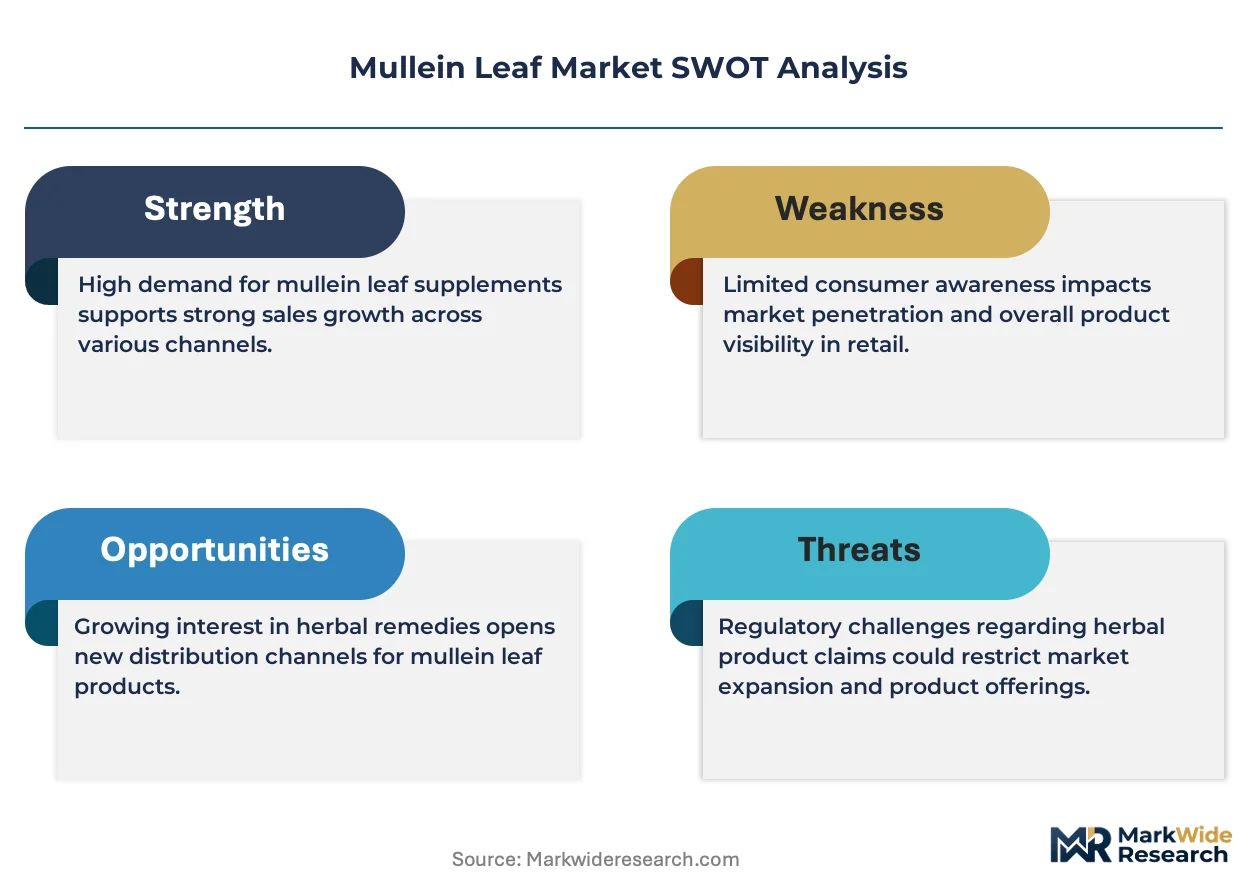
Mullein leaf comprises the dried aerial parts of Verbascum thapsus, a biennial herb containing mucilage, saponins, and flavonoids traditionally harvested at peak flowering for maximum bioactive concentration. The material serves primarily as an expectorant and demulcent in respiratory formulations across herbal and dietary supplement channels. Dried leaves and extracts dominate volume, while capsules capture expanding shelf space in pharmacy retail due to dosing convenience and extended stability profiles. Online retail channels show the fastest trajectory, though health stores retain margin concentration through practitioner-directed sales.
FDA dietary supplement cGMP standards and USDA organic certification govern product quality, batch consistency, and label claims across domestic supply chains. The EU Herbal Directive and EFSA novel food assessments shape export feasibility for North American processors targeting European botanical markets. Stakeholders must monitor evolving pharmacovigilance requirements for traditional herbal medicines and adapt traceability systems accordingly.
Market Dynamics
Herbal supplement manufacturers face intensifying traceability mandates as FDA cGMP enforcement tightens, forcing supply chain reconfiguration toward certified organic sourcing and batch-level documentation systems.
Growth Catalysts
- FDA cGMP Compliance Pressure:Dietary supplement labeling requirements drive manufacturers toward verified botanical suppliers with documented chain-of-custody records.
- Respiratory Wellness Demand:Consumer preference for natural expectorants in cold and flu formulations expands pharmacy retail shelf allocation for mullein capsules.
- Direct-to-Consumer Channels:Online botanical retailers bypass traditional distribution markups, accelerating volume flow from harvest cooperatives to end users.
Market Restraints
- Climate Volatility in Balkan Harvest Zones:Drought stress across Bulgarian wild-crafting regions creates raw material scarcity and price instability for dried leaf supply.
- EU Novel Food Assessment Barriers:EFSA classification requirements block North American extract processors from accessing European botanical markets without extensive safety dossiers.
- Synthetic Expectorant Substitution:Pharmaceutical guaifenesin formulations compete on dosing precision and insurance reimbursement coverage.
Strategic Opportunities
- Practitioner-Directed Clinical Channels:Naturopathic and integrative medicine networks create premium positioning for standardized extract formulations with demonstrated bioactive consistency.
- USDA Organic Certification Expansion:Organic processing infrastructure investments unlock pharmacy retail placement and margin capture previously reserved for conventional supplement categories.
- Liquid Botanical Format Innovation:Alcohol-free glycerite extracts address pediatric and alcohol-sensitive consumer segments underserved by traditional tincture formats.
Industry Challenges
- Phytochemical Standardization Expertise:Scarcity of analytical chemists capable of validating mucilage and saponin content across variable harvest batches constrains quality control scaling.
- Dual Certification Timeline Compression:Simultaneous FDA cGMP and USDA organic audits demand 12-18 month facility preparation cycles that delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mullein Leaf Market |
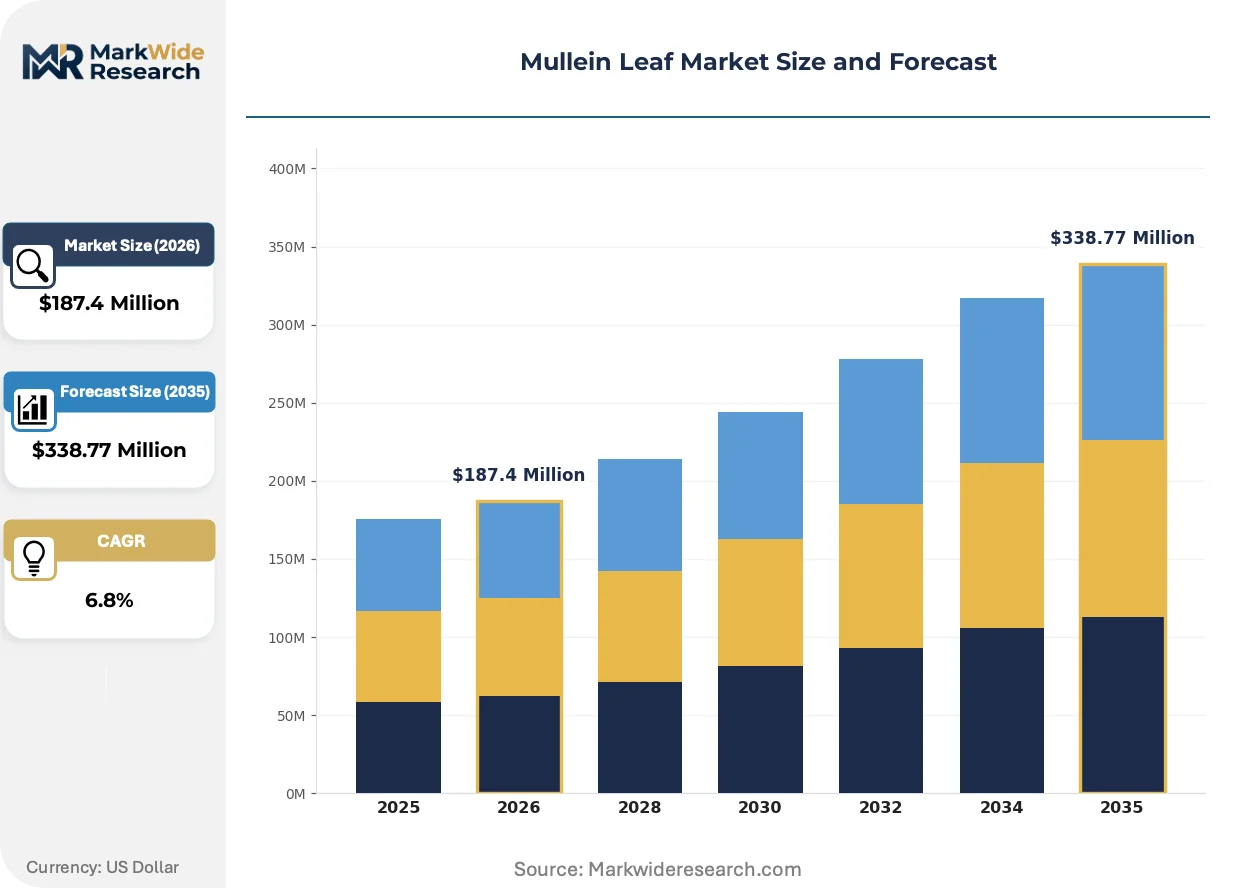
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Leaves, Extracts, Teas, Capsules Application: Herbal Remedies, Dietary Supplements, Traditional Medicine, Natural Remedies Distribution Channel: Health Stores, Online Retail, Pharmacies, Supermarkets End User: Health Enthusiasts, Herbalists, Home Users, Alternative Medicine Practitioners |
| Companies Covered | Mountain Rose Herbs, Alvita, Bio-Botanica Inc, Payne Mountain Farms, Swanson Vitamins, Penn Herb Co. Ltd, Nature’s Answer, Solaray, Starwest Botanicals Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mullein Leaf Market Strategic Shifts
Processing technology and regulatory architecture are compressing traditional supply hierarchies, with extraction methods and compliance frameworks determining competitive access rather than raw material availability alone.
Supercritical CO2 extraction is overtaking conventional solvent-based methods for concentrated mullein resin production. Premium supplement manufacturers in Utah and Oregon adopt this technology to eliminate residual solvent concerns and achieve higher flavonoid retention. The shift is compressing margins for ethanol-extraction facilities unable to justify capital retrofit costs.
REACH registration requirements for herbal substances are reshaping export feasibility for North American processors targeting European markets. The European Chemicals Agency's classification of certain botanical extracts as substances of very high concern forces reformulation or market withdrawal. German and Dutch import distributors now demand pre-registered supply chains, filtering out smaller harvest cooperatives lacking compliance infrastructure.
Subscription-based replenishment models are displacing single-purchase health store transactions for respiratory wellness formulations. Direct-to-consumer brands capture recurring revenue through automated capsule delivery, while independent herbalists lose foot traffic to algorithm-driven personalization platforms. This pattern concentrates most visibly in metropolitan United States markets where pharmacy deserts push consumers toward telehealth-integrated supplement services.
Mullein Leaf Market Segmentation
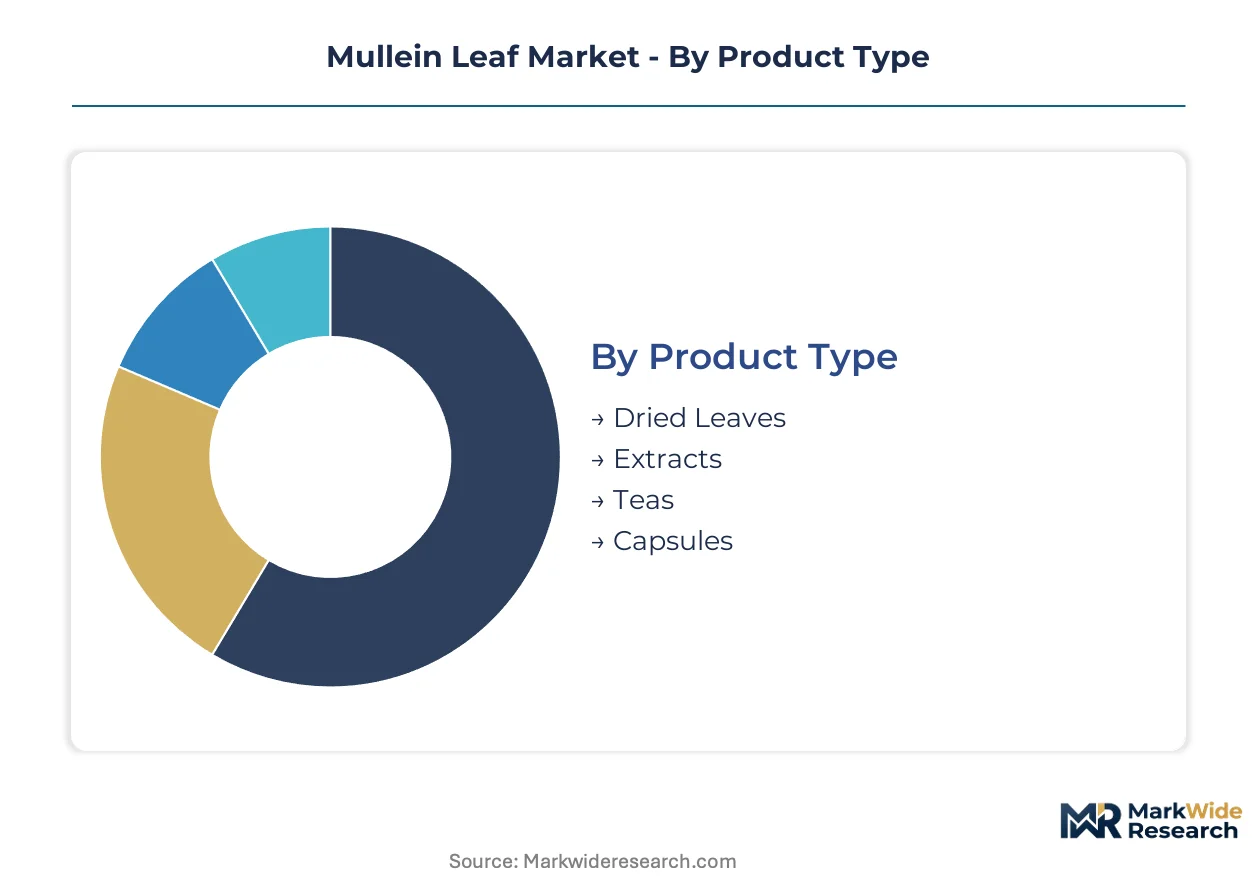
Mullein leaf segmentation reflects divergent processing intensities and regulatory exposure across supply chains. Product format determines shelf stability, dosage precision, and FDA cGMP compliance burden. Distribution channel selection shapes margin capture and end-user accessibility in distinct ways.
Product Type:
Technical sophistication separates commodity dried material from standardized extracts.
- Dried Leaves:Whole or cut-and-sifted aerial parts retain volatile oils and mucilage when properly cured at 40°C. Bulgarian wild-crafting cooperatives supply bulk volumes to Mountain Rose Herbs and regional tea blenders in Oregon, though drought stress across the Balkan range has compressed harvest windows and elevated raw material pricing.
- Extracts:Liquid concentrates produced via ethanol maceration or supercritical CO2 methods concentrate saponins and flavonoids for formulation flexibility. Bio-Botanica Inc and Nature's Answer compete through extraction infrastructure investments in Utah, where FDA cGMP compliance costs filter out smaller processors.
- Teas:Consumer-grade cut leaf packaged in bulk or sachet formats serves traditional preparation preferences in European-American herbalist communities.
- Capsules:Powdered leaf or standardized extract in gelatin or vegetable shells addresses dosing convenience and extended stability requirements of pharmacy retail.
Dried leaves lead on scale; capsules lead on momentum.
Application:
Regulatory classification determines market access velocity and label claim permissibility.
- Herbal Remedies:Traditional preparation formats sold through practitioner channels operate under DSHEA structure-function claim limitations. Naturopathic networks in Portland and Boulder drive premium positioning for mullein expectorant formulations with documented mucilage content.
- Dietary Supplements:Capsule and tablet formats face intensifying FDA cGMP enforcement on identity testing and heavy metal screening. Utah-based manufacturers anchor this segment through vertical integration into certified organic processing.
- Traditional Medicine:Whole herb sales through independent herbalists preserve pre-industrial preparation methods with minimal regulatory overhead.
- Natural Remedies:Broad retail category spanning health stores and online botanical retailers, where subscription replenishment models are displacing single-purchase transactions.
Dietary supplements dominate revenue concentration; natural remedies expand most quickly through direct-to-consumer channels.
Distribution Channel:
Channel selection determines traceability documentation requirements and margin stacking depth.
- Health Stores:Independent retailers and regional chains like Natural Grocers retain practitioner-directed sales relationships with margin concentration in metropolitan United States markets. Staff training on respiratory wellness applications drives attachment rates for mullein formulations.
- Online Retail:Direct-to-consumer botanical platforms bypass traditional distribution markups and capture recurring revenue through algorithm-driven personalization. This channel shows steepest expansion trajectory as pharmacy deserts push consumers toward telehealth-integrated supplement services.
- Pharmacies:CVS and Walgreens shelf placement requires USDA organic certification and child-resistant packaging compliance, filtering out uncertified suppliers.
- Supermarkets:Mass-market placement in Whole Foods and Sprouts demands price competitiveness that compresses margins for small-batch harvest cooperatives.
Health stores retain margin leadership; online retail commands volume acceleration.
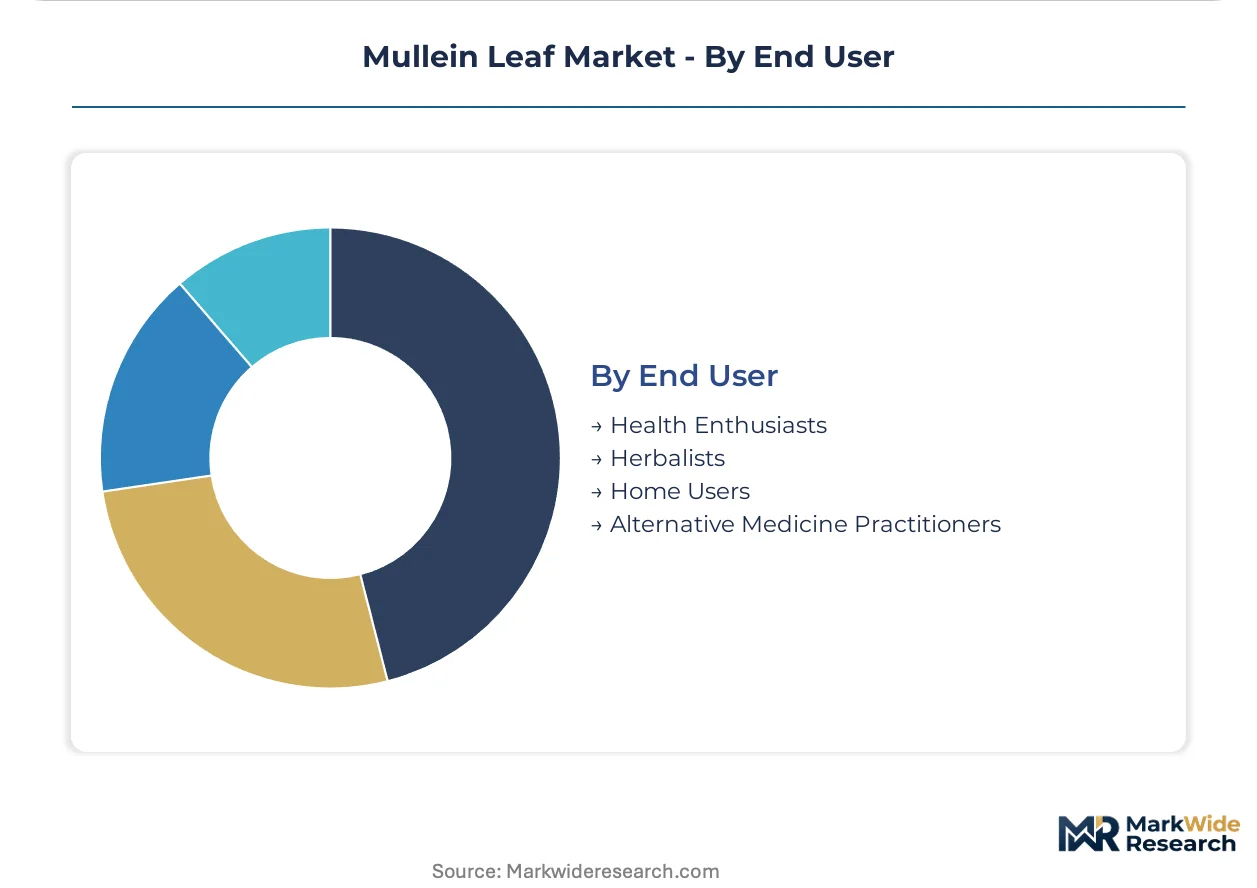
End User:
User sophistication determines information requirements and price elasticity.
- Health Enthusiasts:Self-directed consumers researching bioactive compounds through independent health information platforms drive demand for standardized extract specifications and third-party testing documentation.
- Herbalists:Trained practitioners in American Herbalists Guild networks prioritize traceable sourcing and traditional harvest timing for clinical formulation efficacy.
- Home Users:Casual consumers seeking respiratory wellness support favor capsule convenience and recognizable retail placement over technical specification detail.
- Alternative Medicine Practitioners:Licensed naturopathic physicians and integrative medicine clinics create premium positioning for batch-tested formulations with demonstrated bioactive consistency.
Home users provide volume foundation; alternative medicine practitioners generate premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as FDA cGMP compliance costs in the United States push harvest cooperatives toward lower-cost certification jurisdictions. Cost-of-compliance gaps between North American and Balkan supply zones are accelerating contract migration.
United States
Direct-to-consumer botanical channels expand fastest in metropolitan markets where pharmacy deserts push consumers toward telehealth-integrated supplement services. FDA cGMP enforcement tightens identity testing and heavy metal screening requirements for dietary supplement manufacturers. Utah and Oregon anchor extraction infrastructure investments, with supercritical CO2 facilities clustering around Salt Lake City and Eugene processing corridors.
Bulgaria
Wild-crafting cooperatives supply bulk dried leaf volumes to North American processors amid recalibrating harvest volumes after drought stress across the Balkan range. EU Herbal Directive compliance requirements shape export feasibility for traditional herbal medicines. The Rhodope Mountains concentration of Verbascum thapsus harvesting faces compressed collection windows and elevated raw material pricing.
Germany
Import distributors demand pre-registered supply chains under REACH registration requirements for herbal substances, filtering out smaller harvest cooperatives lacking compliance infrastructure. EFSA novel food assessments block North American extract processors without extensive safety dossiers. Frankfurt and Hamburg serve as consolidation points for botanical imports entering European distribution networks.
Canada
Health Canada and PMRA regulations govern natural health product licensing and site licensing for mullein-containing formulations. Practitioner-directed sales through naturopathic networks in Vancouver and Toronto create premium positioning for standardized extract formulations. British Columbia and Ontario concentrate organic processing infrastructure serving cross-border botanical trade.
Netherlands
Rotterdam and Amsterdam function as re-export hubs for Balkan-sourced dried leaf entering European botanical markets. ECHA classification of certain botanical extracts as substances of very high concern forces reformulation or market withdrawal decisions. Dutch import distributors now require documented chain-of-custody records from upstream Bulgarian suppliers.
Mullein Leaf Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue certified organic positioning and alcohol-free format innovation. The vendor base separates between vertically integrated extract processors and harvest-dependent bulk suppliers. Three archetypes dominate: wild-crafting cooperatives with traceable sourcing, FDA cGMP-certified manufacturers with in-house extraction, and direct-to-consumer brands with subscription replenishment models. Competitive moves concentrate on backward integration into certified organic acreage and strategic partnerships with practitioner networks.
Among North American manufacturers, Mountain Rose Herbs exemplifies the direct farm partnership archetype, while Bio-Botanica Inc and Nature's Answer anchor the FDA cGMP-certified processing tier. These three occupy positions spanning bulk supply, extraction infrastructure, and branded formulation. Their collective presence illustrates how compliance investment and sourcing control separate sustainable competitors from margin-compressed commodity suppliers.
| Leading Market Players |
|---|
| Mountain Rose Herbs |
| Alvita |
| Bio-Botanica Inc |
| Payne Mountain Farms |
| Swanson Vitamins |
| Penn Herb Co. Ltd |
| Nature's Answer |
| Solaray |
| Starwest Botanicals Inc |
| Others |
Value Chain & Pricing Dynamics
Backward integration into certified organic acreage anchors both supply security and premium pricing power for mullein leaf processors navigating FDA cGMP compliance costs. This upstream control separates sustainable competitors from margin-compressed commodity suppliers dependent on volatile Balkan wild-crafting harvests.
Pricing Analysis
Distributor margin stacking through health stores and pharmacy retail creates three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on USDA organic certification tier and supercritical CO2 extraction infrastructure investment. Pricing pressure stems from drought-induced raw material scarcity in Bulgarian harvest zones. Home users exhibit highest price sensitivity, while alternative medicine practitioners accept premium positioning for batch-tested formulations.
Supply Chain Analysis
Certification gating through FDA cGMP and USDA organic audits filters supplier participation and concentrates procurement leverage among vertically integrated processors. Geographic supply concentration centers on Bulgaria, the United States, and Canada. Raw material dependencies include wild-crafted dried leaf, ethanol solvents, and vegetable-derived capsule shells. Single-source vulnerability runs through Balkan wild-crafting cooperatives facing climate volatility. Distribution runs through direct-to-consumer platforms, health stores, and pharmacy retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified organic processing infrastructure and practitioner-directed clinical channels, with cost compression available through supercritical CO2 extraction scale economics.
For Market Incumbents: Extend backward integration into certified organic acreage in Utah and Oregon to secure captive supply chains against Balkan drought volatility. Reinforce FDA cGMP compliance infrastructure as synthetic expectorant substitution from pharmaceutical guaifenesin formulations intensifies competitive pressure on respiratory wellness positioning. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a technology-first wedge into premium capsule segments underserved by ethanol-dependent processors. Target alcohol-free glycerite extract formats for pediatric and alcohol-sensitive consumer white space. Pursue subscription-based replenishment models through telehealth-integrated supplement platforms. For Investors and Strategic Acquirers: Roll-up economics work for FDA cGMP-certified mid-cap processors because compliance cost barriers prevent organic growth by smaller harvest cooperatives. Long-term viability rests on acquisition of extraction infrastructure with dual certification timelines already completed. Watch EFSA novel food assessment rulings as inflection indicators for European market access feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Expansion | Unlocks pharmacy retail placement at CVS and Walgreens through child-resistant packaging compliance. |
| Supercritical CO2 Extraction Scale-Up | Eliminates residual solvent concerns for Utah and Oregon premium supplement manufacturers. |
| Practitioner Network Partnership | Secures premium positioning through American Herbalists Guild and naturopathic clinic channels. |
| Direct-to-Consumer Platform Launch | Bypasses health store distribution markups via algorithm-driven personalization engines. |
| Balkan Supply Agreement Restructuring | Reduces drought exposure through diversified harvest cooperative contracts across Rhodope Mountains. |
Study Parameters
Coverage spans North America and Europe, with primary inputs from each region combining interviews with herbal supplement manufacturers, wild-crafting cooperative managers, FDA regulatory consultants, and naturopathic practitioners. Secondary validation draws from FDA cGMP guidance documents, USDA organic certification databases, EFSA novel food assessments, and customs trade records. Bottom-up volume triangulation across product formats and top-down value reconciliation through distribution channel margins anchor the analytical framework.
Rate-of-change decomposition separates volume drivers from pricing dynamics across the projection horizon. Segmentation dimensions include product type, application category, distribution channel, and end-user sophistication tier. CAGRs derive from historical growth pattern analysis adjusted for regulatory enforcement intensity and channel shift velocity. Industry-specific forecast inputs incorporate Balkan harvest yield variability and FDA audit frequency trends.
The model holds under stable FDA cGMP enforcement and USDA organic certification timelines; deviation in EFSA novel food classification rulings or Balkan climate patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Sichuan Peppercorn Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market