
 North American Seasonings and Spices Market | 2026-2036
North American Seasonings and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
North American Seasonings and Spices Market Analytics
Mexico is reshaping raw material flows through expanded pepper and vanilla cultivation in Veracruz and Oaxaca. McCormick & Company leverages its integrated supply network across three continents to secure consistent botanical inputs. Fuchs North America anchors its competitive stance through custom blend capabilities tailored to protein processing clients. Kerry Group PLC differentiates via clean-label fermentation technologies that reduce sodium while preserving flavor intensity.
Seasonings and spices encompass dried plant-derived materials—whole, ground, or extracted—that impart flavor, color, or preservative function to food products, typically processed through milling, steam treatment, or solvent extraction to achieve specified volatile oil content and microbial safety thresholds. The product type dimension shows blends capturing disproportionate margin pools as food manufacturers outsource formulation complexity, while powder form dominates volume throughput due to solubility advantages in industrial sauce applications. Retail channels maintain stable throughput, but food services generate accelerated order velocity as restaurant chains centralize procurement through broadline distributors.
The FDA enforces pathogen testing mandates under the Food Safety Modernization Act that elevate compliance costs for small importers. USDA organic certification requirements restrict permitted processing aids in spice sterilization, reshaping supplier qualification criteria. Health Canada and CFIA alignment on ethylene oxide residue limits creates cross-border regulatory coherence that simplifies North American sourcing strategies. Stakeholders must monitor evolving state-level prop 65 labeling obligations in California that threaten to fragment packaging compliance across the trade bloc.
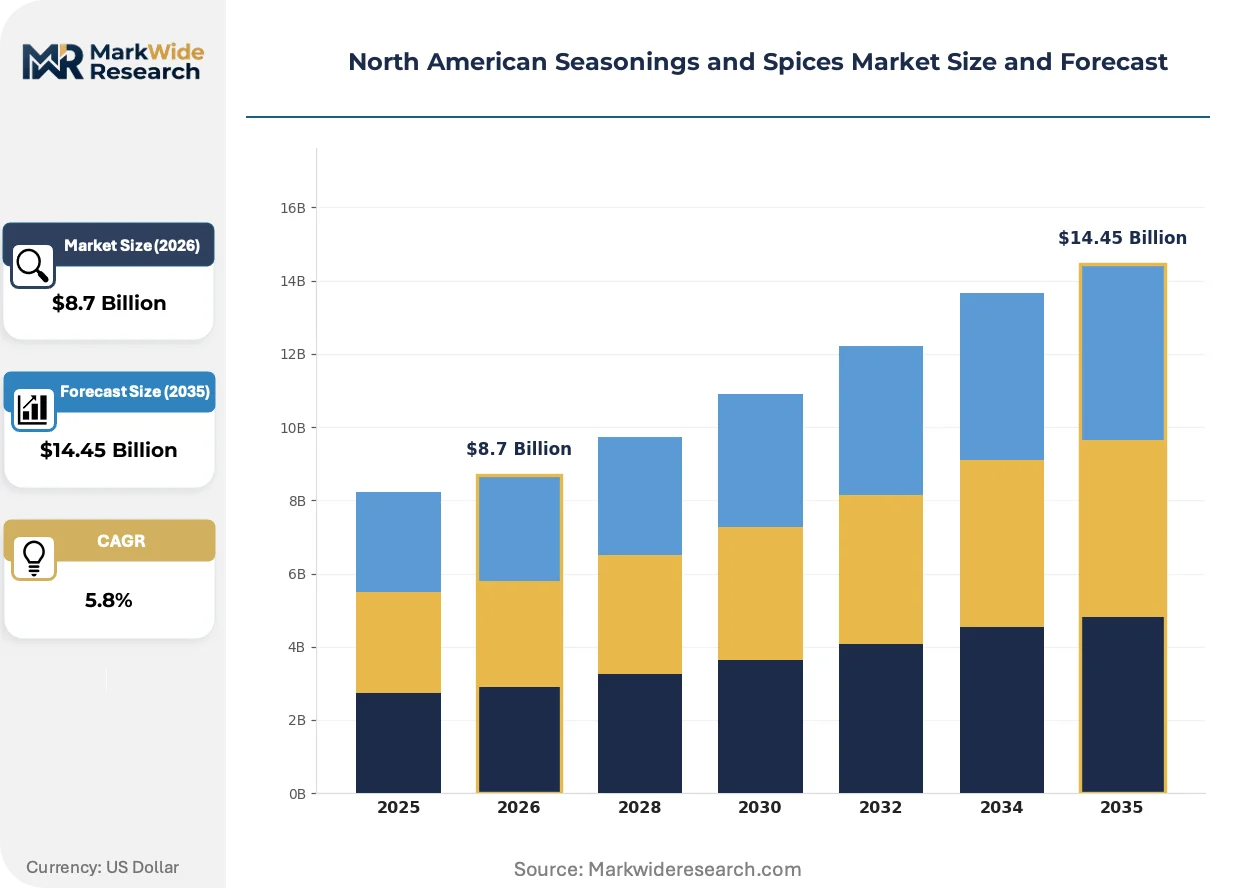
Market Dynamics
Traceability mandates under the FDA Food Safety Modernization Act are compressing supplier qualification timelines while concentrating procurement authority among vertically integrated processors capable of documenting chain-of-custody across multiple jurisdictions.
Growth Catalysts
- Clean-label fermentation:Enzymatic flavor enhancement technologies enable sodium reduction without taste degradation, attracting reformulation contracts from protein processors seeking USDA organic certification compliance.
- California Proposition 65:Warning label requirements for specific spice constituents are accelerating demand for certified contaminant-free supply chains, rewarding importers with validated testing protocols.
- Menu customization programs:US food service operators are expanding proprietary blend specifications that require co-manufacturing partnerships with regional grinding facilities.
Market Restraints
- Ethylene oxide residue limits:Health Canada and CFIA alignment on sterilization thresholds restricts treatment options for imported botanicals, elevating rejection rates at border inspection points.
- Veracruz-Oaxaca sourcing concentration:Mexican vanilla and pepper cultivation clusters face climate volatility that transmits price instability through North American extract supply chains.
- Steam treatment capacity scarcity:Alternative sterilization infrastructure remains insufficient to replace fumigation-dependent processing for high-volume powder applications.
Strategic Opportunities
- Yucatán Peninsula expansion:Underdeveloped achiote and habanero processing infrastructure offers first-mover advantages for integrated grinding and extraction facilities serving US sauce manufacturers.
- Direct-to-foodservice distribution:Bypassing broadline distributors through proprietary e-procurement platforms captures margin pools currently absorbed by intermediary warehousing layers.
- Dual carbon incentives:Mexico's federal sustainability credits and California's Low Carbon Fuel Standard create stacked policy support for solar-dried spice operations with verified emissions reductions.
Industry Challenges
- Sensory evaluation talent scarcity:Qualified flavor chemists and trained panelists for volatile oil profiling command premium compensation, constraining quality control scaling at mid-cap blenders.
- Legacy ERP integration:Lot-tracking software upgrades required for FSMA compliance face implementation delays at family-owned grinding operations with limited IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North American Seasonings and Spices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Blends, Seasoning Sauces End Use: Food Processing, Retail, Food Services, Household Form: Powder, Whole, Liquid, Granulated Packaging Type: Bags, Containers, Jars, Sachets |
| Companies Covered | Ajinomoto Co., Inc., Fuchs North America, McCormick & Company, Inc., Spiceology, Badia Spices, Olam International, B&G Foods, Inc., PS Seasoning, Kerry Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North American Seasonings and Spices Market Evolving Landscape
Processing technologies and compliance architectures are converging to reshape competitive advantage around verified provenance and accelerated formulation cycles rather than commodity scale alone.
Cold plasma sterilization is hybridizing traditional thermal and chemical treatment pathways. Mid-sized organic spice processors in California's Central Valley are piloting atmospheric plasma systems to achieve microbial reduction without volatile oil degradation. This technology is hybridizing quality assurance protocols by enabling non-thermal pathogen elimination that preserves aromatic compound profiles previously sacrificed to steam treatment.
The FDA's updated traceability rule under FSMA Section 204 imposes electronic record-keeping mandates for high-risk spice categories. Small importers face disproportionate compliance burdens as they retrofit paper-based documentation systems for interoperable digital formats. Pepper and sesame supply chains originating in South Asia are experiencing the steepest adaptation costs, driving consolidation toward larger trading houses with pre-existing ERP infrastructure.
Centralized procurement through broadline distributors is fragmenting as regional restaurant chains develop direct relationships with specialty blenders. Foodservice buyers are unbundling spice specification from protein and produce contracts, creating standalone RFP processes that reward formulation agility over volume discounts. This pattern concentrates in the Southwestern United States, where fast-casual chains source chile-specific blends directly from New Mexico and Texas grinding cooperatives.
North American Seasonings and Spices Market Segmentation
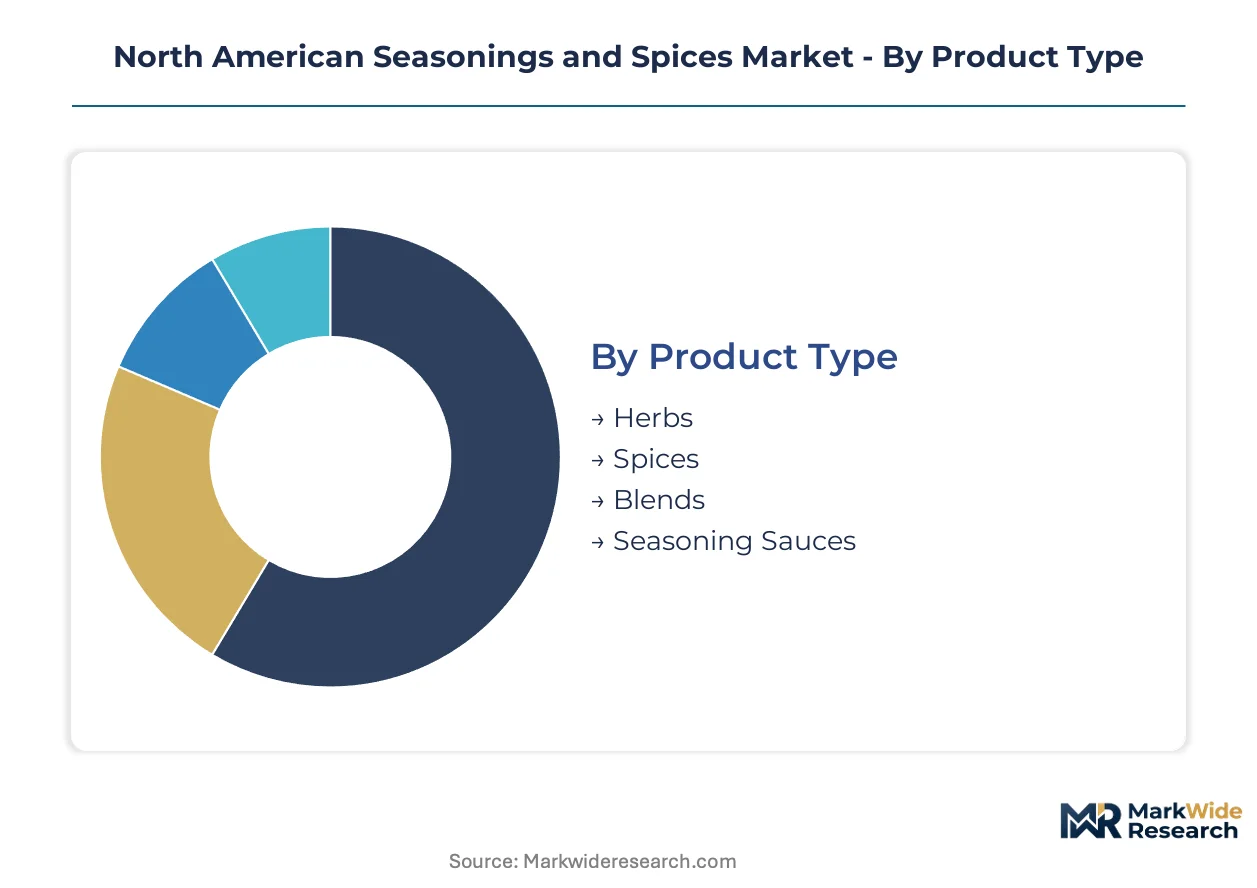
Segmentation in the North American seasonings and spices market reveals divergent velocity profiles across product categories. Procurement cycles for industrial powder forms compress to weeks, while retail jarred blends extend to quarterly replenishment rhythms.
Product Type:
Cycle times vary dramatically across this dimension—blends turn fastest as foodservice chains rotate limited-time offerings, while single-origin spices move slowest due to commodity hedging patterns.
- Herbs:Dried leaf materials including basil, oregano, and parsley with specified volatile oil retention thresholds. California's Central Valley dehydration facilities supply protein processors seeking clean-label ingredient statements for USDA organic certified product lines.
- Spices:Bark, root, seed, and fruit materials processed to specified particle sizes for industrial extraction. Demand clusters in Illinois and Texas meat processing corridors where smoke and cure applications require consistent piperine and capsaicin potency.
- Blends:Pre-formulated combinations targeting specific protein or sauce applications. Quick-service restaurant chains in the Southwestern United States drive formulation velocity through seasonal menu rotations.
- Seasoning Sauces:Liquid or paste concentrates incorporating spice extracts and acidulants. Wet-form products serve barbecue and hot-sauce manufacturers in the Carolinas and Louisiana.
Powder spices anchor the volume base while blends gain share at the steepest rate.
End Use:
Cost tier stratification separates this category—industrial food processing commands lowest unit economics through bulk tote procurement, while household retail sustains premium pricing through brand equity and packaging differentiation.
- Food Processing:Industrial-scale ingredient supply to sauce, snack, and protein manufacturers. FDA FSMA traceability mandates concentrate procurement authority among vertically integrated processors capable of lot-level documentation across multi-state supply chains.
- Retail:Branded and private-label products distributed through grocery and mass merchandiser channels. California Proposition 65 warning requirements are accelerating demand for certified contaminant-free supply chains with validated testing protocols.
- Food Services:Broadline distributor and direct-to-operator supply for restaurant and institutional kitchens. Centralized procurement is fragmenting as regional chains develop direct relationships with specialty blenders in New Mexico and Texas.
- Household:Consumer-packaged goods sold through retail and e-commerce channels. Premium positioning relies on origin storytelling and organic certification badges.
Food processing commands the volume base while food services climbs the fastest on direct-sourcing momentum.
Form:
Application requirements dictate form selection—solubility demands in industrial sauce manufacturing favor powder, while visual identity in premium retail drives whole-spice presentation.
- Powder:Milled materials with specified mesh sizes for homogeneous dispersion. Dominates throughput in industrial sauce applications where solubility prevents sedimentation defects.
- Whole:Intact botanical materials for grinding at point-of-use or visual premium positioning. Specialty retailers and high-end foodservice operations in California and New York favor this form for authenticity signaling.
- Liquid:Extracts, oleoresins, and emulsified concentrates. Beverage and dairy applications in the Midwest leverage liquid forms for precise dosing and microbial stability.
- Granulated:Agglomerated particles balancing solubility with flow characteristics. Seasoning blends for snack coating operations prefer this form to prevent dusting and improve adhesion.
Powder form anchors the volume base while liquid extracts expand most quickly in beverage applications.
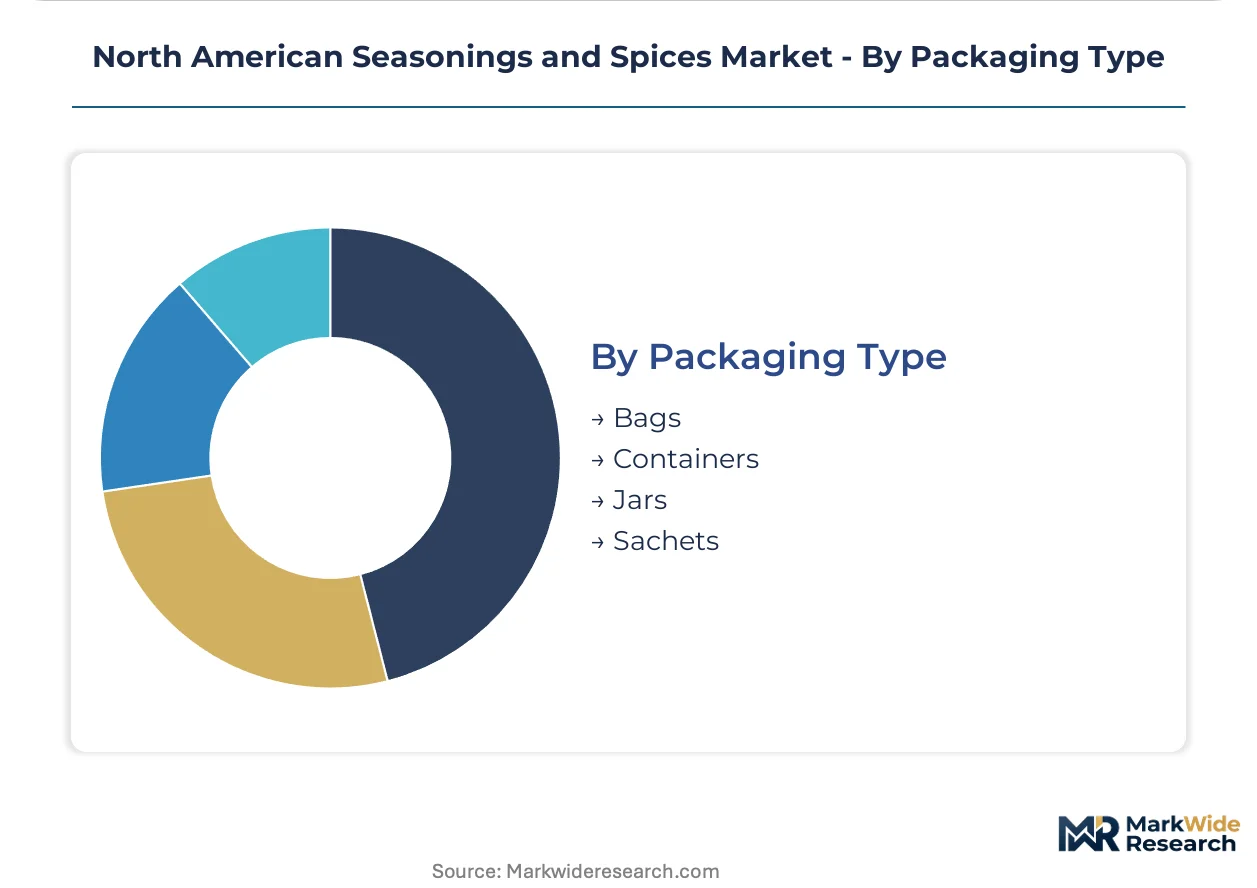
Packaging Type:
Volume scale inversely correlates with packaging sophistication—bulk bags serve industrial tonnage, while single-serve sachets maximize margin per gram through convenience positioning.
- Bags:Flexible multi-wall constructions for industrial bulk supply. Food processing facilities in the Midwest receive spices in supersacks to minimize handling labor and storage footprint.
- Containers:Rigid plastic or composite canisters with moisture barriers. Club store retail channels in the United States favor this format for warehouse shelf stability and consumer pantry storage.
- Jars:Glass or clear plastic vessels with shaker fitments. Visual merchandising requirements in premium grocery drive this format for whole spice and premium blend presentation.
- Sachets:Single-serve flexible pouches for portion control. Foodservice operators expanding menu customization programs require sachet formats for back-of-house consistency and waste reduction.
Bags anchor the volume base while sachets gain share fastest on foodservice customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America—US food manufacturers prioritize bulk powder procurement for industrial sauce lines, while Canadian buyers emphasize certified organic formats for retail premiumization, and Mexican operators concentrate on achiote and habanero extraction for export-oriented processing.
United States
California's Central Valley dehydration facilities supply protein processors seeking clean-label ingredient statements for USDA organic certified product lines. FDA Food Safety Modernization Act traceability mandates compress supplier qualification timelines while concentrating procurement authority among vertically integrated processors. Illinois and Texas meat processing corridors drive consistent demand for smoke and cure applications requiring standardized piperine and capsaicin potency.
Canada
Health Canada and CFIA alignment on ethylene oxide residue limits creates cross-border regulatory coherence that simplifies sourcing strategies for Ontario-based sauce manufacturers. Canadian Prairie Provinces processing facilities specialize in mustard seed milling and dehydration for export to US condiment producers. Montreal and Toronto distribution hubs anchor cold-chain logistics for high-value vanilla and saffron imports.
Mexico
Veracruz and Oaxaca cultivation clusters supply vanilla and pepper raw materials that transmit price volatility through North American extract supply chains. Mexico's federal sustainability credits stack with California's Low Carbon Fuel Standard to incentivize solar-dried spice operations with verified emissions reductions. Yucatán Peninsula achiote and habanero processing infrastructure remains underdeveloped, offering first-mover advantages for integrated grinding facilities.
California
Proposition 65 warning label requirements for specific spice constituents accelerate demand for certified contaminant-free supply chains with validated testing protocols. Mid-sized organic spice processors in the Central Valley pilot atmospheric plasma sterilization systems to achieve microbial reduction without volatile oil degradation. Los Angeles and Long Beach port complexes handle bulk pepper and sesame shipments originating in South Asia.
Southwestern United States
New Mexico and Texas grinding cooperatives supply chile-specific blends directly to fast-casual restaurant chains unbundling spice procurement from protein contracts. Direct-to-foodservice distribution models bypass broadline distributors through proprietary e-procurement platforms. Regional blenders capture margin pools previously absorbed by intermediary warehousing layers through formulation agility over volume discounts.
North American Seasonings and Spices Market Competitive Landscape
Capability concentration sits with specialized blenders possessing formulation agility and validated contaminant-testing protocols; scale advantage sits with diversified processors commanding multi-continent supply networks and FSMA-compliant documentation systems. The market structures around three archetypes: vertically integrated botanical traders, regional custom-grinding specialists, and clean-label fermentation technology providers. Competitive moves concentrate on backward integration into sourcing zones and technology licensing for non-thermal sterilization methods.
Among diversified processors with integrated supply networks, McCormick & Company, Inc. and Olam International exemplify the scale-driven archetype capable of documenting chain-of-custody across multiple jurisdictions. Kerry Group PLC occupies a position within the clean-label technology tier, representing fermentation-based sodium reduction capabilities that attract reformulation contracts from protein processors. Fuchs North America anchors the custom-blend specialist category, serving regional grinding demands with tailored formulation services.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Fuchs North America |
| McCormick & Company, Inc. |
| Spiceology |
| Badia Spices |
| Olam International |
| B&G Foods, Inc. |
| PS Seasoning |
| Kerry Group PLC |
| Others |
Value Network & Pricing Analysis
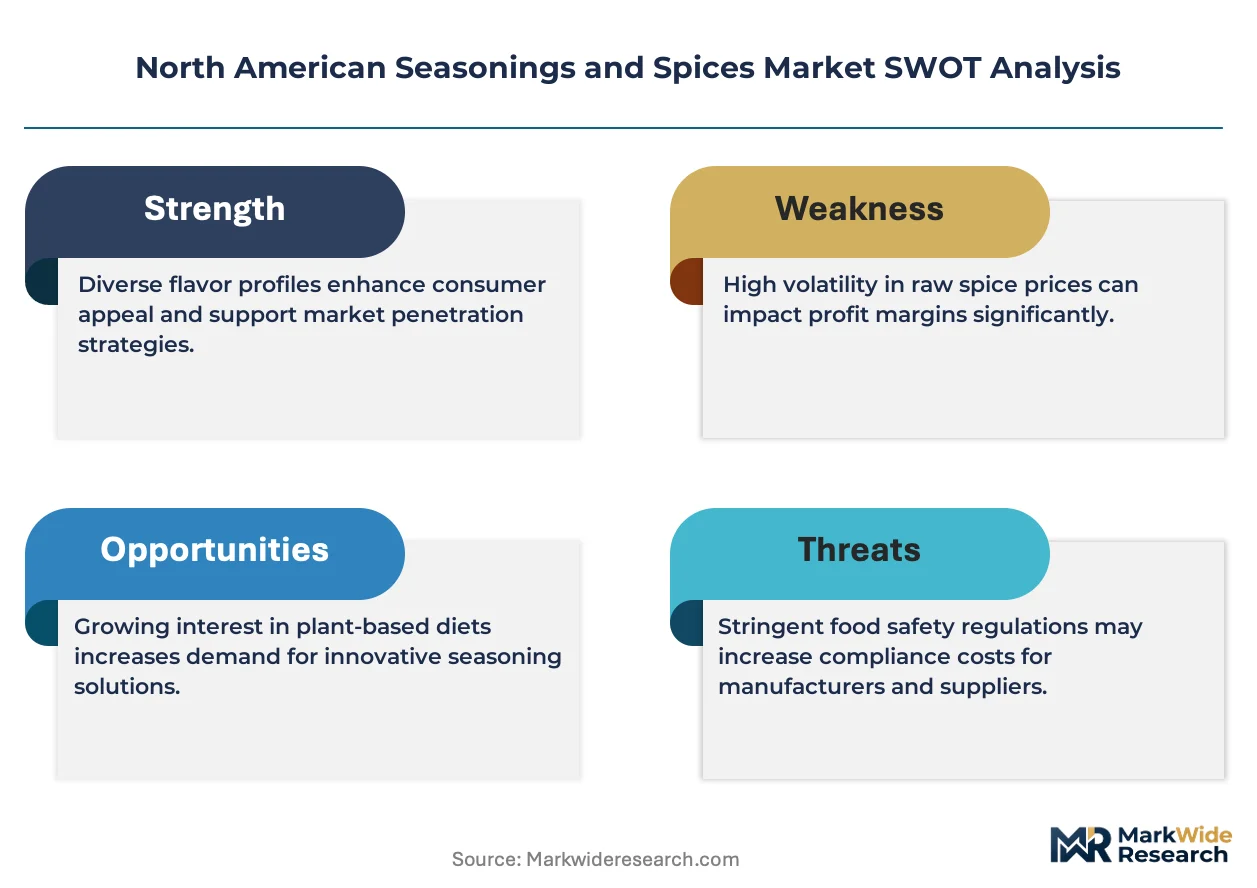
Veracruz and Oaxaca cultivation clusters for vanilla and pepper concentrate upstream supply power among Mexican agricultural cooperatives, translating into volatile input costs that compress margin pools for North American extract processors and finished blend manufacturers.
Pricing Analysis
Long-term offtake contracts between California dehydration facilities and Central Valley herb growers anchor pricing stability for organic-certified inputs, while spot markets dominate conventional pepper and sesame transactions. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified lots from conventional steam-treated grades and bulk commodity powders. Cost compression in conventional powder tiers is intensifying because steam treatment capacity scarcity elevates processing premiums. Quick-service restaurant chains exhibit highest price sensitivity through centralized procurement, while specialty retail channels sustain premium positioning via origin storytelling.
Supply Chain Analysis
Tariff exposure between India and the United States dominates risk calculations for pepper and sesame supply chains serving California port complexes. Raw material flows draw from Veracruz vanilla orchards, Oaxaca pepper plantations, and South Asian sesame processing hubs. Single-source vulnerability concentrates in ethylene oxide-dependent sterilization infrastructure that Health Canada and CFIA alignment has restricted. Distribution runs through broadline distributors for foodservice accounts, while direct-to-operator e-procurement platforms are fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as foodservice procurement unbundles from protein contracts, creating standalone niches for regional blenders with formulation agility and validated contaminant-testing protocols.
For Market Incumbents: Build captive supply networks through backward integration into Yucatán Peninsula achiote and habanero cultivation. Secure chain-of-custody documentation across multiple jurisdictions to defend against FSMA traceability compression. Expand atmospheric plasma sterilization capacity in California's Central Valley to capture premium positioning for volatile oil retention.
For New Entrants and Emerging Players: Underdeveloped grinding infrastructure in Mexico's Yucatán Peninsula offers first-mover positioning for integrated extraction facilities serving US sauce manufacturers. Target direct-to-foodservice distribution through proprietary e-procurement platforms bypassing broadline intermediaries. Lead with clean-label fermentation capabilities that reduce sodium while preserving flavor intensity for protein processor reformulation contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward regional custom-grinding specialists possessing validated testing protocols and direct foodservice relationships. Long-term viability rests on capability concentration around formulation agility rather than commodity scale alone. Watch for FDA enforcement patterns on FSMA Section 204 electronic record-keeping mandates as consolidation inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sourcing Zones | Captive supply from Veracruz and Oaxaca secures vanilla and pepper inputs against climate volatility. |
| Non-Thermal Sterilization Technology Licensing | Cold plasma systems preserve aromatic compounds that steam treatment degrades in organic spice processing. |
| Direct-to-Foodservice Distribution Platform | Proprietary e-procurement captures margin pools currently absorbed by broadline distributor warehousing layers. |
| Clean-Label Fermentation Capability Buildout | Enzymatic sodium reduction attracts reformulation contracts from USDA organic certified protein processors. |
| Dual Carbon Certification Program | Stacked Mexican federal credits and California LCFS incentives reward solar-dried operations with verified emissions reductions. |
Research Methodology
Operator-level perspectives from procurement directors at protein processing facilities, quality control managers at spice grinding operations, regulatory affairs leads at imported food trading houses, and category buyers at broadline distributors anchored the qualitative base. Primary interview insights combined with secondary validation from FDA FSMA guidance documents, USDA organic certification protocols, Health Canada and CFIA ethylene oxide residue advisories, and California Proposition 65 regulatory filings. Bottom-up demand modeling across end-use segments triangulated against top-down trade flow analysis.
Scenario-bracketing around regulatory enforcement intensity, climate volatility in Mexican sourcing zones, and foodservice procurement unbundling velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use application, form specification, and packaging format. CAGRs derived from volume trajectory analysis incorporating FDA traceability mandate implementation pace and steam treatment capacity expansion timelines.
Practitioners should monitor FDA enforcement patterns on FSMA Section 204 electronic record-keeping, Health Canada and CFIA alignment on alternative sterilization approvals, and California Proposition 65 warning requirement expansion for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Organic Spices and Herbs Market