
 Kosher Salt Market | 2026-2036
Kosher Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Kosher Salt Market Analysis
Sea salt is shifting toward premium positioning in foodservice channels, displacing standard table salt in high-end restaurant kitchens. Cargill Inc leverages its grain-handling infrastructure to control bulk kosher salt distribution across North American food manufacturers. Morton Salt Inc anchors consumer brand recognition through retail shelf placement in mass-market grocery channels. Compass Minerals International Inc dominates highway-deicing salt production but extends mining capacity into food-grade kosher salt during seasonal demand windows.
Kosher salt consists of sodium chloride crystals with larger, irregular flake structure and no added iodine or anti-caking agents, produced through evaporation processes that yield a coarse, porous grain optimized for meat koshering and manual pinching. Its primary commercial purpose centers on moisture extraction from protein surfaces and controlled seasoning in volume cooking. Coarse product type leads industrial procurement for meat processing applications where crystal size governs brine penetration rates. Food manufacturers represent the fastest-growing end user segment as clean-label sodium reduction strategies favor kosher salt's perceived natural positioning over processed alternatives. Supermarkets occupy the dominant distribution channel for household volume, though online retailers capture premium and specialty organic variants.
The FDA governs sodium labeling thresholds and health claims on packaged foods, directly influencing manufacturer salt selection and formulation documentation. USDA oversight of meat and poultry processing mandates specific curing salt applications where kosher salt substitutes require process validation. Stakeholders must monitor evolving sodium reduction mandates and certification requirements from Orthodox Union and other kosher authorities that govern product legitimacy for observant consumer segments.
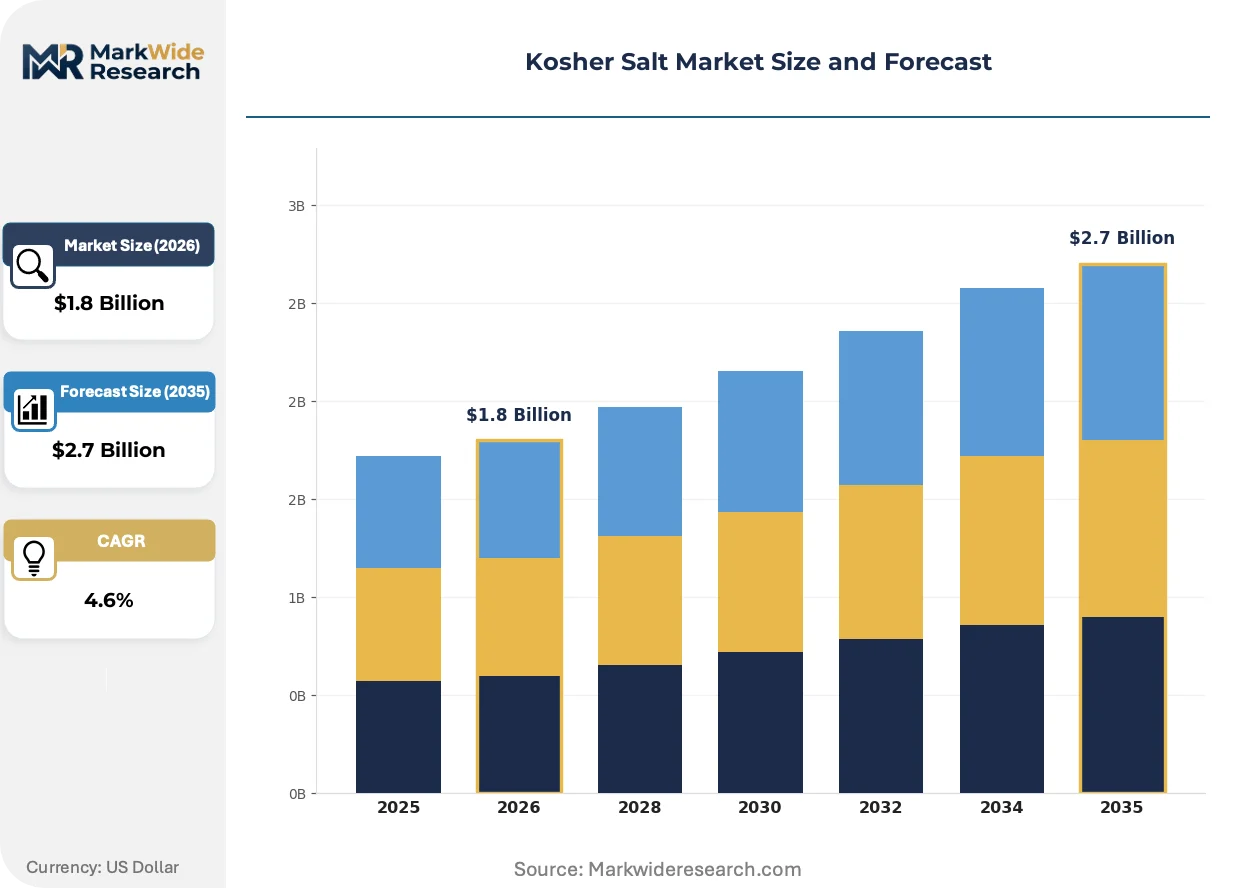
Market Dynamics
The FDA's updated sodium reduction guidelines are forcing processed food manufacturers to reformulate with kosher salt's larger crystal structure, creating procurement concentration among specialty meat processors and artisanal food manufacturers who value controlled dissolution rates.
Growth Catalysts
- Clean-label sodium reduction:Food manufacturers favor kosher salt's additive-free profile over iodized alternatives to meet FDA labeling thresholds for reduced-sodium claims on packaged goods.
- Artisanal curing revival:Specialty meat processors in the United States are expanding coarse salt procurement for traditional brining applications where crystal size governs moisture extraction efficiency.
- Evaporation technology advancement:Solar and vacuum evaporation processes now yield more consistent flake structure, improving pinchability for high-volume restaurant kitchens.
Market Restraints
- Input cost volatility:Natural gas prices directly impact thermal evaporation energy costs for domestic producers during winter production windows.
- Supply concentration risk:North American bulk distribution networks concentrate in grain-handling infrastructure operators, limiting alternative sourcing pathways for mid-size food manufacturers.
- Substitution threat:Sea salt producers are displacing kosher salt in premium foodservice channels through aggressive positioning in high-end restaurant kitchens.
Strategic Opportunities
- E-commerce specialty channels:Online retailers capture organic and specialty kosher salt variants that supermarkets shelve inconsistently, opening direct-to-chef distribution.
- USDA process validation:Meat and poultry processors require documented curing salt substitutions, creating service revenue for kosher salt suppliers who provide compliance documentation.
- Orthodox Union certification expansion:Emerging observant consumer segments in suburban markets drive demand for legitimacy-verified products beyond traditional urban strongholds.
Industry Challenges
- Certification timeline compression:Orthodox Union and other kosher authorities require multi-step facility audits that delay new product launches by quarters.
- Brine penetration standardization:Meat processors lack universal protocols for substituting kosher salt in legacy curing systems designed for fine-crystal alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kosher Salt Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse, Fine, Flaky, Organic End User: Food Manufacturers, Household, Restaurants, Catering Services Packaging Type: Plastic Bags, Glass Containers, Bulk Packaging, Sachets Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Cargill Inc, Morton Salt Inc, San Francisco Salt Company, Saltworks Inc, Redmond Inc, K+S Windsor Salt Ltd, The Marblehead Salt Co LLC, Compass Minerals International Inc, Diamond Crystal Brands Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kosher Salt Market Emerging Trajectories
Solar evaporation infrastructure is reshaping production economics while regulatory pressure on sodium content accelerates formulation innovation. Consumer preference for tactile seasoning control is electrifying demand across both professional and home kitchens.
Precision-controlled solar evaporation is electrifying kosher salt manufacturing by yielding more uniform flake porosity than traditional thermal methods. Food manufacturers in the United States are adopting these outputs for processed meat applications where dissolution predictability affects yield calculations. The technology is electrifying competition between coastal solar facilities and inland vacuum operations.
The FDA's updated sodium reduction guidelines are compelling packaged food reformulation toward larger-crystal salts that deliver perceptible seasoning at lower sodium densities. Manufacturers must document alternative salt performance in stability testing to maintain shelf-life claims. Ready-to-eat meat categories face the steepest compliance timelines under this framework.
Chef-driven tactile seasoning preferences are compressing switching cycles between salt types in professional kitchens. High-volume restaurant operators now specify kosher salt by crystal dimension rather than brand, forcing suppliers to certify geometric consistency. This specification behavior is most visible in independent restaurant clusters across the United States where menu differentiation depends on precise flavor layering.
Kosher Salt Market Segmentation
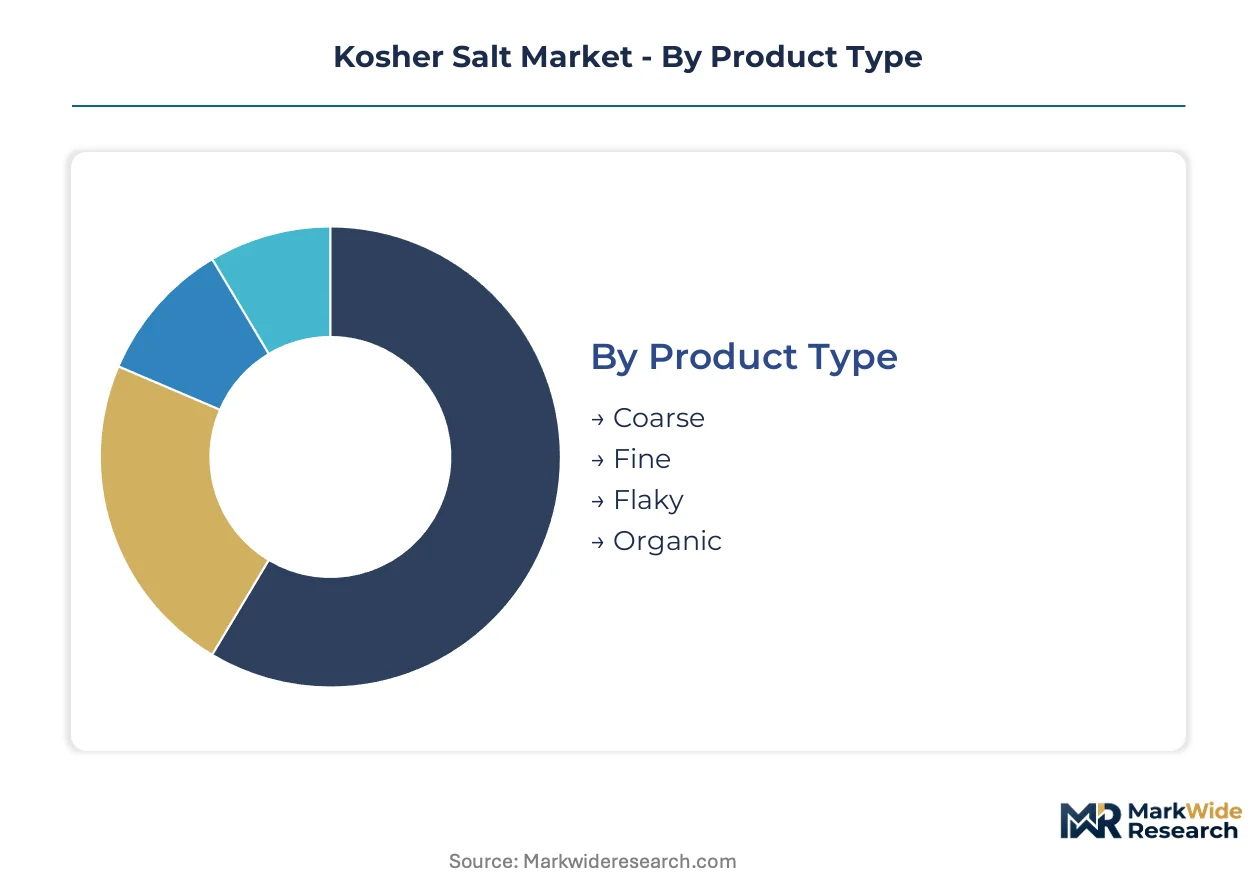
Kosher salt buyers segment sharply by crystal specification needs and operational scale. Procurement patterns diverge between industrial volume purchasers seeking dissolution control and household consumers prioritizing tactile seasoning.
Product Type:
Buyers differentiate primarily by crystal geometry requirements for specific moisture extraction or dissolution applications.
- Coarse:Large, irregular sodium chloride crystals with porous flake structure optimize brine penetration in meat processing. Specialty meat processors in the United States are expanding procurement for traditional curing where crystal size governs moisture extraction efficiency.
- Fine:Smaller grain dimension enables faster dissolution in liquid-based formulations. Food manufacturers favor fine grades for sauce and soup applications where complete sodium dispersion is required within shortened production cycles.
- Flaky:Thin, layered crystal structure provides rapid surface adhesion for finishing applications. Artisanal food manufacturers specify flake geometry for premium product differentiation.
- Organic:Certification-compliant production excluding synthetic processing aids. Emerging observant consumer segments in suburban markets drive demand for legitimacy-verified organic variants.
Coarse product leads volumes today; organic is gaining share fastest.
End User:
Operational scale and formulation sophistication separate procurement behaviors across buyer types.
- Food Manufacturers:Industrial-scale buyers requiring documented curing salt substitutions for USDA process validation. Clean-label sodium reduction strategies favor this segment's additive-free profile requirements.
- Restaurants:High-volume kitchen operators now specify kosher salt by crystal dimension rather than brand. Chef-driven tactile seasoning preferences compress switching cycles in independent restaurant clusters.
- Household:Mass-market consumers purchasing through supermarket retail channels. Traditional Jewish culinary practices intersect with broader gourmet cooking trends in United States metropolitan areas.
- Catering Services:Volume foodservice operations balancing cost efficiency with consistent seasoning delivery. Procurement concentrates in bulk packaging formats for event-scale preparation.
Food manufacturers lead volumes today; restaurants are expanding most quickly.
Packaging Type:
Handling infrastructure and shelf-life requirements determine format selection across the value chain.
- Bulk Packaging:Industrial totes and drums serving meat processors with dedicated brine mixing equipment. Cargill leverages grain-handling infrastructure to control bulk distribution networks.
- Plastic Bags:Standard retail format for household volume with moisture barrier properties. Supermarkets dominate this channel through mass-market grocery shelf placement.
- Glass Containers:Premium positioning for specialty organic variants. Online retailers capture these formats that supermarkets shelve inconsistently.
- Sachets:Single-serve portions for foodservice portion control. Catering operations specify sachets for standardized seasoning in distributed preparation environments.
Bulk packaging leads volumes today; glass containers are climbing the fastest.
Distribution Channel:
Buyer access patterns and product discovery mechanisms vary sharply by channel economics.
- Supermarkets:Mass-market retail shelf placement anchoring consumer brand recognition. Morton Salt dominates this channel through established grocery network relationships.
- Online Retailers:Direct-to-chef distribution capturing premium and specialty organic variants. E-commerce enables geometric specification purchasing bypassing traditional brand loyalty.
- Specialty Stores:Curated selection for observant consumer segments seeking Orthodox Union certification. Emerging suburban markets drive expansion beyond traditional urban strongholds.
- Convenience Stores:Emergency replenishment for household consumers. Limited SKU depth restricts kosher salt availability to standard coarse grades.
Supermarkets lead volumes today; online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's meatpacking district anchors industrial kosher salt procurement for North American curing operations. Specialty processors there specify coarse crystal geometry for controlled brine penetration in traditional applications. This concentration pattern repeats across four additional national markets with distinct regulatory and demand profiles.
United States
Artisanal meat processors in Brooklyn and Chicago expand coarse salt procurement for heritage curing methods. The FDA's updated sodium reduction guidelines compel packaged food reformulation toward larger-crystal salts for perceptible seasoning at lower densities. Kansas City processors validate kosher salt substitutions under USDA meat and poultry oversight protocols.
Canada
Specialty food manufacturers in Toronto and Montreal procure additive-free salts for clean-label export positioning. Health Canada maintains sodium labeling thresholds that align with US FDA frameworks, easing cross-border formulation standardization. Windsor's proximity to Detroit distribution networks concentrates bulk procurement for Great Lakes meat processing clusters.
Israel
Observant consumer segments in Jerusalem and Tel Aviv drive certification-verified demand beyond traditional urban strongholds. The country's national food regulator enforces kosher legitimacy standards that govern product acceptance for religious practice. Haifa's coastal evaporation facilities supply flake-structured variants for premium Mediterranean foodservice channels.
United Kingdom
Gourmet retailers in London and Manchester displace standard table salt with coarse kosher alternatives for home curing revival. The Food Standards Agency monitors sodium content claims on packaged goods, influencing manufacturer salt selection documentation. Birmingham's halal meat processors increasingly specify kosher-certified salts for overlapping religious dietary compliance.
Australia
Artisanal charcuterie producers in Melbourne and Sydney adopt coarse kosher salt for moisture extraction in small-batch curing. Food Standards Australia New Zealand governs additive labeling requirements that favor additive-free salt positioning. Adelaide's specialty foodservice distributors capture premium variants for restaurant kitchen specification purchasing.
Kosher Salt Market Vendor Landscape
Global majors compete with regional champions across bulk distribution infrastructure and certification legitimacy dimensions. The vendor base organizes around three strategic archetypes: grain-handling conglomerates leveraging logistics scale, heritage brands anchoring retail recognition, and specialty purveyors capturing organic and geometric-specification niches. Dominant competitive moves include backward integration into evaporation capacity and geographic expansion of Orthodox Union certification coverage.
Among North American bulk distributors, Cargill Inc and Morton Salt Inc exemplify scale-driven archetypes with divergent channel emphases. Cargill leverages grain-handling infrastructure to control industrial procurement networks, while Morton anchors consumer recognition through mass-market grocery placement. Compass Minerals International Inc occupies a hybrid position, extending seasonal mining capacity into food-grade production during highway-deicing demand windows. San Francisco Salt Company represents the specialty tier, capturing premium organic variants through direct-to-chef distribution channels that bypass traditional retail intermediaries.
| Leading Market Players |
|---|
| Cargill Inc |
| Morton Salt Inc |
| San Francisco Salt Company |
| Saltworks Inc |
| Redmond Inc |
| K+S Windsor Salt Ltd |
| The Marblehead Salt Co LLC |
| Compass Minerals International Inc |
| Diamond Crystal Brands Inc |
| Others |
Supply Flow & Price Mechanics
Clean-label sodium reduction mandates from the FDA are gating qualified supply access and premium-tier pricing power for kosher salt producers serving processed food manufacturers. These regulatory thresholds compress margins on standard grades while amplifying price premiums for certified additive-free variants that satisfy documentation requirements.
Pricing Analysis
Natural gas price pass-through directly governs thermal evaporation cost structures for domestic producers during winter production windows. Contract-based long-term offtake dominates industrial procurement, with price differentiation resting on certification grade and volume scale. Pricing pressure stems from sea salt substitution in premium foodservice channels. Mid-size food manufacturers exhibit highest price sensitivity due to limited alternative sourcing pathways, while artisanal meat processors accept premium positioning for documented USDA compliance.
Supply Chain Analysis
Domestic-content preferences in federal meat procurement specifications are reshaping sourcing patterns toward North American evaporation capacity. Production concentrates in the United States, Canada, and Israel, with raw material dependencies on natural gas feedstock, solar evaporation acreage, and vacuum processing equipment. Single-source vulnerability runs through grain-handling infrastructure operators controlling bulk distribution networks. Distribution runs through supermarket retail anchoring household volume, with online retailers capturing specialty organic variants shelved inconsistently by traditional grocers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kosher salt market functions as a geographic-arbitrage play between FDA-regulated US formulation requirements and Health Canada-aligned export positioning from Ontario and Quebec processors.
For Market Incumbents: Extend Orthodox Union certification coverage into suburban observant consumer segments beyond traditional urban strongholds. Deepen backward integration into solar evaporation capacity to offset natural gas price volatility threatening winter production economics. Anchor channel control through grain-handling infrastructure relationships that limit mid-size competitor sourcing alternatives. For New Entrants and Emerging Players: Direct-to-chef e-commerce routes bypass established retail intermediaries and capture geometric-specification purchasing from independent restaurant clusters. Target organic certification gaps in online retail where supermarkets shelve inconsistently. Penetrate USDA process validation services for meat processors requiring documented curing salt substitution protocols. For Investors and Strategic Acquirers: Roll-up economics work for specialty organic purveyors because certification timeline compression creates barriers that scale players can absorb through multi-facility auditing efficiencies. Target coastal solar evaporation operators with flake-structure consistency advantages over inland thermal methods. Watch FDA sodium reduction enforcement intensity as the inflection signal for clean-label formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Orthodox Union Certification Expansion | Suburban observant segments in the United States drive legitimacy-verified demand beyond urban centers. |
| Solar Evaporation Capacity Buildout | Coastal facilities yield uniform flake porosity that improves dissolution predictability for meat processors. |
| Direct-to-Chef E-Commerce Launch | Online channels capture geometric-specification purchasing that bypasses traditional Morton brand loyalty. |
| USDA Process Validation Services | Documentation revenue streams attach to kosher salt substitutions in Kansas City meat processing clusters. |
| Backward Integration into Evaporation | Cargill leverages grain-handling infrastructure to control captive supply of food-grade production capacity. |
Methodological Framework
Coverage spans the United States, Canada, Israel, the United Kingdom, and Australia, with primary inputs from each market cluster. The analysis combines primary interviews with meat processing plant managers, kosher certification authority auditors, restaurant procurement directors, supermarket category buyers, and specialty foodservice distributors with secondary validation from FDA sodium labeling guidance documents, USDA meat and poultry inspection protocols, Orthodox Union certification directories, and Health Canada food additive regulations. Bottom-up volume triangulation across crystal specification grades reconciles with top-down value estimates from distribution channel economics.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including crystal geometry, end-user operational scale, packaging format handling infrastructure, and distribution channel access patterns. CAGRs derive from regression-adjusted trend extrapolation incorporating solar evaporation technology adoption curves, FDA sodium reduction compliance timelines, and chef-driven specification behavior in independent restaurant clusters.
The model assumes a particular technology adoption path for precision-controlled solar evaporation; alternative pathways for vacuum thermal processing would alter the outlook for flake-structure consistency and dissolution predictability. Forecasts reflect assumptions about regulatory enforcement intensity, natural gas price stability, and sea salt substitution rates in premium foodservice channels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Onion Essential Oil Market