
 Cinnamon Market | 2026-2036
Cinnamon Market Size, Share, and Industry Trends Forecast 2026-2036
Cinnamon Market Analysis
Extract-to-oil value addition is rewriting margin distribution across the cinnamon supply chain. Kotanyi leverages its European grinding and blending footprint to sustain premium positioning in retail spice aisles. McCormick anchors North American private-label and branded shelf presence through controlled sourcing relationships with Sri Lankan estates. Ceylon Spice specializes in single-origin Ceylon grades, differentiating through geographic indication claims and organic certification.
Cinnamon comprises the dried inner bark of Cinnamomum trees, with Ceylon (Cinnamomum verum) containing 0.9-2.3% essential oil and lower coumarin than Cassia (Cinnamomum cassia), making it preferred for high-frequency consumption applications. The bark is harvested during wet seasons, sun-dried into quills, and graded by oil content, color, and quill diameter for food, pharmaceutical, or cosmetic use. Ceylon Cinnamon commands structural margin premiums due to limited acreage in Sri Lanka's southern coastal districts and labor-intensive hand-rolling. Cassia Cinnamon dominates volume throughput, particularly from Indonesia and China, where mechanized peeling supports commodity pricing for industrial baking and beverage formulations. Oil and extract forms capture the fastest expansion trajectory, propelled by pharmaceutical and cosmetics applications requiring standardized cinnamaldehyde concentrations.
FDA food additive regulations and EFSA coumarin exposure limits shape product formulation boundaries and import testing protocols for cinnamon destined for human consumption. ISO 6538 and national pharmacopeial standards govern bark identity, essential oil minimums, and contaminant thresholds for pharmaceutical-grade material. Stakeholders must monitor evolving EU deforestation-free supply chain due diligence rules and organic certification integrity as sourcing transparency becomes a procurement gate.
Market Dynamics
Extract-to-oil value addition is redistributing margin capture from raw bark traders to pharmaceutical and cosmetics formulators in Sri Lanka and Indonesia. FDA and EFSA coumarin limits are forcing Cassia-dependent industrial bakers toward Ceylon-grade alternatives.
Growth Catalysts
- Functional beverage procurement:Manufacturers of adaptogenic drinks and wellness shots now specify Ceylon-grade extracts for clean-label positioning. This pulls premium bark volumes away from traditional spice trading channels.
- EU deforestation-free due diligence:The EU Deforestation Regulation mandates geolocation traceability for imported agricultural commodities. Sri Lankan estate operators with GPS-mapped plots gain preferential access to European pharmaceutical buyers.
- Supercritical CO2 extraction:This solvent-free processing technology yields standardized cinnamaldehyde concentrations for cosmetics applications. Indonesian processors deploying these units capture contract manufacturing business from European fragrance houses.
Market Restraints
- Labor-intensive Ceylon peeling:Sri Lanka's southern coastal districts rely on hand-rolling techniques that resist mechanization. Wage inflation in Galle and Matara districts compresses estate margins against Vietnamese Cassia mechanized operations.
- Coumarin regulatory ceilings:EFSA's 0.1 mg/kg body weight daily limit and FDA import testing protocols block Cassia from high-frequency food applications. German and Austrian retail chains enforce stricter internal thresholds than regulatory minimums.
- Substitute flavor systems:Synthetic cinnamaldehyde and natural alternatives like cassia oil fractions displace whole bark in industrial baking. Commodity buyers in China and Indonesia switch to these lower-cost inputs for price-sensitive formulations.
Strategic Opportunities
- Indian pharmaceutical formulation:CDSCO's streamlined herbal drug approval pathways and domestic Ayurveda demand create pull for certified organic Ceylon extracts. Indian contract manufacturers seek single-origin supply partnerships bypassing European traders.
- US natural cosmetics channel:Sephora and Ulta's clean beauty mandates drive indie skincare brands toward traceable Ceylon oil. Direct-to-brand sourcing agreements bypass traditional flavor and fragrance distributors.
- Carbon credit monetization:Sri Lankan estates with agroforestry certification can bundle carbon sequestration claims with bark shipments. European buyers under CSRD scope 3 reporting requirements value these bundled environmental attributes.
Industry Challenges
- Organic certification integrity:Sri Lanka's fragmented smallholder base complicates audit trails for USDA Organic and EU Organic claims. Certification bodies face backlogs that delay new estate accreditations by 18-24 months.
- Quill grading skill scarcity:Experienced sorters who distinguish Alba, Continental, and Mexican grades by oil content and color are aging out of the workforce. Training programs in Galle district struggle to attract younger workers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cinnamon Market |
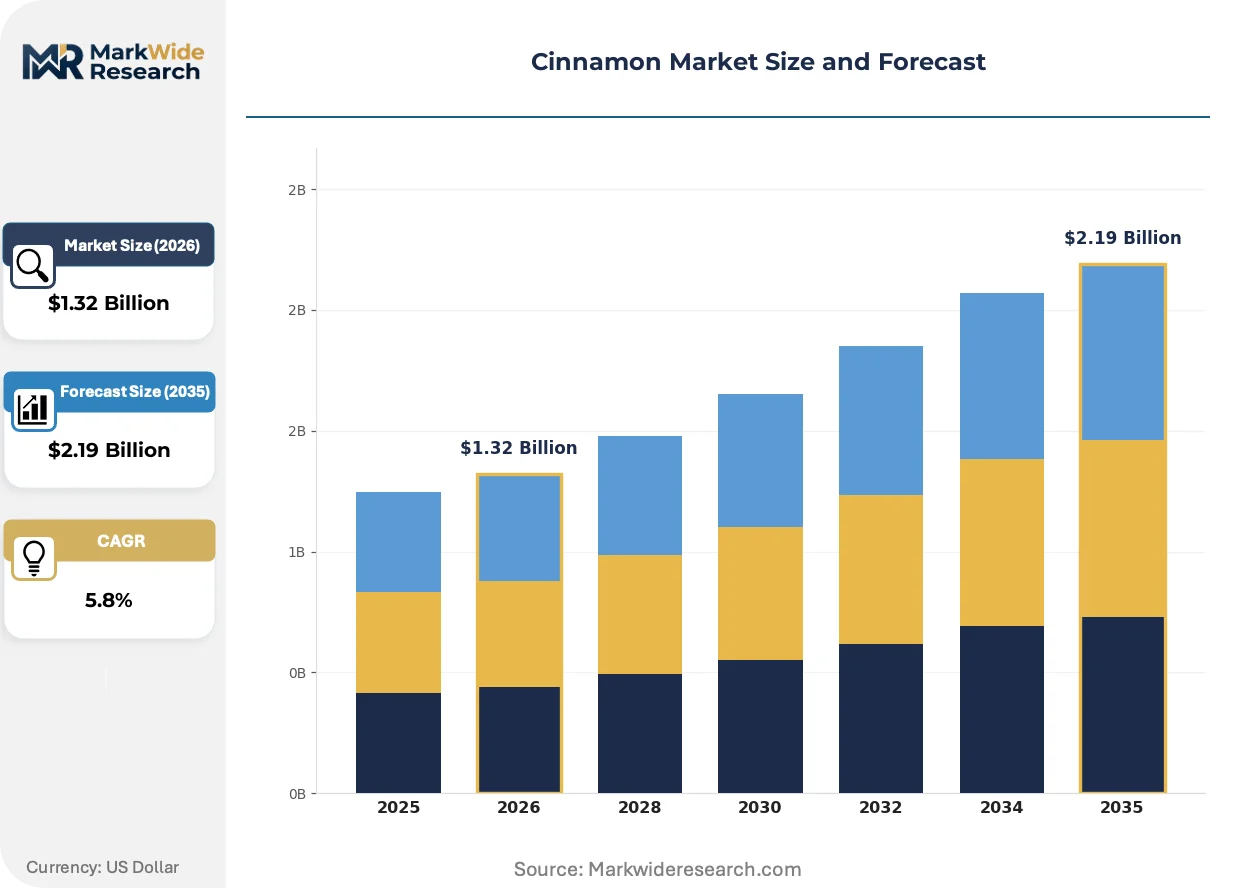
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceylon Cinnamon, Cassia Cinnamon, Ground Cinnamon, Cinnamon Sticks Application: Baking, Beverages, Pharmaceuticals, Cosmetics Form: Whole, Powdered, Oil, Extract Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Kotanyi, Ceylon Spice, McCormick, Kahawatte Plantations, Jideli Food, Angel Yeast, Cinnatopia, Tomax Enterprise, Hsin Kuang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cinnamon Market Emerging Trajectories
Processing technology and regulatory traceability requirements are converging to reshape how cinnamon moves from Sri Lankan estates to end-use formulators. Three developments dominate the current transformation.
Supercritical CO2 extraction systems are hybridizing traditional bark processing with pharmaceutical-grade purification. European cosmetics manufacturers and US natural products brands now specify CO2-extracted oils for their absence of solvent residues. This technology is hybridizing the competitive landscape by enabling Indonesian processors to bypass Sri Lankan quill premiums through standardized output quality.
EU Deforestation Regulation geolocation mandates are forcing supply chain digitization across Sri Lankan and Indonesian export operations. Compliance requires polygon mapping of harvest plots and automated documentation flows that legacy paper-based traders cannot support. Smallholder-dependent supply networks in Vietnam face the steepest adaptation costs as aggregation layers resist transparency investments.
Direct-procurement contracts between Ceylon estates and functional beverage brands are displacing traditional auction and spot-market channels. Manufacturers of adaptogenic shots and wellness drinks now negotiate multi-year supply agreements with specified cinnamaldehyde minimums. This pattern concentrates most visibly in California and New York state, where venture-backed beverage startups prioritize origin storytelling over commodity pricing.
Cinnamon Market Segmentation
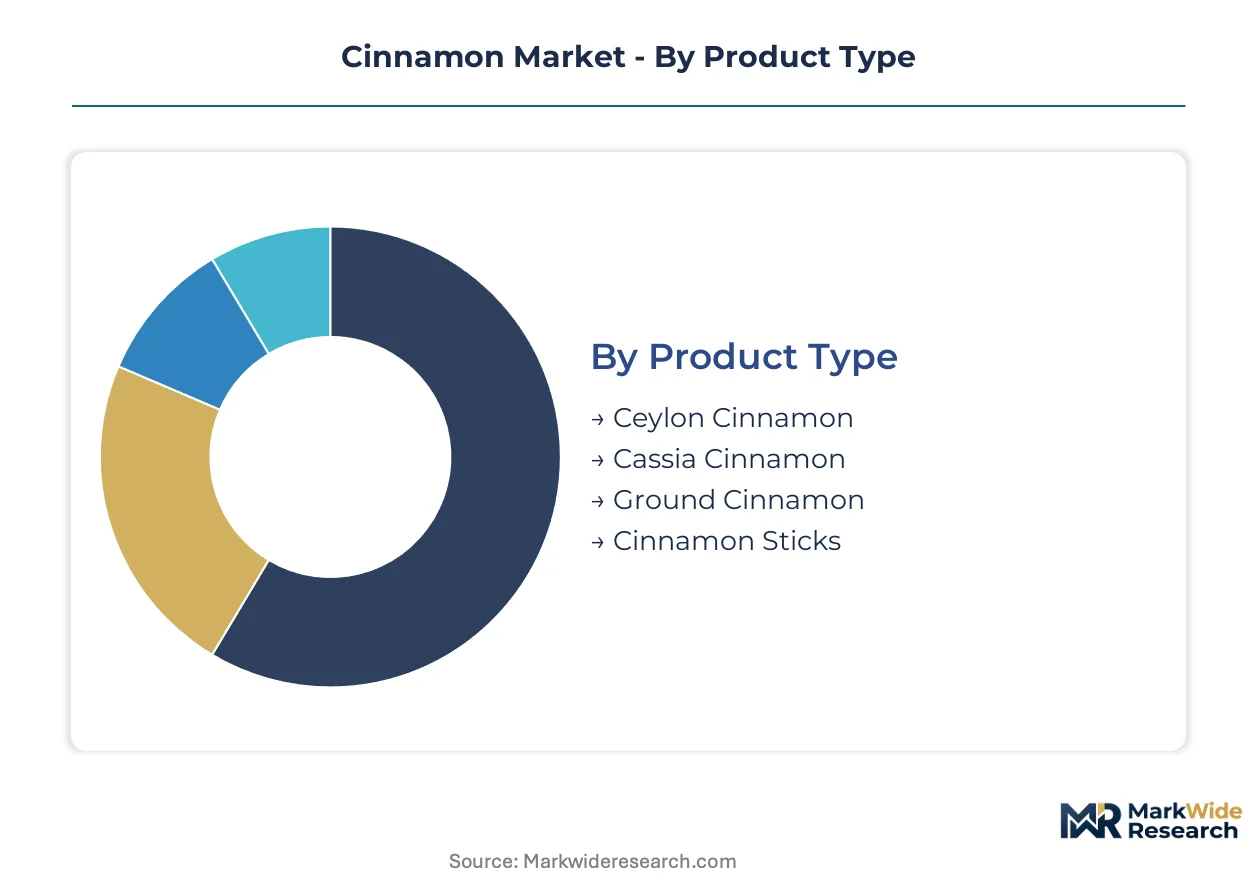
Cinnamon's commercial architecture fragments across four critical dimensions that determine pricing power, regulatory exposure, and channel access. Product origin and coumarin content separate pharmaceutical-grade premiums from commodity baking volumes. Application-specific purity thresholds and form-factor standardization further stratify procurement relationships between estates and end-use formulators.
Product Type:
Origin distinction drives the fundamental cost tier stratification, with labor intensity and phytochemical profile determining access to regulated end-uses.
- Ceylon Cinnamon:Contains 0.9-2.3% essential oil and minimal coumarin, qualifying for high-frequency consumption under EFSA limits. Southern Sri Lankan estates in Galle and Matara districts supply pharmaceutical and premium food manufacturers seeking geographic indication claims.
- Cassia Cinnamon:Higher cinnamaldehyde concentration and elevated coumarin restrict application frequency. Indonesian mechanized peeling operations and Vietnamese bulk cultivation serve industrial baking and commodity flavor houses at price points Ceylon cannot match.
- Ground Cinnamon:Particle size standardization enables consistent dispersion in dry baking mixes. Retail grinders and private-label suppliers specify mesh grades that determine oil retention and shelf stability.
- Cinnamon Sticks:Visual grading by quill diameter and color supports premium positioning in specialty retail and foodservice garnish applications.
Cassia Cinnamon commands the established base. The steepest expansion runs through Ceylon Cinnamon as regulatory limits displace Cassia from daily-consumption formulations.
Application:
End-use purity requirements and consumption frequency create divergent margin structures across regulated industries.
- Pharmaceuticals:Standardized cinnamaldehyde extracts for anti-inflammatory and antimicrobial formulations require ISO 6538 compliance and pharmacopeial certification. CDSCO pathways in India and FDA IND submissions in the US drive specification rigor.
- Beverages:Functional drink manufacturers specify Ceylon-grade extracts for adaptogenic positioning. California and New York venture-backed wellness brands negotiate direct estate contracts bypassing traditional spice traders.
- Cosmetics:Supercritical CO2-extracted oils serve Sephora and Ulta clean beauty mandates with solvent-free credentials.
- Baking:Volume throughput concentrates in industrial producers accepting Cassia for cost-sensitive formulations where coumarin exposure remains below regulatory ceilings.
Baking retains volume leadership. Pharmaceuticals and cosmetics together gain share fastest as extraction technology unlocks standardized active concentrations.
Form:
Processing depth determines value capture distribution between raw bark traders and downstream formulators.
- Extract:Standardized cinnamaldehyde concentrations enable precise dosing in pharmaceutical and cosmetics applications. Indonesian processors deploying supercritical CO2 units capture contract manufacturing from European fragrance houses.
- Oil:Steam-distilled and CO2-expressed grades serve flavor, fragrance, and aromatherapy channels with distinct solvent residue profiles.
- Powdered:Grinding and blending operations in Europe and North America add value through particle size control and contaminant screening.
- Whole:Quill grading by experienced sorters in Sri Lanka's southern districts preserves origin premiums for specialty retail and foodservice.
Whole bark anchors traditional trade flows. Extract forms climb fastest as pharmaceutical and cosmetics formulators seek batch-to-batch consistency unavailable in raw material.
Distribution Channel:
Customer type and purchase scale determine transparency requirements and margin stacking across the value chain.
- Wholesale:Industrial bakeries and flavor houses procure containerized volumes through established trading relationships with Indonesian and Vietnamese aggregators.
- Specialty Stores:Geographic indication and organic certification support premium positioning for Ceylon quills in European and North American gourmet retail.
- Supermarkets:Private-label grinding and blending by Kotanyi and McCormick satisfies mass-market demand for standardized ground cinnamon.
- Online Retail:Direct-to-consumer channels enable estate-level storytelling and subscription models for wellness-focused households.
Wholesale channels move the largest absolute volumes. Online retail expands most quickly as traceability demands and origin narrative preference reshape household purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in industrial baking applications exhibit acute price sensitivity, driving procurement toward Vietnamese and Indonesian Cassia grades. Pharmaceutical and cosmetics formulators demonstrate inelastic demand for Ceylon-certified extracts, absorbing structural premiums for regulatory compliance and origin traceability.
Sri Lanka
Functional beverage manufacturers in California and New York specify Ceylon-grade extracts for adaptogenic positioning, pulling premium volumes from traditional spice auctions. FDA import testing protocols and EFSA coumarin limits reinforce Sri Lankan estate premiums against Cassia alternatives. Galle and Matara districts concentrate hand-rolling operations where wage inflation compresses margins against mechanized competitors.
Indonesia
Industrial bakeries across Germany and Austria procure containerized Cassia volumes at price points Ceylon cannot match, despite stricter internal retail chain thresholds than regulatory minimums. The country's national food safety regulator enforces contaminant screening aligned with EFSA import requirements. Sumatran processing clusters deploy supercritical CO2 extraction units to capture contract manufacturing from European fragrance houses.
Vietnam
Mechanized peeling operations in Yen Bai and Quang Nam provinces supply commodity-grade Cassia for price-sensitive Chinese and ASEAN industrial formulations. The Ministry of Agriculture and Rural Development promotes geographic indication registration to upgrade export positioning. Fragmented smallholder networks face steepest adaptation costs under EU Deforestation Regulation geolocation mandates as aggregation layers resist transparency investments.
United States
Sephora and Ulta clean beauty mandates drive indie skincare brands toward traceable Ceylon oil, bypassing traditional flavor and fragrance distributors. FDA food additive regulations shape extraction purity thresholds and labeling requirements for domestic consumption. California venture-backed wellness startups negotiate direct estate contracts prioritizing origin storytelling over commodity pricing.
India
CDSCO streamlined herbal drug approval pathways and domestic Ayurveda demand create pull for certified organic Ceylon extracts. FSSAI standards govern bark identity and contaminant thresholds for pharmaceutical-grade material. Mumbai and Ahmedabad contract manufacturers seek single-origin supply partnerships bypassing European traders to secure cost advantages.
Cinnamon Market Vendor Landscape
Capability concentration sits with estate-level operators commanding geographic indication and organic certification; scale advantage sits with integrated grinders and blenders serving mass retail channels. The market structures around three tiers: Sri Lankan single-origin estates, European and North American grinding and blending specialists, and Asian commodity processors. Dominant competitive moves include backward integration into estate ownership and technology licensing for supercritical extraction standardization.
Within the premium-tier vector, Ceylon Spice exemplifies geographic indication positioning through single-origin Ceylon grades and organic certification claims. Kotanyi and McCormick occupy positions across the grinding and blending specialist tier, with the former leveraging European footprint and the latter anchoring North American private-label and branded shelf presence. Among Asian commodity processors, Jideli Food and Hsin Kuang represent mechanized Cassia operations serving industrial volume demand.
| Leading Market Players |
|---|
| Kotanyi |
| Ceylon Spice |
| McCormick |
| Kahawatte Plantations |
| Jideli Food |
| Angel Yeast |
| Cinnatopia |
| Tomax Enterprise |
| Hsin Kuang |
| Others |
Supply Flow & Price Mechanics
Colombo Port container freight corridors linking southern Sri Lankan estates to Rotterdam and Hamburg terminals concentrate cost dynamics that amplify Ceylon grade premiums against Indonesian Cassia alternatives. These logistics pathways reward geographic indication claims with price differentiation while squeezing mechanized competitors through origin storytelling value capture.
Pricing Analysis
After-sales service contracts bundling organic certification maintenance and EU Deforestation Regulation compliance documentation drive lifetime value for Ceylon estates. Three-tier pricing structure across premium Ceylon quills, standard Cassia grades, and economy mechanized peels dominates transactional flows. Price differentiation rests on labor-intensive hand-rolling authenticity versus automated throughput. Cost compression in Indonesian Cassia mechanized operations intensifies because of synthetic cinnamaldehyde substitution pressure. Industrial baking procurement teams exhibit acute price sensitivity while pharmaceutical formulators absorb structural premiums for traceable origin documentation.
Supply Chain Analysis
Tariff exposure between Indonesian processors and German industrial bakeries dominates supply chain risk calculations for commodity Cassia flows. Geographic concentration centers on Sri Lanka, Indonesia, and Vietnam for raw bark extraction and primary quill formation. Raw material dependencies draw from monsoon-dependent bark harvests, sulfur-free drying infrastructure, and supercritical CO2 extraction equipment. Single-source vulnerability runs through aging quill grading specialists in Galle district whose skill scarcity threatens batch consistency. Distribution runs through estate-direct contracts for premium Ceylon grades and containerized aggregator channels for industrial Cassia volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Experienced sorters capable of distinguishing Alba from Continental grades by oil content and color represent a vanishing capability pool that constrains premium tier expansion. This human capital scarcity shapes competitive dynamics more profoundly than processing technology diffusion.
For Market Incumbents: Build geographic indication moats through GPS-mapped estate polygons that satisfy EU Deforestation Regulation geolocation mandates ahead of fragmented smallholder networks. Secure backward integration into sulfur-free drying infrastructure in Matara district to defend against Indonesian supercritical CO2 extraction competitors. Channel control through direct procurement contracts with California functional beverage brands offers margin protection against spot-market price volatility. For New Entrants and Emerging Players: Build out certified organic Ceylon extract capacity serving Indian CDSCO herbal drug approval pathways where European trader bypass creates pricing flexibility. Target US natural cosmetics channel direct-to-brand agreements with Sephora-vetted skincare startups seeking solvent-free CO2 extraction credentials. Go-to-market positioning through carbon credit bundling with bark shipments captures CSRD scope 3 reporting demand from European pharmaceutical buyers. For Investors and Strategic Acquirers: Single-origin estate operators with existing USDA Organic accreditation and polygon-mapped harvest plots present acquisition targets with defensible regulatory compliance infrastructure. Long-term viability across the analysis window hinges on traceability technology deployment costs versus premium capture sustainability. Watch for EU Deforestation Regulation enforcement acceleration as the inflection signal indicating compliance capability scarcity premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Deployment | Indonesian processors capture European fragrance house contract manufacturing through solvent-free standardized output. |
| Estate-Level GPS Polygon Mapping | Sri Lankan operators secure preferential EU pharmaceutical buyer access under deforestation-free due diligence rules. |
| Direct-to-Brand Supply Agreements | California wellness startups bypass traditional spice traders for origin storytelling premium capture. |
| Carbon Credit Bundling Programs | Agroforestry-certified estates monetize environmental attributes for CSRD scope 3 reporting European buyers. |
| Quill Grading Workforce Development | Galle district training programs address aging sorter scarcity threatening Alba grade batch consistency. |
Methodological Framework
Cross-validation between estate operator interviews and customs trade flow data anchors the qualitative findings on supply concentration and margin distribution. Primary discussions with Sri Lankan plantation managers, Indonesian processing facility engineers, European pharmaceutical procurement leads, and US functional beverage formulators combined with secondary validation from FDA food additive filings, EFSA scientific opinions, ISO 6538 standards documentation, and EU Deforestation Regulation implementation guidance. Bottom-up estate capacity assessments and top-down trade value reconstructions triangulate volume estimates.
Calibration against historical price spreads between Ceylon and Cassia grades, extraction technology adoption curves, and regulatory compliance cost trajectories shapes the analytical framework. Segmentation dimensions span origin grade, application purity threshold, processing form, and distribution channel depth across the projection horizon. CAGRs derive from trend extrapolation adjusted for coumarin limit enforcement intensity and supercritical CO2 unit deployment rates. Industry-specific inputs include EFSA exposure limit revision probabilities and CDSCO herbal drug approval pathway streamlining momentum.
Practitioners should monitor EU Deforestation Regulation enforcement calibration, synthetic cinnamaldehyde cost parity milestones, and Indonesian wage inflation against Sri Lankan estate labor rates for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Onion Essential Oil Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Hot Pot Seasoning Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Herbs and Spices Market