
 Smoked Black Pepper Market | 2026-2036
Smoked Black Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Black Pepper Market Analytics
The premium-commodity split in smoked black pepper is realigning around cold-smoking duration and wood-source certification. McCormick & Company leverages its North American retail dominance to sustain pricing power in specialty grocers. Olam International Limited anchors global supply through its Vietnam procurement network. Everest Spices differentiates via regional smoke-profile variations targeting South Asian export markets.
Smoked black pepper denotes Piper nigrum fruit subjected to controlled combustion of hardwoods such as hickory or oak, yielding volatile phenolic compounds including guaiacol and syringol that impart characteristic aroma. The process requires moisture content below 12 percent pre-smoking to prevent mold and ensure uniform compound absorption. Powdered pepper leads volume due to food manufacturer demand for ready incorporation, while organic pepper captures expanding margin pools in European and North American specialty retail. Online retail channels grow fastest as direct-to-consumer brands bypass traditional wholesaler markups, though supermarkets retain bulk throughput in emerging markets.
FDA oversight of spice adulteration and mycotoxin thresholds shapes import compliance costs for US-bound shipments. EU REACH and EFSA flavoring substance evaluations constrain allowable smoke-derived compound residues in finished seasonings. India's FSSAI labeling mandates for origin and process disclosure add transparency requirements for export-oriented processors. Stakeholders must monitor evolving smoke residue thresholds across jurisdictions to preempt supply chain disruption.
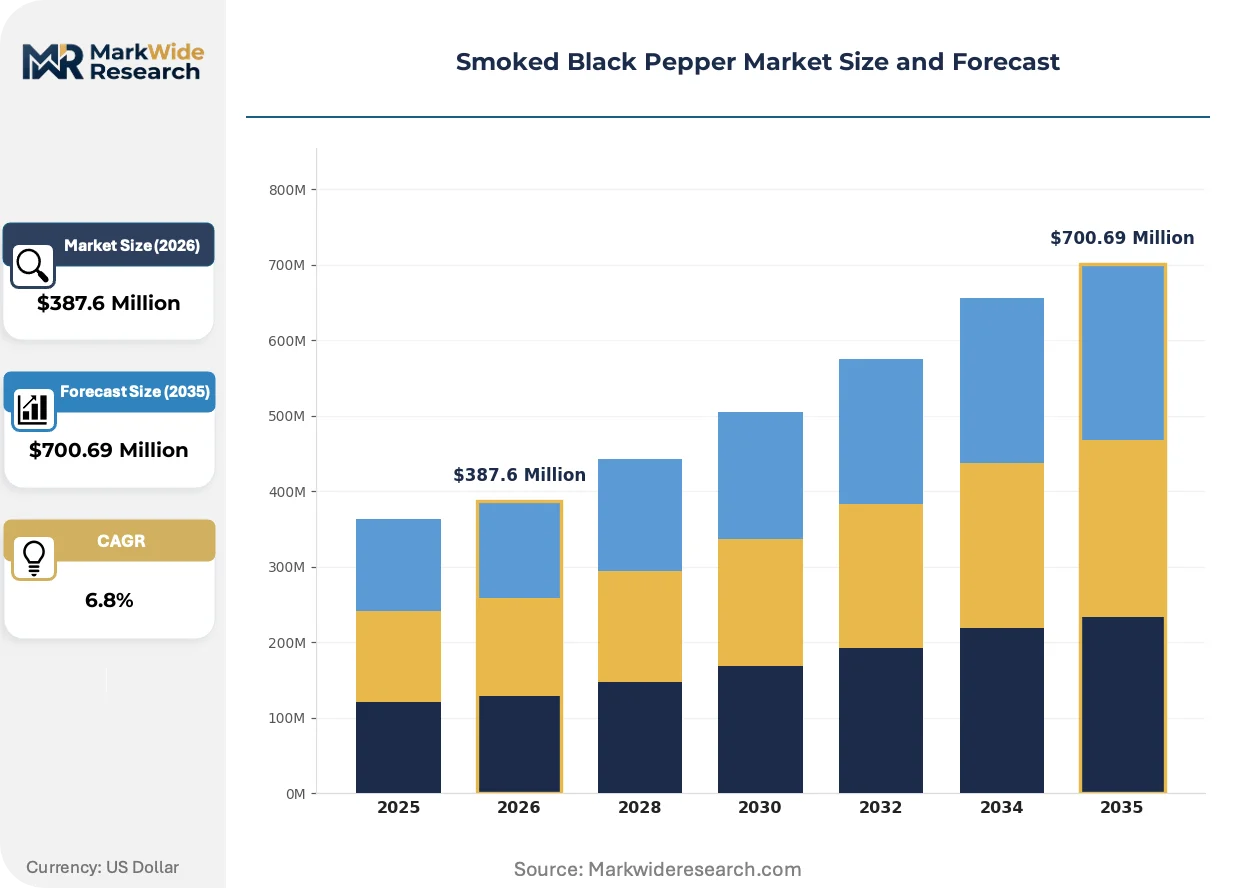
Market Dynamics
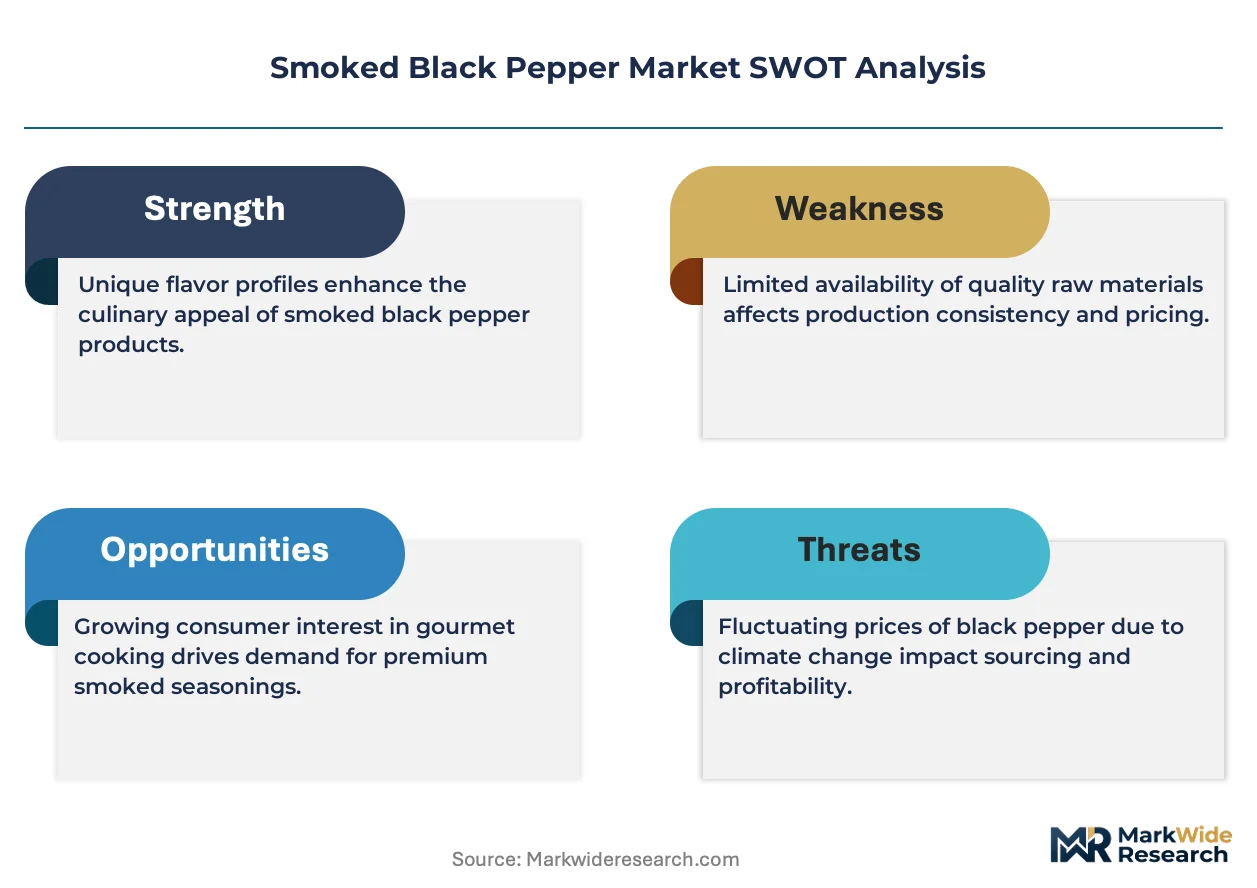
Cold-smoking duration protocols and wood-source certification requirements are restructuring competitive advantage in smoked black pepper, as processors invest in traceable hardwood supply chains to meet tightening EU and North American residue standards.
Growth Catalysts
- EU Flavoring Substance Evaluations:EFSA's tightening thresholds for guaiacol and syringol residues are accelerating facility upgrades among Vietnamese processors seeking European market access.
- Specialty Grocery Expansion:Premium seasoning lines in North American retail channels are absorbing higher-unit-value smoked pepper SKUs as consumer willingness-to-pay for provenance expands.
- Cold-Smoking Technology:Precision humidity and temperature control systems are reducing batch variation, enabling food manufacturers to specify consistent smoke intensity in procurement contracts.
Market Restraints
- Vietnam Supply Concentration:Overreliance on Vietnamese peppercorn sourcing exposes processors to climate volatility and port congestion at Ho Chi Minh City.
- Input Cost Volatility:Hardwood prices for hickory and oak fluctuate with construction sector demand, compressing margins for small-batch smokehouses.
- FDA Mycotoxin Thresholds:Strict aflatoxin limits for US-bound shipments impose testing burdens that disproportionately affect non-integrated traders lacking in-house laboratories.
Strategic Opportunities
- Direct-to-Consumer Channels:Online retail platforms enable specialty brands to bypass traditional wholesaler markups and capture full margin on organic-certified lines.
- South Asian Export Markets:Regional smoke-profile variations targeting diaspora populations in the UK and Gulf states represent underexploited demand pockets.
- Organic Certification Tailwinds:EU Green Deal agricultural transition incentives are expanding organic peppercorn acreage, easing raw material sourcing for certified processors.
Industry Challenges
- Smoke Residue Compliance Timeline:Multi-jurisdiction testing requirements for REACH, FDA, and FSSAI standards extend product release cycles and tie up working capital.
- Skilled Smokehouse Operation:Shortage of technicians trained in hardwood combustion control and moisture management limits facility throughput expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Black Pepper Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Peppercorns, Cracked Pepper, Powdered Pepper, Organic Pepper Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Households, Restaurants, Food Manufacturers, Catering Services Packaging Type: Bags, Jars, Pouches, Bulk Packaging |
| Companies Covered | McCormick & Company, Baria Pepper, Olam International Limited, Everest Spices, MDH Pvt. Ltd., Vietnam Spice Company, Visimex, British Pepper & Spice, Catch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Black Pepper Market Evolving Landscape
Processing technology and distribution architecture are undergoing parallel transformation in smoked black pepper, with automation penetrating traditional smokehouse operations while digital channels reconfigure buyer-seller relationships.
Infrared-assisted cold-smoking chambers are electrifying traditional hardwood combustion methods by enabling precise phenolic compound deposition without open-flame inconsistency. Food manufacturers in ready-meal and snack seasoning segments are adopting these systems to meet batch-to-batch uniformity requirements. The technology is compressing quality variation premiums that previously separated artisanal from industrial suppliers.
REACH authorization requirements for smoke-derived flavoring substances are compelling European processors to document compound migration pathways from wood source to finished seasoning. Industrial consequence includes mandatory supply chain audits and third-party residue certification. Organic and premium lines face the steepest compliance cost escalation, accelerating consolidation among processors with dedicated regulatory affairs functions.
Buyer concentration among North American specialty grocers is consolidating procurement decisions into fewer category managers with authority over premium seasoning resets. Direct sourcing relationships with Vietnamese processors are displacing traditional importer-distributor hierarchies. This pattern is most visible in coastal urban markets where store-brand organic lines compete directly with established specialty labels on smoke-source storytelling.
Smoked Black Pepper Market Segmentation
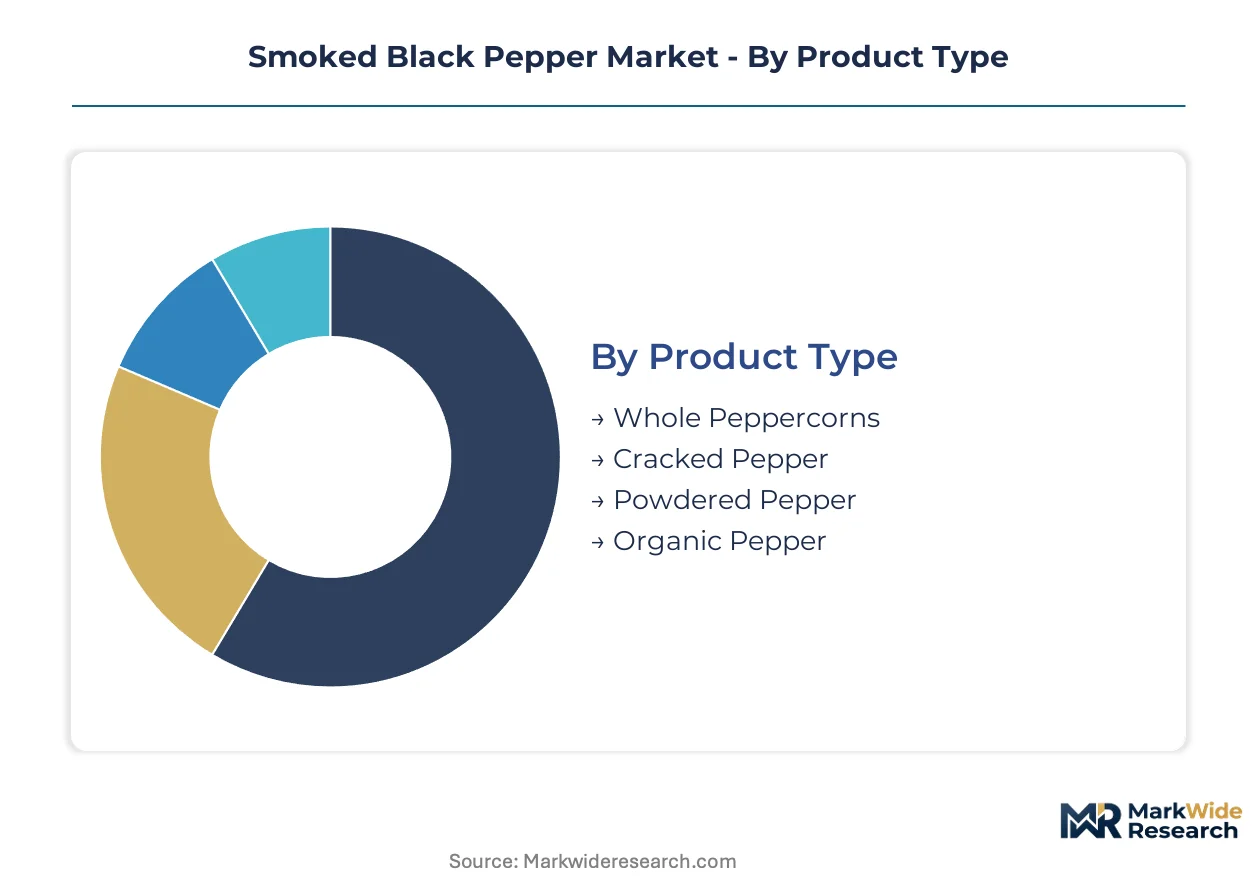
Segmentation in smoked black pepper reveals how certification burdens, processing intensity, and channel economics partition margin capture across the value chain. Processors navigate divergent compliance costs while targeting distinct buyer willingness-to-pay thresholds.
Product Type:
EU REACH authorization for smoke-derived flavoring substances and USDA organic certification impose tiered compliance costs across product formats, with residue testing protocols varying by processing intensity.
- Powdered Pepper:Fine-milled particles below 500 microns enable homogeneous incorporation into seasoning blends and ready-meal formulations. Food manufacturers in Germany and the Netherlands specify batch-to-batch phenolic compound consistency for contract procurement. Powdered formats absorb the highest testing burdens for guaiacol and syringol residues under EFSA thresholds.
- Organic Pepper:Cultivated without synthetic pesticides and processed in certified smokehouses using hardwoods from managed forestry. EU Green Deal agricultural transition incentives are expanding certified acreage in Vietnam. Organic lines command premium positioning in specialty retail channels across France and the United States.
- Whole Peppercorns:Intact fruit retains volatile oils longer; favored by restaurant kitchens for tableside grinding.
- Cracked Pepper:Coarse fragments suit rub applications and visual texture in premium meat packaging.
Leading the category by volume: Powdered Pepper. Growing fastest: Organic Pepper.
Distribution Channel:
Channel selection determines working capital cycles and margin retention, with direct-to-consumer platforms compressing traditional wholesaler markups while supermarkets maintain bulk throughput in emerging markets.
- Online Retail:Direct-to-consumer platforms enable specialty brands to bypass importer-distributor hierarchies and capture full margin on certified lines. Digital channels are expanding fastest in coastal urban United States markets where provenance storytelling drives repeat purchase.
- Specialty Stores:Curated assortments in premium grocers emphasize smoke-source certification and single-origin labeling. Category managers in these channels command increasing authority over premium seasoning resets and private-label development.
- Supermarkets:Mass retail maintains volume throughput through store-brand lines and promotional pricing.
- Wholesalers:Traditional importer-distributor networks serve food service and smaller retail accounts with consolidated procurement.
Highest margin capture: Specialty Stores. Steepest expansion trajectory: Online Retail.
End User:
End-use segmentation tracks specification intensity, with food manufacturers imposing the most stringent batch uniformity requirements while households respond to packaging and storytelling cues.
- Food Manufacturers:Ready-meal and snack seasoning producers specify cold-smoking duration and wood-source documentation in procurement contracts. Infrared-assisted smoking technology adoption concentrates among suppliers serving these accounts in the United States and Germany.
- Restaurants:Fine-dining and fast-casual chains utilize smoked pepper for signature flavor profiles and menu differentiation.
- Households:Consumer packaging emphasizes origin disclosure and organic certification for pantry premiumization.
- Catering Services:Volume purchasers prioritize cost efficiency and consistent supply over provenance attributes.
Dominant demand source by volume: Food Manufacturers. Fastest specification tightening: Restaurants.
Packaging Type:
Packaging economics align with channel and end-use requirements, with shelf-life extension and portion control driving format innovation across retail and food service segments.
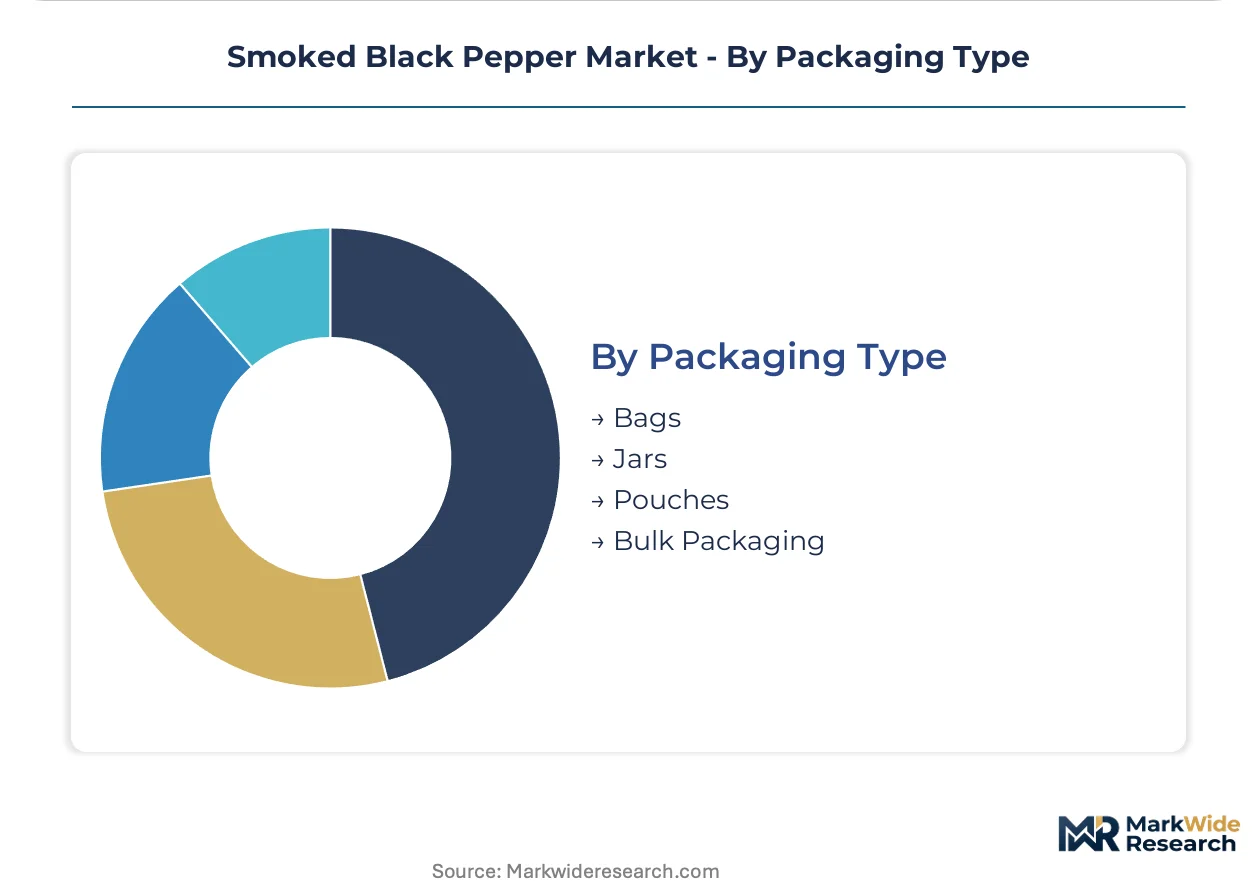
- Jars:Glass containers with grinder tops dominate household pantry segments in North American and European retail. Premium positioning supports single-origin and organic line extensions.
- Pouches:Flexible packaging reduces shipping cube and material cost for online retail fulfillment.
- Bags:Paper and multi-layer formats serve specialty store and supermarket shelf requirements.
- Bulk Packaging:Industrial totes and drums supply food manufacturers and catering operations with minimal unit packaging cost.
Highest unit value realization: Jars. Fastest format innovation: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City anchors global peppercorn processing, with its port infrastructure handling the majority of raw material inflows destined for cold-smoking facilities across Vietnam's Central Highlands corridor.
United States
Specialty grocery chains in coastal metros absorb premium smoked pepper SKUs at elevated price points. FDA mycotoxin thresholds impose testing burdens on Vietnamese import shipments entering through Los Angeles and New York container terminals. Chicago-area food manufacturers specify infrared-assisted cold-smoking protocols in procurement contracts for ready-meal seasoning applications.
Germany
Ready-meal producers in the Ruhr industrial belt demand batch-to-batch phenolic compound consistency for seasoning blends. EFSA's tightening guaiacol and syringol residue thresholds accelerate facility upgrades among suppliers seeking EU market access. Hamburg's spice trading houses consolidate procurement decisions for Central European distribution networks.
Vietnam
Central Highlands peppercorn farms supply raw material to Binh Duong Province smokehouses serving export markets. FSSAI labeling mandates for origin and process disclosure shape documentation requirements for India-bound shipments. Da Nang's processing clusters invest in traceable hardwood supply chains to meet tightening North American and European residue standards.
United Kingdom
South Asian diaspora populations in London and Birmingham drive demand for regional smoke-profile variations. EFSA flavoring substance evaluations constrain allowable smoke-derived compound residues in finished seasonings distributed through British retail channels. Manchester-based specialty importers develop direct sourcing relationships with Vietnamese processors, displacing traditional distributor hierarchies.
India
Export-oriented processors in Kerala and Karnataka navigate FSSAI transparency requirements for origin disclosure. Domestic spice houses in Mumbai and Delhi target Gulf state diaspora markets with differentiated smoke profiles. Gujarat's organic certification expansion aligns with EU Green Deal agricultural transition incentives, easing raw material sourcing for certified processors.
Smoked Black Pepper Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and cold-smoking technology tiers. The vendor base separates into integrated processors with captive Vietnam sourcing, specialty brands commanding retail storytelling premiums, and commodity traders competing on throughput scale. Three archetypes dominate: hardwood supply chain controllers, organic-certified specialists, and direct-to-consumer digital natives. Competitive moves concentrate on backward integration into Vietnamese peppercorn procurement and technology licensing for infrared-assisted smoking systems.
Among North American seasoning conglomerates, McCormick & Company occupies a position exemplifying retail channel dominance and pricing power in specialty grocers. Singapore-based Olam International Limited anchors the integrated processor archetype through its Vietnam procurement network. Indian spice houses Everest Spices and MDH Pvt. Ltd. represent regional specialists targeting South Asian export markets and diaspora demand pockets with differentiated smoke-profile variations.
| Leading Market Players |
|---|
| McCormick & Company |
| Baria Pepper |
| Olam International Limited |
| Everest Spices |
| MDH Pvt. Ltd. |
| Vietnam Spice Company |
| Visimex |
| British Pepper & Spice |
| Catch |
| Others |
Value Network & Pricing Analysis
Black pepper futures on the International Pepper Exchange in Kochi cascade through Vietnamese processing clusters into three-tier pricing stratification across premium organic, certified standard, and commodity bulk tiers. Ho Chi Minh City port congestion and hardwood fuel cost spikes transmit directly into margin compression for mid-tier smokehouses lacking backward integration into Central Highlands peppercorn procurement.
Pricing Analysis
Cold-smoking duration precision anchors value-based pricing for food manufacturer contracts specifying batch-to-batch phenolic compound consistency. Certification grade separates USDA organic and EU organic lines from conventional pepper, while volume scale discounts concentrate in bulk catering supply. Pricing pressure stems from construction sector demand competing for hickory and oak feedstock. Small-batch artisanal producers exhibit lowest price sensitivity; commodity traders serving emerging market supermarkets face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Vietnamese peppercorn output, where Central Highlands farms supply over seventy percent of global raw material for smoked pepper processing. Hardwood combustion inputs draw from managed forestry in the United States and European Union. Tariff exposure on US-bound shipments compounds FDA mycotoxin testing burdens. Distribution runs through Hamburg spice trading houses for European consolidation and direct processor relationships displacing traditional importer-distributor hierarchies in North American coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled smokehouse technician scarcity constrains facility throughput expansion, propping pricing for certified processors with trained hardwood combustion control capabilities. Capacity bottlenecks in Vietnamese cold-smoking infrastructure sustain margin premiums for integrated operators.
For Market Incumbents: Cement backward integration into Central Highlands peppercorn procurement to secure raw material flow against climate volatility. Invest in infrared-assisted smoking technology licensing to defend food manufacturer contract share against artisanal competitors lacking capital for precision humidity control systems. For New Entrants and Emerging Players: Launch via direct-to-consumer online platforms targeting coastal United States organic pantry premiumization. Exploit South Asian diaspora demand pockets in the United Kingdom and Gulf states with regional smoke-profile variations absent from incumbent portfolios. Private-label development for specialty grocery chains offers the most penetrable channel entry. For Investors and Strategic Acquirers: The window for entry favors processors with captive Vietnam sourcing and dedicated regulatory affairs functions. Long-term viability hinges on traceable hardwood supply chain control and multi-jurisdiction residue compliance infrastructure. Watch EFSA smoke-derived compound threshold announcements as the critical inflection signal for facility upgrade capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peppercorn Procurement | Captive Central Highlands sourcing insulates margin from port congestion and climate volatility. |
| Infrared-Assisted Smoking Technology Licensing | Precision phenolic deposition meets food manufacturer batch uniformity specifications in Germany and the United States. |
| Direct-to-Consumer Channel Launch | Online retail bypasses importer-distributor markups and captures full organic certification premium. |
| EU Organic Certification Investment | EU Green Deal agricultural incentives expand certified acreage access for compliant processors. |
| Regional Smoke-Profile Variation Development | Targeted South Asian diaspora markets in the United Kingdom and Gulf states unlock underexploited demand pockets. |
Research Methodology
Independent corroboration across smokehouse operations managers, specialty grocery category buyers, spice trading house procurement leads, and regulatory affairs directors at export-oriented processors underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA import refusal data, EFSA flavoring substance evaluations, EU REACH authorization documentation, and Vietnam customs export statistics enabled bottom-up and top-down triangulation of market sizing.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation modeling incorporated product format, certification tier, distribution channel, and end-use specification intensity. CAGRs derived from processor capacity expansion timelines, organic acreage transition rates under EU Green Deal incentives, and channel shift velocity in North American retail. Hardwood fuel cost indices and EFSA residue threshold evolution served as industry-specific forecast inputs.
Climate volatility in Vietnamese peppercorn growing regions, EFSA guaiacol and syringol limit adjustments, and skilled technician training pipeline constraints are the dominant revision risks. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and channel consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Sichuan Peppercorn Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Global Oregano Essential Oil Market