
 Europe Seasoning Market | 2026-2036
Europe Seasoning Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seasoning Market Insights
Private-label formulation revenue is tilting toward branded blend houses as retailers demand shorter innovation cycles. Kerry Group plc leverages its taste and nutrition campus in Naas to sustain rapid prototyping for European food manufacturers. Fuchs Gruppe anchors its position through backward integration into spice sourcing from origins in Asia and Africa. Döhler GmbH differentiates via liquid extraction technologies that serve beverage and dairy seasoning applications.
Europe seasoning encompasses dried herbs, ground spices, compounded blends, and concentrated sauces used to enhance flavor, preserve shelf stability, or mask off-notes in processed foods. Blends typically contain 3-15 individual ingredients with specified particle sizes between 250-600 microns for uniform dispersion in dry matrices. Herbs and spices dominate value contribution due to volatile oil concentration requirements and origin-linked pricing premiums. Powder form leads volume in food processing channels where dosing accuracy and flowability reduce manufacturing variance, while liquid concentrates capture higher margins in ready-meal and sauce applications.
EFSA evaluates novel ingredient safety under Regulation (EC) No 258/97, while REACH governs extraction solvent residues in concentrated seasonings. The EU Green Deal's pesticide reduction targets are forcing reformulation of herb and spice supply chains toward integrated pest management verified sources. Stakeholders must monitor how the EU Deforestation Regulation reshapes sourcing corridors for tropical spices and whether ECHA adds new substances to restricted solvent lists.
Market Dynamics
Clean-label procurement mandates from European retailers are compressing formulation cycles and forcing blend houses to revalidate entire supply chains for additive-free positioning.
Growth Catalysts
- EU Green Deal pesticide reduction targets:Food manufacturers are accelerating sourcing from integrated pest management verified origins to meet Farm-to-Fork Strategy benchmarks.
- Rotterdam and Barcelona processing corridors:Powder and liquid seasoning volumes are expanding at these hubs due to dosing automation investments by ready-meal producers.
- Clean-label retail procurement:Supermarket chains in Germany, France, and Italy now require 90-day innovation cycles for private-label spice blends.
Market Restraints
- Vanilla and cardamom supply concentration:Madagascar and Guatemala origins face climate volatility that transmits directly into European blend house input costs.
- EFSA novel ingredient evaluation timelines:Regulation (EC) No 258/97 safety assessments create 18-24 month delays for botanical extracts seeking seasoning applications.
- Steam sterilization capacity bottlenecks:Pathogen reduction requirements for raw spice imports exceed available European toll processing infrastructure.
Strategic Opportunities
- Poland and Romania food manufacturing expansion:Greenfield seasoning facilities can capture cost advantages versus Western European production bases.
- EU Deforestation Regulation compliance services:Geolocation traceability platforms for tropical spice sourcing represent an emerging service revenue layer.
- Plant-based meat flavor masking:Off-note suppression blends for pea and oat protein bases command formulation premiums in alternative protein applications.
Industry Challenges
- Sensory scientist scarcity:Flavor chemist and trained descriptive panel recruitment lags behind clean-label reformulation demand in European flavor houses.
- REACH solvent residue compliance:Extraction process revalidation for concentrated seasonings requires capital deployment into supercritical CO2 infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seasoning Market |
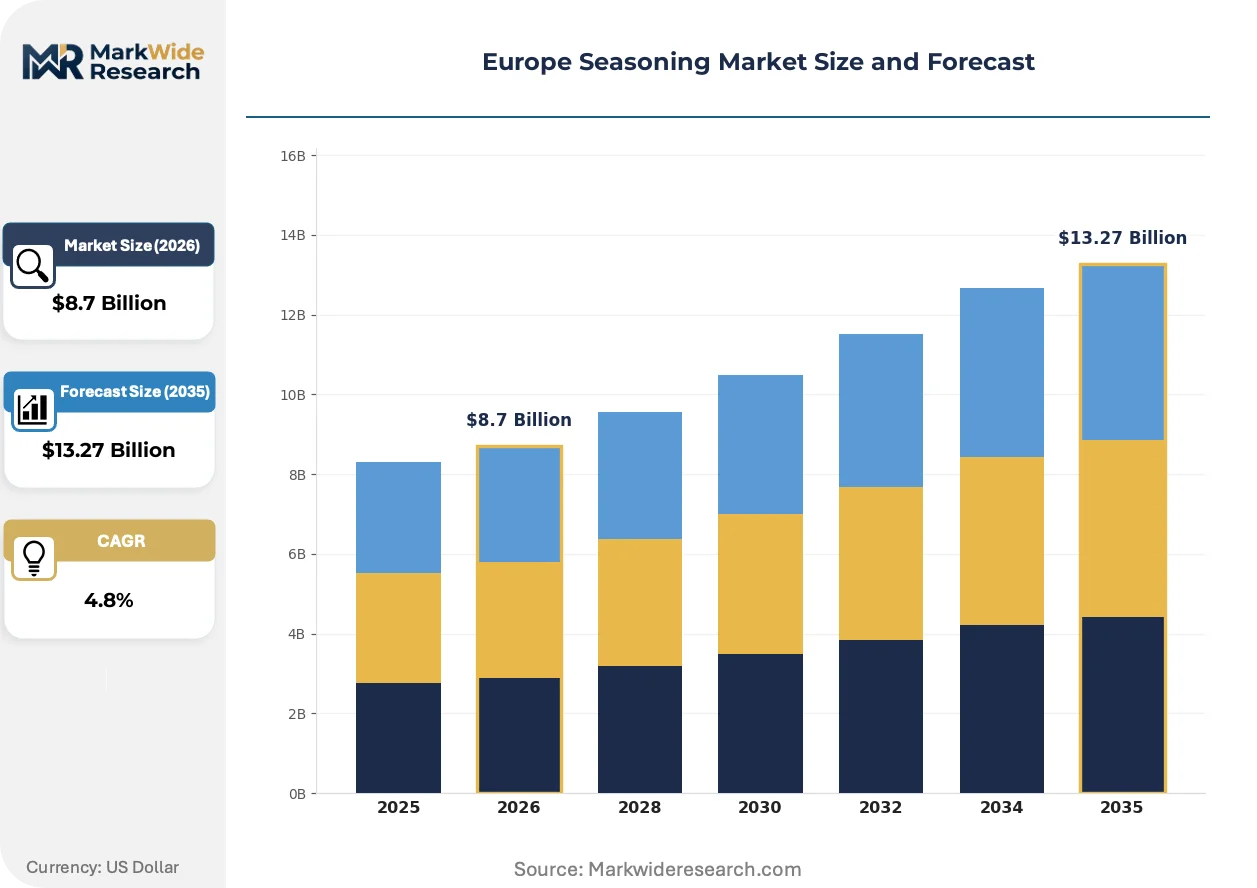
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Blends, Sauces Application: Food Processing, Restaurant, Retail, Catering Form: Liquid, Powder, Granular, Paste Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | McCormick & Company, Inc., Kerry Group plc, Olam International Limited, Associated British Foods plc, Fuchs Gruppe, Döhler GmbH, Euroma B.V., Verstegen Spices & Sauces B.V., SHS Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seasoning Market Trends and Innovations
Extraction technologies and traceability systems are converging to reshape how European blend houses formulate, source, and validate seasoning compositions for processor and retail channels.
Supercritical CO2 extraction is hybridizing volatile oil recovery from delicate herbs and spices. Mid-sized blend houses in the Netherlands and Spain are adopting these systems to eliminate REACH-regulated solvent residues. The technology is compressing the gap between artisanal cold-pressed quality and industrial extraction throughput.
EFSA's evolving guidance on novel botanicals is tightening safety dossier requirements for traditional spice extracts. Food manufacturers must now submit comprehensive toxicological data for heritage ingredients used in new applications. The ready-meal segment is responding by narrowing innovation pipelines to established GRAS-status materials.
Retailer-driven specification tightening is consolidating supplier relationships toward vertically integrated blend houses with captive analytical laboratories. German and French supermarket chains now mandate batch-level mycotoxin and pesticide residue certificates. This certification burden is displacing smaller toll blenders from approved vendor lists.
Europe Seasoning Market Segmentation
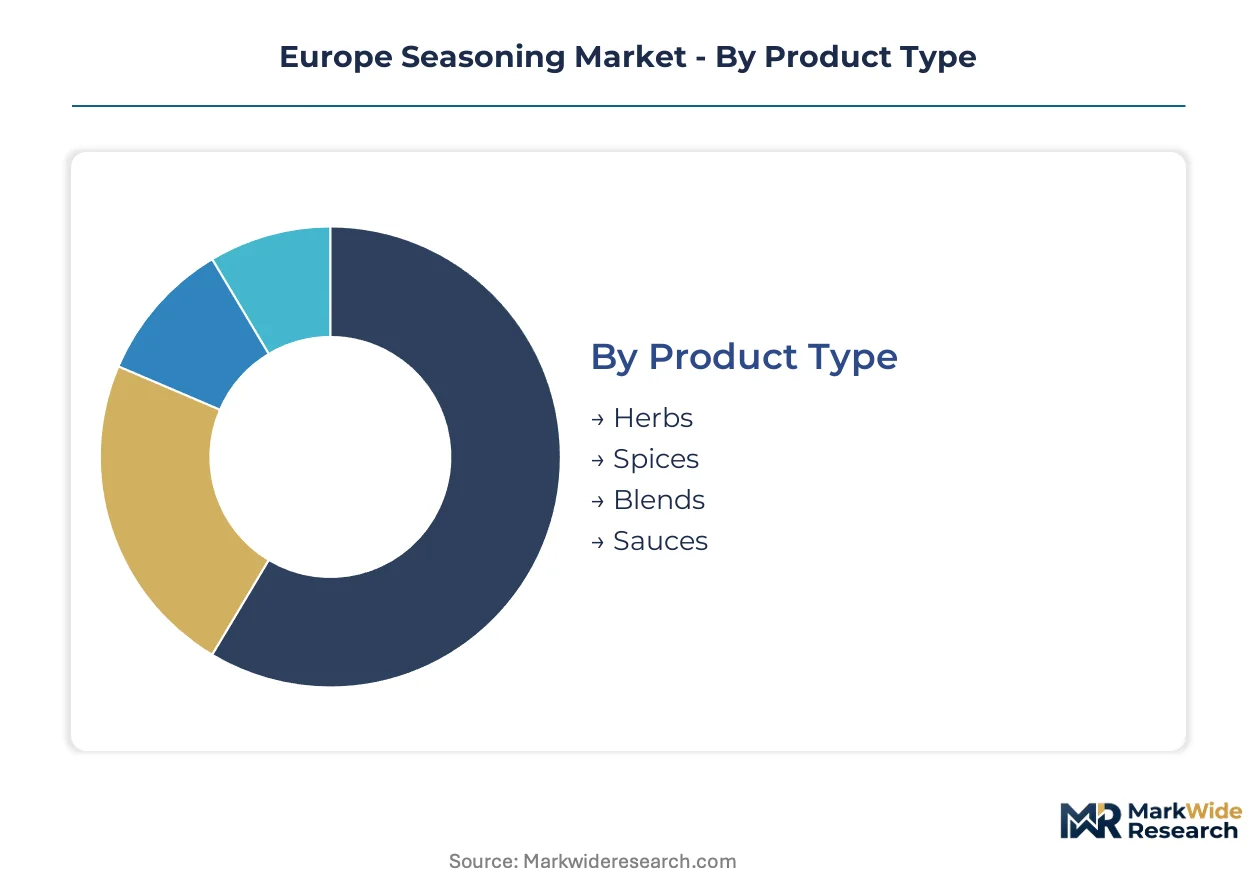
Segmentation in the Europe seasoning market reveals how procurement priorities diverge between industrial processors seeking dosing precision and foodservice operators prioritizing flavor intensity. Understanding these fault lines guides blend house capacity allocation and regulatory compliance investments across the value chain.
Product Type:
Mature commodity segments coexist with emerging value-added formats as clean-label mandates reshape formulation economics.
- Herbs:Dried leafy materials with volatile oil specifications between 0.5-3.0% by weight. German and French retail chains are consolidating procurement toward single-origin dried basil and oregano with integrated pest management verification under EU Green Deal pesticide reduction targets.
- Spices:Ground seed, bark, or rhizome products where particle size distribution determines extraction efficiency. Rotterdam processing corridors are expanding steam sterilization capacity for raw spice imports facing EFSA pathogen reduction requirements.
- Blends:Multi-component formulations containing 3-15 specified ingredients. Italian and Spanish ready-meal manufacturers are driving demand for additive-free blends with 90-day innovation cycles.
- Sauces:Concentrated liquid or semi-liquid flavoring systems. Beverage and dairy applications in France and Germany are adopting cold-processed sauce bases to avoid REACH-regulated solvent residues.
Spices retain volume leadership; blends hold the steepest expansion curve.
Application:
Cost tier differentiation separates high-automation industrial demand from labor-intensive foodservice procurement.
- Food Processing:Large-volume seasoning integration requiring dosing accuracy within ±2% variance. Powder formats dominate at Barcelona and Rotterdam hubs where ready-meal producers have invested in pneumatic conveying systems.
- Restaurant:Flavor-intensity-focused procurement with shorter lead times. Independent operators across Italy and Germany are shifting toward pre-portioned blend sachets to reduce kitchen labor.
- Retail:Private-label and branded packaged seasonings for home consumption. Supermarket chains in France now mandate batch-level mycotoxin certificates, displacing smaller toll blenders from approved vendor lists.
- Catering:Institutional volume procurement with standardized specification requirements. Cost pressures in Poland and Romania are driving consolidation toward regional blend houses with captive analytical laboratories.
Food processing captures the highest absolute volumes; catering climbs fastest as Eastern European institutional foodservice expands.
Form:
Margin structure varies sharply between bulk powder commodities and concentrated liquid specialties.
- Liquid:Extract-based concentrates with soluble solids content typically 20-60%. Döhler GmbH and comparable specialists are deploying supercritical CO2 extraction in the Netherlands and Spain to eliminate solvent residue compliance risks under REACH.
- Powder:Spray-dried or ground materials with specified flowability indices. Food processing corridors around Rotterdam and Barcelona are expanding powder seasoning volumes following automation investments by ready-meal producers.
- Granular:Agglomerated particles with controlled dissolution rates. German soup and sauce manufacturers are adopting granular formats for reduced dusting during high-speed packaging lines.
- Paste:Semi-solid concentrates with moisture content 30-50%. Mediterranean cuisine applications in Italy and Spain favor paste formats for marinades and cooking bases.
Powder maintains volume dominance; liquid extracts gain share fastest in premium beverage and dairy applications.
Distribution Channel:
Customer type fragmentation separates price-sensitive mass retail from specification-driven direct procurement.
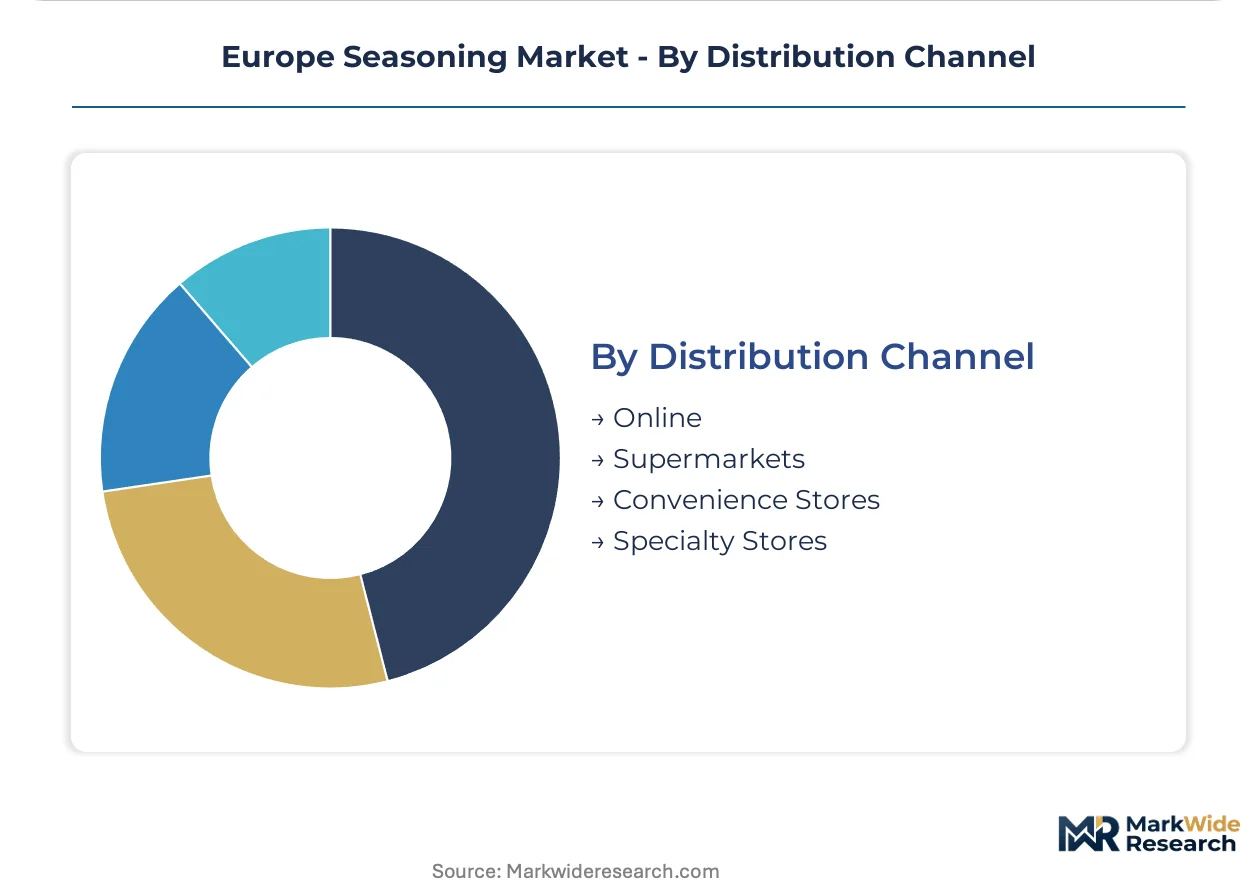
- Online:Direct-to-consumer and B2B platform sales with expanding SKU breadth. Specialist blend houses are using digital channels to reach small-batch food manufacturers bypassing traditional distributor markups.
- Supermarkets:Dominant retail channel for packaged seasonings with strict private-label specifications. German and French chains now require 90-day innovation cycles and complete supply chain revalidation for additive-free positioning.
- Convenience Stores:Impulse-oriented smaller format retail. Single-serve and travel-size seasoning packets are expanding shelf space in urban convenience networks across France and Italy.
- Specialty Stores:Premium and ethnic-focused retail with origin-linked storytelling. Mediterranean herb shops in Italy and spice merchants in the Netherlands are driving demand for geolocation-verified sourcing under EU Deforestation Regulation compliance requirements.
Supermarkets retain volume leadership; online channels expand most quickly as direct procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European procurement channels. German and French retail buyers demand additive-free positioning with compressed innovation cycles, while Eastern European food manufacturers prioritize cost-efficient bulk sourcing. Southern European foodservice operators show intermediate sensitivity, trading flavor intensity premiums against labor reduction benefits.
Germany
Supermarket chains mandate 90-day reformulation cycles for private-label spice blends. EFSA novel ingredient evaluations under Regulation (EC) No 258/97 create compliance bottlenecks for botanical extract introductions. The Hamburg-Rotterdam corridor anchors powder seasoning automation investments by ready-meal producers seeking dosing precision within ±2% variance.
France
Beverage and dairy applications drive cold-processed sauce base adoption to circumvent REACH-regulated solvent residues. The EU Green Deal pesticide reduction targets force integrated pest management verification for dried herb procurement. Lyon and Paris processing clusters expand supercritical CO2 extraction capacity for volatile oil recovery from delicate botanicals.
Italy
Ready-meal manufacturers accelerate demand for additive-free blends with specified particle distributions between 250-600 microns. Mediterranean cuisine applications favor paste formats for marinades and cooking bases. The Emilia-Romagna food processing belt concentrates seasoning procurement for pasta sauce and prepared meal production lines.
Netherlands
Rotterdam's processing corridor attracts pneumatic conveying system investments from pan-European ready-meal producers. Steam sterilization capacity bottlenecks for raw spice imports exceed available toll processing infrastructure. Dutch blend houses deploy geolocation traceability platforms to satisfy EU Deforestation Regulation compliance requirements for tropical spice sourcing.
Poland
Institutional foodservice expansion drives cost-optimized seasoning procurement from regional blend houses with captive analytical laboratories. Greenfield seasoning facilities capture production cost advantages versus Western European bases. Warsaw and Krakow manufacturing zones concentrate contract manufacturing for pan-European retail private-label programs.
Europe Seasoning Market Competitive Landscape
Capability concentration sits with specialized extraction technology providers; scale advantage sits with diversified taste and nutrition conglomerates. The vendor base organizes into three functional tiers: vertically integrated spice originators controlling upstream supply, mid-sized blend houses with rapid prototyping campuses, and liquid extraction specialists serving beverage and dairy channels. Dominant competitive moves include backward integration into integrated pest management verified sourcing and supercritical CO2 infrastructure deployment for REACH compliance.
Within the diversified nutrition tier, Kerry Group plc and Associated British Foods plc exemplify scale-driven positioning across European food manufacturing corridors. Among specialized blend houses, Fuchs Gruppe and Döhler GmbH occupy distinct archetype positions—Fuchs exemplifying origin-integrated spice procurement and Döhler representing liquid extraction technology specialization for beverage and dairy applications. McCormick & Company, Inc. anchors the premium-branded retail vector with established supermarket channel relationships.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Kerry Group plc |
| Olam International Limited |
| Associated British Foods plc |
| Fuchs Gruppe |
| Döhler GmbH |
| Euroma B.V. |
| Verstegen Spices & Sauces B.V. |
| SHS Group |
| Others |
Pricing and Supply Chain Analysis
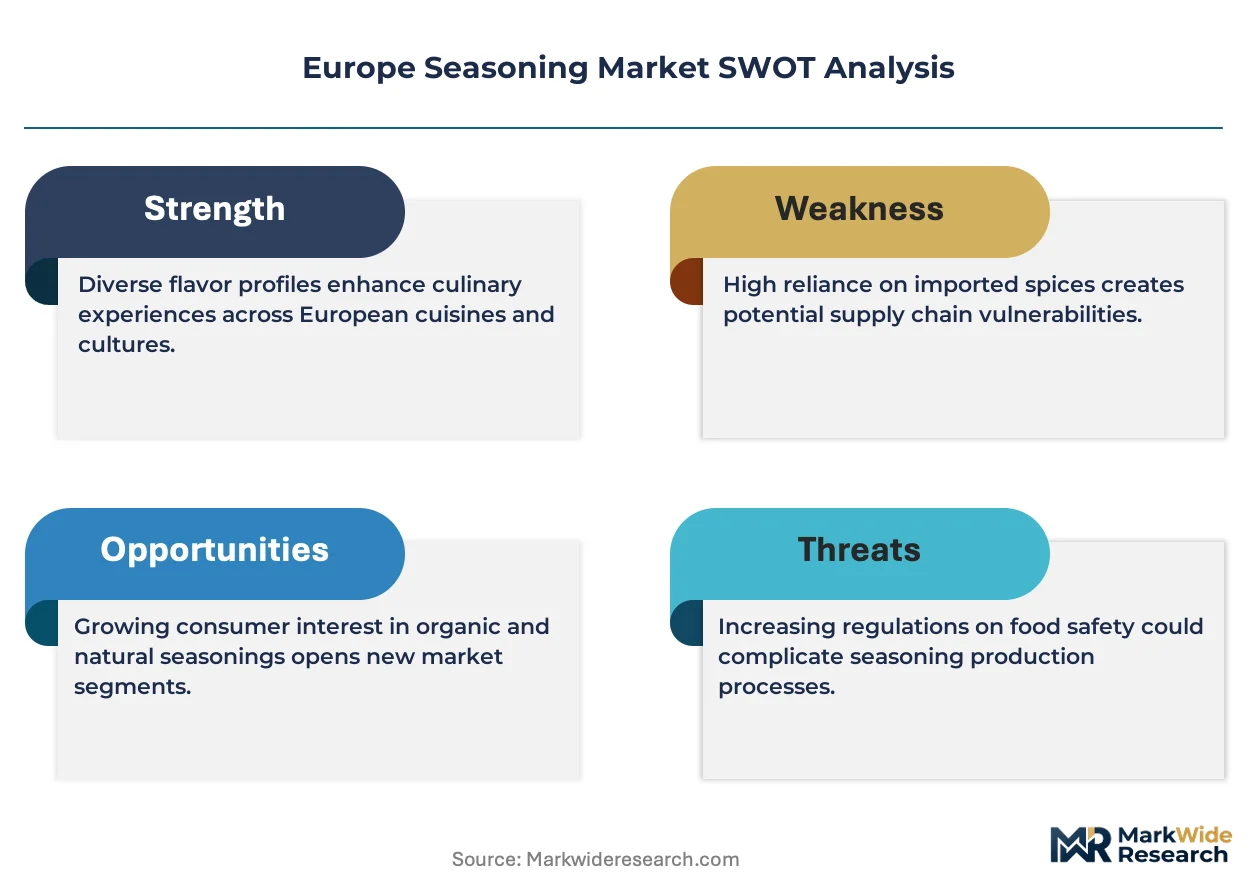
Madagascar vanilla and Guatemalan cardamom origins concentrate upstream supply for European blend houses, anchoring margin pools in extraction technology ownership and geolocation-verified sourcing services rather than commodity trading alone. REACH solvent residue compliance and EU Deforestation Regulation traceability requirements are compressing toll processing margins while rewarding vertically integrated operators with captive analytical laboratories.
Pricing Analysis
After-sales revenue from technical formulation support and rapid prototyping contracts drives lifetime value for blend house relationships with ready-meal manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates supercritical CO2-extracted volatile oils from conventional solvent-based concentrates and commodity ground spices. Cost compression in standard-tier powder blends is intensifying because Rotterdam and Barcelona processing corridors are expanding pneumatic conveying automation. Food processing buyers show highest price sensitivity due to dosing precision requirements and volume scale, while beverage and dairy applications accept premium positioning for cold-processed liquid concentrates.
Supply Chain Analysis
Tariff exposure between tropical origin countries and EU processing hubs dominates supply chain risk assessment for European seasoning procurement. Raw spice sourcing draws from Madagascar, Guatemala, and Vietnam for vanilla, cardamom, and pepper respectively. Steam sterilization capacity bottlenecks in European toll processing infrastructure create single-source vulnerability for pathogen-reduced imports. Distribution runs through Rotterdam and Barcelona corridors for industrial volumes, with specialty retail channels feeding from Dutch and Italian geolocation-verified sourcing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained sensory scientists and flavor chemists with clean-label formulation expertise represent the critical capability gap constraining European blend house expansion, with recruitment timelines lagging 90-day retail innovation cycles by 12-18 months.
For Market Incumbents: Pre-empt emerging competition from mid-sized Dutch and Spanish extraction technology specialists by deploying supercritical CO2 infrastructure before REACH solvent restrictions tighten. Capture backward integration into integrated pest management verified herb origins in Germany and France to defend against private-label displacement by retailer-controlled supply chains. Lock in analytical laboratory certification capacity to maintain approved vendor status as German and French supermarket chains mandate batch-level mycotoxin documentation. For New Entrants and Emerging Players: Build out greenfield seasoning facilities in Poland and Romania to capture cost advantages versus Western European production bases while serving institutional foodservice expansion. Target plant-based meat flavor masking applications as the most penetrable segment, where off-note suppression blends for pea and oat protein bases command formulation premiums. Establish direct-to-food-manufacturer digital procurement platforms to bypass traditional distributor markups and accelerate customer acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-cap blend houses in the Netherlands and Spain that have deployed extraction technology but lack origin-integrated sourcing scale. Long-term viability across the projection horizon rests on geolocation traceability platform ownership and EU Deforestation Regulation compliance service revenue layers. Watch for ECHA additions to restricted solvent lists as the inflection indicator that would accelerate supercritical CO2 infrastructure deployment and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Verified Origins | Captures integrated pest management certification for German and French retail procurement mandates. |
| Supercritical CO2 Infrastructure Deployment | Eliminates REACH-regulated solvent residues for Lyon and Paris beverage and dairy processing clusters. |
| Geolocation Traceability Platform Launch | Services EU Deforestation Regulation compliance for tropical spice sourcing corridors through Rotterdam. |
| Rapid Prototyping Campus Expansion | Compresses innovation cycles to 90-day retail requirements at Kerry Group's Naas taste and nutrition facility. |
| Plant-Based Protein Flavor Masking R&D | Captures formulation premiums in alternative protein applications for pea and oat protein bases. |
Research Methodology
Operator-level perspectives from procurement directors at German and French supermarket chains, technical directors at Rotterdam and Barcelona ready-meal processing facilities, and regulatory affairs leads at Dutch and Spanish blend houses anchored the qualitative base. Primary interview findings triangulated against EFSA guidance documents, ECHA restricted substance registers, EU customs trade data for spice imports, and SEC filings from listed taste and nutrition conglomerates. Bottom-up volume modeling across product type, application, and form segments validated against top-down market sizing from trade association statistics.
Scenario-bracketing around pesticide reduction target implementation timelines and EU Deforestation Regulation enforcement phases structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, form, and distribution channel with regional regulatory cluster differentiation. CAGRs derived from elasticity-adjusted volume projections incorporating automation investment cycles at processing corridors and clean-label procurement mandate diffusion rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Polish and Romanian greenfield entrants or accelerated EFSA novel ingredient approval pathways would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Cajun Spice Market