
 Savoury Seasoning Market | 2026-2036
Savoury Seasoning Market Size, Share, and Industry Trends Forecast 2026-2036
Savoury Seasoning Market Analytics
Food service verticals is recalibrating procurement priorities toward umami-rich, low-sodium formulations. Kerry Group plc leverages its taste modulation technology to capture institutional kitchen contracts across Europe. Ajinomoto Co., Inc. dominates fermented seasoning substrates through its MSG and nucleotide portfolio. Givaudan anchors premium savory flavor development with its culinary innovation centers in Asia and Latin America.
Savoury seasoning comprises dried, ground, or extracted plant-derived and fermented materials formulated to enhance salt perception, meatiness, and aromatic depth in prepared foods. Blending typically involves particle size standardization between 250 and 850 microns for uniform dispersion in dry applications and controlled release in thermal processing. Blends command the widest margin pools due to proprietary formulations and customer co-development agreements. Powder form leads volume in industrial channels where dosing precision and shelf stability matter. Food Processing application segments sustain the fastest growth as ready-meal and snack manufacturers outsource compound seasoning production.
EFSA evaluates novel savory flavor compounds under its food additive re-evaluation program, while FDA enforces FSMA preventive controls for seasoning manufacturing facilities. REACH compliance shapes ingredient sourcing for European processors using natural extractives. ISO 22000 certification has become a baseline qualifier for export-oriented seasoning suppliers. Stakeholders must monitor evolving sodium reduction mandates and natural extract labeling thresholds to align R&D pipelines with tightening compliance frameworks.
Market Dynamics
Clean-label reformulation mandates from EFSA are compressing traditional additive-dependent portfolios while Southeast Asian food processors scale industrial seasoning demand. This regulatory-demand tension is restructuring supplier capabilities across the value chain.
Growth Catalysts
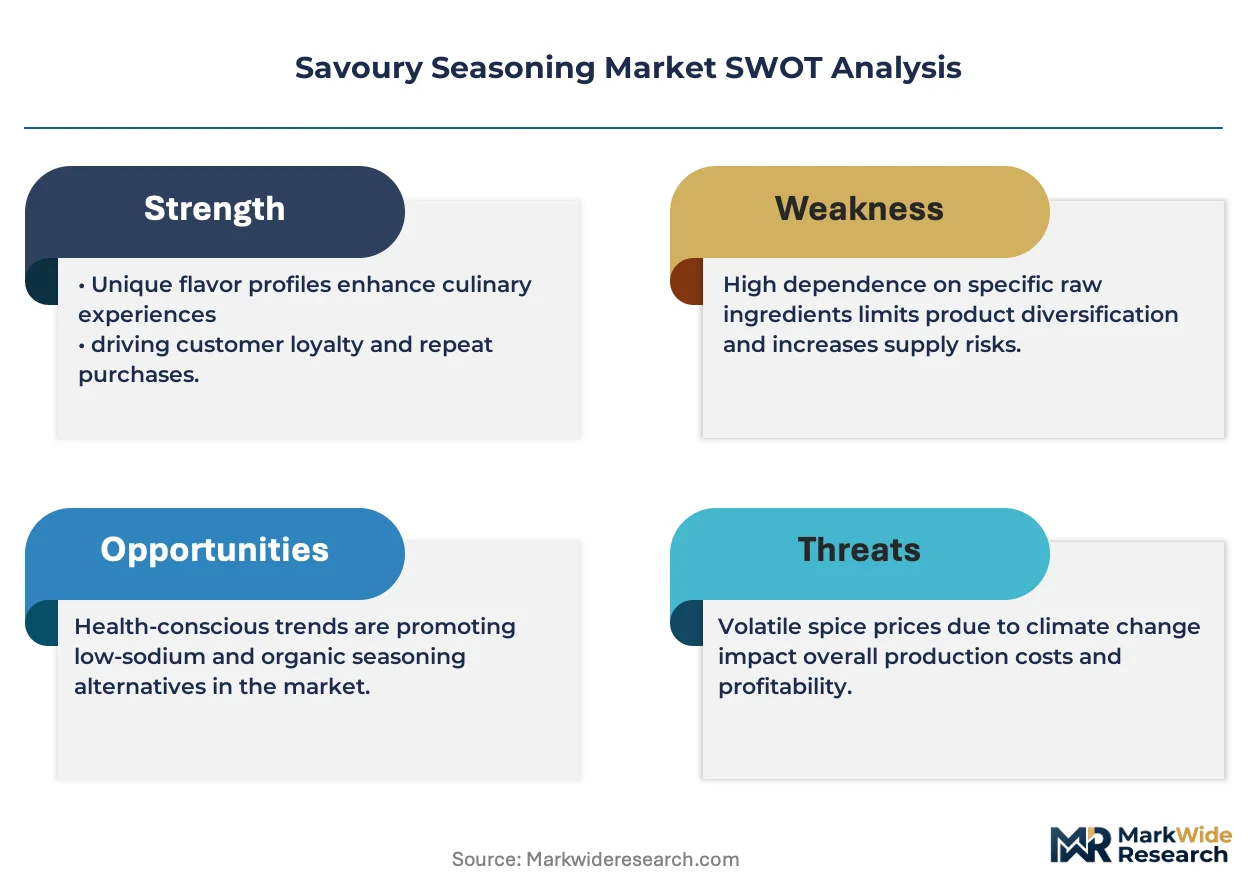
- EFSA Additive Re-evaluation:Tightened disclosure requirements under EFSA guidelines are accelerating clean-label seasoning development. Food manufacturers are reformulating portfolios to eliminate E-number dependencies.
- Southeast Asian Processing Expansion:Industrial food processing growth in Indonesia, Vietnam, and Thailand is creating concentrated demand for standardized compound seasonings. Traditional spice consumption patterns are industrializing rapidly.
- Fermented Substrate Technology:Advanced fermentation processes for umami nucleotides are enabling sodium reduction without taste compromise. Ready-meal manufacturers are adopting these substrates at scale.
Market Restraints
- Raw Material Volatility:Climate-driven supply fluctuations in cardamom, black pepper, and paprika origins are compressing margin predictability. Sourcing teams face procurement uncertainty across harvest cycles.
- Natural Extract Concentration:Premium botanical extract supply concentrates in specific Mediterranean and Indian growing regions. Geographic clustering creates single-point vulnerability for clean-label formulators.
- Labeling Threshold Complexity:Divergent natural extract labeling thresholds between EU member states and FDA jurisdictions create formulation fragmentation. Product platforms require regional customization.
Strategic Opportunities
- Indian Food Processing:Underpenetrated industrial seasoning adoption in India's organized food sector offers expansion white space. FSSAI compliance alignment unlocks institutional kitchen and QSR supply contracts.
- Precision Fermentation Convergence:Integration of synthetic biology with traditional fermentation is creating novel savory molecules. Biotechnology firms and flavor houses are co-developing next-generation substrates.
- Direct-to-Manufacturer Platforms:Digital procurement channels are disintermediating traditional spice trading layers. Compound seasoning suppliers are building direct formulation partnerships with mid-sized food processors.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists with dual expertise in natural extract stability and industrial scale-up are in short supply. Technical recruitment lags portfolio expansion timelines.
- ISO 22000 Certification Backlogs:Export-oriented suppliers face extended audit queues for food safety management certification. Facility upgrades and documentation requirements strain capital deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savoury Seasoning Market |
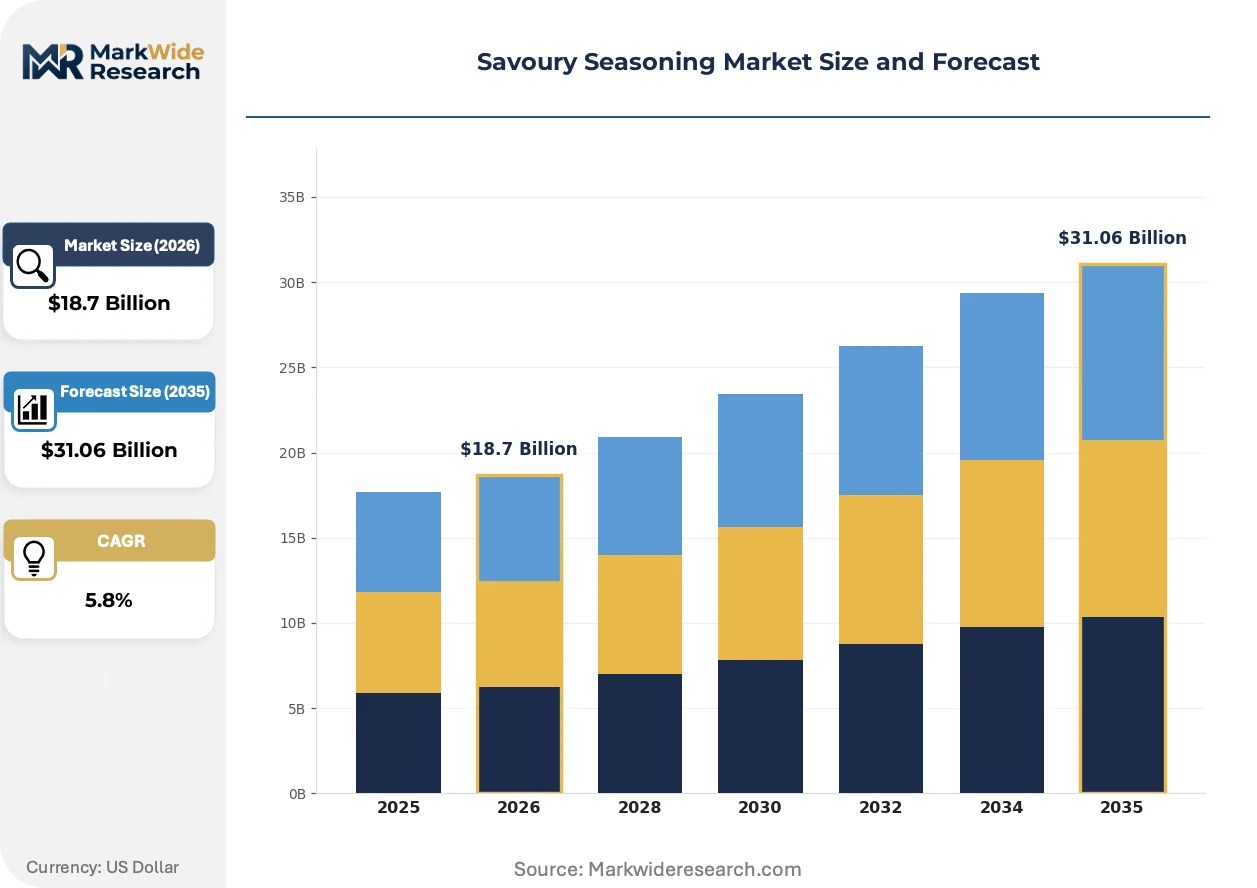
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spices, Herbs, Blends, Sauces Application: Food Service, Retail, Home Cooking, Food Processing End User: Restaurants, Caterers, Food Manufacturers, Households Form: Powder, Whole, Liquid, Granular |
| Companies Covered | Ajinomoto Co., Inc., Kerry Group plc, Givaudan, Symrise AG, ADM (Archer Daniels Midland Company), Koninklijke DSM N.V., Sensient Technologies Corporation, Tate & Lyle PLC, Associated British Foods plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savoury Seasoning Market Evolving Landscape
Active reformulation across sodium reduction, natural extraction, and precision dosing is compressing traditional seasoning architectures. Technology convergence and regulatory tightening are simultaneously enabling and constraining innovation pathways.
Encapsulated flavor delivery systems is overtaking conventional spray-dried powders in thermal-processed applications. Ready-meal manufacturers in Germany and the Netherlands are adopting lipid-based and modified starch matrices to control release during retort processing. This shift is enabling cleaner labels while maintaining aromatic intensity through aggressive heat treatment.
EFSA's systematic re-evaluation of food additives under the 2021-2026 program is forcing reformulation of yeast extracts and hydrolyzed vegetable proteins. Manufacturers are submitting novel safety dossiers for traditionally grandfathered ingredients. The snack seasoning segment is most affected, with producers accelerating natural umami source substitution.
Central kitchen consolidation among European foodservice chains is compressing supplier relationship structures. Procurement teams at institutional operators are consolidating vendor bases toward full-service compound seasoning partners. France and Spain exhibit the fastest transition, with contract manufacturers absorbing blending and logistics functions previously handled in-house.
Savoury Seasoning Market Segmentation
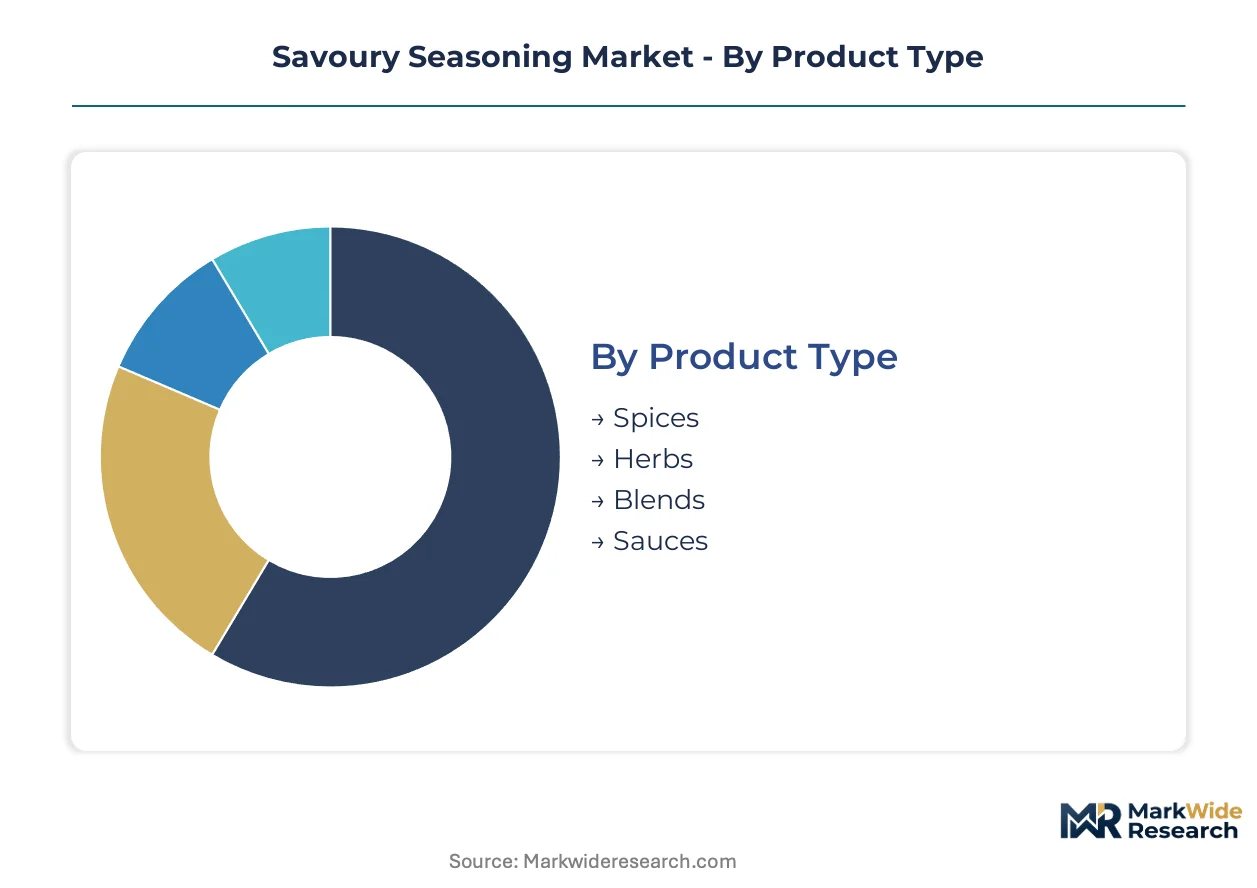
Savoury seasoning procurement patterns diverge sharply across use cases, with industrial buyers prioritizing dosing precision and shelf stability while foodservice operators emphasize flavor intensity and menu flexibility. Segment-specific formulation requirements are reshaping supplier R&D allocation and manufacturing asset deployment across the value chain.
Product Type:
Upgrade cycles in product type selection track regulatory pressure on additive disclosure, with EFSA-driven reformulation accelerating migration from single-ingredient spices toward engineered blends that deliver clean-label performance.
- Spices:Single-origin dried and ground plant materials such as black pepper, paprika, and cardamom deliver concentrated aromatic compounds. Procurement teams in Germany and Spain face climate-driven supply volatility in Indian and Vietnamese origins, compressing margin predictability across harvest cycles.
- Herbs:Leaf-derived materials including oregano, basil, and thyme provide volatile oil-based flavor contribution. Mediterranean processors in Italy and Greece concentrate demand for standardized moisture content and microbial specification, driven by ready-meal manufacturer outsourcing.
- Blends:Proprietary multi-component formulations commanding widest margin pools through customer co-development agreements.
- Sauces:Liquid and semi-liquid concentrated preparations requiring thermal stability and controlled viscosity for industrial dosing systems.
Blends sit at the top of the volume ranking, with sauces climbing the fastest as retort-processed ready-meal manufacturers adopt liquid delivery formats.
Application:
Application segmentation reflects divergent procurement economics, with institutional buyers consolidating toward full-service compound partners while retail channels fragment across premium and private-label tiers.
- Food Service:Central kitchen procurement for restaurant chains and institutional operators demands umami-rich, low-sodium formulations with batch-to-batch consistency. Consolidation among European foodservice chains in France and Spain is compressing supplier relationship structures toward integrated blending and logistics partners.
- Food Processing:Ready-meal and snack manufacturers outsource compound seasoning production to achieve dosing precision and regulatory compliance. Encapsulated flavor delivery systems are displacing conventional spray-dried powders in thermal-processed applications across Germany and the Netherlands.
- Retail:Packaged seasoning for consumer purchase through grocery and specialty channels, stratifying across premium botanical and mass-market tiers.
- Home Cooking:Direct-to-consumer formats emphasizing convenience and recipe-specific positioning.
Food Processing leads volume concentration, with Food Service gaining share fastest through central kitchen vendor consolidation.
End User:
End user segmentation maps directly to specification complexity and contract structure, with food manufacturers driving technical innovation while households prioritize accessibility and brand recognition.
- Food Manufacturers:Industrial processors of ready-meals, snacks, and prepared proteins requiring ISO 22000-certified suppliers with documented allergen control and traceability systems. These buyers command the most intensive co-development relationships and longest contract durations.
- Restaurants:Independent and chain operators with divergent procurement sophistication, from direct spice trading to contracted blend supply.
- Caterers:Institutional and event-focused foodservice operators with high-volume, price-sensitive procurement patterns.
- Households:Individual consumers purchasing through retail channels with minimal technical specification requirements.
Food Manufacturers anchor volume demand, with Restaurants expanding most quickly as chain consolidation accelerates standardized seasoning adoption.
Form:
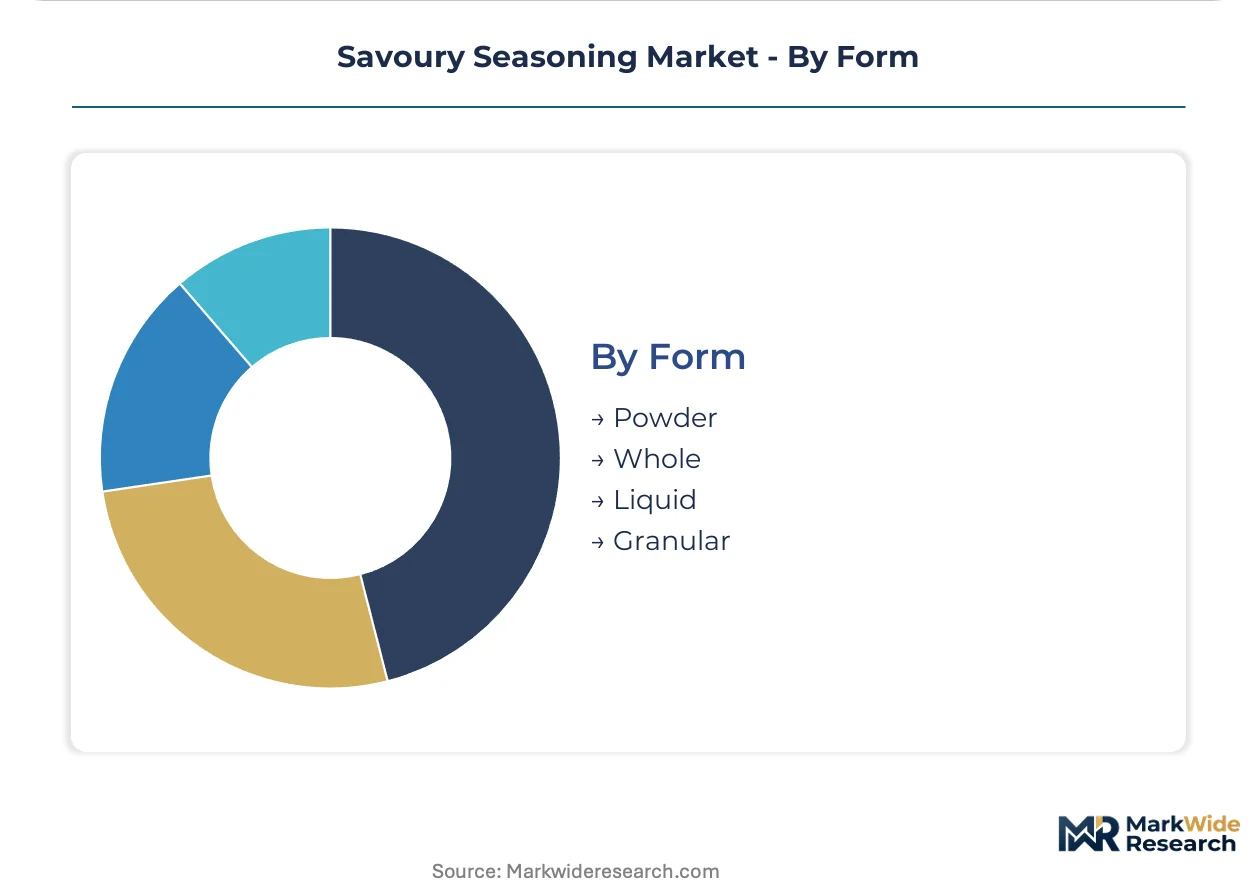
Form selection determines manufacturing asset requirements and supply chain configuration, with powder formats dominating industrial channels and whole forms retaining niche premium positioning.
- Powder:Particle-size-standardized materials between 250 and 850 microns enabling uniform dispersion in dry applications and controlled release in thermal processing. Powder leads industrial channel volume where dosing precision and shelf stability matter for automated manufacturing lines.
- Liquid:Extract-based and emulsion formats enabling rapid dissolution and homogeneous distribution in wet processing environments. Ready-meal manufacturers are adopting lipid-based and modified starch matrices to control release during retort processing.
- Whole:Intact dried spices and herbs for grinding at point of use, retaining volatile oil integrity for premium applications.
- Granular:Agglomerated particles balancing flowability with dissolution performance for specific industrial dosing equipment.
Powder commands the volume base, with liquid formats gaining fastest through encapsulated delivery system adoption in thermal-processed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as EFSA's additive disclosure mandates push reformulation investment toward jurisdictions with clearer compliance pathways and established fermentation infrastructure. Southeast Asian processors capture cost advantages while European suppliers absorb certification overhead.
Indonesia
Industrial food processing expansion in Java and Sumatra is driving compound seasoning demand as traditional spice consumption industrializes. FSSAI-aligned importers are building traceability systems to access Indian institutional kitchen contracts. Surabaya's processing corridor concentrates wet seasoning manufacturing for regional ready-meal export.
Germany
Encapsulated flavor delivery adoption in retort-processed applications is accelerating among ready-meal manufacturers. EFSA's systematic additive re-evaluation is forcing yeast extract reformulation across snack seasoning portfolios. Hamburg and Frankfurt anchor central kitchen procurement consolidation for foodservice chains seeking integrated blending partners.
India
Organized food sector penetration is creating white space for industrial seasoning adoption as QSR chains standardize procurement. FSSAI compliance alignment unlocks institutional supply contracts previously served by informal spice traders. Maharashtra and Gujarat concentrate co-development relationships between compound suppliers and emerging processed food manufacturers.
Netherlands
Thermal-processed application demand is shifting toward lipid-based controlled-release matrices for aromatic intensity retention. REACH compliance shapes natural extractive sourcing for European processors serving clean-label retail channels. The Rotterdam-Antwerp corridor dominates liquid seasoning logistics for industrial dosing system integration.
Vietnam
Export-oriented seafood and instant noodle processing is scaling standardized umami substrate demand. The country's national food safety regulator is tightening additive disclosure alignment with EFSA guidelines for EU market access. Ho Chi Minh City's industrial zones concentrate fermentation-derived nucleotide manufacturing for regional supply.
Savoury Seasoning Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary blend developers commanding margin premiums through co-development agreements while toll processors capture volume in standardized formulations. The vendor base concentrates around three strategic archetypes: integrated flavor houses with fermentation capabilities, regional blend specialists serving foodservice consolidation, and commodity traders pivoting toward compound seasoning. M&A activity targets captive fermentation capacity, while strategic partnerships between biotechnology firms and established houses accelerate novel substrate development.
Within the integrated flavor house tier, Ajinomoto Co., Inc. and Kerry Group plc exemplify divergent approaches to umami technology deployment. Ajinomoto anchors fermented substrate expertise through its nucleotide heritage, while Kerry Group plc occupies a position bridging taste modulation technology with European institutional kitchen consolidation. Givaudan represents the premium culinary innovation archetype, anchoring development capacity across Asian and Latin American innovation centers.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Kerry Group plc |
| Givaudan |
| Symrise AG |
| ADM (Archer Daniels Midland Company) |
| Koninklijke DSM N.V. |
| Sensient Technologies Corporation |
| Tate & Lyle PLC |
| Associated British Foods plc |
| Others |
Value Network & Pricing Analysis
EFSA-driven clean-label reformulation mandates are forcing procurement teams to abandon low-cost synthetic additives and absorb premium natural extract costs, compressing margin pools at the mid-tier while rewarding suppliers with captive fermentation capacity and geographic diversification.
Pricing Analysis
Distributor margins in the seasoning value chain typically capture 15-25 points before compound blenders add formulation premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with ISO 22000-certified suppliers commanding 12-18% premiums over uncertified competitors. Pricing pressure stems from climate-driven raw material volatility in cardamom and black pepper origins, forcing cost pass-through negotiations. Food manufacturers exhibit highest price sensitivity due to volume scale and contract duration, while specialty foodservice operators absorb premiums for proprietary co-developed formulations.
Supply Chain Analysis
India's domestic-content requirements under FSSAI traceability mandates are reshaping sourcing patterns for export-oriented compound suppliers. Geographic supply concentrates in India, Vietnam, and Indonesia for black pepper, paprika, and fermented nucleotide substrates. Raw material dependencies rest on monsoon-sensitive spice harvests, Mediterranean botanical extract availability, and fermentation-derived umami precursors. Single-source vulnerability in specific Indian growing regions for premium cardamom creates procurement risk. Distribution runs through Rotterdam-Antwerp liquid seasoning corridors for European industrial dosing integration, with dry powder flows consolidating through Hamburg and Singapore hub facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in savoury seasoning hinges on fermentation technology scale-down economics enabling premium clean-label positioning at mid-tier price points, while sodium reduction substrates capture regulatory-driven substitution demand.
For Market Incumbents: Deploy captive fermentation capacity expansion to defend against biotechnology-enabled new entrants targeting precision-derived umami molecules. Accelerate ISO 22000 certification coverage across Southeast Asian toll manufacturing partners to preempt export compliance bottlenecks. Consolidate supplier relationships with Indonesian and Vietnamese spice originators through long-term offtake structures that lock in harvest-cycle pricing. For New Entrants and Emerging Players: Begin with India's underpenetrated organized food sector, where FSSAI-aligned compound seasoning adoption lags industrial processing growth by 8-12 percentage points. Target mid-sized ready-meal manufacturers in Maharashtra and Gujarat with direct-to-manufacturer digital procurement platforms that disintermediate traditional spice trading layers. Lead with sodium reduction formulation expertise to capture EFSA-mandated reformulation contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology firms possessing synthetic biology capabilities applicable to precision fermentation of novel savory molecules. Five-to-ten year viability favors targets with dual expertise in natural extract stability and industrial scale-up, given formulation chemist scarcity. Watch for EFSA additive re-evaluation timeline acceleration as inflection signal for clean-label substitution demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables sodium reduction without taste compromise for EFSA-compliant reformulation. |
| Captive Spice Origin Integration | Secures climate-vulnerable cardamom and pepper supply through backward plantation control. |
| Direct-to-Manufacturer Platform Launch | Disintermediates traditional trading layers for mid-sized food processor margin capture. |
| ISO 22000 Certification Acceleration | Unlocks export-oriented supply contracts previously blocked by audit queue backlogs. |
| Culinary Innovation Center Expansion | Anchors co-development relationships with European foodservice chain consolidation. |
Research Methodology
Coverage spans Europe, Southeast Asia, and South Asia, with primary inputs from each region triangulated against secondary validation. Research combined structured interviews with compound seasoning R&D directors, food manufacturer procurement leads, foodservice chain central kitchen operators, and FSSAI compliance consultants. Secondary sources included EFSA additive re-evaluation dossiers, EU customs trade data for spice imports, FSSAI regulatory circulars, and SEC filings from listed flavor houses. Bottom-up volume modeling across product type, application, and form segments was cross-checked against top-down market sizing from industrial processing capacity data.
Granularity-level modeling operated at the country-form-application intersection, with separate forecasts for powder, liquid, and granular delivery formats across food processing, foodservice, retail, and home cooking channels. CAGRs were derived from trend extrapolation of industrial seasoning outsourcing rates, regulatory reformulation timelines, and fermentation technology adoption curves. Industry-specific inputs included EFSA re-evaluation program schedules, Southeast Asian ready-meal production capacity expansion pipelines, and Indian organized food sector penetration trajectories.
Caveats apply where EFSA additive re-evaluation acceleration, monsoon failure patterns in Indian spice origins, or precision fermentation breakthrough economics could materially shift the outlook. Forecasts reflect documented assumptions regarding clean-label substitution elasticity and industrial outsourcing propensity. A small set of named triggers—regulatory timeline compression, climate supply shocks, and biotechnology partnership announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Hot Pot Seasoning Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Spices Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Frankincense Extract Market