
 Chipotle Salt Market | 2026-2036
Chipotle Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Chipotle Salt Market Analytics
Multi-pack bundling of chipotle salt with complementary spice blends is broadening buyer choice across both retail and foodservice channels. Salt Works leverages vertical integration from sea salt harvesting to smoked finishing, sustaining cost discipline through captive supply. The Spice Lab competes through artisan positioning and direct-to-consumer channel control. Jacobsen Salt anchors Pacific Northwest sourcing credibility, differentiating via terroir-specific mineral profiles that command premium placement.
Chipotle salt denotes sea or mined salt infused with smoke-dried jalapeño (Capsicum annuum) particulate, typically achieving Scoville-adjacent heat levels of 2,500–8,000 SHU through controlled pyrolysis of mesquite or hickory wood. The ingredient functions primarily as a finishing and rub seasoning in commercial kitchens and CPG formulations where simultaneous salinity, smoke, and capsicum heat reduce SKU complexity. Smoked chipotle salt occupies the dominant revenue position due to established barbecue and Latin American cuisine associations, while fine-grain product type variants represent the fastest-growing configuration as beverage and sauce manufacturers seek homogeneous dispersion. Specialty stores distribution channel captures disproportionate margin pools through experiential merchandising and educated staff consultation that validates premium pricing.
FDA oversight of spice adulteration under the Food Safety Modernization Act and EFSA maximum residue limits for polycyclic aromatic hydrocarbons in smoked foods directly constrain pyrolysis methods and supplier qualification. USDA organic certification and Non-GMO Project verification function as de facto market access requirements for North American retail placement. Stakeholders must monitor evolving smoke-flavoring regulatory thresholds while calibrating R&D investment between natural wood-smoke processes and liquid smoke alternatives that offer batch consistency with lower PAH exposure risk.
Market Dynamics
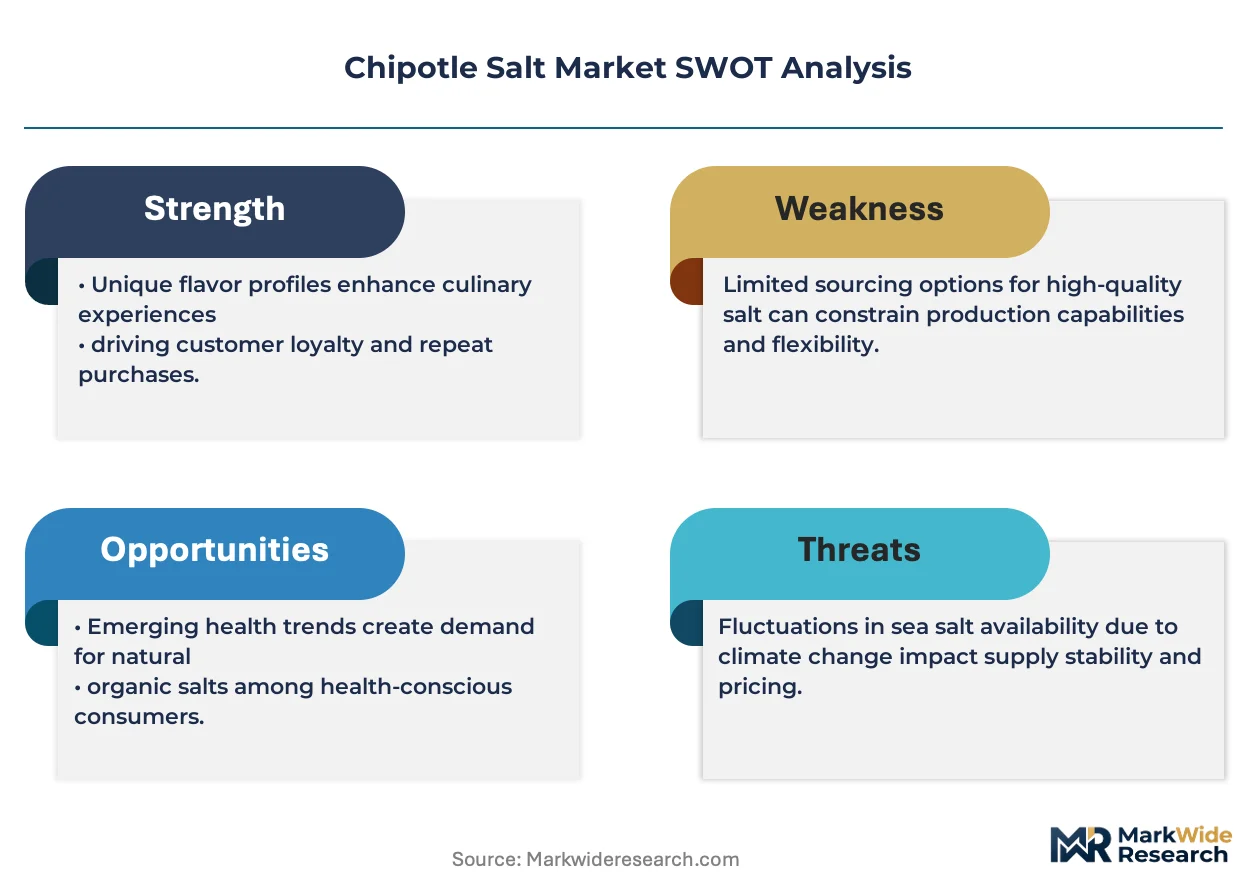
Clean-label mandates under FDA and EFSA frameworks are forcing chipotle salt producers to requalify pyrolysis methods and liquid smoke alternatives, reshaping competitive positioning between natural wood-smoke and controlled thermal processing suppliers.
Growth Catalysts
- USDA Organic Certification:North American retailers now require Non-GMO Project verification as a de facto shelf-access condition, pulling specialty manufacturers toward certified supply chains.
- Premium Snack Seasoning:CPG formulators in the United States are bundling chipotle salt into multi-SKU barbecue rub portfolios to reduce flavor complexity.
- Mexico:Jalapeño cultivation clusters in Chihuahua and Oaxaca provide captive raw material access for smoke-dried Capsicum annuum processors.
Market Restraints
- PAH Residue Limits:EFSA maximum thresholds for polycyclic aromatic hydrocarbons in smoked foods constrain mesquite and hickory pyrolysis temperatures.
- Sea Salt Harvest Volatility:Pacific Northwest tidal flat yields fluctuate with El Niño cycles, compressing margin predictability for artisan producers.
- Liquid Smoke Substitution:Batch-consistent synthetic alternatives threaten natural wood-smoke chipotle salt price premiums in beverage applications.
Strategic Opportunities
- Germany:Underpenetrated foodservice channels in Bavaria and Berlin offer expansion headroom for Latin American cuisine adoption.
- Fine-Grain Configuration:Sauce and beverage manufacturers seek homogeneous dispersion formats currently supplied by limited specialty mills.
- Experiential Retail:Specialty stores with educated staff consultation validate premium pricing through sensory merchandising.
Industry Challenges
- Smoke-Flavoring Regulatory Thresholds:Evolving FDA Food Safety Modernization Act enforcement timelines delay new product launches by 8-14 months.
- Capsaicin Extraction Skill Gap:Controlled pyrolysis operators with Scoville calibration expertise remain concentrated in Mexico and the American Southwest.
- Dual Certification Burden:Simultaneous USDA organic and EFSA compliance requires parallel documentation systems that smaller producers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chipotle Salt Market |
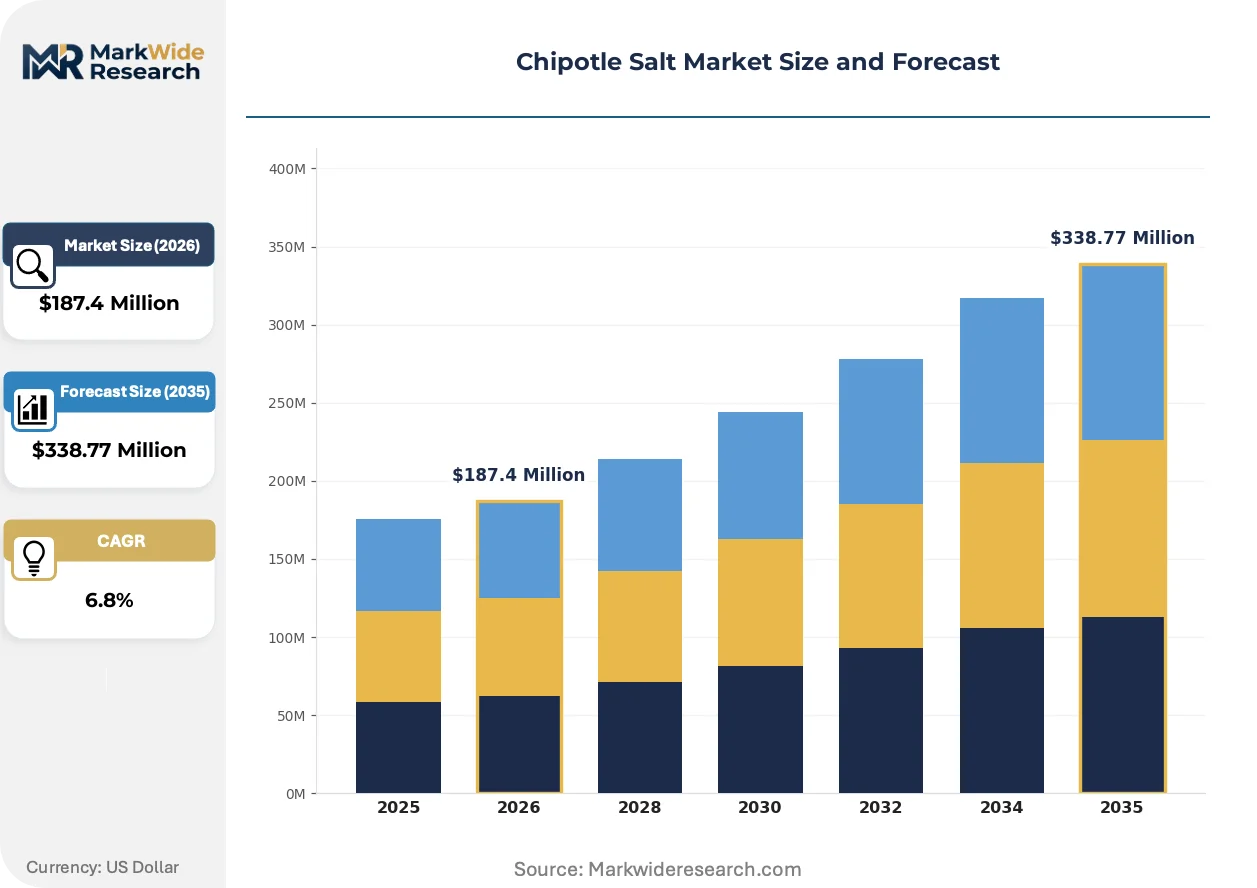
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smoked, Flavored, Coarse, Fine End User: Restaurants, Food Manufacturers, Retailers, Home Chefs Distribution Channel: Online, Wholesale, Supermarkets, Specialty Stores Packaging Type: Bulk, Jars, Sachets, Pouches |
| Companies Covered | Salt Works, The Spice Lab, Intergrow Brands, Frontier Co-op, Jacobsen Salt, Nassau Candy, Gustus Vitae, My Spice Sage, Spice Mountain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chipotle Salt Market Evolving Landscape
Technology convergence between precision thermal processing and analytical chemistry is compressing the gap between artisan smoke profiles and industrial consistency, while regulatory pressure on polycyclic aromatic hydrocarbons accelerates method substitution.
Controlled atmosphere pyrolysis with real-time particulate monitoring is decentralizing chipotle salt production away from coastal smokehouse concentrations. Mid-size spice processors in Texas and New Mexico are adopting these systems to capture margin pools previously held by vertically integrated sea salt harvesters. The technology enables inland production nodes with reduced logistics exposure to Pacific tidal harvest volatility.
EFSA's 2023 tightening of benzo[a]pyrene limits in smoked flavorings is forcing European importers to requalify Mexican suppliers. German and Dutch distributors now require third-party PAH testing certificates as standard purchase order conditions. This regulatory friction favors liquid smoke alternatives in sauce manufacturing while preserving natural wood-smoke positioning for premium finishing salt tiers.
Direct-to-consumer subscription models are displacing traditional spice aisle distribution for artisan chipotle salt brands. Specialty food enthusiasts in the United States and Germany purchase curated quarterly shipments with provenance documentation and recipe pairings. This channel shift concentrates customer lifetime value data with producers while eroding broker margins in conventional grocery wholesale.
Chipotle Salt Market Segmentation
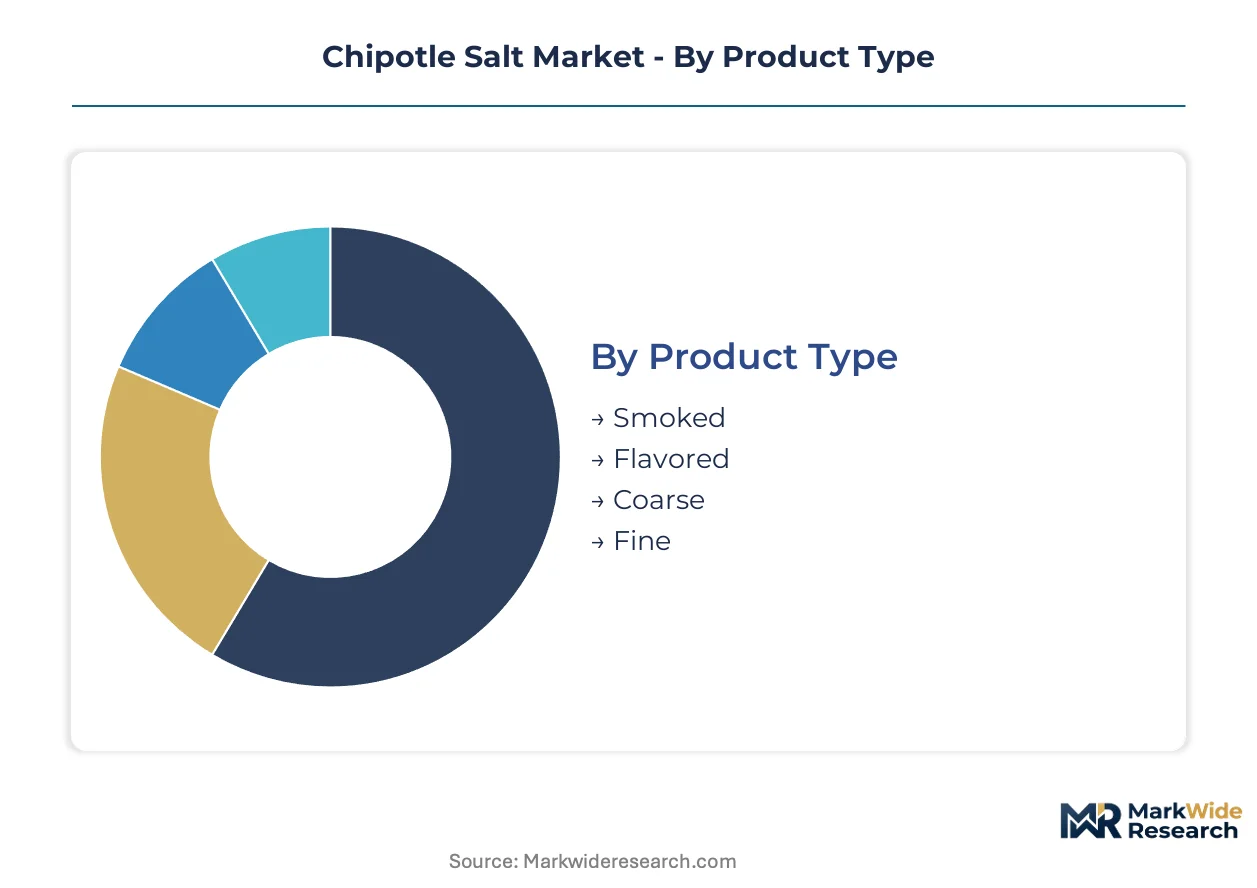
Chipotle salt segmentation reflects divergent integration depths across standalone finishing applications versus embedded CPG formulations. Product configuration and distribution channel choices directly determine whether producers capture premium pricing in artisan retail or volume efficiencies in industrial supply.
Product Type:
Integration depth separates standalone smoke-dried formats from compound flavor systems that embed chipotle salt within broader seasoning matrices.
- Smoked:Mesquite or hickory pyrolysis infuses sea salt with smoke-dried jalapeño particulate, achieving 2,500–8,000 SHU heat levels. Demand concentrates in United States barbecue rub portfolios and German foodservice channels where simultaneous smoke-salt-heat functionality reduces ingredient complexity. EFSA benzo[a]pyrene limits constrain European sourcing qualifications.
- Fine:Homogeneous particle distribution enables seamless dispersion in beverage formulations and emulsified sauces. Beverage manufacturers in Germany and sauce processors in Mexico seek this configuration for batch consistency, though liquid smoke alternatives threaten price premiums.
- Coarse:Crystalline structure suited for finishing applications where texture and visual appeal command premium placement in specialty retail.
- Flavored:Compound systems blending chipotle salt with complementary spices for single-SKU convenience in home cooking segments.
Smoked leads volumes today; fine is gaining share fastest.
End User:
Cost tier stratification separates premium artisan positioning from commodity industrial supply based on certification requirements and batch scale.
- Food Manufacturers:CPG formulators bundle chipotle salt into multi-SKU seasoning lines to compress flavor complexity and reduce supplier count. United States snack seasoning operations drive volume procurement with USDA organic certification as de facto shelf-access condition.
- Restaurants:Commercial kitchens employ chipotle salt as finishing and rub seasoning where simultaneous salinity, smoke, and capsicum heat streamline mise en place. Bavaria and Berlin foodservice channels show underpenetrated expansion headroom for Latin American cuisine adoption.
- Retailers:Specialty stores with educated staff consultation validate premium pricing through sensory merchandising and provenance documentation.
- Home Chefs:Direct-to-consumer subscription models concentrate customer lifetime value with curated quarterly shipments and recipe pairings.
Food manufacturers dominate procurement volumes; restaurants show steepest expansion trajectory.
Distribution Channel:
Customer type determines margin capture, with experiential retail commanding premium pricing against transactional wholesale efficiency.
- Specialty Stores:Experiential merchandising with educated staff consultation validates premium placement and provenance storytelling. Disproportionate margin pools accrue to retailers investing in sensory engagement infrastructure.
- Online:Direct-to-consumer subscription models displace traditional spice aisle distribution, concentrating customer data with producers and eroding broker margins in conventional grocery wholesale.
- Wholesale:Volume efficiency for food manufacturers and restaurant chains with standardized specifications and consolidated procurement.
- Supermarkets:Mass-market placement requiring Non-GMO Project verification and competitive pricing against private label alternatives.
Specialty stores anchor premium tier margins; online channels climb the fastest.
Packaging Type:
Volume scale and application context separate industrial bulk from consumer-facing formats with brand differentiation potential.
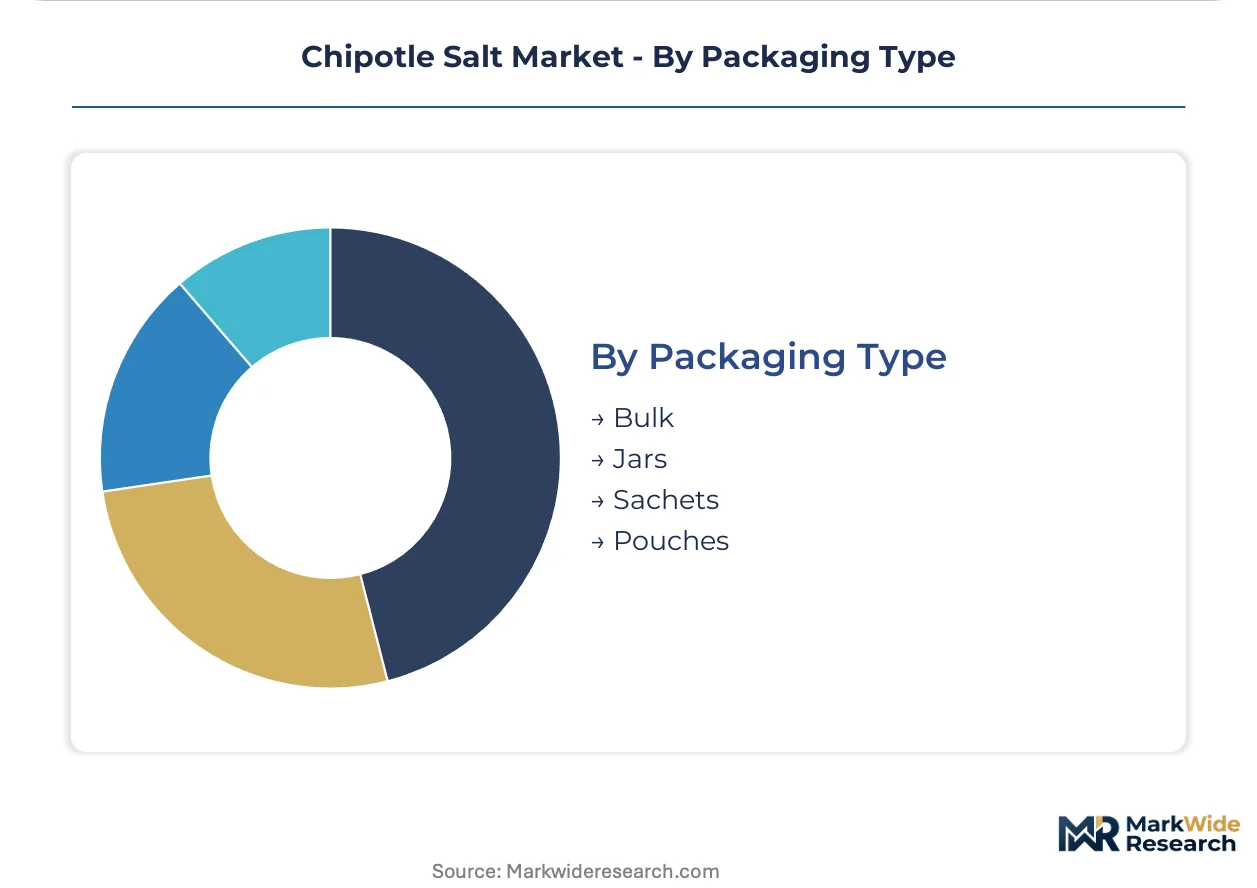
- Bulk:Industrial-scale supply for CPG formulators and restaurant chains with captive grinding or blending operations. Procurement emphasizes batch consistency and certification documentation over packaging aesthetics.
- Jars:Premium retail positioning with resealable convenience for home chefs seeking pantry visibility and measured dispensing control.
- Sachets:Single-serve portions for foodservice condiment programs and travel retail, balancing portion control with brand exposure.
- Pouches:Flexible format for refill programs and subscription shipments, reducing shipping weight against glass alternatives.
Bulk commands industrial procurement volumes; jars sustain premium retail pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chipotle salt production traces its commercial origins to Mexico's traditional smoke-drying practices in Chihuahua and Oaxaca, where jalapeño cultivation and mesquite pyrolysis first merged with sea salt finishing. This heritage foundation now supports specialized manufacturing clusters across three continents.
United States
Barbecue rub portfolios and premium snack seasoning lines drive procurement volumes from Texas to California. FDA Food Safety Modernization Act enforcement shapes supplier qualification timelines, particularly for polycyclic aromatic hydrocarbon documentation. Pacific Northwest tidal flat operations in Oregon face El Niño-driven harvest volatility that compresses margin predictability for artisan producers.
Mexico
Jalapeño cultivation clusters in Chihuahua and Oaxaca provide captive raw material access for smoke-dried Capsicum annuum processors serving export markets. Domestic regulators enforce maximum residue limits that align with EFSA import requirements. Guadalajara-area processors are expanding controlled atmosphere pyrolysis capacity to reduce coastal logistics dependence.
Germany
Bavaria and Berlin foodservice channels show underpenetrated expansion headroom for Latin American cuisine adoption. EFSA benzo[a]pyrene limits in smoked flavorings constrain sourcing from traditional Mexican suppliers. Hamburg distributors now require third-party PAH testing certificates as standard purchase order conditions, favoring liquid smoke alternatives in industrial sauce manufacturing.
Canada
Specialty retail demand concentrates in Toronto and Vancouver metropolitan markets where direct-to-consumer subscription models gain traction. Health Canada oversight of spice adulteration parallels FDA frameworks, creating aligned certification requirements for cross-border suppliers. British Columbia's coastal salt harvesters are exploring smoke-dried jalapeño partnerships to differentiate Pacific mineral profiles.
United Kingdom
London specialty food retailers and Manchester-area CPG formulators represent the primary demand nodes for premium finishing salts. Trading standards enforcement around smoke-flavoring labeling creates compliance friction for imported chipotle salt variants. Edinburgh-based spice distributors are building direct sourcing relationships with Mexican smokehouse operators to bypass continental European re-export markups.
Chipotle Salt Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and channel control dimensions. The vendor base stratifies between vertically integrated sea salt harvesters, artisan smokehouse specialists, and direct-to-consumer subscription operators. Three archetypes dominate: coastal smokehouse integrators controlling tidal flat-to-finishing workflows; inland pyrolysis adopters leveraging precision thermal processing; and digitally native brands bypassing wholesale brokerage. Consolidation pressure concentrates among mid-size spice processors seeking captive supply security, while geographic expansion and portfolio diversification represent the dominant competitive vectors.
Within the coastal integration tier, Salt Works and Jacobsen Salt occupy positions defined by Pacific Northwest sourcing credibility and terroir-specific mineral differentiation. The Spice Lab exemplifies the direct-to-consumer archetype through subscription channel control and artisan positioning. Frontier Co-op represents cooperative-structured procurement models that aggregate smaller smokehouse operators under unified certification and distribution umbrellas. These three company structures illustrate how scale, geography, and ownership model combine to determine margin capture in pyrolysis-based seasoning markets.
| Leading Market Players |
|---|
| Salt Works |
| The Spice Lab |
| Intergrow Brands |
| Frontier Co-op |
| Jacobsen Salt |
| Nassau Candy |
| Gustus Vitae |
| My Spice Sage |
| Spice Mountain |
| Others |
Value Network & Pricing Analysis
USDA organic certification mandates from North American retailers are compressing supplier qualification timelines and forcing pyrolysis operators to absorb dual-documentation costs, which pricing power must recover through premium tier positioning or volume efficiency gains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates artisan smokehouse brands with terroir documentation from mid-tier certified suppliers and commodity liquid-smoke alternatives. Price differentiation hinges on USDA organic verification and EFSA PAH compliance documentation, with the latter commanding 15-40% premiums in German foodservice channels. Cost compression in the economy tier is intensifying because beverage manufacturers are substituting liquid smoke for natural pyrolysis. Food manufacturers show highest price sensitivity due to consolidated procurement and SKU rationalization pressures, while specialty retailers absorb premiums through experiential merchandising.
Supply Chain Analysis
Mexican domestic-content advantages in Chihuahua and Oaxaca jalapeño cultivation clusters are reshaping sourcing patterns as EFSA importers seek captive raw material access to bypass third-party PAH testing bottlenecks. Supply concentrates in Mexico, the United States, and Germany, with the latter serving as a re-export hub constrained by Hamburg distributor certification requirements. Raw material dependencies include mesquite and hickory wood for pyrolysis, Pacific Northwest tidal flat sea salt, and smoke-dried Capsicum annuum with calibrated Scoville profiles. Single-source vulnerability runs through El Niño-driven Pacific Northwest harvest volatility. Distribution runs through specialty retail experiential channels, direct-to-consumer subscription platforms, and consolidated food manufacturer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chipotle salt market compounds steadily through clean-label regulatory ratcheting that permanently expands certified supply chain premiums and locks in artisan positioning advantages.
For Market Incumbents: Anticipate liquid smoke substitution threats in beverage applications by deepening controlled atmosphere pyrolysis R&D investments and securing dual USDA-EFSA certification moats. Defensive consolidation moves should target mid-size smokehouse operators in Texas and New Mexico to capture inland production nodes and reduce Pacific tidal flat exposure. Priority levers include vertical integration into jalapeño cultivation clusters and direct-to-consumer channel control through subscription infrastructure. For New Entrants and Emerging Players: EFSA's 2023 benzo[a]pyrene tightening opens a window for PAH-compliant pyrolysis specialists to capture German foodservice share from incumbent Mexican suppliers struggling with requalification timelines. White-space targets include fine-grain configuration supply for sauce manufacturers in Bavaria and Berlin, plus experiential retail partnerships in Canadian metropolitan markets. Go-to-market positioning should anchor on third-party testing documentation and provenance storytelling rather than price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with digitally native brands controlling subscription customer data and mid-size pyrolysis operators with EFSA-ready certification infrastructure. Long-term viability frames around 5-10 year regulatory compliance deepening rather than commodity cyclicality. Acquisition target archetype: inland controlled atmosphere pyrolysis adopters with dual certification progress and direct channel assets. Watch for inflection when Hamburg distributors shift from certificate requirements to preferred supplier list exclusivity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Jalapeño Cultivation | Captive supply from Chihuahua and Oaxaca clusters reduces raw material cost volatility and EFSA requalification friction. |
| Controlled Atmosphere Pyrolysis Capacity Buildout | Inland Texas and New Mexico nodes bypass Pacific Northwest El Niño exposure and compress logistics costs. |
| Dual Certification Program | Parallel USDA organic and EFSA compliance documentation unlocks North American retail and German foodservice placement simultaneously. |
| Direct-to-Consumer Subscription Launch | Curated quarterly shipments with recipe pairings concentrate customer lifetime value data and erode wholesale broker margins. |
| Fine-Grain Configuration Expansion | Homogeneous particle distribution capabilities capture sauce and beverage manufacturer procurement shifting from coarse finishing formats. |
Research Methodology
Multiple input streams — structured interviews with smokehouse operators and spice procurement directors, regulatory filing analysis from FDA and EFSA, and trade flow data from customs authorities — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged pyrolysis equipment manufacturers, specialty retail category managers, and CPG formulators in the United States, Mexico, and Germany. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EFSA scientific opinions on PAH limits, USDA organic certification databases, and Pacific Northwest tidal harvest yield records.
Data-stream reconciliation anchored volume and value outputs to modeled segmentation across product configuration, end-user cost tier, and distribution channel control dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints. Industry-specific forecast inputs included EFSA regulatory enforcement timelines, El Niño cycle projections affecting Pacific sea salt yields, and subscription channel adoption rates in German and Canadian metropolitan markets.
Revisions become necessary when EFSA tightens benzo[a]pyrene thresholds beyond current third-party testing capabilities, when FDA accelerates FSMA enforcement timelines, or when liquid smoke substitution crosses critical penetration thresholds in beverage manufacturing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market