
 Global Dehydrated Onion Market | 2026-2036
Global Dehydrated Onion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dehydrated Onion Market Foresight
Foodservice demand is rebalancing toward industrial-scale seasoning and ready-meal manufacturing, pulling volume away from traditional retail spice channels. Olam Food Ingredients leverages backward integration into Indian onion sourcing to sustain cost-advantaged supply. Sensient Technologies Corporation specializes in color-stable dehydrated onion extracts for premium sauce applications. Jain Farm Fresh Foods Limited anchors domestic Indian supply while extending export reach into European food manufacturers.
Dehydrated onion comprises fresh Allium cepa subjected to controlled thermal reduction, typically achieving moisture content below six percent to inhibit microbial activity and extend shelf stability. The process preserves volatile sulfur compounds responsible for characteristic flavor, rendering the material suitable for dry soup bases, seasoning matrices, and reconstituted food systems. Powder form dominates volume throughput due to blending compatibility across food processing lines, though flake and granule categories capture higher per-unit margins in foodservice and retail seasoning. Application concentration in ready-to-eat meals and sauce manufacturing reflects processor demand for consistent flavor dosing without fresh bulb variability. End-user segmentation shows food manufacturers controlling procurement scale, while spice companies compete on custom granulation and certification tiers.
FDA oversight of imported dehydrated vegetables through the Food Safety Modernization Act shapes traceability requirements for US-bound shipments. EU REACH and EFSA mycotoxin thresholds filter market access for non-European suppliers, with ECHA classification of processing aids affecting solvent-based extraction methods. India's FSSAI and DGFT export certification frameworks govern domestic processor compliance. Stakeholders must monitor evolving pesticide maximum residue limits across destination markets and calibrate sourcing regions accordingly.
Market Dynamics
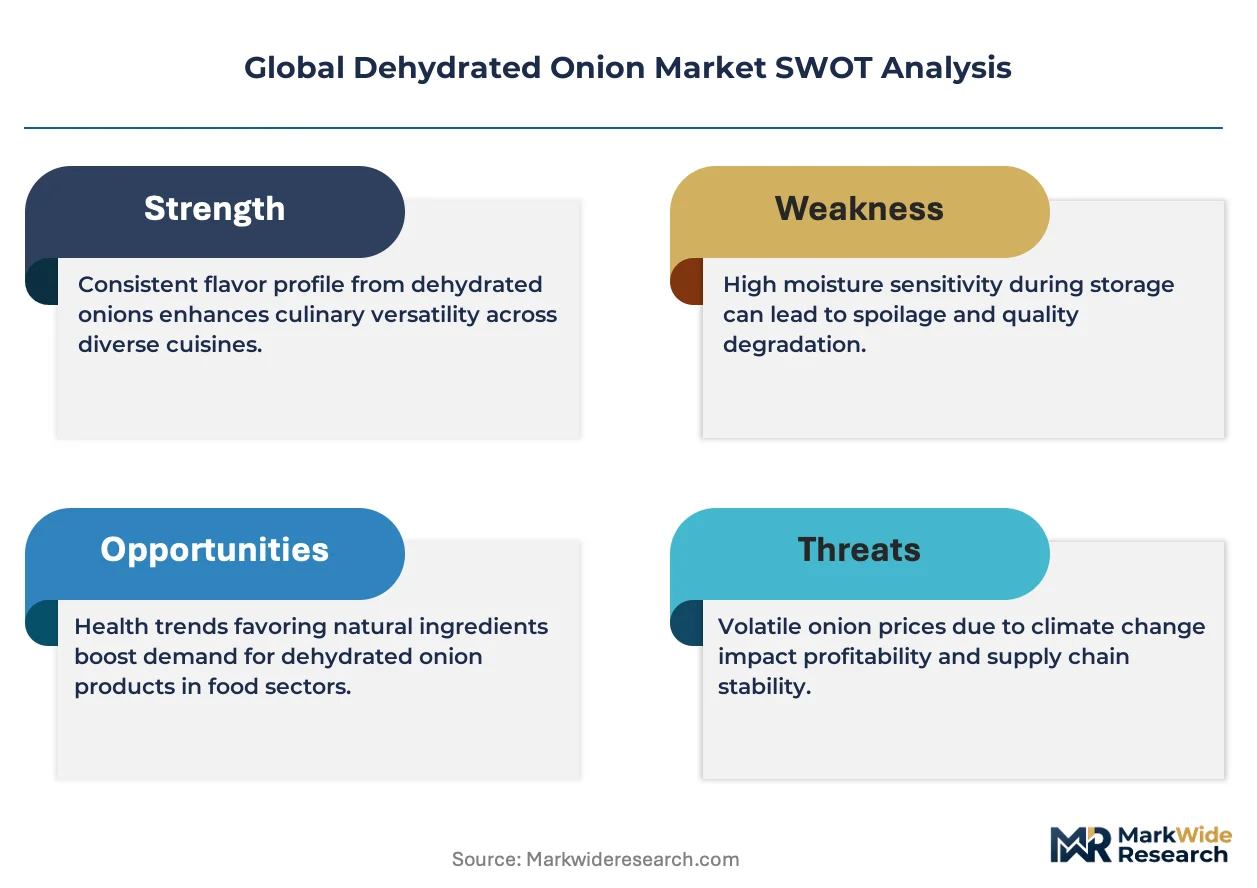
EU REACH compliance on pesticide residues and mycotoxin thresholds is compressing export-grade production standards, forcing processors to recalibrate sourcing regions and invest in traceability infrastructure to maintain market access.
Growth Catalysts
- Clean-label seasoning demand:Food manufacturers are reformulating dry soup bases and sauce matrices to eliminate synthetic additives, pulling volume toward certified organic dehydrated onion grades.
- India's PLI scheme:The Production Linked Incentive scheme for food processing infrastructure is expanding dehydration capacity in Gujarat and Maharashtra onion belts.
- Controlled atmosphere storage:Post-harvest bulb preservation technology is extending raw material availability windows, smoothing seasonal supply volatility for processors.
Market Restraints
- Fresh bulb price volatility:Input cost swings in Indian onion markets transmit directly to dehydration unit economics, compressing margin stability.
- EU EFSA mycotoxin thresholds:Strict aflatoxin and ochratoxin limits for imported dehydrated vegetables create non-tariff barriers for non-European suppliers.
- Freeze-dried substitutes:Premium ready-meal manufacturers are piloting freeze-dried Allium alternatives for superior flavor retention in reconstituted systems.
Strategic Opportunities
- US clean-label sauce manufacturing:FDA Food Safety Modernization Act traceability requirements favor suppliers with documented pesticide-free sourcing, creating entry points for certified Indian processors.
- Low-moisture ready-to-eat meals:Military and expedition food systems are specifying sub-five-percent moisture onion powders for extended shelf-life applications.
- EU Green Deal sustainable sourcing:Carbon footprint disclosure mandates for imported food ingredients reward processors with renewable energy-powered dehydration facilities.
Industry Challenges
- Certification timeline compression:Simultaneous FSSAI, DGFT export, and EU organic audits require dedicated compliance personnel and extended validation cycles.
- Volatile sulfur compound retention:Thermal processing optimization demands R&D investment to prevent flavor degradation during moisture reduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dehydrated Onion Market |
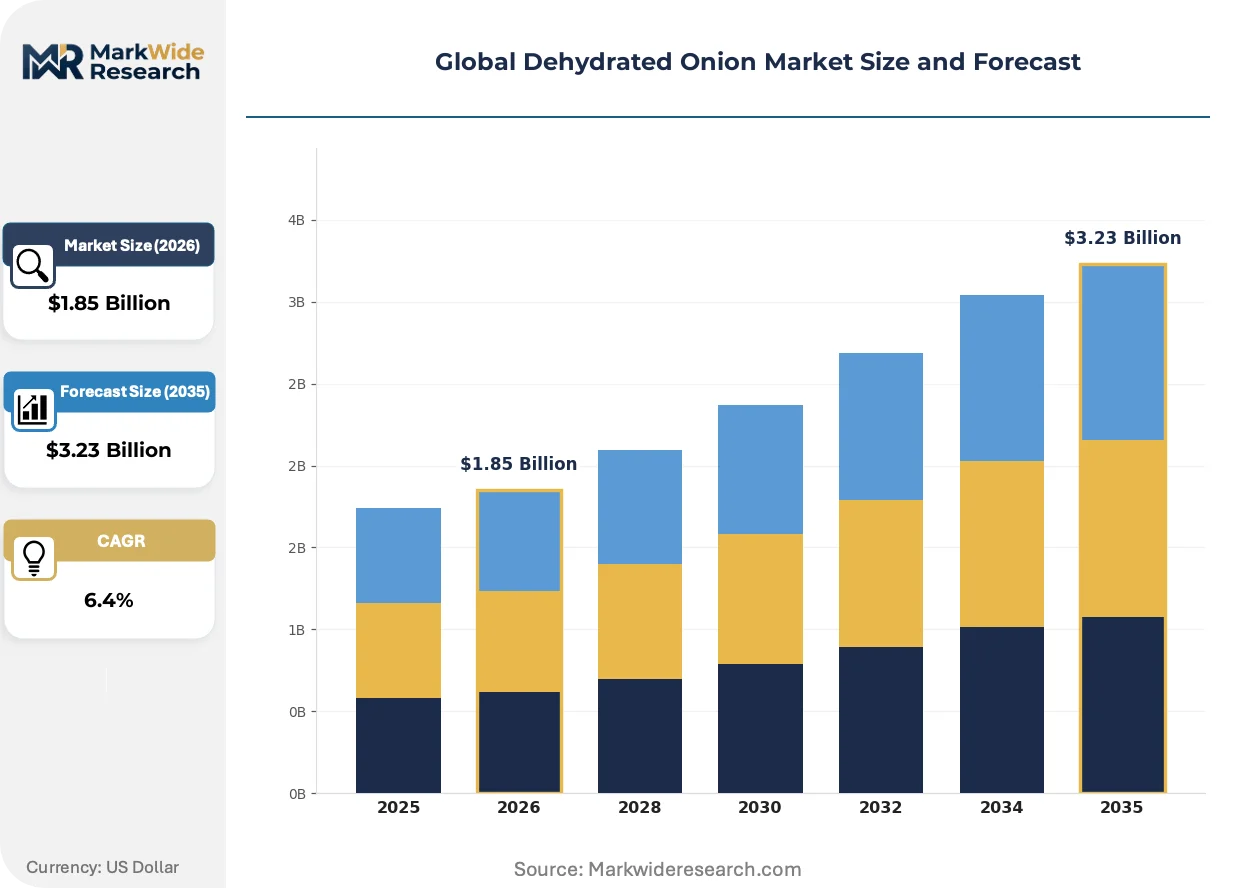
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Flakes, Granules, Minced, Sliced Application: Food Processing, Seasoning Mixes, Ready-to-Eat Meals, Snacks, Sauces End User: Food Manufacturers, Foodservice Providers, Retail Chains, Spice Companies Packaging Type: Vacuum Packs, Flexible Pouches, Jars, Bulk Bags, Canisters |
| Companies Covered | Olam Food Ingredients (Olam Group), Sensient Technologies Corporation, Jain Farm Fresh Foods Limited, Daksh Foods Pvt. Ltd., Van Drunen Farms, Earth Expo Company, BC Foods Inc., Silva International, Inc., AGRIN EXPORT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dehydrated Onion Market Shifts & Advancements
Dehydration technology is converging with precision agriculture and blockchain traceability, reshaping how processors validate origin claims and optimize thermal efficiency. These shifts are redrawing competitive boundaries between commodity suppliers and certified-grade specialists.
Infrared-assisted drying systems are absorbing energy costs from conventional hot-air dehydration while preserving heat-sensitive volatile sulfur compounds. Mid-scale processors in Maharashtra are retrofitting hybrid units to qualify for EU export certification. The technology is absorbing market share from legacy convective systems by delivering measurable pesticide residue reduction alongside moisture precision.
EU REACH Annex XVII restrictions on processing aids are forcing solvent-based extraction methods out of premium extract production. ECHA classification of residual solvents now triggers additional safety data requirements for color-stable onion extracts. European sauce manufacturers are responding by qualifying Indian suppliers with supercritical CO2 extraction capabilities.
Direct-procurement contracts between food manufacturers and dehydration units are displacing traditional spice trader intermediaries. Large ready-meal producers in Germany and the Netherlands are establishing annual volume commitments with Gujarat-based processors. India is the geography where this channel compression is most advanced, with contract farming arrangements now covering significant raw material throughput.
Global Dehydrated Onion Market Segmentation
Dehydrated onion segmentation reflects divergent buyer priorities across industrial procurement and consumer-facing channels. Product form dictates processing compatibility, while packaging and end-user categories separate volume-scale contracts from premium retail positioning.
Product Form:
Buyers differentiate primarily by blending requirements and reconstitution behavior in target food systems.
- Powder:Fine particle size below 80 mesh enables homogeneous dispersion in dry soup bases and seasoning matrices. Food manufacturers in Germany and the Netherlands specify powder for automated dosing lines, though per-unit margins remain compressed by commodity competition.
- Flakes:Larger cut dimensions preserve visual identity in finished products. Premium sauce manufacturers in France favor flakes for texture contrast, paying margin premiums over powder grades despite lower volume throughput.
- Granules:Intermediate sizing suits tabletop seasoning and retail spice applications where flowability matters.
- Minced:Coarse cut for reconstituted systems requiring bite integrity.
- Sliced:Ring-shaped cuts target garnish and salad topping applications with aesthetic requirements.
Powder leads volumes today; flakes are gaining share fastest in European premium channels.
Application:
End-use concentration separates industrial-scale procurement from fragmented specialty demand.
- Food Processing:Dry soup and broth manufacturers constitute the largest single demand pool, specifying sub-six-percent moisture with documented pesticide residue compliance. US-bound shipments face FDA Food Safety Modernization Act traceability mandates that favor established Indian exporters with blockchain-enabled lot tracking.
- Seasoning Mixes:Spice companies compete on custom granulation and volatile sulfur compound retention, sourcing distinct powder grades for regional flavor profiles. EU REACH compliance on mycotoxin thresholds filters supplier qualification, compressing viable vendor pools.
- Ready-to-Eat Meals:Military and expedition food systems drive sub-five-percent moisture specifications for extended shelf stability.
- Snacks:Flavored chip and cracker applications favor flakes for topical adhesion.
- Sauces:Wet-system reconstitution demands color-stable extracts with controlled enzymatic browning.
Food processing dominates procurement scale; ready-to-eat meals are climbing the fastest on defense and emergency preparedness contracts.
End User:
Procurement sophistication and certification requirements segment buyers into distinct supplier relationship models.
- Food Manufacturers:Direct-contracting ready-meal producers in Germany bypass traditional spice traders, establishing annual volume commitments with Gujarat-based dehydration units. FSSAI and DGFT export certification from Indian suppliers satisfies their documentation requirements.
- Foodservice Providers:Institutional kitchens and chain restaurants prioritize cost-stable supply over premium grades, accepting standard powder with flexible delivery scheduling.
- Retail Chains:Private-label seasoning programs demand organic certification tiers and consumer-facing packaging compliance.
- Spice Companies:Custom granulation and regional flavor profiling sustain margin differentiation against commodity suppliers.
Food manufacturers control the largest contract values; retail chains are expanding fastest on clean-label reformulation trends.
Packaging Type:
Shelf-life requirements and handling economics separate industrial bulk from consumer convenience formats.
- Vacuum Packs:Oxygen exclusion extends volatile sulfur compound retention for premium sauce extract applications. European manufacturers specify vacuum packaging to satisfy EFSA mycotoxin prevention protocols during extended storage.
- Flexible Pouches:Cost-efficient barrier films suit foodservice redistribution with moderate shelf-life demands.
- Jars:Glass containment targets retail spice aisles with moisture visibility and resealability.
- Bulk Bags:One-tonne flexible intermediate bulk containers minimize per-kilogram handling costs for food processing lines.
- Canisters:Rigid packaging for tabletop seasoning with dispensing convenience.
Bulk bags lead industrial volumes; vacuum packs are expanding most quickly in EU premium extract supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dehydration capacity toward jurisdictions with lower compliance costs, while EU-bound exporters absorb certification premiums to retain premium market access.
India
Food processing demand from European sauce manufacturers and US soup base producers anchors export volume. FSSAI and DGFT certification frameworks govern processor compliance for outbound shipments. Gujarat and Maharashtra onion belts supply raw material to dehydration clusters in Rajkot, Nashik, and Pune, where contract farming arrangements now cover significant throughput.
Germany
Ready-meal manufacturers and industrial seasoning blenders constitute the largest procurement pool within Europe. REACH Annex XVII restrictions on processing aids and EFSA mycotoxin thresholds filter supplier qualification. Hamburg and Frankfurt logistics corridors handle redistribution of Indian-origin material to Central European food processing lines.
United States
FDA Food Safety Modernization Act traceability mandates favor established exporters with documented pesticide-free sourcing. Clean-label sauce reformulation is pulling volume toward certified organic grades. Chicago and New Jersey distribution hubs consolidate imports for redistribution to Midwestern soup and broth manufacturers.
Netherlands
Rotterdam's port infrastructure serves as the primary European entry point for Indian dehydrated onion shipments. EU Green Deal carbon footprint disclosure mandates reward processors with renewable energy credentials. Food manufacturers in the Randstad region are establishing direct-procurement contracts with Gujarat-based dehydration units.
France
Premium sauce producers favor flake grades for texture contrast in finished products. ECHA classification of residual solvents affects qualification of color-stable extract suppliers. Lyon and Paris food processing clusters are qualifying Indian suppliers with supercritical CO2 extraction capabilities.
Global Dehydrated Onion Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-procurement relationships displacing traditional spice trader intermediaries in industrial channels. The vendor base organizes into three tiers: multinational ingredient suppliers with backward integration into sourcing, mid-scale regional processors with export certification, and commodity traders serving foodservice redistribution. Consolidation pressure concentrates among mid-scale processors seeking FSSAI-DGFT-EU organic audit alignment. Capacity expansion in Gujarat and Maharashtra and technology licensing for infrared-assisted drying systems represent the dominant competitive moves.
Within the multinational ingredient tier, Olam Food Ingredients and Sensient Technologies Corporation exemplify divergent strategic positioning. Olam leverages its Singapore-based structure and Indian sourcing footprint to anchor cost-advantaged supply to European and North American food manufacturers. Sensient occupies a position as a US-based specialty extracts supplier, with its corporate form suggesting emphasis on color-stable formulations for premium sauce applications. Jain Farm Fresh Foods Limited represents the India-based domestic anchor extending export reach, its limited company structure indicating family-owned or closely held ownership typical of Gujarat food processing enterprises.
| Leading Market Players |
|---|
| Olam Food Ingredients (Olam Group) |
| Sensient Technologies Corporation |
| Jain Farm Fresh Foods Limited |
| Daksh Foods Pvt. Ltd. |
| Van Drunen Farms |
| Earth Expo Company |
| BC Foods Inc. |
| Silva International, Inc. |
| AGRIN EXPORT |
| Others |
Supply & Pricing Matrix
Dehydration-technician labor pools concentrated in Gujarat and Maharashtra onion belts compress wage differentials between commodity-grade and EU-export-certified production tiers, widening the spread between standard powder pricing and vacuum-packed premium flake margins. This workforce geography binds pricing power to seasonal harvest availability and certification-capable facility throughput.
Pricing Analysis
Distributor margin layers in European seasoning channels absorb 15-25 point markups over ex-factory Indian prices, while direct-procurement contracts between German ready-meal manufacturers and Rajkot dehydration units eliminate intermediary costs. Three-tier pricing structure across premium, standard, and economy levels separates EU organic-certified flakes from FSSAI-grade powder and unbranded bulk supply. Pricing pressure stems from fresh bulb cost volatility in Nashik wholesale markets transmitting directly to dehydration unit economics. Foodservice redistribution buyers exhibit highest price sensitivity, whereas French premium sauce manufacturers accept sustained premiums for color-stable granules with documented REACH compliance.
Supply Chain Analysis
Workforce availability in Maharashtra and Gujarat dehydration clusters fluctuates with agricultural harvest cycles, constraining capacity utilization during peak onion processing windows. Manufacturing concentrates in India, with secondary processing nodes in Germany and the Netherlands for EU redistribution. Raw material supply draws from Gujarat and Maharashtra onion belts, packaging films from domestic Indian converters, and supercritical CO2 extraction equipment from European suppliers. Single-source vulnerability manifests in monsoon-dependent harvest volumes that dictate annual dehydration campaign timing. Distribution runs through Rotterdam port infrastructure for European-bound shipments and Chicago-New Jersey corridors for US delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dehydrated Onion Market functions as a stable compounder anchored by irreversible food-manufacturer demand for consistent flavor dosing without fresh bulb variability.
For Market Incumbents: Anchor procurement scale through multi-year direct contracts with Maharashtra contract farming cooperatives, securing raw material priority ahead of seasonal price spikes. Invest in infrared-assisted drying retrofits to capture EU Green Deal carbon disclosure premiums and defend margin position against freeze-dried substitute pilots in premium ready-meal channels. For New Entrants and Emerging Players: Enter via supercritical CO2 extraction capability gaps among mid-scale Gujarat processors, targeting French sauce manufacturers disqualified from solvent-based extract suppliers under REACH Annex XVII. Qualify for FSSAI-DGFT-EU organic tri-certification to access German food manufacturer direct-procurement channels bypassing traditional spice traders. For Investors and Strategic Acquirers: Food ingredient multinationals with backward integration capabilities represent the most active acquirer in this space, seeking certified dehydration capacity to secure clean-label supply chains. Mid-scale Indian processors with aligned FSSAI-DGFT-EU organic audit timelines present prime acquisition targets. Monitor EU EFSA mycotoxin threshold enforcement actions as early signals of supplier disqualification waves that would reshape viable vendor pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Olam Food Ingredients secures captive onion supply from Gujarat cooperatives, insulating margin from spot market volatility. |
| Infrared-Assisted Drying Retrofit | Maharashtra processors qualify for EU Green Deal carbon credentials while preserving volatile sulfur compounds in premium extracts. |
| Supercritical CO2 Extraction Deployment | Indian suppliers access French premium sauce channels blocked from solvent-based competitors under ECHA processing aid restrictions. |
| Blockchain Traceability Implementation | Gujarat dehydration units satisfy FDA Food Safety Modernization Act documentation requirements for US-bound organic shipments. |
| Direct-Procurement Contract Establishment | German ready-meal manufacturers lock in annual volume commitments with Rajkot processors, displacing traditional spice trader intermediaries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dehydration plant managers, procurement leads at European seasoning blenders, FSSAI certification auditors, and Dutch foodservice redistribution buyers with secondary validation. Sources included DGFT export certification databases, EU REACH Annex XVII substance restriction filings, FDA Food Safety Modernization Act traceability guidance documents, and Maharashtra State Agricultural Marketing Board harvest volume records. Bottom-up capacity modeling across Gujarat and Maharashtra dehydration clusters was triangulated against top-down demand estimates from European ready-meal production data.
Historical reference periods anchored volume and value projections across the analysis window, with growth trajectories derived from segment-level demand elasticity modeling. Segmentation dimensions included product form, application category, end-user procurement sophistication, and packaging type, with additional cross-cutting analysis by certification tier. Forecast inputs incorporated EU EFSA mycotoxin threshold enforcement probability, PLI scheme capacity expansion timelines, and freeze-dried substitute adoption curves in premium ready-meal segments.
The model holds under stable EU-India trade access and consistent monsoon patterns; deviation in FSSAI-DGFT-EU organic audit alignment timelines or REACH processing aid reclassifications would shift competitive positioning toward certified-grade specialists. Practitioners should monitor EU Green Deal carbon border adjustment mechanism proposals and Indian onion harvest forecast revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Asia-Pacific Prepared Mustard Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Paprika Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market