
 India Anti Caking Market | 2026-2036
India Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
India Anti Caking Market Foresight
Modular blending formats for anti-caking agents is repositioning buyer procurement across India's food and chemical sectors. Cargill India Private Limited leverages its pan-India distribution network to supply standardized anti-caking blends to regional food processors. BASF India Limited anchors its position through technical service partnerships with pharmaceutical formulators requiring excipient-grade purity. Evonik Industries AG differentiates via precipitated silica technologies tailored to high-humidity storage conditions prevalent in coastal manufacturing zones.
Anti-caking agents are hygroscopicity-control additives, typically comprising silicates, carbonates, or phosphates, that maintain free-flow properties in powdered and granulated materials by absorbing moisture or coating particle surfaces. These agents prevent agglomeration during storage, transport, and automated dosing in continuous production lines. Silicates command substantial volume share due to their cost-performance ratio in bulk chemical applications, while calcium carbonate formats gain traction in pharmaceutical tablet manufacturing where inert excipient compatibility matters. Powder and granular forms dominate current offtake, though liquid suspensions are emerging for spray-drying integration in dairy and beverage processing.
FSSAI mandates maximum permissible limits for silicon dioxide and other anti-caking additives in food categories, directly influencing formulation choices and supplier qualification protocols. BIS certification requirements for industrial-grade silicates and carbonates shape market access for domestic and imported material streams. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical-grade anti-caking excipients through drug master file submissions and facility inspections. Stakeholders must monitor evolving purity thresholds across food, drug, and agricultural chemical channels to align product portfolios with compliance trajectories and avoid qualification gaps in segmented supply chains.
Market Dynamics
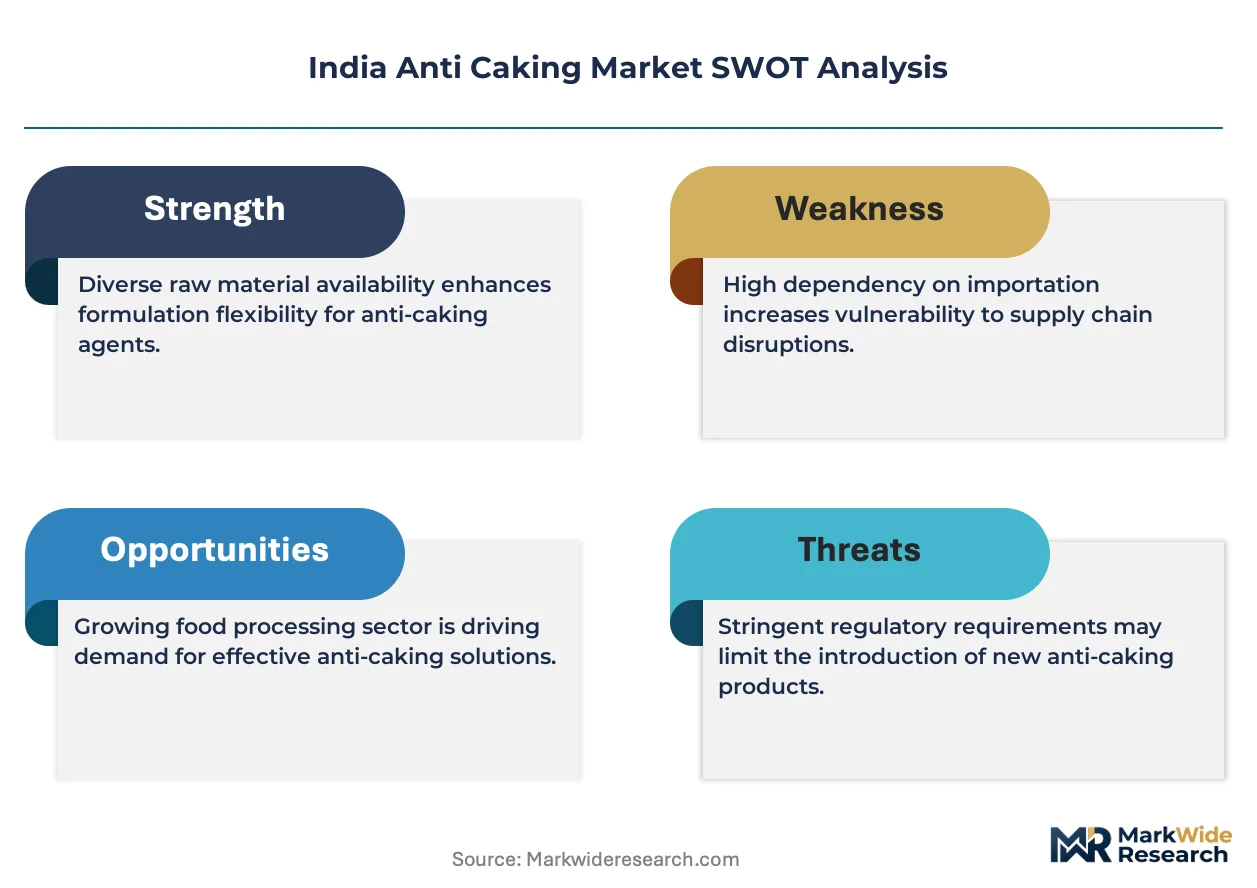
FSSAI purity standard revisions are compressing supplier qualification timelines while Maharashtra and Gujarat chemical clusters absorb disproportionate procurement volumes, creating a dual-speed market where certified players capture premium positioning.
Growth Catalysts
- Instant Mix Manufacturing Expansion:Food processors in Gujarat are scaling anti-caking agent procurement for masala and soup powder lines, pulling silicate and phosphate volumes toward dedicated blending facilities.
- FSSAI Additive Harmonization:The regulator's tightened silicon dioxide limits in seasoning categories are forcing reformulation cycles that favor qualified domestic suppliers over import-dependent buyers.
- Coastal Humidity Adaptation:Precipitated silica technologies engineered for high-moisture storage conditions are unlocking pharmaceutical and agrochemical applications previously served by carbonates.
Market Restraints
- Phosphate Raw Material Volatility:Rock phosphate import dependency exposes formulators to currency and freight cost swings that compress margin buffers on standard-grade products.
- Domestic Silicate Supply Concentration:Rajasthan and Gujarat-based silicate producers control bulk chemical-grade output, creating single-source vulnerability for regional food processors outside these catchments.
- Excipient-Grade Purity Thresholds:CDSCO drug master file requirements for pharmaceutical anti-caking agents impose 18-24 month qualification timelines that freeze out mid-tier chemical suppliers.
Strategic Opportunities
- Tamil Nadu Dairy Processing Corridor:Spray-dried milk powder and beverage premix facilities around Coimbatore remain underpenetrated for liquid suspension anti-caking formats tailored to continuous drying lines.
- PLI Scheme Alignment:The production-linked incentive framework for specialty chemicals offers capital subsidy pathways for domestic precipitated silica capacity expansion serving export-oriented pharmaceutical formulators.
- BIS Certification Arbitrage:Early movers securing industrial-grade carbonate and silicate certifications ahead of 2025-2026 specification tightening can capture displaced import volumes from non-compliant traders.
Industry Challenges
- Excipient-Formulation Skill Scarcity:Pharmaceutical tablet manufacturers report acute shortage of technical staff capable of integrating anti-caking agents into high-speed compression workflows without compromising dissolution profiles.
- Multi-Regulatory Compliance Burden:Suppliers serving food, drug, and agricultural chemical channels simultaneously must maintain parallel FSSAI, CDSCO, and Central Insecticides Board documentation systems that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Anti Caking Market |
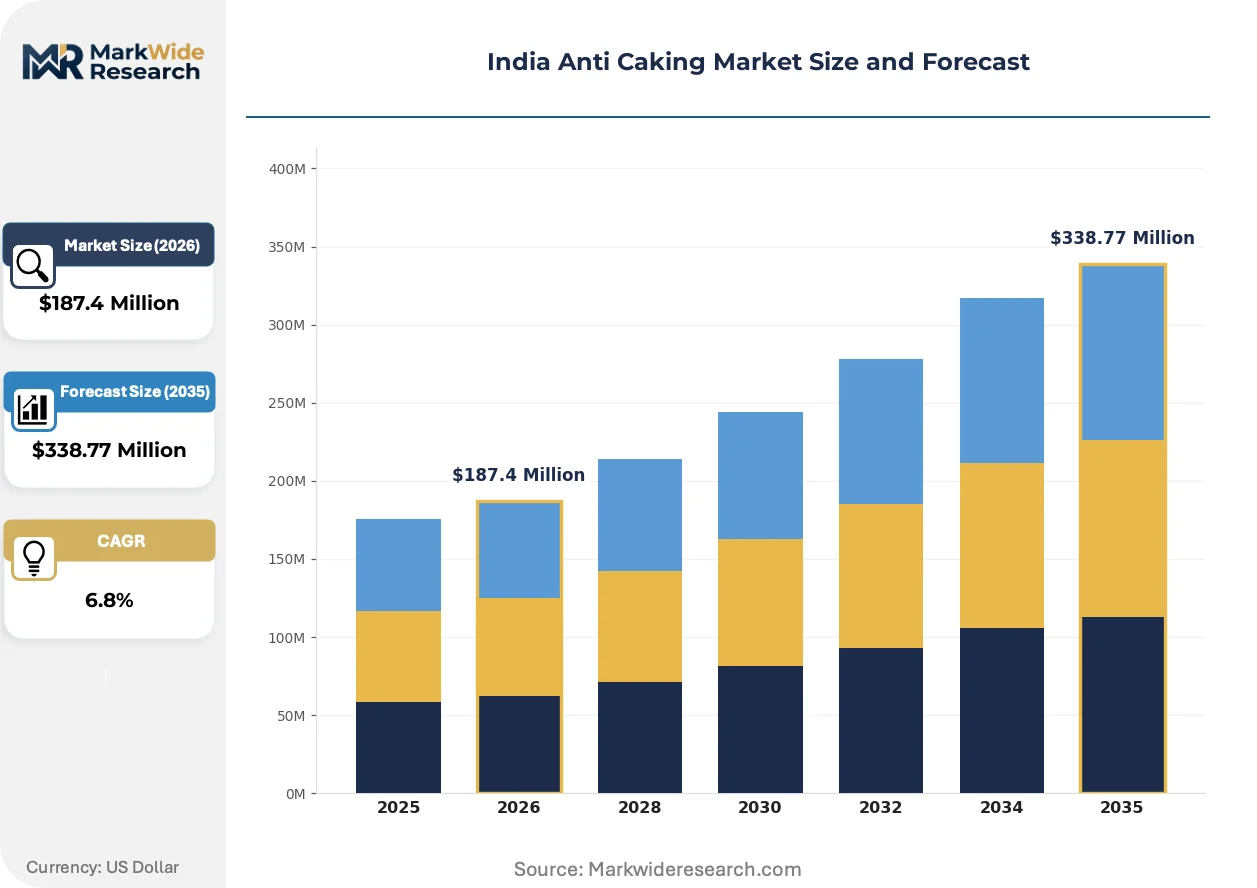
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bicarbonate, Calcium Carbonate, Magnesium Carbonate, Silicates End User: Food & Beverage, Pharmaceuticals, Agriculture, Chemical Industry Form: Powder, Granular, Liquid, Tablets Packaging Type: Bulk Bags, Sachets, Drums, Retail Packs |
| Companies Covered | PPG Industries, Cargill India Private Limited, BASF India Limited, Kao Corporation, Corbion Purac, PQ Corporation, Evonik Industries AG, Brenntag AG, Huber Engineered Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Anti Caking Market Shifts & Advancements
Modular blending systems and regulatory data digitization are compressing product development cycles while procurement patterns fragment across direct manufacturer relationships and specialized chemical distributors.
Nano-precipitated silica with controlled particle size distribution is rewriting moisture management performance benchmarks for high-value pharmaceutical and nutraceutical applications. Mumbai-based formulators are adopting these grades for effervescent tablet lines where flow consistency directly determines batch yield. The technology is compressing the addressable market for conventional fumed silica in premium excipient segments.
FSSAI's 2024 draft amendments on silicon dioxide and calcium silicate labeling thresholds are forcing reformulation investments across seasoning and instant noodle categories. Domestic blenders are accelerating purity testing infrastructure to preempt enforcement actions. Gujarat food processors are responding by consolidating supplier bases toward BIS-certified domestic producers with documented traceability systems.
Direct procurement relationships between large food manufacturers and Rajasthan silicate producers are displacing traditional distributor intermediaries in bulk chemical segments. Mahindra Agri and ITC Foods have established captive supply agreements that bypass Mumbai-based trading houses. This pattern is most visible in western India where chemical cluster proximity enables just-in-time inventory models.
India Anti Caking Market Segmentation
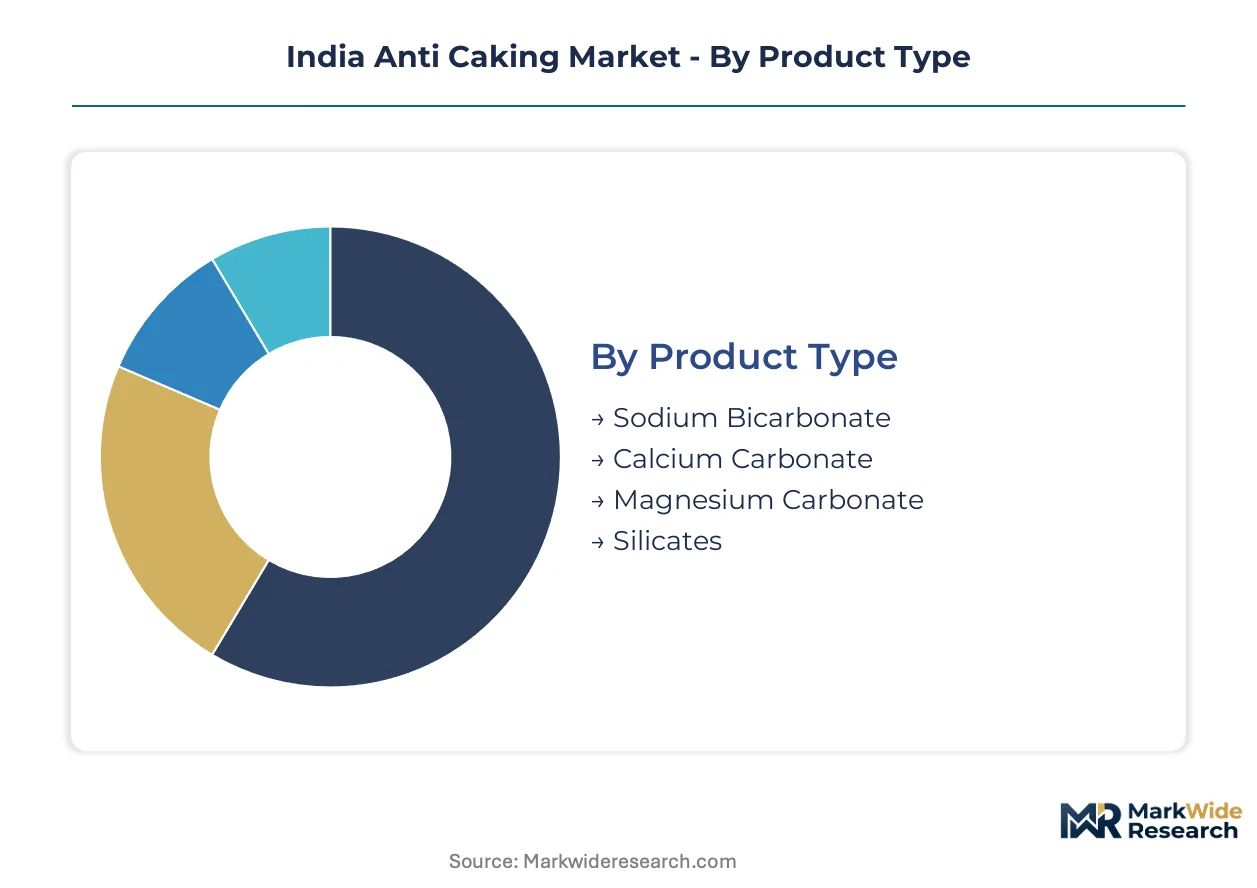
Anti-caking agent procurement in India fragments across purity grades, moisture sensitivity requirements, and regulatory channel specifications. Formulators select segments based on FSSAI compliance tiers, CDSCO excipient classifications, and BIS industrial-grade certifications that determine market access.
Product Type:
Silicate and carbonate chemistries dominate procurement volumes, with specification choices driven by end-use humidity exposure and cost-performance thresholds.
- Silicates:Precipitated and fumed silica variants absorb moisture through high surface-area particle structures. Gujarat food processors deploy these grades for masala powder lines where coastal humidity exceeds storage tolerance of alternative chemistries.
- Calcium Carbonate:Inert, non-hygroscopic powder serves pharmaceutical tablet manufacturing where excipient compatibility and dissolution profile stability take priority over moisture absorption capacity. Mumbai formulators favor this grade for high-speed compression workflows.
- Sodium Bicarbonate:Dual-function anti-caking and leavening agent concentrated in bakery premix and effervescent tablet applications.
- Magnesium Carbonate:Lightweight, high-porosity grade absorbing oils and moisture in seasoning blends and sports nutrition powders.
Mature deployment sits with silicates. Newer deployment is concentrated in calcium carbonate pharmaceutical grades.
End User:
Customer procurement patterns diverge sharply between regulated channels requiring certification documentation and bulk chemical buyers prioritizing unit economics.
- Food & Beverage:Instant mix manufacturers in Maharashtra and Gujarat drive silicate and phosphate volumes for seasoning, soup powder, and dairy premix applications. FSSAI silicon dioxide limit revisions are compressing supplier qualification timelines toward BIS-certified domestic sources.
- Pharmaceuticals:Tablet formulators demand excipient-grade purity with documented traceability for CDSCO drug master file submissions. Precipitated silica technologies engineered for high-humidity stability are displacing conventional fumed silica in premium effervescent lines.
- Agriculture:Fertilizer and pesticide granulation operations in Punjab and Haryana absorb industrial-grade carbonates for flowability control in bulk blending equipment.
- Chemical Industry:Detergent and catalyst manufacturers procure technical-grade silicates where BIS certification suffices and pharmaceutical purity thresholds represent cost overkill.
Procurement volume concentrates in food and beverage. Steepest expansion trajectory appears in pharmaceuticals.
Form:
Physical format selection hinges on integration method—direct blending, spray-drying, or high-speed compression—and moisture exposure during processing.
- Powder:Standard-grade particulate form dominating bulk chemical and food processing applications where dry blending equipment handles free-flow integration. Rajasthan silicate producers supply this format under long-term agreements with western India food manufacturers.
- Granular:Larger particle size reducing dust generation and improving flow properties in automated dosing systems. Agricultural chemical blenders in Gujarat prefer this form for fertilizer coating operations.
- Liquid:Suspension format emerging for spray-drying integration in Tamil Nadu dairy processing corridors around Coimbatore, where continuous drying lines require homogeneous feedstock distribution.
- Tablets:Pre-compressed excipient units for pharmaceutical formulators seeking precise dosing control in high-speed tablet compression workflows.
Established supply relationships center on powder formats. Liquid suspensions are gaining share fastest in dairy and beverage processing corridors.
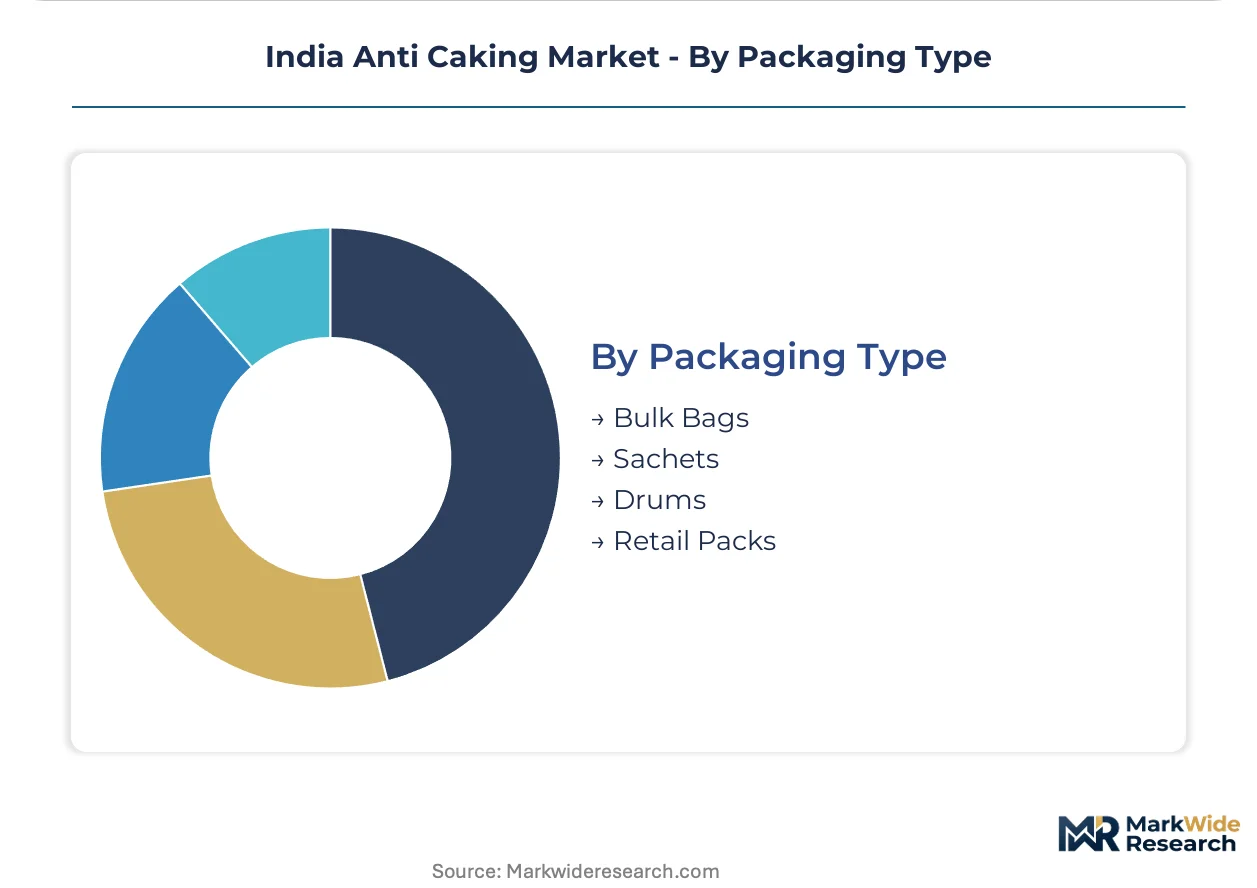
Packaging Type:
Packaging configuration tracks procurement scale, inventory turnover velocity, and moisture protection requirements through distribution channels.
- Bulk Bags:Flexible intermediate bulk containers handling 500-1000 kg loads for Rajasthan-to-Gujarat silicate movements and captive supply agreements bypassing distributor intermediaries.
- Drums:Steel and fiber containers for pharmaceutical-grade materials requiring sealed storage through CDSCO-qualified warehousing.
- Sachets:Small-format sealed packets for retail seasoning and instant mix brands distributing through modern trade and e-commerce channels.
- Retail Packs:Consumer-facing containers for specialty food and nutraceutical applications with brand differentiation requirements.
Volume leadership belongs to bulk bags. Retail packs are expanding most quickly in branded seasoning and nutraceutical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Rajasthan and Gujarat, while consumption spreads across western and southern food processing corridors. This geographic split shapes logistics costs and supplier qualification patterns. State-level regulatory enforcement varies, creating compliance arbitrage between manufacturing zones.
Maharashtra
Mumbai-based pharmaceutical formulators drive excipient-grade silica procurement for tablet compression workflows. CDSCO drug master file requirements impose 18-24 month qualification timelines that favor established suppliers with documented traceability. The Thane-Belapur chemical belt hosts blending facilities serving both domestic tablet manufacturers and export-oriented formulators.
Gujarat
Instant mix manufacturers in Ahmedabad and Vadodara scale anti-caking agent procurement for masala and soup powder lines. FSSAI silicon dioxide limit revisions are compressing supplier bases toward BIS-certified domestic producers. The Dahej and Ankleshwar industrial corridors absorb disproportionate silicate volumes through captive supply agreements bypassing traditional distributors.
Tamil Nadu
Spray-dried milk powder facilities around Coimbatore remain underpenetrated for liquid suspension anti-caking formats. Dairy processors seek homogeneous feedstock distribution for continuous drying lines. The state's food processing corridor lacks proximity to Rajasthan silicate producers, creating logistics premiums that liquid formats could offset.
Karnataka
Bengaluru nutraceutical manufacturers adopt nano-precipitated silica for effervescent tablet lines where flow consistency determines batch yield. The state's pharmaceutical cluster demands excipient-grade purity with shorter lead times than Rajasthan supply chains provide. Local blending operations are emerging to bridge this gap.
Haryana
Fertilizer granulation operations in Ambala and Panipat absorb industrial-grade carbonates for flowability control in bulk blending equipment. BIS certification suffices for this channel, avoiding pharmaceutical purity thresholds. The state's agricultural chemical sector faces phosphate raw material volatility due to rock phosphate import dependency.
India Anti Caking Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers. The market structures around three player categories: pan-India distribution networks, technical service partnerships, and precipitated silica technology specialists. Consolidation pressures mount as FSSAI purity standards tighten and qualification timelines extend. Capacity expansion and strategic partnerships dominate competitive moves, with direct procurement relationships displacing distributor intermediaries in western India.
Among diversified chemical conglomerates, BASF India Limited and Evonik Industries AG exemplify multinational archetypes anchoring premium positioning through technical service capabilities. Cargill India Private Limited represents the agribusiness-diversified model with pan-India distribution reach. These three players occupy positions across food, pharmaceutical, and industrial chemical channels, reflecting the market's segmentation by regulatory intensity rather than chemistry alone.
| Leading Market Players |
|---|
| PPG Industries |
| Cargill India Private Limited |
| BASF India Limited |
| Kao Corporation |
| Corbion Purac |
| PQ Corporation |
| Evonik Industries AG |
| Brenntag AG |
| Huber Engineered Materials |
| Others |
Supply & Pricing Matrix
FSSAI silicon dioxide limit revisions are compressing supplier qualification timelines toward BIS-certified domestic sources, forcing buyers to absorb premium pricing for documented traceability or risk disqualification from seasoning and instant mix procurement channels.
Pricing Analysis
Margin tightening in pharmaceutical-grade segments reflects CDSCO drug master file requirements that extend qualification timelines and concentrate volume among established excipient suppliers. Three-tier pricing structure across excipient-grade, food-grade, and industrial-grade certifications separates premium positioning from commodity positioning. Cost-down pressure on standard-grade silicates accelerates because Rajasthan producers face limited competition in bulk chemical channels. Agricultural fertilizer blenders exhibit highest price sensitivity, while Mumbai tablet formulators prioritize purity documentation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Gujarat food processors are forcing procurement teams to qualify secondary Rajasthan silicate producers despite geographic concentration risks. Supply draws from India, with precipitated silica technologies imported from Germany and specialty carbonates sourced from China. Rock phosphate dependency for phosphate-based anti-caking agents creates single-source vulnerability through Middle Eastern supply corridors. Distribution runs through direct captive agreements in western India and specialized chemical distributors serving pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Anti Caking Market sits in a technology-transition phase where nano-precipitated silica displaces conventional fumed silica in premium pharmaceutical applications, rewriting moisture management performance benchmarks and supplier qualification protocols.
For Market Incumbents: Anticipate FSSAI enforcement actions on silicon dioxide labeling by accelerating purity testing infrastructure investments ahead of specification tightening. Defensive consolidation through backward integration into Rajasthan silicate mining operations secures supply continuity against single-source vulnerability. Prioritize CDSCO drug master file maintenance to preserve excipient-grade positioning against mid-tier chemical suppliers frozen out by 18-24 month qualification timelines.
For New Entrants and Emerging Players: Begin with Tamil Nadu dairy processing corridors where spray-dried milk powder facilities remain underpenetrated for liquid suspension anti-caking formats. White-space targets include Coimbatore-area continuous drying lines seeking homogeneous feedstock distribution and Karnataka nutraceutical manufacturers demanding shorter lead times than Rajasthan supply chains provide. Go-to-market angle centers on technical service partnerships for effervescent tablet formulators.
For Investors and Strategic Acquirers: The window for entry favors precipitated silica technology specialists with documented humidity-adaptation capabilities serving pharmaceutical export channels. Long-term viability hinges on PLI scheme alignment for specialty chemicals capacity expansion. Acquisition target archetype includes domestic blenders with BIS certification moats ahead of 2025-2026 specification tightening. Signal to watch is FSSAI draft amendment finalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicate Mining | Captive supply from Rajasthan deposits eliminates distributor intermediaries and secures bulk chemical-grade volumes. |
| CDSCO Drug Master File Investment | Excipient-grade qualification timelines freeze out competitors and anchor premium positioning in Mumbai pharmaceutical corridors. |
| Liquid Suspension Format Development | Spray-drying integration unlocks Tamil Nadu dairy processing demand previously served by powder formats. |
| BIS Certification Pre-Positioning | Early compliance ahead of 2025-2026 specification tightening captures displaced import volumes from non-compliant traders. |
| Technical Service Partnership Model | Pharmaceutical formulator relationships differentiate against commodity silicate suppliers in high-humidity storage applications. |
Research Methodology
Document review covered FSSAI additive regulations, BIS certification standards, CDSCO excipient guidelines, and customs trade data, complemented by interviews with plant managers at Rajasthan silicate producers, procurement leads at Gujarat food processors, technical R&D directors at pharmaceutical formulators, and distribution channel partners in Mumbai chemical trading corridors. Secondary validation drew from SEC filings of multinational chemical conglomerates, industry association reports, and production capacity disclosures. Bottom-up volume estimates triangulated against top-down market sizing across grade tiers and end-use channels.
Segmented outputs across the projection horizon reflect modeling by product chemistry, purity grade, physical form, packaging configuration, and regional production hub. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of regulatory compliance timelines. Industry-specific inputs included FSSAI amendment implementation schedules, PLI scheme subsidy allocation trajectories, and coastal humidity exposure indices affecting storage condition specifications.
Regulatory enforcement delays, raw material import tariff fluctuations, and excipient-formulation skill scarcity are the dominant revision risks to forecast assumptions. Deviation in FSSAI silicon dioxide limit implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Locust Bean Gum Market