
 Oncology Drugs Market | 2026-2036
Oncology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Drugs Market Intelligence
Good Manufacturing Practice certification is rotating toward continuous bioprocessing standards, raising barriers for legacy batch manufacturers. Roche leverages its diagnostic-drug pairing strategy to sustain oncology leadership across multiple tumor types. AstraZeneca anchors its position through antibody-drug conjugate specialization in solid tumors. Bristol-Myers Squibb competes via checkpoint inhibitor combinations that extend into earlier lines of therapy.
Oncology drugs comprise therapeutics engineered to selectively modulate malignant cell proliferation, including small molecules, biologics, and cellular therapies formulated to precise purity specifications exceeding standard pharmaceutical grades. These agents serve the clinical purpose of extending survival, inducing remission, or managing tumor burden across diverse malignancies. Immunotherapy and targeted therapy segments command premium positioning due to durable response profiles and expanding label indications. Chemotherapy retains volume dominance in emerging markets where biosimilar access remains limited. Monoclonal antibodies concentrate margin pools through high-price maintenance regimens in breast and lung cancer indications.
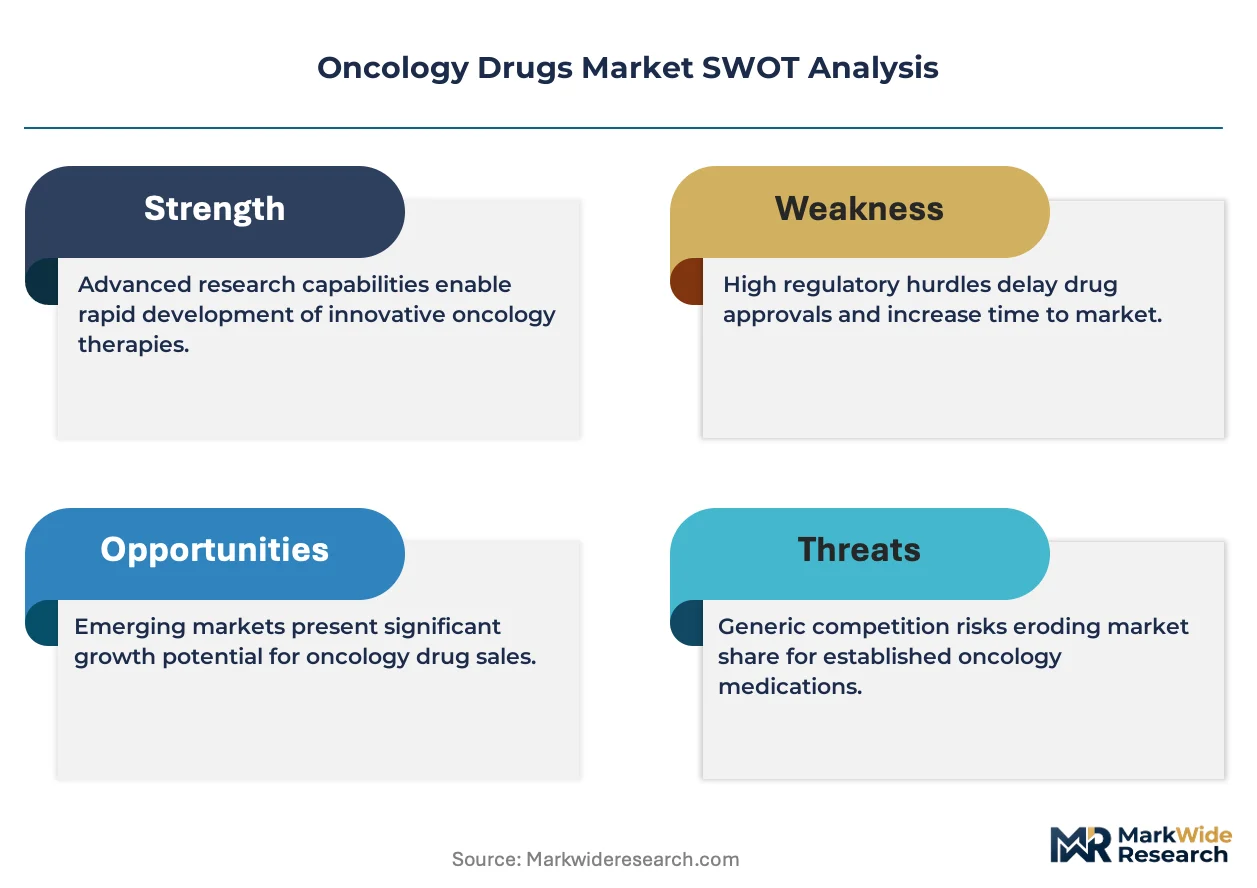
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines while mandating confirmatory trial commitments. The EPA oversees active pharmaceutical ingredient manufacturing discharge standards that constrain production location decisions. Stakeholders must monitor confirmatory trial failure rates and subsequent withdrawal patterns, as these regulatory reversals reshape portfolio risk calculations and reimbursement durability assumptions.
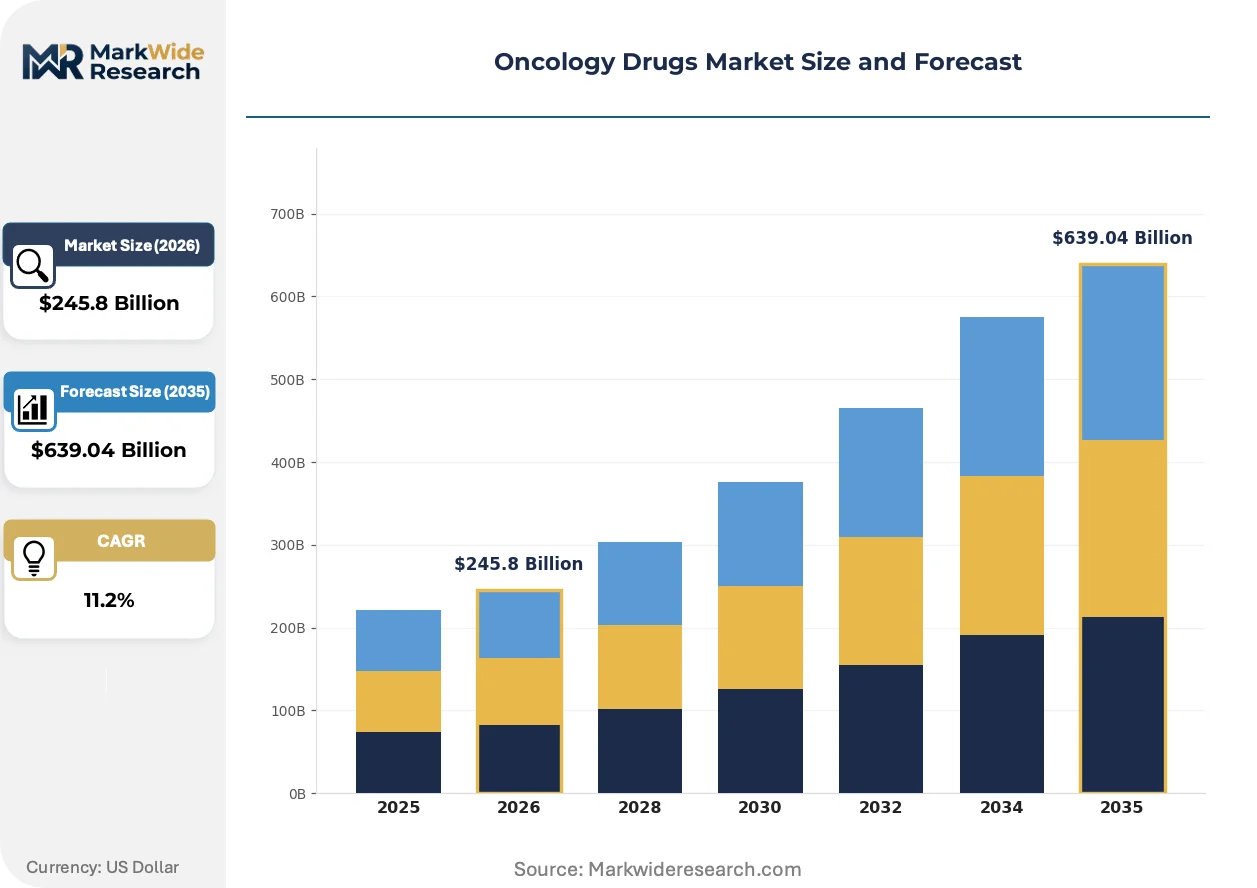
Market Dynamics
FDA accelerated approval pathways compress development timelines while mandating confirmatory trial commitments, reshaping how oncology portfolios balance speed against durability risk. This structural pressure concentrates investment in modalities with clearer surrogate endpoints.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's drug pricing provisions accelerate oncology pipeline prioritization toward biologics and orphan indications exempt from early negotiation timelines.
- Continuous Bioprocessing:Single-use bioreactor adoption reduces facility construction timelines by 40% and enables rapid capacity scaling for antibody-drug conjugate manufacturing.
- China:NMPA priority review pathways for breakthrough therapies compress regulatory timelines to 130 days, attracting multinational Phase III trial placement and regional launch sequencing.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for cytotoxic chemotherapies concentrates in Zhejiang and Jiangsu provinces, creating geopolitical exposure and quality audit backlogs.
- Confirmatory Trial Failure Risk:FDA withdrawals of accelerated approvals for checkpoint inhibitors in urothelial and gastric cancers force portfolio write-downs and reimbursement clawback exposure.
- Cold Chain Infrastructure Gaps:CAR-T cell therapy distribution requires minus 150-degree Celsius logistics that remain unavailable across India, Brazil, and Indonesia, limiting addressable patient pools.
Strategic Opportunities
- Sub-Saharan Africa:Biosimilar trastuzumab and rituximab penetration remains below 15% across Nigeria, Kenya, and South Africa, creating first-mover advantage for localized fill-finish partnerships.
- Antibody-Drug Conjugate Convergence:Site-specific conjugation technologies paired with novel payload classes (topoisomerase I inhibitors, kinesin spindle protein inhibitors) expand therapeutic index and solid tumor applicability.
- Hospital-at-Home Administration:Subcutaneous formulation development for pembrolizumab and daratumumab enables reimbursement for home infusion services under Medicare's Hospital Outpatient Prospective Payment System.
Industry Challenges
- Cell Therapy Manufacturing Talent:Vector production, cell expansion, and quality control functions face acute shortages as academic training programs lag commercial facility expansion by 36 months.
- Legacy EHR Integration:Real-world evidence collection for confirmatory trials requires interoperability with Epic and Cerner systems that resist standardized data extraction protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Drugs Market |
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $639.04 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Targeted Therapy, Immunotherapy, Hormonal Therapy, Chemotherapy, Monoclonal Antibodies Therapy Area: Lung Cancer, Breast Cancer, Colorectal Cancer, Prostate Cancer, Leukemia End User: Oncology Clinics, Cancer Research Centers, Specialty Pharmacies, Ambulatory Surgical Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular, Transdermal |
| Companies Covered | AstraZeneca, Johnson & Johnson Services, Inc., Roche, Pfizer Inc., AbbVie Inc., Novartis AG, Bristol-Myers Squibb Company, Amgen Inc., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Drugs Market Strategic Shifts & Innovations
Biologics manufacturing is splitting between legacy batch processes and continuous platforms, with regulatory acceptance now determining competitive positioning rather than technical feasibility alone.
Continuous bioprocessing is bifurcating the contract manufacturing landscape. Perfusion-based cell culture systems reduce facility footprints by 70% while doubling volumetric productivity. Large-capacity stainless steel facilities in Singapore and Switzerland face stranded asset risk as mid-scale single-use plants in North Carolina and Massachusetts capture novel biologics contracts. The technology is bifurcating margin structures between capital-intensive legacy operators and nimble continuous specialists.
EMA's revised Good Manufacturing Practice Annex 1 for sterile products mandates barrier isolation technology and real-time environmental monitoring. This compresses compliance timelines for legacy European facilities while creating competitive advantage for greenfield investments in Ireland and the Netherlands that incorporated these standards during construction. Oncology sterile injectable manufacturers now face 18-month retrofit cycles or contract manufacturing organization switching.
Site-of-care decisions increasingly follow reimbursement rate differentials rather than clinical convenience. Hospital outpatient departments expand infusion capacity to capture 340B drug pricing advantages, while physician office administration declines where Medicare reimbursement cuts compress margins. This concentration is most visible across Texas, Florida, and Arizona oncology networks where hospital system consolidation has accelerated since 2022.
Oncology Drugs Market Segmentation
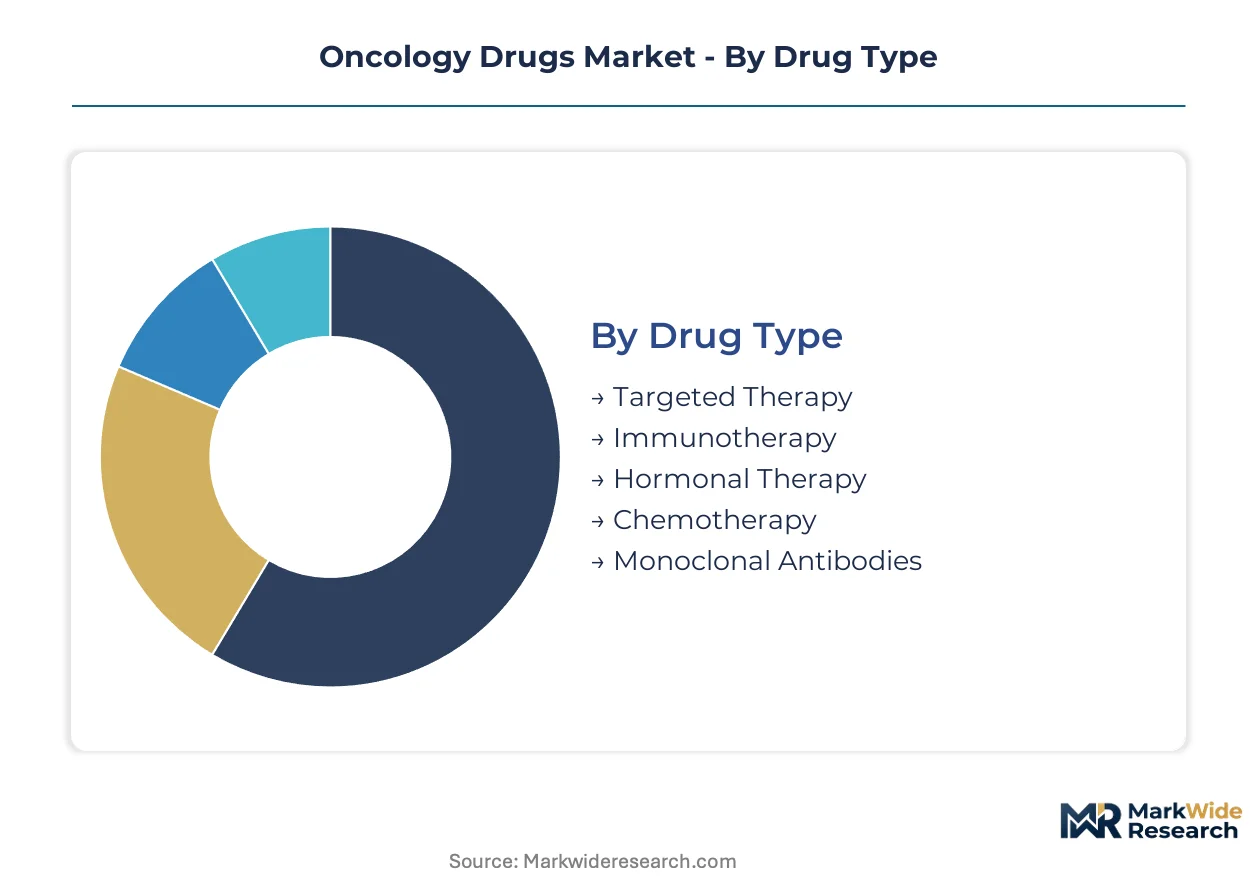
Oncology drug segmentation reveals divergent growth mechanics across therapeutic modalities and care settings. Each dimension carries distinct regulatory, reimbursement, and manufacturing requirements that reshape competitive positioning.
Drug Type:
Domestic demand concentrates in immunotherapy and targeted therapy segments where US reimbursement rates sustain premium pricing. Export-led growth flows through chemotherapy and hormonal therapy where emerging market volume requirements dominate procurement decisions.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell therapies engineered to activate host immune recognition of malignant cells. Demand clusters in US hospital outpatient departments where Medicare's add-on payment structure rewards high-cost administration. IRA price negotiation exemptions for biologics accelerate pipeline investment toward this modality.
- Targeted Therapy:Small-molecule kinase inhibitors and PARP inhibitors designed against specific oncogenic mutations. Concentrated prescribing follows companion diagnostic availability in academic medical centers across Germany, Switzerland, and the United States. Resistance mutation patterns force continuous next-generation development cycles.
- Hormonal Therapy:Androgen and estrogen pathway modulators for prostate and breast malignancies. Standardized protocols drive volume in India and Brazil where generic substitution rates exceed 60 percent.
- Chemotherapy:Cytotoxic alkylating agents, antimetabolites, and taxanes retaining first-line positions in resource-constrained settings. Zhejiang and Jiangsu province API concentration creates supply vulnerability for US and European formulators.
- Monoclonal Antibodies:Naked and conjugated antibodies targeting HER2, EGFR, and CD20 surface antigens. Maintenance regimen pricing sustains margin pools in Japanese and South Korean reimbursement frameworks.
Immunotherapy commands the established base. The steepest expansion runs through targeted therapy.
Therapy Area:
Cost tier stratification separates curative-intent indications with multi-year treatment horizons from palliative settings where duration compresses value capture.
- Lung Cancer:NSCLC biomarker stratification now recognizes over ten actionable mutations requiring matched therapy selection. US community oncology practices concentrate PD-L1 testing and EGFR/ALK genotyping volume.
- Breast Cancer:HER2-directed and CDK4/6 inhibitor regimens dominate adjuvant and metastatic settings. European reference pricing systems in France and Italy drive biosimilar trastuzumab penetration above 40 percent.
- Colorectal Cancer:MSI-high status determines checkpoint inhibitor eligibility in first-line metastatic disease. Japanese screening programs shift diagnosis toward earlier stages with curative surgical options.
- Prostate Cancer:PARP inhibitor approvals in HRR-mutated castration-resistant disease expand addressable populations. Australian and Canadian health technology assessment bodies apply stricter cost-effectiveness thresholds than FDA.
- Leukemia:BCR-ABL tyrosine kinase inhibitors and B-cell maturation antigen-directed therapies transform chronic and acute lymphoid malignancies into manageable conditions. Pediatric protocol requirements in US children's hospitals sustain specialized manufacturing runs.
Lung cancer absorbs the largest development investment. Breast cancer delivers the most durable revenue streams.
End User:
Volume concentration follows site-of-care reimbursement differentials rather than clinical preference alone.
- Oncology Clinics:Physician-owned infusion centers facing Medicare reimbursement compression in Texas, Florida, and Arizona. 340B pricing advantages drive hospital acquisition of independent practices.
- Cancer Research Centers:NCI-designated comprehensive cancer centers conducting early-phase trials with investigational agents. FDA breakthrough therapy designation pathways prioritize these sites for patient access programs.
- Specialty Pharmacies:Limited distribution networks for oral oncolytics requiring REMS compliance and patient monitoring. Accreditation standards from URAC and ACHC create entry barriers.
- Ambulatory Surgical Centers:Emerging site for subcutaneous administration and port placement procedures. CMS reimbursement rate differentials versus hospital outpatient departments remain under 15 percent.
Oncology clinics retain the highest patient throughput. Cancer research centers capture the most favorable pricing for novel agents.
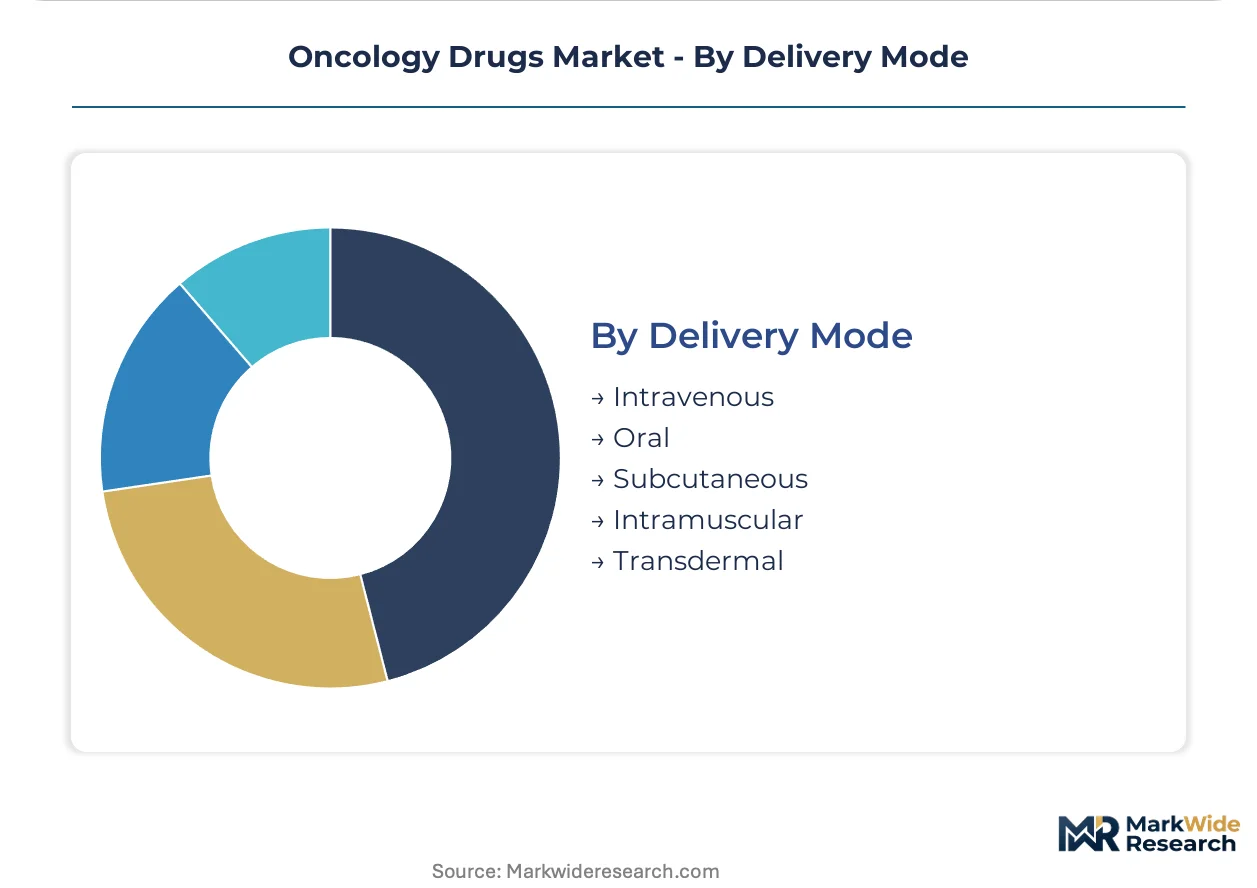
Delivery Mode:
Supply concentration in sterile injectable manufacturing favors intravenous formats, while patient convenience pressures drive subcutaneous and oral development.
- Intravenous:Infusion-dependent biologics requiring hospital or clinic administration. Cold chain and compounding pharmacy infrastructure concentrates in US Northeast and Midwest population corridors.
- Oral:Small-molecule kinase inhibitors enabling home administration with pharmacy benefit manager managed distribution. Prior authorization requirements create administrative burden for community oncologists.
- Subcutaneous:Reformulation investments for pembrolizumab and daratumumab to enable home administration under Medicare's Hospital Outpatient Prospective Payment System.
- Intramuscular:Limited application for hormonal depot formulations in prostate and breast cancer maintenance settings.
- Transdermal:Experimental delivery for topical kinase inhibitors in cutaneous T-cell lymphoma and basal cell carcinoma with confined disease burden.
Intravenous formats dominate current revenue. Subcutaneous development pipelines are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies in the United States reshape site-of-care decisions and prescribing volumes across oncology networks. China's NMPA priority review pathways attract multinational trial placement and accelerate regional launch sequencing. Germany's EMA-aligned regulatory framework anchors European reference pricing systems.
United States
Hospital outpatient departments expand infusion capacity to capture 340B drug pricing advantages across Texas, Florida, and Arizona oncology networks. The Inflation Reduction Act's Medicare price negotiation provisions accelerate pipeline prioritization toward biologics and orphan indications. The FDA's accelerated approval pathway compresses development timelines while mandating confirmatory trial commitments for breakthrough therapies.
China
NMPA priority review pathways for breakthrough therapies compress regulatory timelines to 130 days, attracting multinational Phase III trial placement. Active pharmaceutical ingredient manufacturing for cytotoxic chemotherapies concentrates in Zhejiang and Jiangsu provinces, creating geopolitical exposure. Shanghai and Suzhou biotech clusters host expanding antibody-drug conjugate manufacturing capacity for regional supply.
Germany
Companion diagnostic availability concentrates prescribing of small-molecule kinase inhibitors in academic medical centers across Munich and Heidelberg. EMA conditional marketing authorization frameworks align with national health technology assessment processes. The Rhine-Main and Bavarian pharmaceutical clusters sustain sterile injectable manufacturing for European distribution.
Japan
MSI-high screening programs shift colorectal cancer diagnosis toward earlier stages with curative surgical options in Tokyo and Osaka metropolitan areas. PMDA regulatory frameworks prioritize oncology indications through sakigake designation pathways. Maintenance regimen pricing for monoclonal antibodies sustains margin pools under national health insurance reimbursement frameworks.
India
Biosimilar trastuzumab and rituximab penetration remains below 15 percent across Maharashtra and Karnataka, creating first-mover advantage for localized fill-finish partnerships. CDSCO regulatory pathways accommodate abbreviated approval routes for reference-listed drugs. Hyderabad and Ahmedabad pharmaceutical corridors expand cytotoxic API manufacturing for export markets.
Oncology Drugs Market Key Industry Players
Player mix skews toward integrated pharmaceutical conglomerates with diagnostic-drug pairing capabilities and specialized biologics manufacturers with continuous processing expertise. Market structure concentrates around checkpoint inhibitor combinations, antibody-drug conjugate platforms, and targeted therapy portfolios. Strategic archetypes include diagnostic-therapeutic integrators, modality specialists, and biosimilar scale operators. Competitive moves center on confirmatory trial acceleration and subcutaneous formulation development for site-of-care expansion.
Among Swiss-based pharmaceutical conglomerates, Roche exemplifies diagnostic-drug integration strategies across multiple tumor types. AstraZeneca and Bristol-Myers Squibb occupy positions within the immunotherapy-specialist tier, with the former anchoring antibody-drug conjugate development in solid tumors and the latter representing checkpoint inhibitor combination approaches. These three entities illustrate divergent archetypes for sustaining oncology leadership amid compressed regulatory timelines and reimbursement pressure.
| Leading Market Players |
|---|
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| Roche |
| Pfizer Inc. |
| AbbVie Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| Merck & Co., Inc. |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with contract manufacturing organizations lock in sterile injectable supply access and provide twelve-month price visibility for antibody-drug conjugate portfolios. These structures concentrate negotiation leverage among sponsors with multi-product commitments to continuous bioprocessing facilities in North Carolina and Massachusetts.
Pricing Analysis
Certification level creates the primary spread, with FDA-grade biologics commanding substantial premiums over EMA-equivalent tiers in US hospital outpatient settings. Value-based pricing models tied to progression-free survival endpoints dominate immunotherapy reimbursement, while chemotherapy faces acute price compression from biosimilar substitution in Indian and Brazilian procurement. Academic medical centers exhibit lowest price sensitivity due to research funding buffers; community oncology clinics face highest sensitivity from Medicare reimbursement compression.
Supply Chain Analysis
Strategic stockpiling of cytotoxic active pharmaceutical ingredients dominates over just-in-time preferences given Zhejiang and Jiangsu province concentration risks. Mammalian cell culture media and novel payload chemistries draw from Swiss and German specialty chemical suppliers. Single-source vulnerability in plasmid DNA production for CAR-T vectors constrains cell therapy expansion. Distribution runs through hospital-owned specialty pharmacies with 340B pricing capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against biosimilar substitution in trastuzumab and rituximab maintenance regimens, where reference product erosion threatens oncology margin pools.
For Market Incumbents: Fortify antibody-drug conjugate pipelines through site-specific conjugation technology acquisitions that extend therapeutic index differentiation. Secure backward integration into payload manufacturing to defend margin position from specialty chemical supplier consolidation. Prioritize confirmatory trial acceleration to preempt accelerated approval withdrawal risks.
For New Entrants and Emerging Players: Subcutaneous formulation development for checkpoint inhibitors represents the most penetrable service-layer gap, as incumbents under-serve home administration demand. Target Medicare Hospital Outpatient Prospective Payment System reimbursement arbitrage through device-enabled delivery partnerships. Pursue localized fill-finish partnerships in Nigeria and Kenya for biosimilar oncology access.
For Investors and Strategic Acquirers: Capital is best deployed toward continuous bioprocessing specialists with FDA pre-approval inspection readiness and single-use platform scalability. Long-term viability centers on modality-agnostic manufacturing infrastructure capable of antibody, ADC, and cell therapy production. Watch FDA confirmatory trial failure rates as inflection indicator for reimbursement durability assumptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Confirmatory Trial Acceleration | Preempts IRA price negotiation exposure for accelerated approval therapies. |
| Subcutaneous Formulation Development | Captures Medicare Hospital Outpatient Prospective Payment System home infusion reimbursement. |
| Continuous Bioprocessing Scale-Up | Reduces facility footprint while doubling volumetric productivity for antibody-drug conjugates. |
| Site-of-Care Expansion Partnerships | Secures 340B pricing advantages through hospital outpatient department capacity agreements. |
| Companion Diagnostic Integration | Locks in prescribing concentration for targeted therapy portfolios in academic medical centers. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions. Primary fieldwork combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement data enabled bottom-up and top-down triangulation.
Segmentation dimensions modeled include therapeutic modality, therapy area, end-user setting, and regional regulatory cluster across the projection horizon. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated confirmatory trial success rates and IRA negotiation timeline exemptions.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA conditional marketing authorization frameworks; material policy shifts would require re-modeling. Revision becomes warranted when confirmatory trial failure rates for breakthrough therapies cross thresholds that trigger reimbursement clawback exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market