
 Octreotide Market | 2026-2036
Octreotide Market Size, Share, and Industry Trends Forecast 2026-2036
Octreotide Market Analysis
REACH compliance for peptide manufacturing is repositioning European production economics toward higher-purity synthesis routes. Novartis AG leverages its long-acting release formulation heritage to sustain premium positioning in acromegaly care. Sun Pharmaceutical Industries Ltd. anchors its competitive stance through aggressive generic penetration across emerging markets. Teva Pharmaceutical Industries Ltd. differentiates via vertically controlled peptide supply chains that reduce API dependency.
Octreotide is a synthetic octapeptide analog of somatostatin, composed of eight amino acids with a molecular weight of approximately 1,019 daltons, manufactured through solid-phase peptide synthesis and used primarily to suppress growth hormone and gastrointestinal peptide secretion in neuroendocrine disorders. Injection formulations dominate clinical practice due to established bioavailability profiles and decades of physician familiarity, while subcutaneous delivery mode captures the largest volume share through patient-administered depot preparations. Homecare settings represent the fastest-growing end-user channel as payers push infusion outside institutional walls.
FDA bioequivalence guidelines for peptide drugs, EMA's biosimilar framework under the MDR pathway, and India's CDSCO tightening for imported APIs collectively elevate compliance burdens while filtering subscale competitors. These frameworks shape demand by mandating costly stability studies and immunogenicity profiling that favor manufacturers with dedicated peptide facilities. Stakeholders must monitor evolving FDA draft guidance on peptide generic substitution and calibrate portfolio investments between innovator formulations and complex generic pipelines accordingly.
Market Dynamics
Peptide manufacturing compliance costs are concentrating production among facilities capable of multi-jurisdictional FDA, EMA, and PMDA filings, filtering out contract manufacturers lacking dedicated peptide synthesis infrastructure.
Growth Catalysts
- Homecare infusion migration:Payer pressure across Germany, Japan, and the United States is accelerating patient-administered depot formulations outside hospital walls.
- EMA MDR pathway maturation:The biosimilar framework for complex peptides is creating predictable approval timelines that attract portfolio investment from mid-scale manufacturers.
- Neuroendocrine tumor protocol expansion:Hospital-based oncology departments are widening first-line somatostatin analog use in diagnostic and therapeutic sequences.
Market Restraints
- API supply concentration:Solid-phase peptide synthesis precursors cluster among Chinese and Indian specialty chemical producers, exposing finished dose manufacturers to single-source fragility.
- Immunogenicity profiling costs:FDA and EMA stability study mandates for peptide generics impose seven-figure validation burdens that exclude subscale entrants.
- Biologic substitution pressure:Long-acting growth hormone receptor antagonists and radioligand therapies are encroaching on acromegaly and NET maintenance indications.
Strategic Opportunities
- Subcutaneous micro-needle delivery:Needle-free administration technology is converging with patient preference data to open pediatric and needle-phobic adult segments.
- India CDSCO pathway optimization:Streamlined import API registration is enabling faster market entry for complex generic peptide portfolios.
- Real-world evidence contracting:Outcomes-based reimbursement pilots in German and Japanese national health systems reward longitudinal efficacy data collection.
Industry Challenges
- Peptide chemist scarcity:Solid-phase synthesis expertise concentrates among aging specialists in Basel, Boston, and Hyderabad, constraining facility expansion timelines.
- Cross-contamination validation:Multi-product peptide facilities face extended cleaning protocol development to satisfy FDA and EMA shared-manufacturing guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octreotide Market |
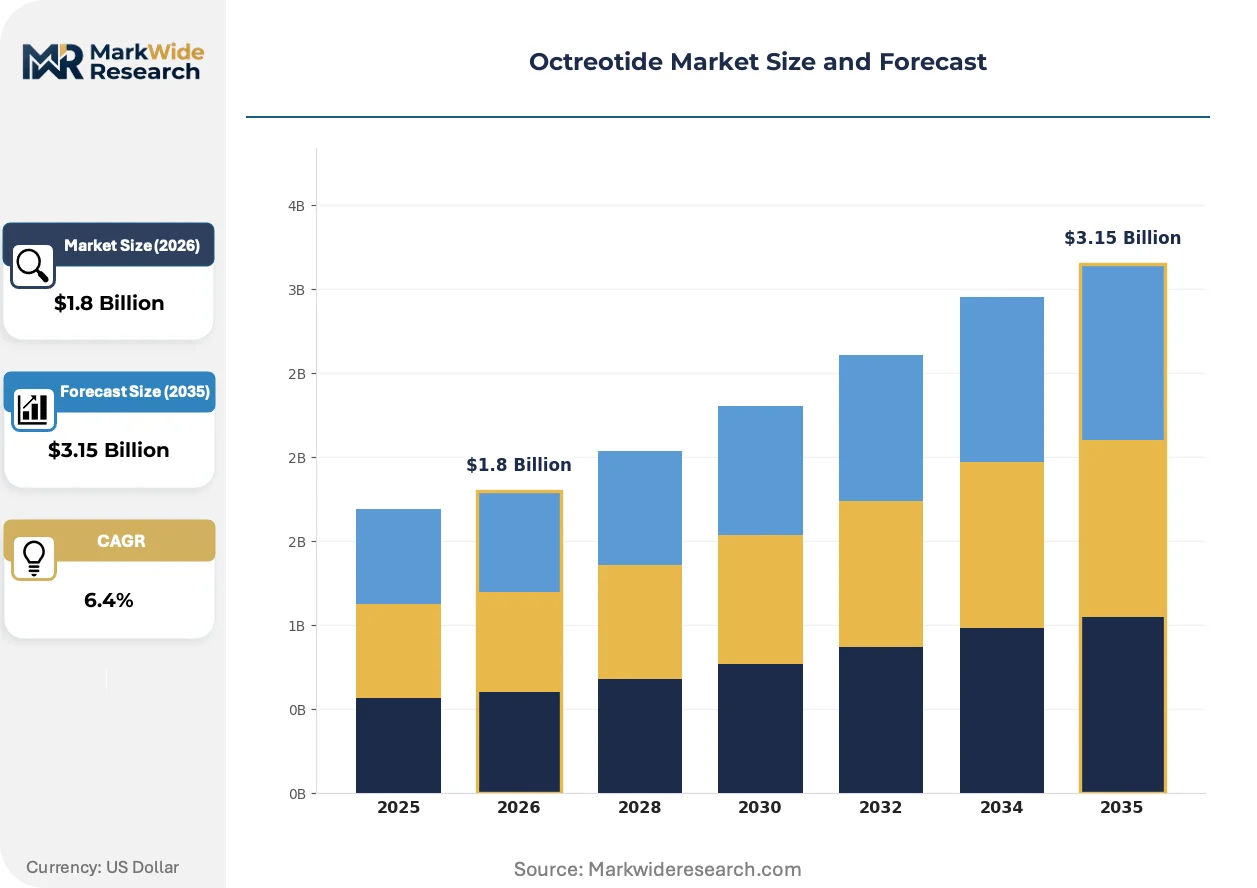
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Capsule, Powder, Solution Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral End User: Hospitals, Clinics, Homecare Settings, Pharmacies Indication: Acromegaly, Carcinoid Syndrome, VIPoma, Other Endocrine Disorders |
| Companies Covered | Novartis AG, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Viatris Inc., Fresenius Kabi AG, Ipsen S.A., Aurobindo Pharma Limited, Dr. Reddy’s Laboratories Ltd., Hikma Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octreotide Market Emerging Trajectories
Formulation science and delivery mechanism innovation are compressing dosing frequency while regulatory science is hardening evidentiary standards for generic substitution equivalence.
Continuous flow peptide synthesis is converging with traditional batch solid-phase methods to reduce solvent waste and improve yield consistency. Mid-scale manufacturers in Switzerland and Massachusetts are piloting hybrid production lines that retain batch flexibility for low-volume orphan indications while capturing flow chemistry economies for commercial-scale octreotide analogs. This technology convergence is compressing cost differentials between innovator and complex generic manufacturing.
REACH Annex XVII restrictions on N-methylpyrrolidone solvent use are forcing European peptide facilities to validate alternative dissolution chemistries by 2026. The ECHA enforcement trajectory is elevating capital requirements for synthesis route redevelopment. German and Dutch manufacturers are responding fastest, securing first-mover advantage in green chemistry certification that commands premium positioning in EMA-regulated markets.
Hospital procurement consortia in the United States and Japan are unbundling somatostatin analog purchasing from broader oncology formulary contracts. This concentration of buying power is compressing price negotiation cycles from annual to quarterly intervals. The shift is most visible in academic medical center networks where pharmacy and therapeutics committees now mandate biosimilar substitution unless clinical equivalence data is submitted within 90 days.
Octreotide Market Segmentation
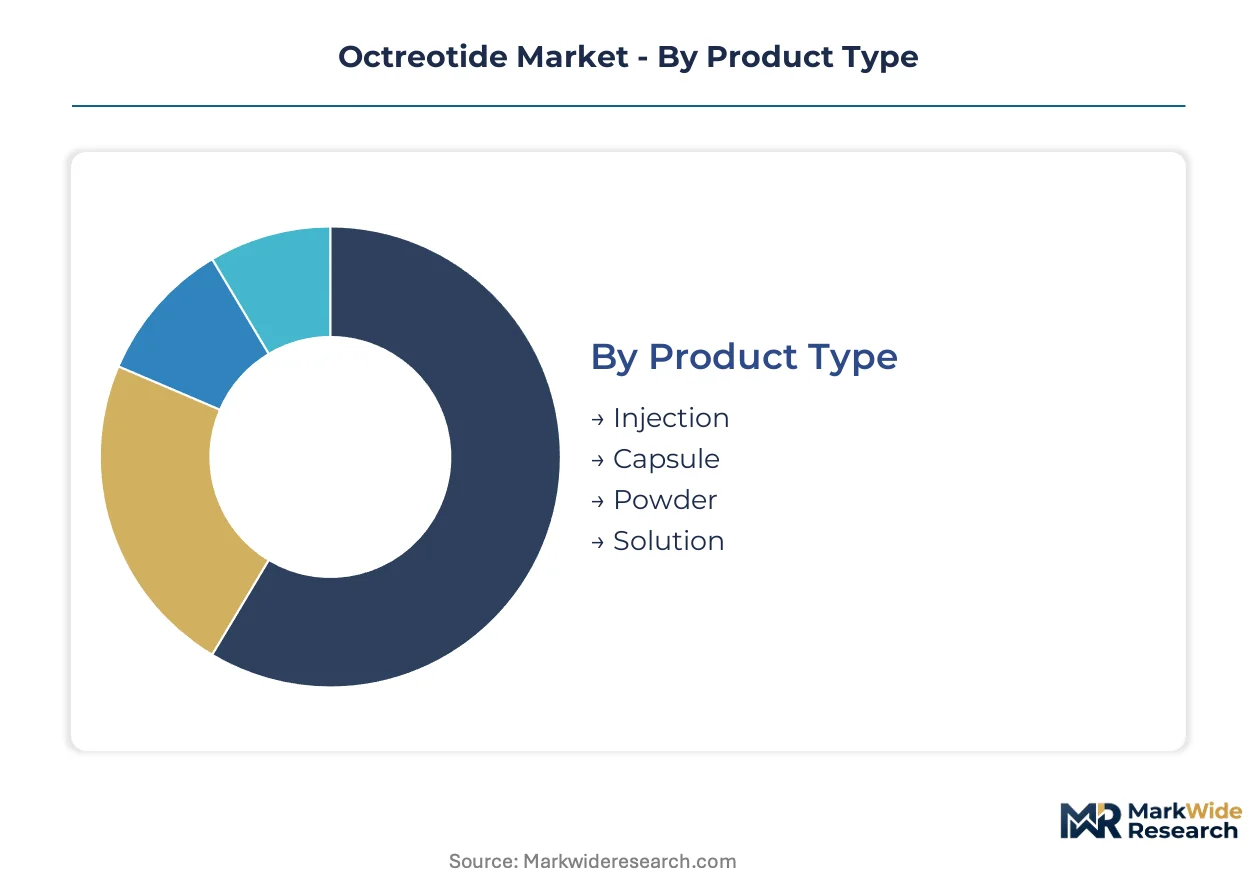
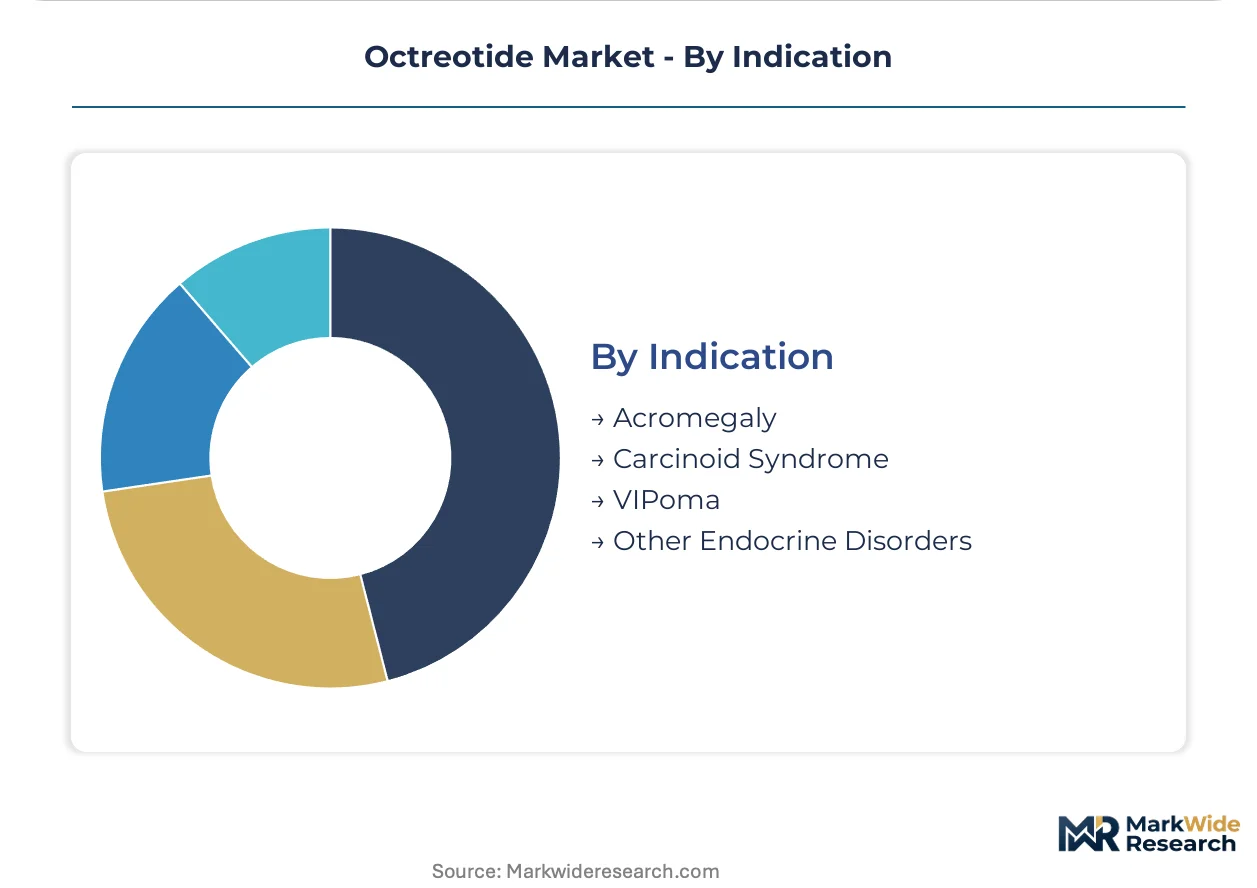
Octreotide's therapeutic versatility across neuroendocrine disorders creates distinct demand profiles by formulation, administration route, care setting, and disease indication. Each segmentation axis carries unique regulatory, reimbursement, and manufacturing implications that reshape competitive positioning.
Product Type:
Buyers differentiate by bioavailability requirements, stability constraints, and administration infrastructure rather than price alone.
- Injection:Liquid formulations in vials or pre-filled syringes dominate hospital-based neuroendocrine tumor protocols. Demand concentrates across the United States, Germany, and Japan where FDA, EMA, and PMDA bioequivalence standards for peptide generics filter subscale manufacturers.
- Capsule:Oral solid dosage forms appeal to outpatient maintenance therapy, though limited bioavailability restricts use to specific patient populations. German and Japanese payers increasingly favor these for homecare migration to reduce institutional infusion costs.
- Powder:Lyophilized presentations for reconstitution serve specialized compounding pharmacies and research institutions requiring dose flexibility.
- Solution:Ready-to-use liquid formulations streamline nursing workflows in high-volume oncology units.
Volume sits with Injection; growth tilts toward Capsule.
Delivery Mode:
Route selection tracks patient autonomy preferences and payer pressure to shift administration outside institutional walls.
- Subcutaneous:Patient-administered depot preparations capture the largest volume share through long-acting release formulations. Homecare settings across Germany and the United States drive expansion as reimbursement frameworks reward reduced hospital days.
- Intravenous:Continuous infusion maintains primacy in acute carcinoid crisis management and perioperative care. Japanese academic medical centers anchor demand for IV precision in diagnostic sequences.
- Intramuscular:Monthly depot injections serve acromegaly maintenance with established physician familiarity.
- Oral:Emerging formulations target pediatric and needle-phobic segments, though absorption variability constrains adoption.
Subcutaneous administration commands current volume; oral delivery gains share fastest.
End User:
Procurement authority and reimbursement pathways diverge sharply across institutional and non-institutional channels.
- Hospitals:Academic medical center networks in the United States and Japan unbundle somatostatin analog purchasing from broader oncology contracts, compressing negotiation cycles to quarterly intervals.
- Clinics:Outpatient endocrinology practices favor pre-filled delivery systems that minimize nursing overhead.
- Homecare Settings:Payer pressure across German, Japanese, and US national health systems accelerates patient-administered depot formulations outside hospital walls, representing the steepest expansion trajectory.
- Pharmacies:Retail channels capture oral formulation dispensing as maintenance therapy extends.
Hospitals retain volume concentration; homecare channels climb the fastest.
Indication:
Disease severity and treatment protocol positioning determine formulation selection and dosing frequency.
- Acromegaly:Long-acting somatostatin analog therapy anchors maintenance care, though growth hormone receptor antagonists and radioligand therapies encroach on established protocols.
- Carcinoid Syndrome:First-line symptom control in neuroendocrine tumor management drives high-volume injection demand across United States and European hospital systems.
- VIPoma:Rare pancreatic neuroendocrine tumor indication requires specialized high-dose infusion protocols.
- Other Endocrine Disorders:Off-label and emerging applications in thyroid storm and gastrointestinal bleeding expand addressable use cases.
Carcinoid Syndrome anchors current volume; acromegaly faces substitution pressure while other endocrine disorders gain share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Basel, Boston, and Hyderabad concentrate peptide synthesis infrastructure through tax-advantaged R&D credits and streamlined environmental permitting. These clusters anchor production capacity for long-acting somatostatin analogs.
United States
Academic medical center networks in Boston and New York unbundle somatostatin analog procurement from oncology formularies, compressing price negotiation cycles. FDA bioequivalence guidelines for peptide generics mandate costly immunogenicity profiling. The Boston-Cambridge corridor houses concentrated solid-phase synthesis expertise serving both innovator and complex generic pipelines.
Germany
Hospital procurement consortia accelerate patient-administered depot formulations outside institutional walls to reduce reimbursement costs. REACH Annex XVII restrictions on N-methylpyrrolidone solvents force validation of alternative dissolution chemistries by 2026. The Rhine-Main region around Frankfurt anchors multi-jurisdictional FDA and EMA filing capabilities for peptide manufacturers.
Japan
PMDA regulatory frameworks for complex peptides create predictable approval timelines attracting portfolio investment. National health system reimbursement pilots reward longitudinal efficacy data collection. The Kansai region around Osaka maintains specialized high-dose infusion protocol capabilities for rare neuroendocrine tumor indications.
India
CDSCO tightening for imported APIs elevates compliance burdens while filtering subscale competitors. Streamlined import registration enables faster market entry for complex generic peptide portfolios. Hyderabad's Genome Valley hosts concentrated solid-phase synthesis facilities serving global finished dose manufacturers.
Switzerland
Green chemistry certification commands premium positioning in EMA-regulated markets as manufacturers respond fastest to ECHA enforcement trajectories. Swissmedic regulatory science supports hybrid production lines combining continuous flow and batch synthesis. The Basel region retains deep peptide chemistry expertise among aging specialist cohorts.
Octreotide Market Vendor Landscape
Swiss and German producers anchor the premium formulation tier; Indian and Israeli specialists hold the complex generic and API supply segments. The vendor base separates into three strategic tiers: innovator heritage players with long-acting release portfolios, vertically integrated generic houses controlling peptide supply chains, and mid-scale manufacturers exploiting streamlined regulatory pathways. Dominant competitive moves include backward integration into solid-phase synthesis precursors and geographic expansion through multi-jurisdictional FDA, EMA, and PMDA filings.
Within the innovator heritage tier, Novartis AG exemplifies sustained premium positioning through formulation science depth. Among vertically integrated generic houses, Sun Pharmaceutical Industries Ltd. and Teva Pharmaceutical Industries Ltd. occupy positions emphasizing captive API supply and aggressive emerging market penetration respectively. These three anchors illustrate how competitive advantage in peptide therapeutics depends on regulatory filing breadth and manufacturing control rather than scale alone.
| Leading Market Players |
|---|
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Fresenius Kabi AG |
| Ipsen S.A. |
| Aurobindo Pharma Limited |
| Dr. Reddy's Laboratories Ltd. |
| Hikma Pharmaceuticals PLC |
| Others |
Supply Flow & Price Mechanics
N-methylpyrrolidone solvent price volatility cascades through solid-phase peptide synthesis economics, compressing margins for European manufacturers facing REACH Annex XVII compliance deadlines while amplifying cost differentials between green-certified Swiss facilities and legacy Asian producers.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with validated multi-jurisdictional FDA and EMA filings, commanding premium positioning for abbreviated approval timelines while spot-market peptide API lots trade at discounts reflecting single-source fragility. Three-tier pricing structure across premium, standard, and economy levels separates Swiss green-chemistry-certified innovators from Indian complex generic houses and Chinese commodity API suppliers. Pricing pressure stems from hospital procurement consortia unbundling somatostatin analog purchasing and compressing negotiation cycles. Academic medical center networks exhibit highest price sensitivity due to biosimilar substitution mandates, while rare disease specialty clinics retain lowest sensitivity given limited therapeutic alternatives.
Supply Chain Analysis
EMA MDR and FDA bioequivalence qualification requirements gate entry to regulated markets, filtering subscale contract manufacturers lacking dedicated peptide synthesis infrastructure. Solid-phase peptide synthesis precursors concentrate among Chinese and Indian specialty chemical producers, exposing finished dose manufacturers in Germany, Switzerland, and the United States to single-source API dependencies. Key inputs include protected amino acid derivatives, coupling reagents, and resin supports. Tariff exposure on Chinese specialty chemical imports presents structural vulnerability. Distribution runs through hospital procurement consortia in the United States and Japan, direct tender contracts in Germany, and retail pharmacy networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Octreotide manufacturing economics favor consolidation as REACH compliance costs and immunogenicity profiling burdens force subscale European contract manufacturers toward exit or acquisition.
For Market Incumbents: Hedge against biologic substitution pressure by accelerating real-world evidence contracting with German and Japanese national health systems, while securing captive supply of solid-phase synthesis precursors through backward integration into Hyderabad and Basel production clusters. Growth hormone receptor antagonists and radioligand therapies threaten acromegaly maintenance indications, demanding formulation science investment in long-acting release differentiation. For New Entrants and Emerging Players: CDSCO streamlined import API registration in India opens a window for complex generic peptide portfolios targeting price-sensitive hospital procurement consortia. White-space opportunities concentrate in subcutaneous micro-needle delivery technology for pediatric and needle-phobic segments, and in oral formulation development for homecare migration. A go-to-market angle anchored in green chemistry certification commands premium positioning in EMA-regulated markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale manufacturers with validated multi-jurisdictional filings in the Rhine-Main region around Frankfurt, where REACH-driven facility redevelopment costs exceed standalone viability. Long-term viability over a decade horizon rests on regulatory filing breadth and manufacturing control rather than scale alone. The signal to watch is FDA draft guidance finalization on peptide generic substitution, which would trigger portfolio reallocation between innovator and complex generic pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Certification | REACH Annex XVII compliance secures premium positioning in EMA-regulated German and Swiss markets. |
| Backward Integration into API Synthesis | Captive solid-phase peptide production in Hyderabad reduces dependency on Chinese specialty chemical suppliers. |
| Real-World Evidence Contracting | Outcomes-based reimbursement pilots in German national health systems reward longitudinal efficacy data collection. |
| Subcutaneous Micro-Needle Development | Needle-free delivery technology opens pediatric and needle-phobic adult segments currently underserved. |
| Multi-Jurisdictional Filing Expansion | Simultaneous FDA, EMA, and PMDA submissions accelerate market access across United States, Germany, and Japan. |
Methodological Framework
Document review covered FDA bioequivalence guidance drafts, EMA MDR pathway submissions, CDSCO import registration protocols, and REACH Annex XVII enforcement trajectories, complemented by interviews with regulatory affairs leads at peptide manufacturers, hospital procurement managers at academic medical center networks, formulary directors at German and Japanese national health systems, and solid-phase synthesis chemists in Basel and Hyderabad. Secondary validation drew from SEC 10-K filings of listed pharmaceutical companies, clinical trial registries, and customs trade data on peptide API imports. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Cross-referencing historical somatostatin analog prescription trends against expert panel input on homecare migration velocity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include formulation type, delivery mode, end-user channel, and indication severity. CAGRs derived from weighted average of epidemiological growth in neuroendocrine tumor incidence, protocol expansion rates in hospital-based oncology departments, and payer reimbursement trajectory assumptions. Industry-specific forecast inputs incorporated REACH solvent substitution timelines and PMDA complex peptide approval precedent analysis.
The model assumes a particular technology adoption path for continuous flow peptide synthesis; alternative pathways for hybrid batch-flow manufacturing would alter the outlook through yield consistency and capital efficiency trade-offs. Forecasts reflect assumptions on regulatory timeline predictability, API supply concentration persistence, and biologic substitution encroachment rates. A model refresh is warranted upon material change in FDA draft guidance finalization on peptide generic substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Insulin Secretagogues Market