
 Nucleic Acid Therapeutics CDMO Market | 2026-2036
Nucleic Acid Therapeutics CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Therapeutics CDMO Market Analytics
Buyer concentration among large biotech firms is realigning contract manufacturing priorities toward integrated mRNA and oligonucleotide platforms. Thermo Fisher Scientific leverages its Fisher Scientific distribution network to secure raw material access for nucleic acid synthesis. Lonza Group Ltd anchors European manufacturing capacity with specialized facilities in Switzerland. WuXi AppTec Co. Ltd. competes on cost-adjusted process development for Asian and North American clients.
Nucleic Acid Therapeutics CDMO encompasses outsourced development and manufacturing of mRNA, siRNA, DNA, and oligonucleotide-based therapies, requiring GMP-compliant synthesis with controlled impurity profiles below 0.5% for clinical-grade material. The primary commercial purpose is enabling pharmaceutical innovators to scale gene-modifying therapies without capital-intensive in-house bioprocessing infrastructure. mRNA manufacturing commands the deepest margin pools due to lipid nanoparticle formulation complexity and cold-chain validation requirements. siRNA process development represents the fastest-growing service line as liver-targeted therapies advance through Phase III pipelines. Analytical services remain a mature, high-retention segment where long-term quality agreements lock in recurring revenue.
FDA enforces Chemistry, Manufacturing, and Controls standards that extend nucleic acid batch release timelines, while EMA's ATMP classification creates divergent pathway costs across Atlantic markets. China's NMPA accelerates local trial requirements that reshape where CDMOs validate master cell banks. Switzerland's Swissmedic maintains alignment with EMA standards while offering faster scientific advice meetings for oligonucleotide sponsors. Stakeholders must monitor how regulator convergence on viral vector versus non-viral delivery standards determines platform investment recovery rates.
Market Dynamics
Biotech innovators are consolidating outsourced manufacturing partnerships around integrated mRNA and oligonucleotide platforms, compressing supplier selection cycles from multi-year evaluations to accelerated qualification protocols. This concentration dynamic favors CDMOs with validated lipid nanoparticle formulation capabilities and established cold-chain logistics networks.
Growth Catalysts
- EMA ATMP Classification Pathways:The European regulator's streamlined advanced therapy medicinal product designations accelerate oligonucleotide sponsor timelines, pulling manufacturing demand toward Swiss and German contract facilities.
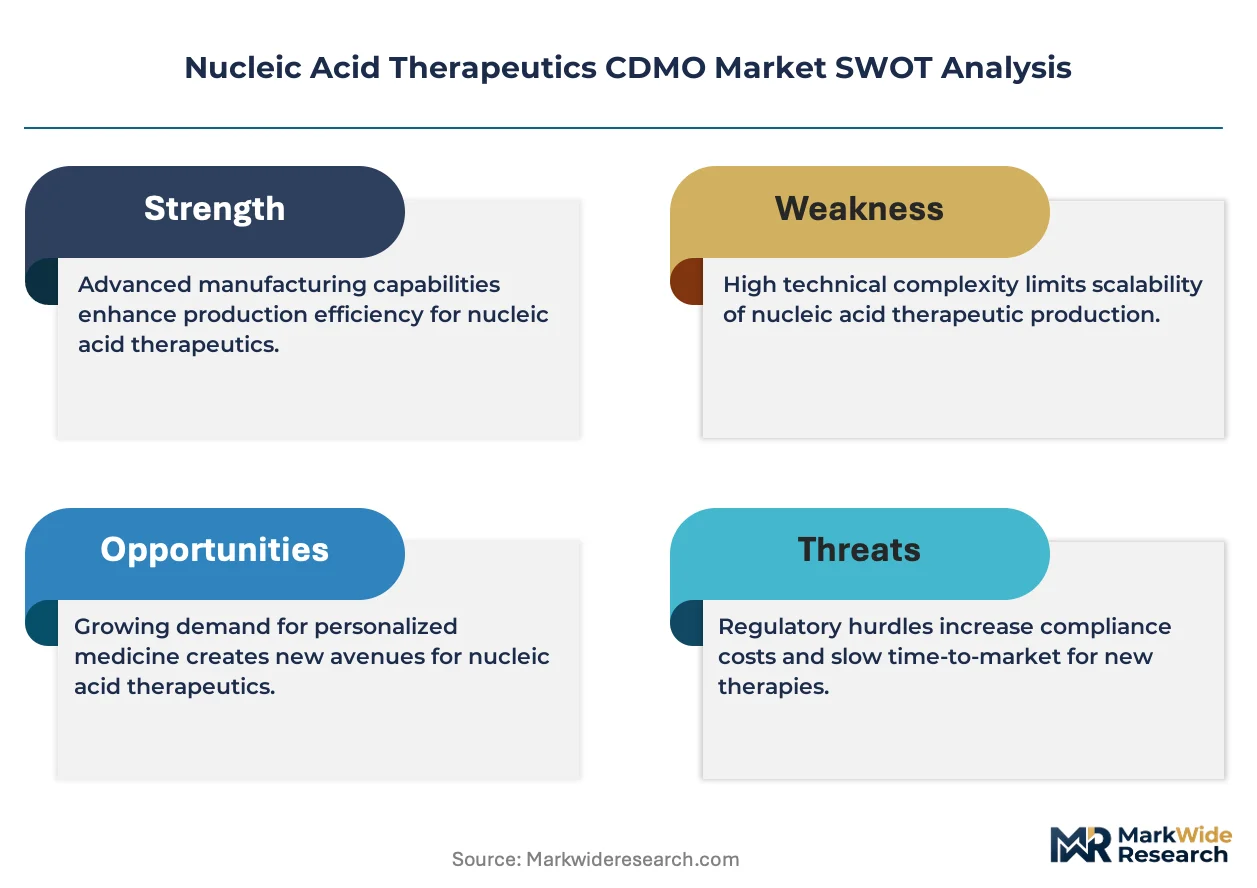
- siRNA Liver-Targeted Pipelines:Phase III progression of hepatocyte-directed small interfering RNA therapies expands process development service contracts for CDMOs with validated GalNAc conjugation expertise.
- China NMPA Local Trial Mandates:China's national medical products administration now requires domestic clinical validation for imported nucleic acid therapies, forcing sponsors to establish Asian manufacturing footprints.
Market Restraints
- Specialized Raw Material Concentration:High-purity phosphoramidite monomers and modified nucleosides depend on a narrow supplier base concentrated in Switzerland and Germany, exposing synthesis schedules to single-source fragility.
- FDA Chemistry Manufacturing Controls Burden:Extended batch release timelines for nucleic acid impurity profiling stretch working capital cycles and compress CDMO margin structures.
- Plasmid DNA Template Scarcity:GMP-grade plasmid production capacity lags mRNA manufacturing expansion, creating upstream bottlenecks for linearized template supply.
Strategic Opportunities
- India CDSCO Emerging Pathway:India's central drugs standard control organization is building nucleic acid regulatory capacity, opening cost-adjusted process development for Western sponsors seeking geographic diversification.
- Continuous Manufacturing Convergence:Integration of flow chemistry with solid-phase synthesis platforms promises yield improvements and reduced solvent waste for oligonucleotide production.
- Japan PMDA Orphan Drug Incentives:Japan's pharmaceutical and medical devices agency offers priority review vouchers for rare disease nucleic acid therapies, attracting sponsor investment and associated manufacturing contracts.
Industry Challenges
- Oligonucleotide Analytical Talent Scarcity:Mass spectrometry specialists capable of validating sub-0.5% impurity specifications command premium compensation, constraining CDMO scale-up velocity.
- Multi-Modal Facility Retrofit Costs:Converting existing biologics suites for nucleic acid GMP compliance requires dedicated HVAC segregation and single-use fluid management systems, demanding capital commitments that strain mid-tier operators.
- Cross-Regulatory Master Cell Bank Harmonization:Divergent FDA, EMA, and NMPA requirements for cell line characterization force redundant testing protocols, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Therapeutics CDMO Market |
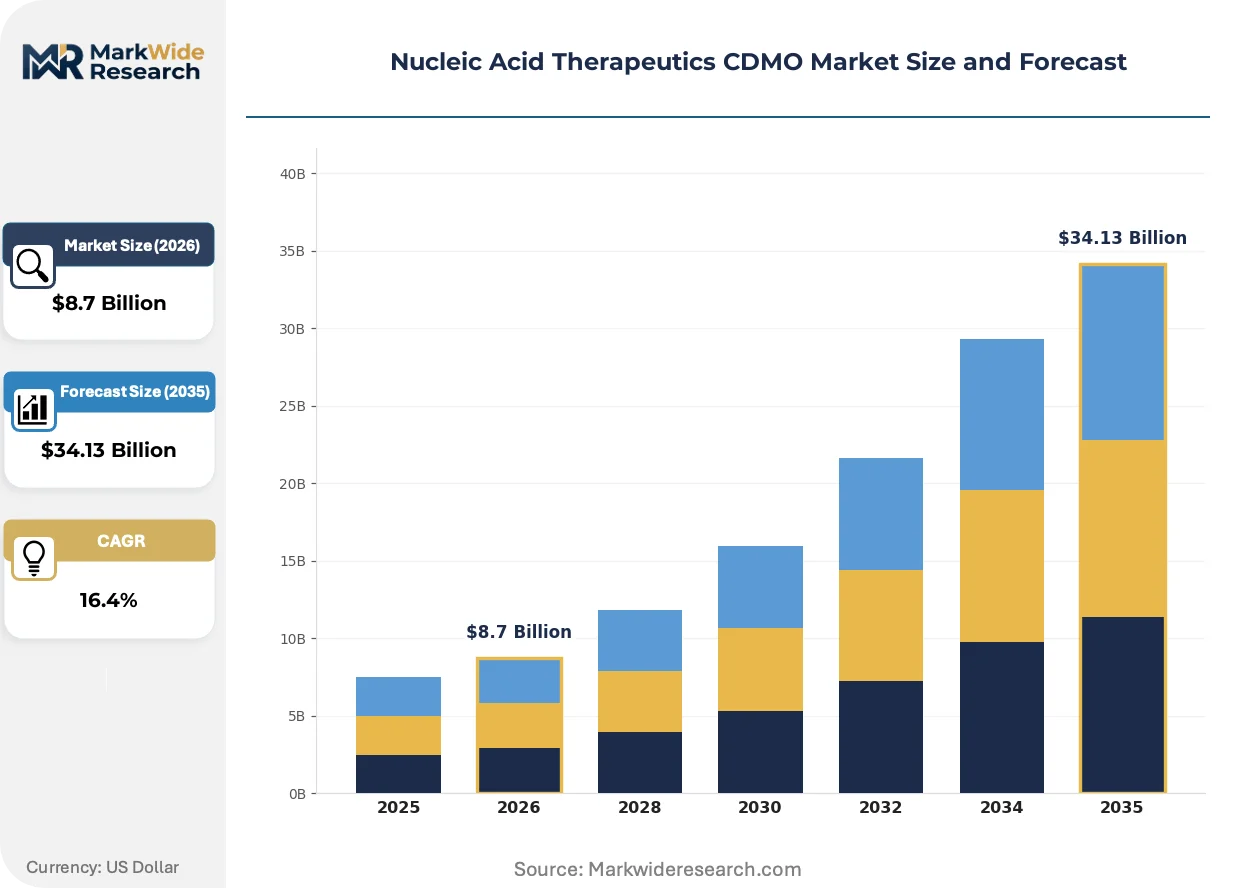
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: mRNA, siRNA, DNA, Oligonucleotides End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Universities Delivery Mode: Liposomes, Nanoparticles, Viral Vectors, Electroporation Service Type: Process Development, Analytical Services, Manufacturing, Quality Control |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza Group Ltd, AGC Biologics Inc., Catalent Inc, Danaher Corporation, Agilent Technologies Inc., Ajinomoto Bio-Pharma Services, WuXi AppTec Co. Ltd., Bachem AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Therapeutics CDMO Market Evolving Landscape
Automation and closed-system processing architectures are compressing nucleic acid manufacturing contamination risks while accelerating batch turnaround. These technological shifts are redrawing competitive boundaries between established biologics CDMOs and specialized nucleic acid entrants.
Continuous flow synthesis technology is integrating solid-phase oligonucleotide production with real-time process analytical technology controls. Mid-size biotech sponsors are adopting these platforms for Phase II material supply, reducing scale-up risks between clinical stages. The technology is integrating quality-by-design principles earlier in development cycles, compressing traditional phase-gate timelines.
FDA's evolving guidance on lipid nanoparticle critical quality attributes is tightening characterization requirements for mRNA drug products. The policy shift demands expanded analytical method validation for particle size distribution and encapsulation efficiency measurements. mRNA-focused CDMOs are responding by building dedicated analytical development groups separate from legacy biologics teams.
Biotech procurement teams are consolidating vendor panels around full-service nucleic acid platforms rather than fragmenting synthesis, formulation, and analytical work. This pattern displaces specialized single-service providers and rewards integrated CDMOs with end-to-end capabilities. The concentration is most visible among US-based gene therapy sponsors with multiple assets in simultaneous development.
Nucleic Acid Therapeutics CDMO Market Segmentation
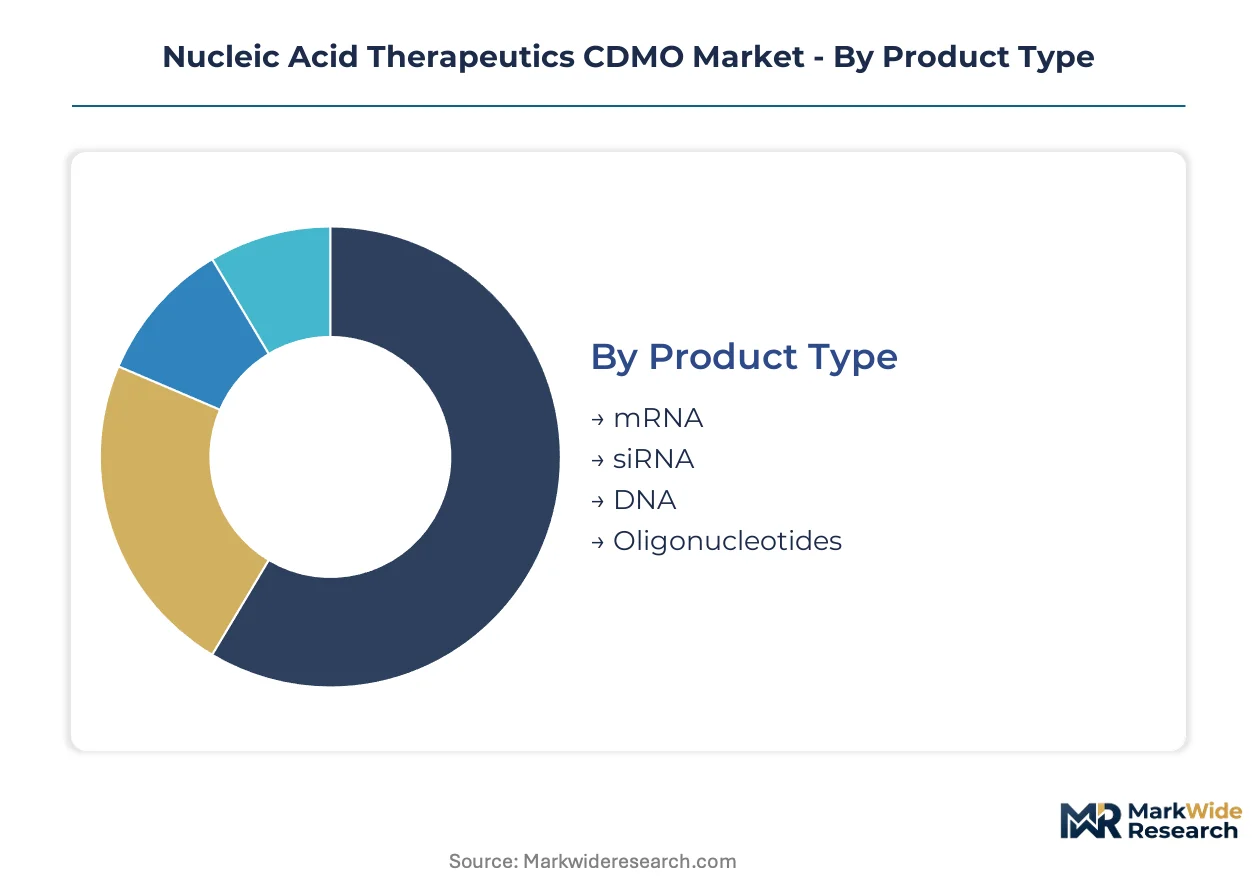
Nucleic acid CDMO segmentation reflects divergent technical capabilities and capital intensity across therapeutic modalities. Contract manufacturers align facility investments with the specific synthesis, formulation, and analytical demands of each product category and service tier.
Product Type:
Supply concentration among specialized raw material vendors shapes competitive positioning across therapeutic platforms.
- mRNA:Synthetic messenger RNA requiring enzymatic in vitro transcription from linearized DNA templates and lipid nanoparticle encapsulation. Demand concentrates in United States-based gene therapy sponsors scaling COVID-19 vaccine-derived manufacturing platforms toward oncology applications; lipid formulation complexity limits qualified supplier pools.
- siRNA:Small interfering RNA molecules chemically synthesized with GalNAc conjugation for hepatocyte targeting. Switzerland and German CDMOs capture liver-directed therapy process development contracts as Alnylam and Arrowhead pipeline assets advance; GalNAc ligand supply tightness constrains batch scheduling.
- DNA:Plasmid and linear DNA constructs serving as therapeutic agents or mRNA manufacturing templates. United States sponsors dominate GMP-grade plasmid demand for gene therapy and vaccine applications.
- Oligonucleotides:Antisense, aptamer, and splice-switching chemistries manufactured through solid-phase synthesis. European sponsors favor Swiss and German facilities for EMA-aligned impurity profiling.
Today's leader: mRNA. Tomorrow's challenger: siRNA.
End User:
Procurement scale and technical sophistication determine CDMO engagement models and contract structures.
- Pharmaceutical Companies:Large-cap sponsors with multi-asset nucleic acid pipelines. These buyers consolidate manufacturing partnerships around integrated platforms, demanding end-to-end capabilities from process development through commercial supply.
- Biotech Firms:Venture-backed innovators representing the fastest-expanding demand segment. United States and China-based biotechs compress supplier qualification timelines, prioritizing CDMOs with established IND-enabling track records and accelerated CMC packages.
- Research Institutions:Academic medical centers and government laboratories requiring preclinical-grade material. Contracts emphasize flexible batch scales and permissive intellectual property terms over GMP compliance.
- Universities:Early-stage discovery programs sourcing small-scale synthesis for target validation. Price sensitivity dominates vendor selection, with preference for domestic suppliers to simplify material transfer agreements.
Pharmaceutical companies anchor current revenue. Biotech firms drive capacity expansion decisions.
Delivery Mode:
Formulation complexity creates tiered margin structures and specialized facility requirements.
- Liposomes:Phospholipid vesicle systems for nucleic acid encapsulation. Mature technology with established manufacturing protocols; demand concentrates in European oncology sponsors.
- Nanoparticles:Lipid nanoparticles and polymer-based systems dominating mRNA and siRNA delivery. United States CDMOs with validated microfluidic mixing platforms capture premium pricing; FDA critical quality attribute guidance tightens characterization burdens.
- Viral Vectors:Adeno-associated and lentiviral systems for DNA delivery. Capacity constraints persist despite manufacturing scale-up; plasmid supply bottlenecks extend lead times.
- Electroporation:Physical delivery method for ex vivo cell modification. Emerging demand from cell therapy sponsors in Switzerland and United States; equipment-intensive process favors CDMOs with dedicated electroporation suites.
Nanoparticles command premium positioning. Electroporation gains sponsor attention for cell therapy integration.
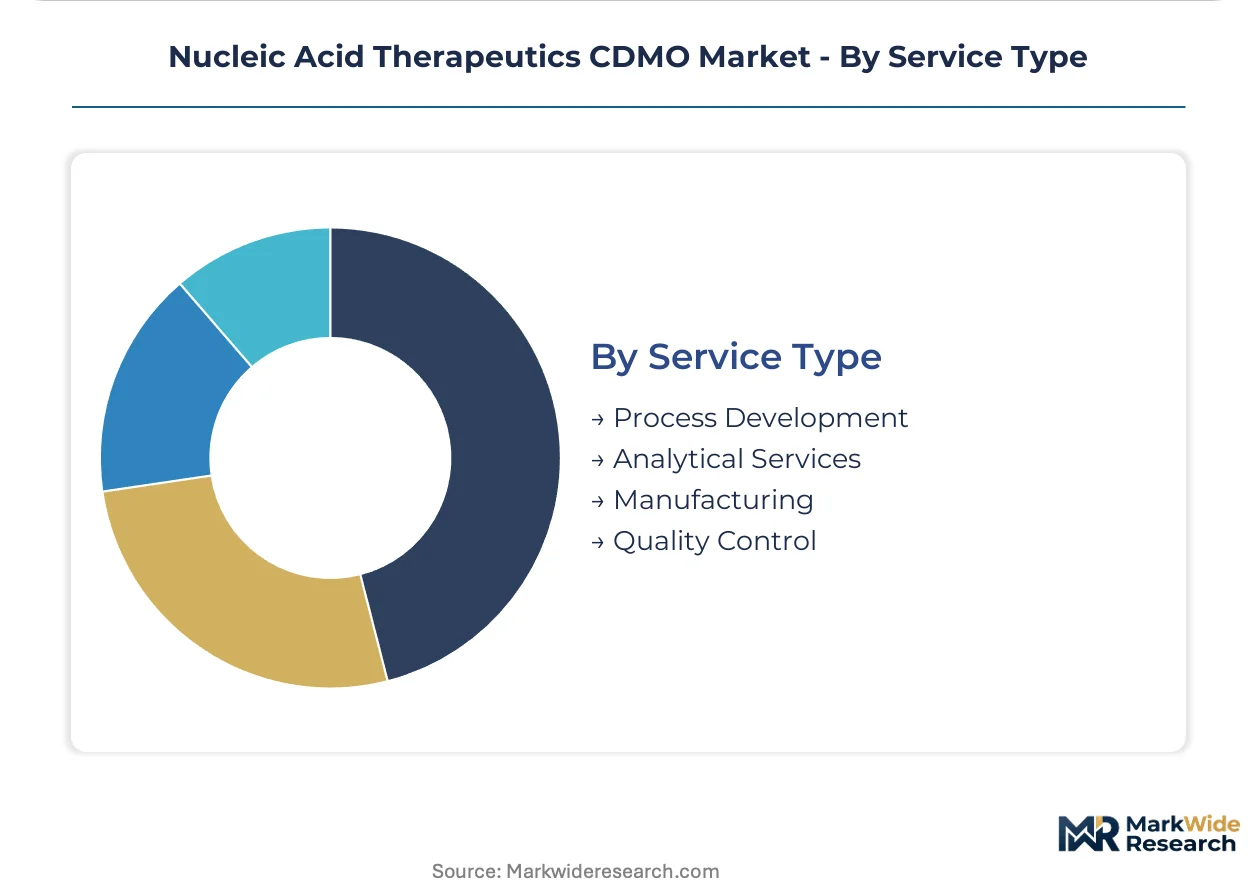
Service Type:
Margin retention and contract duration vary across the development-to-commercial continuum.
- Process Development:Route scouting, optimization, and scale-up validation for clinical manufacturing. China-based CDMOs compete on cost-adjusted development timelines for Western sponsors seeking geographic diversification.
- Analytical Services:Method development, validation, and release testing for nucleic acid quality attributes. High retention segment where long-term quality agreements lock in recurring revenue; mass spectrometry expertise scarcity constrains capacity expansion.
- Manufacturing:GMP production of clinical and commercial drug substance and drug product. Switzerland and United States facilities anchor supply for Atlantic markets; China NMPA local trial mandates pull investment toward Asian capacity.
- Quality Control:In-process testing, stability studies, and regulatory documentation. Integrated CDMOs bundle QC with manufacturing to capture full-service contracts; standalone providers face procurement consolidation pressure.
Manufacturing generates volume concentration. Analytical services defend margin stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA local trial mandates pull manufacturing investment eastward while Switzerland's Swissmedic alignment with EMA standards anchors Atlantic market supply. Facility location decisions increasingly hinge on regulatory pathway convergence rather than labor cost arbitrage alone.
United States
Gene therapy sponsors in Massachusetts and California compress supplier qualification timelines for mRNA manufacturing partnerships. FDA Chemistry Manufacturing and Controls standards extend nucleic acid batch release timelines, tightening working capital requirements for CDMO operators. The Greater Boston cluster concentrates lipid nanoparticle formulation expertise as COVID-19 vaccine platforms pivot toward oncology applications.
Switzerland
Swissmedic offers faster scientific advice meetings for oligonucleotide sponsors than EMA central procedures, attracting Phase III pipeline manufacturing contracts. The country's specialized facilities anchor European capacity for liver-targeted siRNA therapies requiring GalNAc conjugation validation. Basel and Zurich host concentrated phosphoramidite monomer supplier networks that reduce synthesis schedule fragility.
Germany
EMA ATMP classification pathways accelerate oligonucleotide sponsor timelines, pulling process development demand toward German contract facilities. The country's national pharmaceutical regulator enforces REACH-aligned impurity profiling standards for clinical-grade material. Munich and Heidelberg clusters specialize in solid-phase synthesis platforms for antisense and splice-switching chemistries.
China
NMPA domestic clinical validation requirements for imported nucleic acid therapies force sponsors to establish Asian manufacturing footprints. The regulator accelerates local trial mandates that reshape where CDMOs validate master cell banks. Shanghai and Suzhou concentrate cost-adjusted process development capacity serving Western biotechs seeking geographic diversification.
India
CDSCO is building nucleic acid regulatory capacity, opening cost-adjusted process development for Western sponsors. The country's central drugs standard control organization develops inspector training programs for GMP compliance assessment. Hyderabad and Bangalore clusters attract analytical method validation contracts as mass spectrometry talent scarcity constrains capacity expansion elsewhere.
Nucleic Acid Therapeutics CDMO Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across nucleic acid CDMO service tiers. The market structure concentrates around integrated platform providers capable of end-to-end mRNA and oligonucleotide manufacturing. Three archetypes dominate: full-service life science conglomerates with distribution networks, European specialists with EMA-aligned quality systems, and Asian cost-optimized process developers. Competitive moves center on capacity expansion for lipid nanoparticle formulation and strategic partnerships securing phosphoramidite monomer supply.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. occupies a position exemplifying raw material access advantages through captive distribution networks. Lonza Group Ltd represents the European specialist archetype with Swiss-based GMP facilities aligned to EMA standards. WuXi AppTec Co. Ltd. anchors the Asian cost-optimized tier, serving North American and European sponsors with accelerated CMC packages. These three companies illustrate how geographic positioning and regulatory alignment shape competitive differentiation rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza Group Ltd |
| AGC Biologics Inc. |
| Catalent Inc |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Ajinomoto Bio-Pharma Services |
| WuXi AppTec Co. Ltd. |
| Bachem AG |
| Others |
Value Network & Pricing Analysis
Phosphoramidite monomer costs flow from Swiss and German chemical suppliers through three-tier pricing structures separating GMP-grade clinical material from preclinical and research-grade tiers, with lipid nanoparticle formulation premiums reflecting raw material scarcity and cold-chain validation overhead.
Pricing Analysis
Capacity additions in China are reshaping price floors for process development services while compressing Western CDMO margins on early-stage contracts. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified commercial manufacturing from clinical-grade production and preclinical material, with FDA Chemistry Manufacturing and Controls compliance costs driving premium tier differentiation. Pricing pressure stems from sponsor procurement consolidation around integrated platforms. Biotech firms exhibit highest price sensitivity, prioritizing accelerated CMC timelines over quality tier premiums.
Supply Chain Analysis
Single-source vulnerability sits with high-purity phosphoramidite monomer and modified nucleoside suppliers concentrated in Switzerland and Germany. Raw material sourcing draws from Swiss chemical manufacturers, German specialty chemical producers, and emerging Indian API suppliers, with GMP-grade plasmid DNA templates feeding from United States production facilities. Tariff exposure on Chinese-sourced process development services represents the dominant structural risk. Distribution runs through sponsor-direct contracting models with long-term quality agreements locking in analytical service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nucleic acid therapeutics CDMO market functions as a stable compounder, with biotech pipeline expansion driving sustained manufacturing demand across therapeutic modalities.
For Market Incumbents: Lock in long-term phosphoramidite supply agreements to defend against single-source fragility threatening batch scheduling reliability. Anchor European market position through Swissmedic-aligned quality systems that accelerate oligonucleotide sponsor scientific advice timelines. Expand lipid nanoparticle formulation capacity in United States clusters where gene therapy sponsors concentrate multi-asset partnerships. For New Entrants and Emerging Players: Capture India CDSCO regulatory capacity building as Western sponsors seek geographic diversification away from China NMPA uncertainty. Target analytical services white space where mass spectrometry talent scarcity constrains incumbent scale-up velocity. Pursue GalNAc conjugation expertise as the entry wedge for liver-targeted siRNA process development contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier CDMOs lack capital for multi-modal facility retrofit costs and integrated platform investments. Five-to-ten year viability favors full-service providers with validated mRNA and oligonucleotide capabilities spanning process development through commercial supply. Watch FDA guidance convergence on lipid nanoparticle critical quality attributes as the signal for platform investment recovery rate inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphoramidite Supply Agreement | Secures raw material access from Swiss and German chemical suppliers against single-source fragility. |
| Lipid Nanoparticle Capacity Expansion | Captures premium pricing from United States gene therapy sponsors scaling oncology applications. |
| GalNAc Conjugation Expertise Development | Positions for liver-targeted siRNA process development as Alnylam and Arrowhead pipelines advance. |
| Swissmedic Scientific Advice Alignment | Accelerates oligonucleotide sponsor timelines versus EMA central procedures. |
| India CDSCO Regulatory Capacity Investment | Opens cost-adjusted process development for Western sponsors seeking geographic diversification. |
Research Methodology
Direct dialogue with CDMO operations directors, regulatory affairs leads at nucleic acid sponsors, biotech procurement managers, and analytical development scientists grounds qualitative findings in operational reality. Secondary validation draws from FDA Chemistry Manufacturing and Controls guidance documents, EMA ATMP classification pathways, NMPA local trial mandate filings, and Swissmedic scientific advice procedural data. Bottom-up capacity modeling and top-down demand projection triangulate market sizing across the analysis window.
Bottom-up modeling aggregates individual CDMO facility capacity, utilization rates, and service mix assumptions, while top-down analysis calibrates against sponsor pipeline progression and regulatory submission volumes. Segmentation dimensions span therapeutic modality, service tier, delivery mode complexity, and regional regulatory cluster. CAGRs derive from sponsor manufacturing outsourcing rate trajectories and capacity expansion announcement velocities. Forecast inputs incorporate lipid nanoparticle formulation demand curves and siRNA GalNAc conjugation service line growth.
Regulatory guidance divergence, phosphoramidite supply disruption, and sponsor insolvency waves are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about pipeline progression rates and outsourcing penetration ceilings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market