
 Plant Genotyping Equipment Market | 2026-2036
Plant Genotyping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Genotyping Equipment Market Intelligence
High-throughput sequencing integration is tilting plant genotyping from discrete marker assays toward continuous genomic prediction pipelines. Illumina Inc. leverages its installed base of sequencing platforms to anchor recurring consumable revenue across major agricultural research institutions. Thermo Fisher Scientific Inc. competes through verticalized qPCR-to-NGS workflows that reduce sample-handling friction for seed companies. QIAGEN N.V. differentiates with automated nucleic acid extraction systems that feed directly into downstream genotyping instruments.
Plant genotyping equipment comprises instruments, reagents, and software systems that detect genetic polymorphisms—typically single nucleotide polymorphisms (SNPs) or insertion-deletion variants—at throughputs ranging from tens to millions of loci per run, serving breeders and researchers who select parents or validate edits. Sequencing platforms now capture the largest share of capital expenditure as replacement cycles favor higher-density output per run, while CRISPR technology represents the fastest-growing segment because edited lines require rapid, cost-effective confirmation of on-target and off-target events. Genotyping kits retain durable margin pools due to per-sample consumable pull-through tied to expanding breeding program volumes.
The USDA Animal and Plant Health Inspection Service governs movement of genetically engineered plants, while the EPA registers pesticidal plant-incorporated protectants, both shaping which traits justify genotyping investment; ISO 17025 accreditation requirements for commercial testing laboratories further standardize instrument validation protocols. The EU Green Deal and its Farm to Fork strategy accelerate genomic selection adoption in European breeding programs by linking sustainability metrics to variety registration. Stakeholders must monitor how divergent transgenic regulation between the United States and European Union redirects R&D investment toward cisgenic and gene-edited approaches that demand different genotyping architectures.
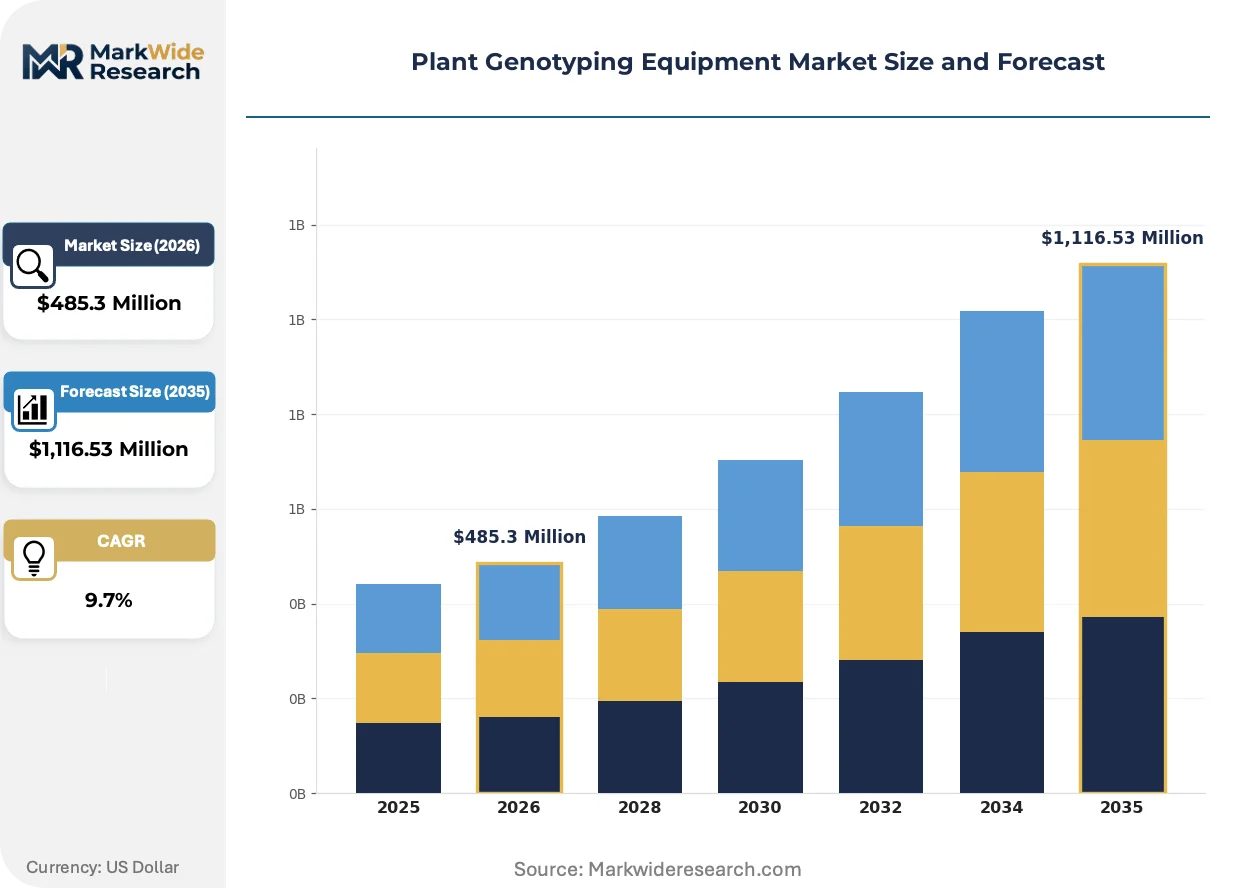
Market Dynamics
CRISPR-based trait validation workflows are compressing development cycles and forcing seed companies to rebuild their genotyping infrastructure around continuous genomic prediction rather than discrete marker assays.
Growth Catalysts
- USDA-coordinated germplasm networks:Federally backed seed repositories in the United States accelerate instrument procurement by standardizing genetic reference panels across public breeding programs.
- EU Green Deal sustainability metrics:The Farm to Fork strategy links variety registration to environmental performance, compelling European breeders to adopt genomic selection for faster trait stacking.
- Marker-assisted selection protocols:Seed companies replace phenotypic screening with DNA-based parent selection, driving consumable pull-through for high-density SNP arrays.
Market Restraints
- Capital intensity of sequencing platforms:Replacement cycles toward higher-density output per run demand substantial upfront investment from mid-sized breeding programs.
- Consumable cost volatility:Reagent pricing tied to oligonucleotide synthesis inputs creates margin pressure for high-throughput operations running thousands of samples monthly.
- Divergent transgenic regulation:The gap between United States and European Union approval pathways forces dual validation workflows that duplicate genotyping expenditure.
Strategic Opportunities
- Gene-edited crop pipelines:Cisgenic approaches that bypass transgenic classification in the European Union create demand for off-target detection architectures distinct from conventional GMO screening.
- Automated nucleic acid extraction:Integration of sample prep robotics with downstream instruments reduces handling friction for seed company labs scaling to industrial throughputs.
- Venture-backed agbiotech clusters:Startup density in research corridors like Research Triangle Park and St. Louis generates concentrated instrument demand from pre-commercial breeding operations.
Industry Challenges
- Bioinformatics talent scarcity:Breeding programs lack personnel capable of interpreting genomic prediction outputs, creating bottlenecks between data generation and selection decisions.
- ISO 17025 accreditation timelines:Commercial testing laboratories face extended validation protocols for instrument qualification, delaying service revenue recognition.
- Legacy LIMS integration:Seed company IT infrastructure built around phenotypic data models requires costly reconfiguration to ingest continuous genomic streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Genotyping Equipment Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,116.53 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Sequencing Platforms, Genotyping Kits, PCR Instruments Technology: Next-Generation Sequencing, SNP Genotyping, Microarray Analysis, CRISPR Technology End User: Agricultural Research Institutions, Seed Companies, Biotechnology Firms, Academic Research Application: Crop Improvement, Disease Resistance, Trait Mapping, Genomic Selection |
| Companies Covered | Agilent Technologies Inc., PerkinElmer Inc., Illumina Inc., Oxford Nanopore Technologies Limited, QIAGEN N.V., Thermo Fisher Scientific Inc., Merck KGaA, Eurofins Scientific, BGI Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Genotyping Equipment Market Strategic Shifts & Innovations
Instrumentation architectures are pivoting from discrete genotyping assays toward integrated genomic prediction pipelines that compress breeding timelines and reshape competitive positioning among platform vendors.
High-throughput sequencing is migrating from targeted SNP panels toward whole-genome prediction models in North American maize and soybean programs. Large-scale seed companies now sequence thousands of lines per season to train genomic selection algorithms. This migration from marker-assisted selection to direct genomic prediction collapses the distinction between genotyping and breeding decision support.
The EU Green Deal's Farm to Fork strategy is accelerating regulatory acceptance of gene-edited varieties with reduced pesticide footprints. European breeding programs are responding by redirecting R&D investment toward CRISPR-based trait stacks that require rapid on-target confirmation. This policy shift favors genotyping architectures optimized for edited line validation over conventional transgenic event screening.
Service unbundling is fragmenting the traditional instrument-reagent-software bundle as seed companies seek specialized bioinformatics support. Third-party analytics providers now contract directly with breeding programs to interpret sequencing output, displacing vendor-captive analysis packages. This channel shift is most visible in United States contract research organizations serving mid-sized seed companies lacking in-house computational biology capacity.
Plant Genotyping Equipment Market Segmentation
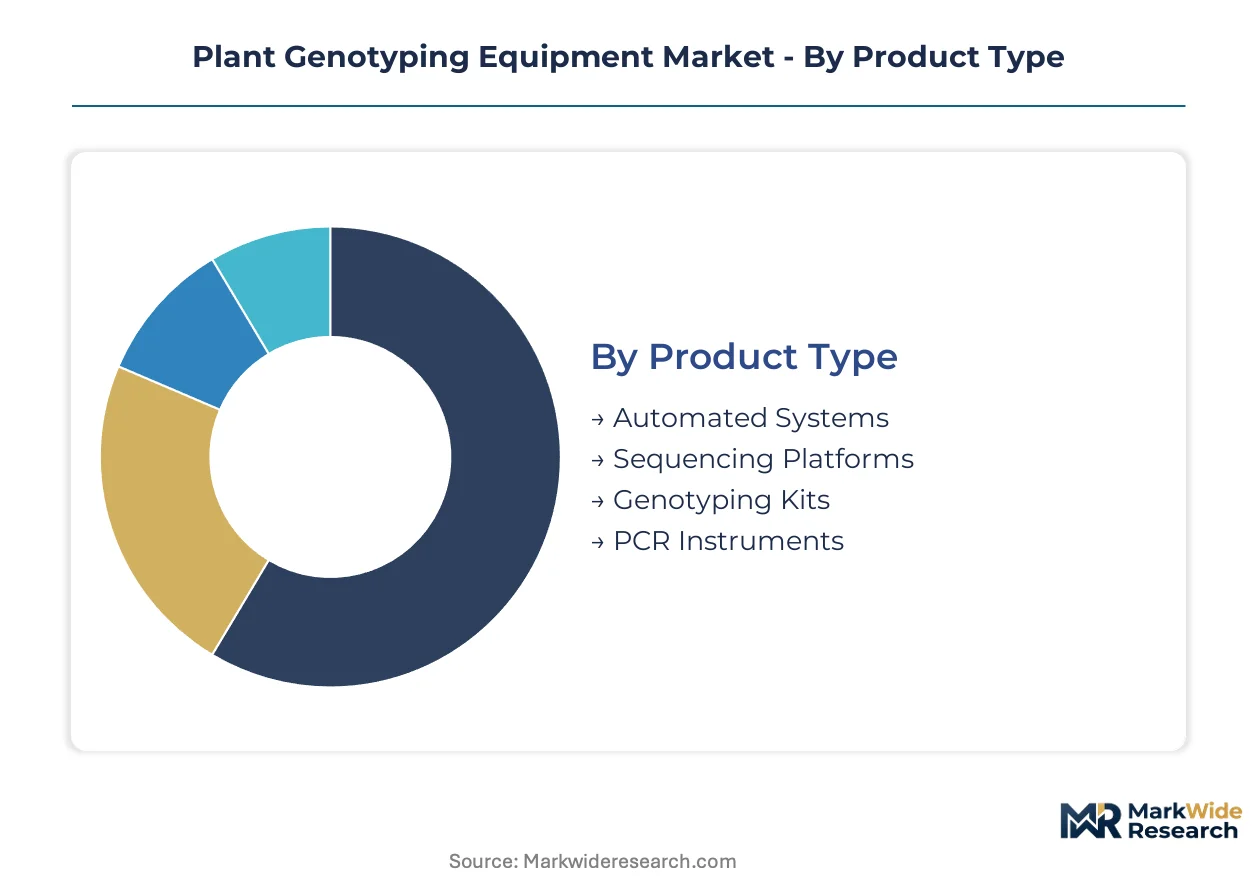
Segmentation reveals how capital deployment, consumable pull-through, and service intensity vary across equipment categories. Breeders allocate budgets differently between high-throughput platforms and discrete assays depending on program scale and trait validation urgency.
Product Type:
After-sales-service intensity varies sharply across product categories, with sequencing platforms demanding multi-year service contracts while kits generate minimal recurring support revenue.
- Sequencing Platforms:High-capacity instruments from Illumina and Thermo Fisher anchor capital budgets through multi-year service agreements and firmware upgrades. Demand concentrates at USDA-coordinated germplasm repositories and venture-backed agbiotech clusters in Research Triangle Park and St. Louis where continuous genomic prediction pipelines require maximum uptime guarantees.
- Automated Systems:Robotic nucleic acid extraction and liquid handling units from QIAGEN reduce sample-handling friction for seed companies scaling to industrial throughputs. European breeding programs under EU Green Deal sustainability mandates purchase these systems to compress genomic selection timelines and meet variety registration deadlines.
- Genotyping Kits:Per-sample consumables tied to expanding breeding program volumes generate durable margin pools through recurring reagent pull-through.
- PCR Instruments:Benchtop thermal cyclers serve mid-sized breeding operations and academic laboratories with lower capital intensity than sequencing platforms.
Sequencing platforms hold the largest share; momentum sits with automated systems.
Technology:
Technology selection determines whether breeding programs operate discrete marker assays or continuous genomic prediction pipelines.
- Next-Generation Sequencing:Whole-genome prediction models now dominate North American maize and soybean programs where large-scale seed companies sequence thousands of lines per season. USDA-backed germplasm networks standardize reference panels that accelerate algorithm training and selection accuracy.
- CRISPR Technology:On-target and off-target validation workflows compress development cycles as seed companies replace conventional breeding timelines with edited line confirmation. European programs under divergent transgenic regulation invest heavily here to bypass GMO classification hurdles.
- SNP Genotyping:Targeted single nucleotide polymorphism assays retain relevance for parent selection in programs not yet migrated to whole-genome approaches.
- Microarray Analysis:Fixed-content SNP arrays serve standardized screening applications where probe design costs amortize across high sample volumes.
Next-generation sequencing commands dominant investment; CRISPR technology is climbing the fastest.
End User:
End-user type shapes procurement patterns from capital-intensive platform purchases to consumable-driven recurring revenue.
- Seed Companies:Marker-assisted selection protocols now replace phenotypic screening across multinational breeding operations. These firms drive the steepest expansion trajectory through compressed development cycles and industrial-scale sample volumes that maximize instrument utilization rates.
- Agricultural Research Institutions:USDA-coordinated networks and European public breeding programs standardize genetic reference panels that anchor instrument procurement decisions across multiple satellite laboratories.
- Biotechnology Firms:Venture-backed agbiotech startups in United States research corridors generate concentrated demand for pre-commercial breeding operations and trait validation services.
- Academic Research:University laboratories purchase lower-throughput instruments for fundamental genetics research with less urgent breeding timeline pressure.
Seed companies hold the largest share; biotechnology firms are gaining share fastest.
Application:
Application focus determines whether genotyping infrastructure serves upstream research or downstream variety development.
- Genomic Selection:Continuous prediction pipelines collapse the distinction between genotyping and breeding decision support. Large-scale programs now sequence directly for selection rather than running discrete marker assays, compressing generational intervals.
- Crop Improvement:Yield and quality trait stacking drives consumable volumes across both public and private breeding programs with well-established genomic selection infrastructure.
- Trait Mapping:Quantitative trait locus discovery applications serve research-intensive institutions mapping novel genetic variation for future breeding targets.
- Disease Resistance:Pathogen resistance screening maintains steady demand for targeted genotyping panels in regions with high biotic pressure.
Genomic selection holds the largest share; crop improvement shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seed companies concentrate procurement in the United States, Germany, and China, where federal germplasm networks and venture capital corridors generate the densest instrument demand. Public breeding programs in Brazil and India are accelerating adoption as national agricultural strategies prioritize genomic selection timelines.
United States
USDA-coordinated germplasm repositories standardize genetic reference panels across public breeding programs. The EPA registers pesticidal plant-incorporated protectants, shaping which traits justify downstream genotyping investment. Research Triangle Park and St. Louis anchor venture-backed agbiotech clusters where pre-commercial breeding operations drive concentrated instrument procurement.
Germany
European breeding programs under the EU Green Deal redirect R&D toward gene-edited varieties with reduced pesticide footprints. EFSA guidelines on novel food assessments influence validation workflow design for edited line confirmation. The Munich and Cologne regions host precision agriculture technology clusters where automated nucleic acid extraction systems feed into downstream genotyping pipelines.
China
State-backed agricultural modernization programs expand genomic selection infrastructure for rice and wheat improvement. The Ministry of Agriculture and Rural Affairs coordinates national germplasm banks that standardize instrument procurement across provincial breeding stations. Yangtze River Delta research corridors concentrate demand for high-throughput sequencing platforms serving both state enterprises and private seed firms.
Brazil
Large-scale soybean and maize breeding operations drive consumable pull-through for SNP genotyping panels. ANVISA regulatory pathways for genetically modified organisms shape dual validation workflows that duplicate genotyping expenditure. São Paulo state anchors multinational seed company R&D facilities where marker-assisted selection protocols replace phenotypic screening.
India
ICAR-coordinated network projects expand marker-assisted breeding infrastructure for drought-tolerant variety development. FSSAI guidelines on genetically modified food labeling influence trait validation priorities for export-oriented crops. Hyderabad and Pune research clusters concentrate demand for mid-throughput PCR instruments serving both public institutions and emerging private seed firms.
Plant Genotyping Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where sequencing platform vendors anchor capital budgets through multi-year service agreements. The market consolidates around three strategic archetypes: integrated life science conglomerates with sequencing-to-sample-prep workflows, dedicated genomics platform specialists with installed-base leverage, and regional automation providers with nucleic acid extraction expertise. Dominant competitive moves include portfolio diversification into gene-editing validation architectures and strategic partnerships with seed company breeding programs to embed consumable pull-through.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Illumina Inc. exemplify channel-controlling positions through verticalized instrument-reagent-software bundles. QIAGEN N.V. occupies a distinct automation-specialist position, while Eurofins Scientific represents the contract research organization archetype that unbundles traditional vendor-captive analytics. These three anchors collectively illustrate how competitive positioning stratifies between platform scale, consumable lock-in, and service unbundling strategies.
| Leading Market Players |
|---|
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Illumina Inc. |
| Oxford Nanopore Technologies Limited |
| QIAGEN N.V. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Eurofins Scientific |
| BGI Genomics |
| Others |
Cost & Logistics Intelligence
Oligonucleotide synthesis capacity concentrates in South Korea and the United States, tethering consumable pricing power to a handful of contract manufacturers that supply reagent kits to seed company breeding programs. This upstream concentration compresses margins for mid-sized instrument vendors while amplifying pull-through revenue for integrated platform providers with captive consumable lines.
Pricing Analysis
Cost-plus contracts with oligonucleotide price indexation dominate high-volume reagent procurement, insulating large seed companies from spot volatility while exposing smaller laboratories to margin erosion. Three-tier pricing structure across premium, standard, and economy levels separates full-service sequencing platforms from benchtop PCR units and basic genotyping kits. Pricing pressure stems from seed company consolidation demanding volume discounts on consumable bundles. Academic research institutions exhibit highest price sensitivity, whereas multinational breeding operations prioritize uptime guarantees over per-sample costs.
Supply Chain Analysis
Upstream feedstock for sequencing flowcells and microarray substrates draws from precision glass manufacturing clusters in Germany and Japan, with specialized polymer chemistries sourced from Swiss and Dutch specialty chemical producers. Critical dependencies include synthetic oligonucleotides, fluorescence-labeled nucleotides, and high-purity reagent-grade solvents. Single-source vulnerability concentrates in flowcell production, where proprietary surface chemistry patents limit qualified suppliers. Distribution runs through direct field service organizations for capital equipment, while consumables flow via authorized distributors with cold-chain logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with the unbundling of bioinformatics services from instrument-reagent bundles, as seed companies lacking computational biology capacity seek specialized analytics partners. This demand-side shift creates niche entry points for contract research organizations and software specialists outside traditional vendor ecosystems.
For Market Incumbents: Harden consumable lock-in through multi-year service agreements that embed firmware-controlled reagent authentication, blocking third-party assay compatibility. Deepen backward integration into oligonucleotide synthesis to secure supply continuity against South Korean contract manufacturing bottlenecks. Priority lever centers on acquiring gene-editing validation software specialists before platform-agnostic entrants capture CRISPR workflow market share.
For New Entrants and Emerging Players: Build out automated nucleic acid extraction systems optimized for seed company industrial throughputs, where QIAGEN's installed base leaves room for price-competitive displacement. Most penetrable segment sits with mid-sized European breeding programs under EU Green Deal sustainability mandates seeking compressed genomic selection timelines. Go-to-market angle emphasizes ISO 17025 accreditation support bundled with instrument qualification protocols.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture technology clusters in Research Triangle Park and St. Louis, where venture-backed agbiotech startups have matured toward commercial breeding scale. Long-term viability framing favors genomic prediction platform providers over discrete assay vendors as breeding programs migrate from marker-assisted selection to continuous pipelines. Signal to watch is USDA germplasm network procurement standardization, which will concentrate instrument vendor selection around qualified platform providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Validation Partnership | Aligns CRISPR workflow capabilities with EFSA guidelines on novel food assessments for European market access. |
| Consumable Authentication Technology | Embeds firmware-controlled reagent lock-in that blocks third-party assay compatibility and secures recurring revenue. |
| Automated Sample Prep Integration | Reduces handling friction for seed companies scaling to industrial throughputs under compressed breeding timelines. |
| Bioinformatics Service Unbundling | Captures demand from mid-sized breeding programs lacking in-house computational biology capacity. |
| ISO 17025 Accreditation Support | Accelerates commercial testing laboratory instrument qualification timelines and delays competitor service revenue recognition. |
Research Approach
A standing panel of breeding program directors, agricultural research institution procurement officers, agbiotech startup founders, and reagent manufacturing supply chain managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against USDA germplasm network procurement records, EPA pesticidal plant-incorporated protectant registrations, EU Green Deal implementation documents, and instrument vendor SEC filings. Bottom-up triangulation across seed company capital expenditure disclosures and top-down reconciliation against national agricultural modernization program budgets anchored volume estimates.
Scenario-bracketing framed projections across the analysis window, with optimistic and conservative cases reflecting divergent regulatory acceptance timelines for gene-edited varieties in the European Union. Segmentation dimensions modeled include product type, technology platform, end-user category, and application focus, with additional stratification by breeding program scale and genomic selection maturity. CAGRs derived from instrument replacement cycle analysis, consumable pull-through coefficients, and breeding program expansion rates. Industry-specific inputs incorporated CRISPR validation workflow adoption curves and EU Farm to Fork sustainability metric implementation schedules.
Practitioners should monitor EPA registration pathway shifts for plant-incorporated protectants and EFSA novel food assessment guideline revisions for early signals of forecast deviation. Cross-checking against USDA Agricultural Research Service equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Cell Culture Protein Surface Coating Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market