
 Phenylketonuria (PKU) Market | 2026-2036
Phenylketonuria (PKU) Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylketonuria (PKU) Market Outlook
Specialist clinic procurement networks are rewriting how enzyme replacement therapies reach pediatric patients. BioMarin Pharmaceutical leverages its manufacturing scale to anchor supply contracts with major metabolic centers across North America and Europe. Ultragenyx Pharmaceutical competes through deep specialization in rare disease infrastructure, while Codexis differentiates via engineered enzyme platforms that extend therapeutic half-life.
Phenylketonuria is an autosomal recessive metabolic disorder caused by phenylalanine hydroxylase deficiency, resulting in toxic accumulation of phenylalanine that requires lifelong dietary protein restriction and synthetic amino acid supplementation. Medical foods dominate current revenue pools due to chronic consumption requirements, though gene therapy represents the fastest-growing segment as clinical programs advance toward regulatory submission. Enzyme replacement occupies a mature position with established reimbursement pathways, while nutritional supplements capture margin in home care settings where patient compliance drives repeat purchasing.
FDA orphan drug designations and EMA priority medicines frameworks accelerate PKU therapy development timelines and shape market access negotiations. The EU F-Gas Regulation and REACH chemical standards constrain manufacturing inputs for certain synthetic enzyme processes, directing capital toward greener production methods. Stakeholders must monitor regulatory divergence between FDA gene therapy guidance and EMA advanced therapy medicinal product standards when structuring pivotal trial designs.
Market Dynamics
Gene therapy clinical pipelines are compressing the addressable patient pool for chronic medical foods by targeting curative outcomes, forcing incumbent nutritional suppliers to defend lifetime value propositions against one-time intervention models.
Growth Catalysts
- EMA Priority Medicines Framework:Accelerated assessment pathways for advanced therapy medicinal products compress development timelines for gene therapy candidates targeting phenylalanine hydroxylase deficiency.
- Engineered enzyme platforms:Directed evolution technologies extend therapeutic half-life of phenylalanine ammonia-lyase variants, reducing injection frequency burdens for adolescent and adult patients.
- Germany statutory reimbursement:Full coverage mandates for PKU medical foods under statutory health insurance eliminate patient cost barriers and secure predictable revenue streams for metabolic food manufacturers.
Market Restraints
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases constrain cold-chain manufacturing inputs for certain synthetic enzyme production processes, elevating compliance costs.
- Single-source API concentration:Critical raw materials for synthetic amino acid formulations depend on concentrated Chinese intermediate suppliers, exposing formulators to geographic supply disruption.
- Gene therapy substitution threat:Curative modalities under FDA review threaten to displace chronic consumption models that currently sustain medical food revenue pools.
Strategic Opportunities
- Home care channel expansion:Direct-to-patient distribution models bypass hospital pharmacy procurement, capturing margin from compliance-driven repeat purchasing of amino acid supplements.
- Neonatal screening mandates:US state-level expansion of newborn metabolic panels creates addressable patient cohorts earlier in disease progression, extending treatment initiation windows.
- Digital phenylalanine monitoring:Convergence of continuous biosensors with mobile health platforms enables real-time dietary adjustment, creating adherence service revenue adjacent to core therapeutics.
Industry Challenges
- Gene therapy manufacturing talent scarcity:Viral vector production and quality control expertise concentrates at limited contract development organizations, constraining pipeline scaling.
- Cross-border reimbursement harmonization:Divergent national health technology assessment methodologies fragment market access negotiations across European single-payer systems.
- Pediatric formulation stability:Palatability engineering for medical foods must satisfy FDA pediatric study requirements while maintaining amino acid profile integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylketonuria (PKU) Market |
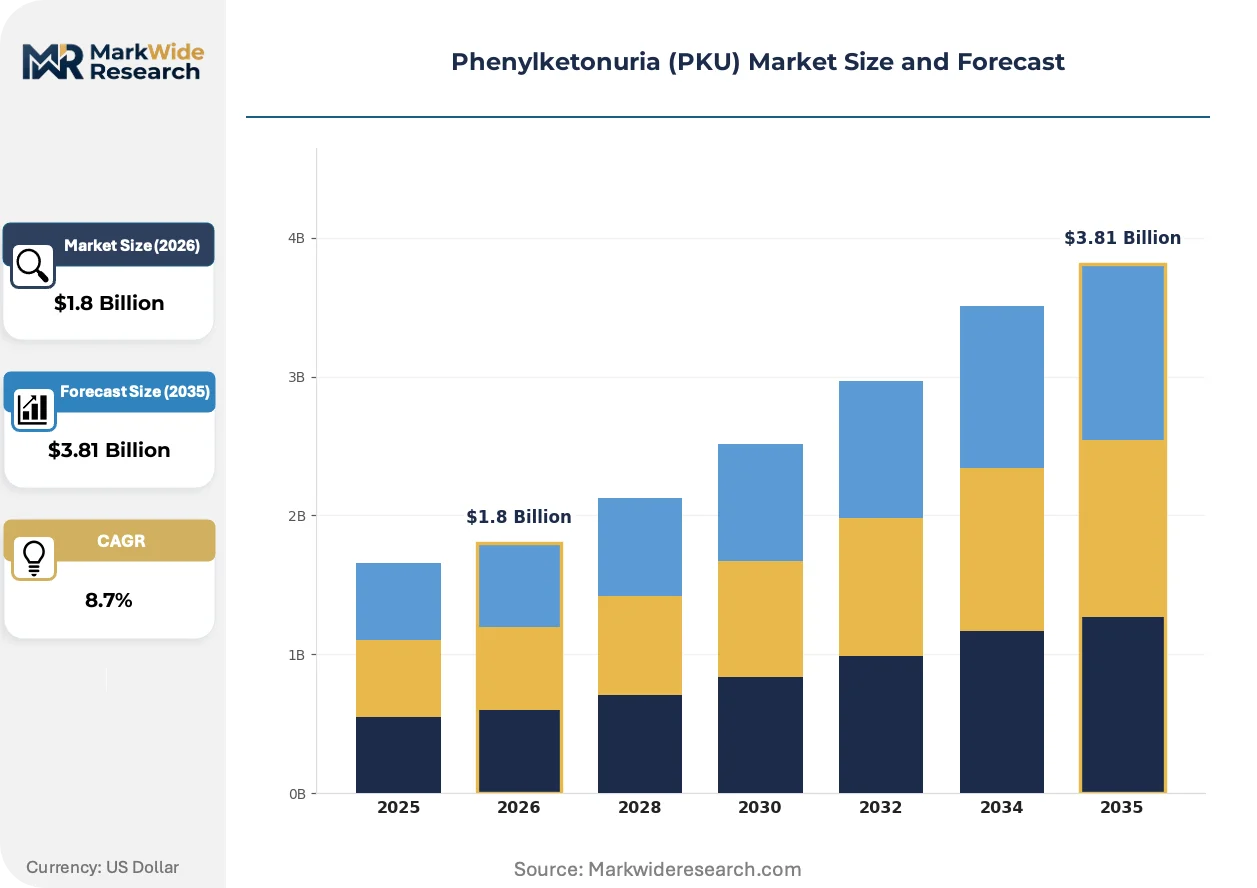
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Foods, Enzyme Replacement, Gene Therapy, Nutritional Supplements, Enzyme Inhibitors Therapy Area: Metabolic Disorders, Genetic Diseases, Rare Disorders, Nutritional Deficiencies, Pediatric Conditions End User: Specialist Clinics, Diagnostic Laboratories, Home Care Providers, Pediatric Centers, Research Institutions Delivery Mode: Oral Administration, Injectable Therapy, Dietary Management, Enzyme Therapy, Patient Monitoring |
| Companies Covered | Codexis, Ultragenyx Pharmaceutical, BioMarin Pharmaceutical, SOM Biotech, Erytech Pharma, PTC Therapeutics, Homology Medicines, Daiichi Sankyo, Synlogic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylketonuria (PKU) Market Strategic Shifts
Biological manufacturing modalities and regulatory science advances are compressing traditional boundaries between nutritional management and pharmaceutical intervention in metabolic disease care.
Engineered phenylalanine ammonia-lyase variants are collapsing the efficacy gap between enzyme replacement and dietary restriction by enabling meaningful phenylalanine reduction without full protein elimination. Metabolic centers in the United States and Germany are adopting these subcutaneous therapies for adolescent patients who demonstrate dietary non-compliance. The technology is collapsing the historical binary between medical food dependence and transplant-eligible disease severity, creating an intermediate therapeutic category.
REACH chemical standards and EU F-Gas Regulation are forcing reformulation of synthetic enzyme manufacturing processes toward aqueous-phase biocatalysis and solvent reduction. Contract manufacturers serving PKU therapy developers face capital allocation decisions between legacy chemical routes and green chemistry infrastructure. The regulatory pressure is compressing most severely on European production facilities, where ECHA registration deadlines outpace FDA environmental review timelines.
Home-based care models are displacing hospital-centric metabolic clinic visits as the locus of patient monitoring and prescription fulfillment. Specialist dietitians now coordinate remotely with patients using connected metabolic testing devices, while specialty pharmacies manage direct shipment of medical foods and supplements. This behavioral shift concentrates most visibly in Germany and the United States, where reimbursement structures accommodate remote patient monitoring codes and home infusion nursing benefits.
Phenylketonuria (PKU) Market Segmentation
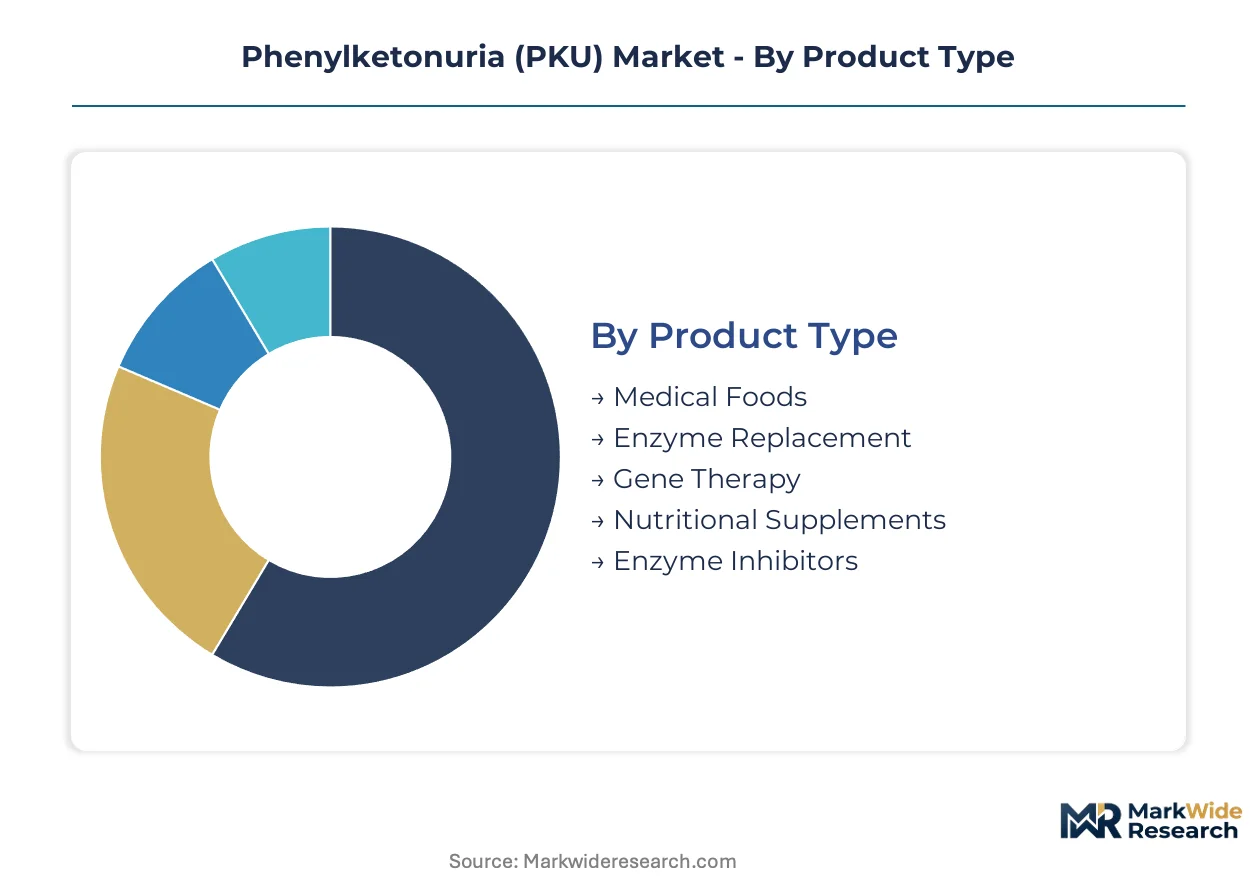
PKU market segmentation reveals divergent service intensity profiles across product categories. Chronic medical foods demand continuous patient support infrastructure, while gene therapy shifts value capture toward one-time intervention models requiring specialized manufacturing and follow-up protocols.
Product Type:
After-sales service intensity varies dramatically across PKU therapeutic modalities, with chronic consumption products requiring sustained patient education and compliance monitoring versus curative approaches demanding intensive peri-treatment support.
- Medical Foods:Synthetic amino acid formulations and phenylalanine-free protein substitutes constitute the foundational chronic therapy. Demand concentrates in Germany where statutory health insurance mandates eliminate patient cost barriers, while US pediatric centers drive volume through expanded newborn screening programs.
- Enzyme Replacement:Engineered phenylalanine ammonia-lyase variants delivered via subcutaneous injection extend therapeutic half-life and reduce dosing frequency. Metabolic centers in the United States prioritize these therapies for adolescent patients demonstrating dietary non-compliance, collapsing the historical binary between nutritional management and transplant-eligible severity.
- Gene Therapy:Viral vector-delivered phenylalanine hydroxylase gene correction targets curative outcomes. Clinical pipelines under FDA and EMA review are redirecting R&D investment toward this modality.
- Nutritional Supplements:Adjunct micronutrient and cofactor formulations support metabolic optimization. Home care channels capture margin from compliance-driven repeat purchasing.
- Enzyme Inhibitors:Small-molecule approaches targeting alternative metabolic pathways. Development programs remain pre-commercial with concentrated academic research institution sponsorship.
Medical foods hold the largest share; momentum sits with gene therapy.
Therapy Area:
Cost tier stratification across PKU therapeutic categories reflects divergent development timelines and reimbursement complexity, with rare disease premiums commanding pricing power against commoditized nutritional interventions.
- Metabolic Disorders:Core disease category encompassing phenylalanine hydroxylase deficiency and related enzymopathies. Specialist clinic procurement networks anchor demand through centralized patient management protocols.
- Genetic Diseases:Gene therapy development concentrates here, with EMA priority medicines frameworks accelerating assessment pathways. Manufacturing scale constraints limit near-term volume expansion.
- Rare Disorders:Orphan drug designations from FDA and EMA confer development incentives and market exclusivity protections. Revenue concentration reflects limited patient populations with high per-patient lifetime value.
- Nutritional Deficiencies:Secondary prevention focus addressing micronutrient gaps from protein-restricted diets. Home care providers drive distribution efficiency through direct-to-patient models.
- Pediatric Conditions:Early intervention emphasis with newborn screening expansion creating addressable cohorts. Palatability engineering requirements constrain formulation flexibility under FDA pediatric study mandates.
Metabolic disorders anchor current revenue; genetic diseases are climbing the fastest.
End User:
Application-specific procurement patterns fragment across institutional settings, with hospital-centric metabolic clinics yielding to distributed home-based care models in mature reimbursement markets.
- Specialist Clinics:Academic metabolic centers coordinate multidisciplinary care and anchor enzyme replacement therapy initiation. BioMarin Pharmaceutical leverages manufacturing scale to secure supply contracts with major North American and European centers.
- Pediatric Centers:Newborn screening program expansion across US states creates treatment initiation windows. Remote patient monitoring codes increasingly reimburse telemedicine coordination.
- Home Care Providers:Direct-to-patient distribution bypasses hospital pharmacy procurement. Germany and the United States lead this behavioral shift through reimbursement structures accommodating home infusion nursing benefits.
- Diagnostic Laboratories:Neonatal metabolic screening infrastructure determines patient identification timing. State-level mandate expansion extends addressable detection.
- Research Institutions:Gene therapy clinical trial execution and natural history study coordination. Viral vector production expertise concentrates at limited contract development organizations.
Specialist clinics retain the largest share; home care providers are gaining share fastest.
Delivery Mode:
Patient compliance requirements and reimbursement accessibility shape volume concentration across administration routes, with oral familiarity competing against injectable efficacy in adolescent and adult populations.
- Oral Administration:Medical foods and nutritional supplements maintain patient preference through familiar consumption patterns. Palatability engineering must satisfy FDA pediatric study requirements while preserving amino acid profile integrity.
- Injectable Therapy:Subcutaneous enzyme replacement reduces phenylalanine burden without full protein elimination. Adolescent non-compliance with dietary restriction drives metabolic center adoption.
- Dietary Management:Lifelong protein restriction with synthetic amino acid supplementation remains the standard of care foundation. Compliance fatigue limits efficacy in long-term patient cohorts.
- Enzyme Therapy:Phenylalanine ammonia-lyase variants enable meaningful metabolic control with reduced dietary stringency. REACH chemical standards and EU F-Gas Regulation force manufacturing process reformulation toward aqueous-phase biocatalysis.
- Patient Monitoring:Continuous biosensors and mobile health platforms enable real-time phenylalanine tracking. Digital adherence services create revenue adjacent to core therapeutics.
Oral administration dominates current volume; injectable therapy shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gene therapy guidance and EMA advanced therapy medicinal product standards anchor regulatory divergence across the dominant PKU markets, shaping clinical trial placement and reimbursement negotiations in the United States and Germany.
United States
Pediatric centers in Massachusetts and California are expanding newborn screening programs for metabolic disorders, creating earlier treatment initiation windows. FDA orphan drug designations accelerate PKU therapy development timelines and confer market exclusivity protections. The Boston-Cambridge biotech cluster concentrates gene therapy pipeline execution, with viral vector production expertise anchoring contract development organization capacity.
Germany
Statutory health insurance mandates full reimbursement for PKU medical foods, eliminating patient cost barriers and securing predictable revenue streams for metabolic food manufacturers. EMA priority medicines frameworks compress assessment pathways for advanced therapy medicinal products targeting phenylalanine hydroxylase deficiency. The Munich-Heidelberg corridor hosts specialist metabolic centers that coordinate multidisciplinary care and anchor enzyme replacement therapy initiation protocols.
United Kingdom
NHS England's specialized commissioning frameworks determine access to high-cost metabolic therapies through national health technology assessment. The UK Medicines and Healthcare products Regulatory Agency aligns gene therapy evaluation with EMA standards while maintaining independent marketing authorization pathways. London's academic hospital trusts concentrate pediatric metabolic expertise and natural history study coordination for emerging therapeutic modalities.
Japan
PMDA sakigake designation pathways accelerate review of innovative therapies for rare metabolic diseases with high unmet need. The Ministry of Health, Labour and Welfare's reimbursement pricing methodology for orphan drugs incorporates rarity premiums and cost-effectiveness thresholds. Tokyo-Osaka medical center networks manage the majority of diagnosed PKU patients through centralized specialist clinic protocols.
Switzerland
Swissmedic's parallel review procedures with EMA streamline market access for therapies receiving European marketing authorization. Mandatory health insurance coverage for congenital metabolic disorders eliminates financial barriers to medical food consumption and enzyme replacement access. The Basel-Zurich corridor concentrates pharmaceutical manufacturing infrastructure serving European distribution networks for synthetic amino acid formulations.
Phenylketonuria (PKU) Market Competitive Environment
Gene therapy specialists and chronic therapy incumbents split the market across divergent value capture models, with curative modalities threatening lifetime revenue pools that currently sustain medical food suppliers. The competitive structure compresses into three strategic archetypes: viral vector platform developers pursuing one-time intervention economics, engineered enzyme manufacturers extending half-life performance for subcutaneous delivery, and metabolic nutrition formulators defending compliance-driven repeat purchasing. Dominant competitive moves include strategic partnerships bridging manufacturing scale gaps and portfolio diversification into adjacent rare metabolic indications.
Among the disclosed participants, BioMarin Pharmaceutical occupies a position exemplifying the enzyme replacement archetype through manufacturing scale advantages, while Ultragenyx Pharmaceutical represents deep specialization in rare disease infrastructure and patient support ecosystems. Codexis anchors the engineered biologics tier with directed evolution capabilities. These three entities collectively illustrate the competitive tension between incremental therapeutic improvement and curative modality displacement.
| Leading Market Players |
|---|
| Codexis |
| Ultragenyx Pharmaceutical |
| BioMarin Pharmaceutical |
| SOM Biotech |
| Erytech Pharma |
| PTC Therapeutics |
| Homology Medicines |
| Daiichi Sankyo |
| Synlogic |
| Others |
Value Chain & Pricing Dynamics
Single-source API concentration in Chinese intermediate suppliers for synthetic amino acid formulations dictates both the premium commanded by vertically integrated formulators and the geographic redundancy strategies of procurement officers. This dependency vector compresses margin structures for medical food manufacturers while elevating pricing power for contract manufacturers with diversified feedstock access.
Pricing Analysis
Configured-to-order pricing for patient-specific amino acid profiles commands substantial premiums over standard formulations. Three-tier pricing structure across premium, standard, and economy levels reflects palatability engineering investments, FDA pediatric study compliance costs, and after-sales dietitian support bundling. Cost compression in economy-tier medical foods is intensifying because of statutory reimbursement rate pressure in German statutory health insurance negotiations. Pediatric centers demonstrate lowest price sensitivity due to mandated coverage, while home care direct-to-patient channels exhibit highest sensitivity to out-of-pocket supplement costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for synthetic amino acid manufacturers. Critical raw material production concentrates in China, India, and Germany, with phenylalanine-free protein substitutes drawing from concentrated fermentation capacity in Shandong province and Bavaria. REACH chemical standards and EU F-Gas Regulation constrain cold-chain manufacturing inputs, elevating compliance costs for enzyme production. Distribution runs through hospital pharmacy procurement networks in North America and specialty pharmacy direct-to-patient channels in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as gene therapy pipelines compress the addressable chronic therapy pool, creating defensive niches for compliance-focused service providers and specialized manufacturing intermediates.
For Market Incumbents: Entrench manufacturing scale advantages through backward integration into fermentation capacity and synthetic amino acid intermediate production. Secure long-term supply contracts with major metabolic centers before gene therapy substitution accelerates. Anchor position via exclusive dietitian support service bundling that creates switching costs beyond product formulation. For New Entrants and Emerging Players: Home care channel underpenetration in Japan and Switzerland offers white-space expansion with lower competitive density than saturated German and US markets. Target adolescent non-compliant patient segments with palatability-engineered medical food formats that bypass established hospital procurement relationships. Pursue direct-to-patient subscription models with connected metabolic monitoring device integration. For Investors and Strategic Acquirers: The market sits at a substitution-threat phase that favors engineered enzyme platform developers with extendable half-life IP. Long-term viability hinges on portfolio diversification into adjacent rare metabolic indications with shared manufacturing infrastructure. Monitor FDA gene therapy approval timelines as the critical inflection signal for chronic therapy revenue pool compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Clinical Advancement | FDA and EMA review pipelines redirect R&D investment toward curative modalities with one-time intervention economics. |
| Engineered Enzyme Platform Expansion | Directed evolution capabilities extend phenylalanine ammonia-lyase half-life, reducing injection frequency burdens for adolescent patients. |
| Home Care Channel Buildout | Direct-to-patient distribution models capture margin from compliance-driven repeat purchasing of amino acid supplements. |
| Neonatal Screening Mandate Expansion | US state-level newborn metabolic panel expansion creates earlier treatment initiation windows and extended patient lifetime value. |
| Green Manufacturing Transition | EU F-Gas Regulation and REACH standards force aqueous-phase biocatalysis adoption, favoring capital-rich incumbents with infrastructure upgrade capacity. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with metabolic center directors, formulary access specialists, and hospital procurement managers; and secondary validation against FDA orphan drug filings, EMA priority medicines designations, ClinicalTrials.gov gene therapy protocols, and German statutory health insurance reimbursement databases. Bottom-up patient cohort modeling triangulated with top-down metabolic food manufacturer revenue aggregation across the analysis window.
Forecast inputs encompassed treatment modality segmentation, patient age cohort progression, regional regulatory cluster divergence, and therapy substitution elasticity parameters. CAGRs derived from logistic diffusion modeling of gene therapy penetration against chronic medical food consumption decay functions. Modeled dimensions included product type, therapy area, end user institution type, and delivery mode administration route.
Practitioners should monitor FDA gene therapy guidance finalization and EMA advanced therapy medicinal product approval timelines for early signals of chronic therapy revenue pool compression. Forecasts reflect assumptions about regulatory pathway duration, manufacturing scale-up feasibility, and patient compliance persistence that industry-specific disruptions could materially revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Biologic Response Modifiers Market