
 Bio-Active Peptides Market | 2026-2036
Bio-Active Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Active Peptides Market Insights
Pharmaceutical-grade peptide specifications are reorganizing competitive dynamics across the bio-active peptides landscape. GELITA AG leverages its century-long collagen expertise to sustain dominance in medical nutrition and wound care applications. PolyPeptide Group anchors the contract manufacturing segment with multi-kilogram GMP peptide synthesis capacity serving biotech clients. DSM differentiates through its Quali portfolio, combining vitamin and peptide premixes for fortified food systems.
Bio-active peptides comprise short amino acid chains, typically 2–20 residues, derived from enzymatic hydrolysis of food proteins or solid-phase chemical synthesis; these molecules exhibit hormone-regulating, antimicrobial, or cell-signaling activity at micromolar concentrations. Collagen peptides occupy the largest volume tier due to established clinical evidence for joint and skin health, while whey protein hydrolysates command premium positioning in sports nutrition for rapid absorption kinetics. Nutraceutical applications generate the deepest margin pools as direct-to-consumer brands seek differentiated positioning, whereas pharmaceutical development of peptide therapeutics demands longer validation cycles but offers patent-protected revenue structures.
FDA New Dietary Ingredient notifications and EFSA health claim authorizations create dual compliance burdens for suppliers seeking transatlantic distribution. ISO 17025 laboratory accreditation and USP peptide reference standards increasingly determine qualification for pharmaceutical procurement channels. Stakeholders must monitor evolving peptide-allergen labeling requirements and synthetic biology alternatives that could displace traditional enzymatic extraction methods.
Market Dynamics
Enzymatic hydrolysis scale-up constraints are forcing nutraceutical manufacturers toward solid-phase chemical synthesis partnerships, compressing batch economics and redrawing supplier qualification hierarchies across functional food value chains.
Growth Catalysts
- Sports nutrition absorption kinetics:Whey protein hydrolysates with di- and tripeptide fractions below 1000 Da achieve 30-minute gastric emptying, driving formulation switches in pre-workout and recovery segments.
- EFSA Article 13.1 health claims:Authorized collagen peptide claims for joint maintenance reduce regulatory friction for European functional food launches, accelerating brand pipeline commitments.
- Medical nutrition procurement:Hospital formulary acceptance of peptide-based enteral nutrition is expanding post-surgical recovery protocols in German and Swiss acute care networks.
Market Restraints
- Fish collagen input volatility:Marine peptide feedstock costs fluctuate with North Atlantic fishery quotas and Asian aquaculture disease cycles, squeezing margin stability for hydrolysate producers.
- FDA NDI notification timelines:The 75-day safety review window for novel peptide structures delays US market entry by 8-14 months versus GRAS self-affirmation pathways available to established ingredients.
- Plant protein hydrolysate functionality gaps:Legume-derived peptides lack the proline-hydroxyproline-glycine repeat motifs critical for extracellular matrix signaling, limiting substitution in skin and joint applications.
Strategic Opportunities
- Microbiome modulation applications:Bio-active milk peptides with ACE-inhibitory and opioid-like activity are entering pediatric nutrition and senior digestive health formulations in Japanese and South Korean markets.
- Precision fermentation convergence:Recombinant peptide production via microbial hosts eliminates enzymatic hydrolysis variability, enabling pharmaceutical-grade specifications for wound care matrices.
- Direct-to-consumer subscription channels:Collagen peptide powders bypass traditional pharmacy and mass retail gatekeepers, capturing lifetime value through personalized dosing regimens and auto-replenishment models.
Industry Challenges
- Peptide-allergen cross-reactivity labeling:Manufacturers lack standardized IgE binding assays to support "free-from" claims, exposing brands to litigation risk in California and EU member states with strict precautionary labeling.
- GMP peptide synthesis capex requirements:Multi-kilogram SPPS capacity demands $15-25 million facility investments with 4-year depreciation horizons, constraining mid-tier contract manufacturers.
- USP reference standard procurement delays:Six-month backlogs for certified peptide calibrators stall method validation timelines for pharmaceutical clients seeking CMC package completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Active Peptides Market |
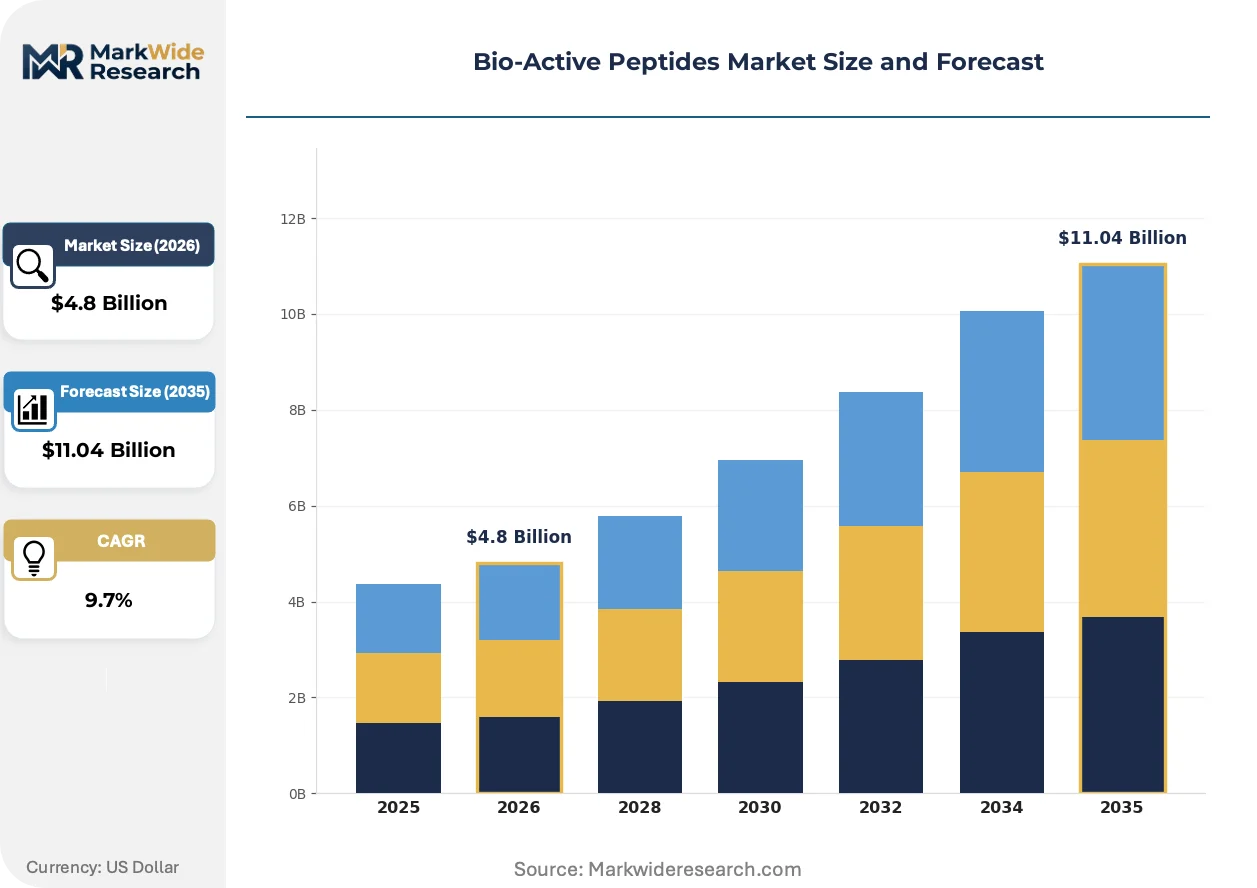
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen Peptides, Whey Protein, Casein Peptides, Soy Peptides Application: Nutraceuticals, Functional Foods, Pharmaceutical, Cosmetics End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Research Institutions Form: Powder, Liquid, Capsule, Granule |
| Companies Covered | GELITA AG, PolyPeptide Group, Seagarden AS, Arlak Biotech Pvt. Ltd., Phermpep Co. Ltd., Ingredia Nutritional, Creative Peptides, ADM, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Active Peptides Market Trends and Innovations
Synthetic biology platforms are collapsing the cost curve for rare amino acid incorporation, while regulatory science struggles to keep pace with novel peptide bioactivity characterization. These forces are fragmenting traditional extraction-based supply relationships.
Continuous flow peptide synthesis is fragmenting batch-reactor dominance in pharmaceutical-grade manufacturing. Biotech CDMOs adopt microfluidic reactor trains with real-time mass spectrometry monitoring, cutting cycle times from weeks to days. This compression enables just-in-sequence supply to personalized medicine programs, displacing inventory-heavy sourcing models.
EFSA's 2023 updated guidance on protein hydrolysate characterization demands quantitative peptide mapping and bioactivity retention validation across shelf life. European functional food brands now commission forced-degradation studies as standard NPD checkpoints. The collagen peptide segment bears disproportionate compliance burden given its volume concentration in German and French retail channels.
Hospital nutrition procurement committees in the US and Germany are unbundling peptide-based enteral formulas from device contracts, creating standalone ingredient specification sheets. This disintermediation forces peptide suppliers to demonstrate batch-to-batch bioactivity consistency independent of delivery system partners. Swiss medical nutrition manufacturers have responded with certificate-of-analysis standardization that pre-qualifies materials for competitive tender processes.
Bio-Active Peptides Market Segmentation
Bio-active peptide suppliers configure production lines around molecular weight distributions and bioactivity signatures that diverge sharply across end-use specifications. Segmentation discipline separates commodity hydrolysate volumes from pharmaceutical-grade precision, determining margin capture and regulatory pathway selection.
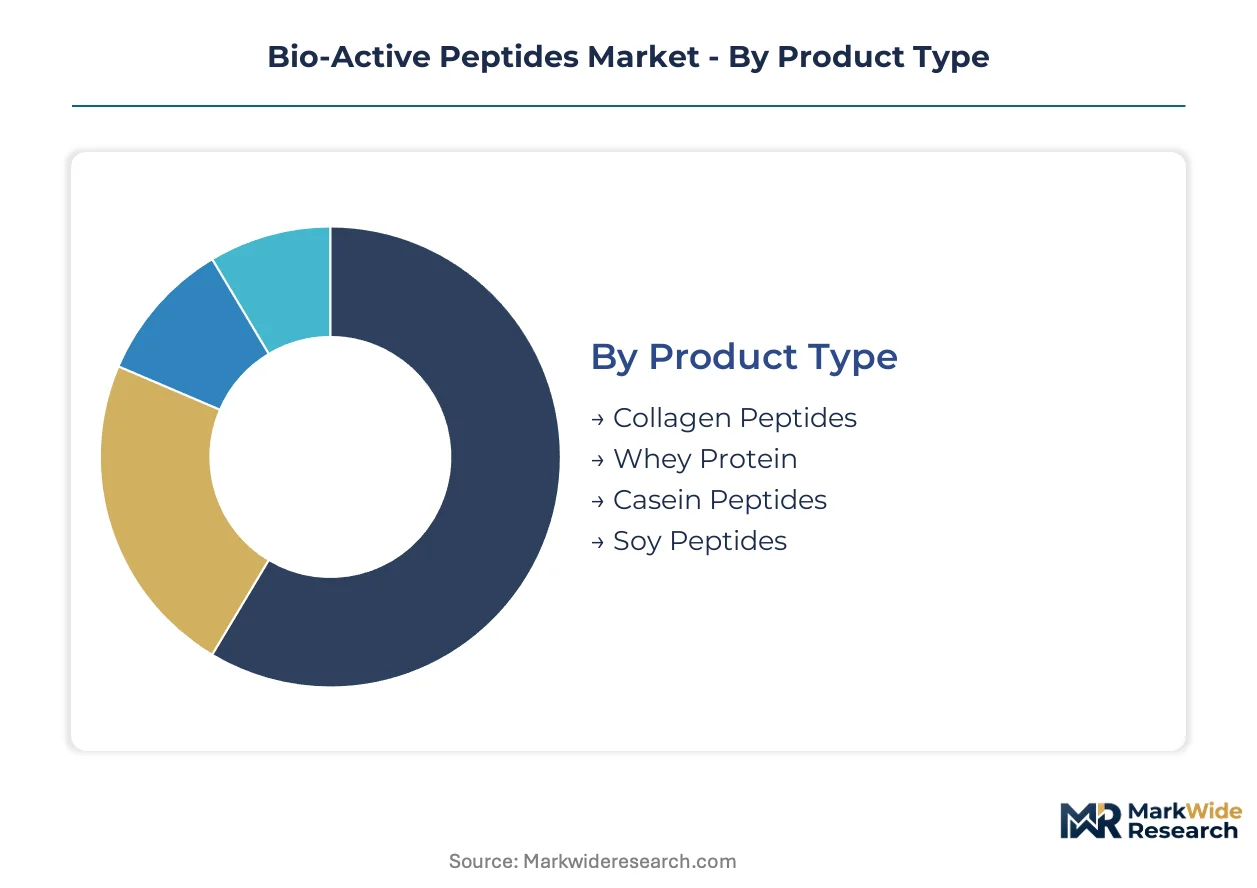
Product Type:
Collagen peptides dominate export flows to Asian cosmetic and European medical nutrition markets, while whey derivatives serve concentrated domestic sports nutrition demand in North America.
- Collagen Peptides:These proline-hydroxyproline-glycine rich chains, typically 2-10 kDa molecular weight, support extracellular matrix signaling. Demand concentrates in German medical nutrition and Japanese beauty-from-within supplements, driven by EFSA-authorized joint health claims and aging demographics.
- Whey Protein:Rapidly absorbed di- and tripeptide fractions below 1000 Da achieve 30-minute gastric emptying kinetics. North American pre-workout formulations and recovery beverages represent the primary demand concentration, with absorption speed commanding formulation premiums.
- Casein Peptides:Slow-release bioactive sequences support overnight muscle protein synthesis protocols.
- Soy Peptides:Plant-derived hydrolysates serve vegetarian positioning requirements despite functionality gaps in matrix signaling applications.
Collagen peptides hold the largest share; momentum sits with whey protein fractions optimized for absorption velocity.
Application:
Margin structures stratify across regulatory burden tiers, with pharmaceutical development demanding multi-year validation cycles and nutraceutical channels permitting rapid formulation pivots.
- Nutraceuticals:Direct-to-consumer powders and capsules generate the deepest margin pools as brands seek differentiated positioning through peptide dosing regimens. German and Swiss consumers drive premium collagen subscription models with auto-replenishment capture.
- Functional Foods:EFSA Article 13.1 health claim authorizations for collagen peptides reduce regulatory friction in European retail launches. French and German functional dairy and beverage brands accelerate pipeline commitments based on approved joint maintenance messaging.
- Pharmaceutical:Peptide therapeutics development requires FDA New Dietary Ingredient notifications or drug approval pathways with extended timelines.
- Cosmetics:Topical peptide actives target dermal penetration and signaling claims in Korean and Japanese skincare formulations.
Nutraceuticals command margin leadership; pharmaceutical applications are climbing the fastest as wound care and enteral nutrition specifications tighten.
End User:
Procurement sophistication varies dramatically across customer types, with healthcare networks demanding batch-to-batch bioactivity certificates and cosmetic brands prioritizing stability and sensory compatibility.
- Healthcare Providers:Hospital formulary committees in Germany and Switzerland unbundle peptide-based enteral formulas from device contracts, creating standalone ingredient specifications. Post-surgical recovery protocols drive consistent procurement with certificate-of-analysis standardization requirements.
- Food Manufacturers:European functional food brands commission forced-degradation studies as standard new product development checkpoints following EFSA protein hydrolysate guidance updates.
- Cosmetic Companies:Korean and Japanese skincare formulators prioritize molecular weight consistency for dermal penetration claims.
- Research Institutions:Academic and clinical trial sponsors require USP reference standard compliance for method validation.
Healthcare providers anchor volume commitment; food manufacturers are expanding most quickly as health claim frameworks clarify.
Form:
Processing economics and stability requirements determine format selection, with powder dominating bulk ingredient trade and capsules capturing finished goods premiums.
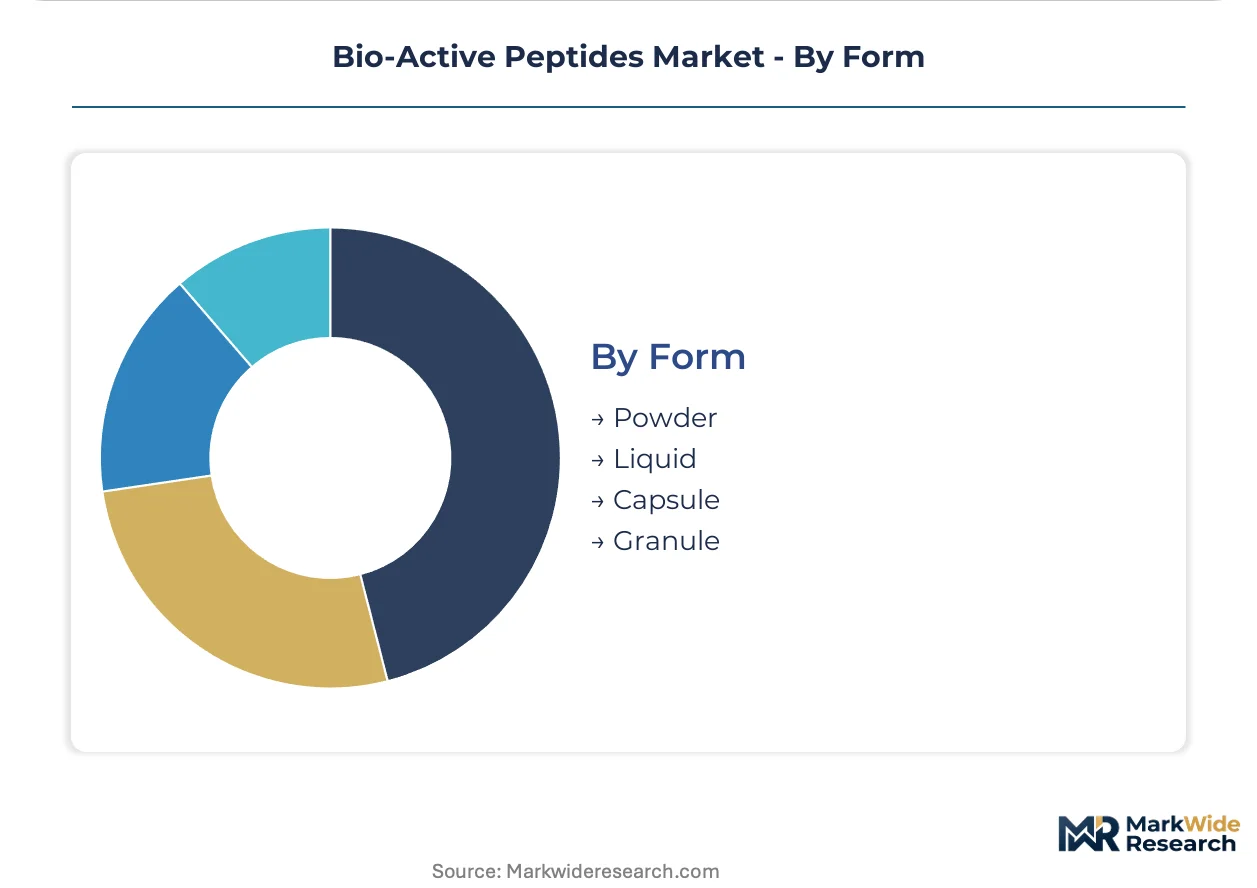
- Powder:Spray-dried and agglomerated formats dominate industrial-scale supply to food and nutraceutical manufacturers. German collagen peptide production facilities ship multi-ton quantities to European compounders with moisture specification controls.
- Liquid:Ready-to-drink delivery systems command convenience premiums in sports nutrition and medical nutrition channels. Stability challenges require pH buffering and preservative systems that add formulation complexity.
- Capsule:Hard-shell gelatin and vegetable-derived encapsulation serve precision dosing requirements in premium supplement positioning.
- Granule:Intermediate flowability formats bridge powder handling efficiency and finished product convenience.
Powder maintains production dominance; liquid formats are gaining share fastest in convenience-oriented consumption occasions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German collagen peptide production facilities anchor European supply chains, while enzymatic hydrolysis capacity clusters in coastal zones with access to marine feedstock streams.
United States
FDA New Dietary Ingredient notifications drive compliance investment for novel peptide structures entering sports nutrition channels. The 75-day safety review window compresses margin timelines for entrants versus GRAS-affirmed ingredients. Greater Boston biotech clusters host contract synthesis operations serving pharmaceutical peptide development programs.
Germany
EFSA Article 13.1 health claim authorizations for collagen peptides accelerate functional food launches across German retail networks. Hospital formulary committees unbundle peptide-based enteral formulas from device contracts, creating standalone procurement specifications. North Rhine-Westphalia hosts major hydrolysis facilities supplying compounders throughout the Benelux corridor.
Japan
METI guidance on functional food substantiation shapes peptide bioactivity characterization standards for domestic manufacturers. Beauty-from-within collagen consumption drives per-capita demand intensity unmatched in other developed markets. Osaka-Kobe industrial zones concentrate enzymatic extraction capacity serving Asian cosmetic brand supply chains.
South Korea
MFDS regulatory frameworks for health functional foods permit rapid peptide ingredient registration compared to pharmaceutical pathways. Pediatric nutrition and senior digestive health formulations absorb bio-active milk peptides with ACE-inhibitory properties. Seoul Capital Area R&D clusters pioneer precision fermentation approaches to recombinant peptide production.
Switzerland
Swissmedic medical device and nutrition interface regulations demand batch-to-batch bioactivity certification for enteral formula suppliers. Post-surgical recovery protocols in Swiss acute care networks specify peptide-based substrates with documented nitrogen retention kinetics. Basel pharmaceutical corridor hosts CDMO operations with multi-kilogram GMP peptide synthesis capacity.
Bio-Active Peptides Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the bio-active peptides landscape. Collagen specialists with century-long extraction expertise dominate medical nutrition procurement channels, while contract manufacturers anchor pharmaceutical-grade peptide synthesis. The competitive structure stratifies into three archetypes: integrated hydrolysate producers, multi-kilogram GMP synthesis houses, and precision fermentation platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as enzymatic hydrolysis constraints force technology convergence.
Among German-anchored collagen specialists, GELITA AG exemplifies integrated hydrolysate production with medical nutrition and wound care positioning. PolyPeptide Group occupies the contract manufacturing tier with multi-kilogram GMP synthesis capacity serving biotech development programs. DSM-Firmenich represents the premix and fortification archetype, combining peptide and vitamin portfolios for food system applications.
| Leading Market Players |
|---|
| GELITA AG |
| PolyPeptide Group |
| Seagarden AS |
| Arlak Biotech Pvt. Ltd. |
| Phermpep Co. Ltd. |
| Ingredia Nutritional |
| Creative Peptides |
| ADM |
| DSM |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German collagen peptide producers and European medical nutrition brands lock in multi-year supply access while anchoring price visibility against North Atlantic fishery quota volatility. These arrangements insulate compounders from spot-market marine feedstock swings but embed volume minimums that strain working capital during demand softness.
Pricing Analysis
EFSA Article 13.1 health claim authorizations dictate the pricing tier structure for European collagen peptide suppliers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade GMP material from nutraceutical-grade hydrolysates and commodity feed applications. Cost compression in standard-tier hydrolysates is intensifying because Asian aquaculture disease cycles squeeze fish collagen input availability. Hospital procurement committees demonstrate the lowest price sensitivity due to formulary unbundling and bioactivity certification requirements, while mass-market sports nutrition brands face acute margin pressure from absorption-kinetics commoditization.
Supply Chain Analysis
Strategic stockpiling of marine raw materials dominates inventory strategy among coastal enzymatic hydrolysis operators buffering against North Atlantic fishery quota seasonality. Supply concentration rests on Germany, Norway, and Japan, where coastal processing facilities cluster near cold-water species landing points. Raw material dependencies center on cod skin and haddock bone streams, porcine and bovine hide collagen, and recombinant microbial expression hosts. Single-source vulnerability runs through North Atlantic pelagic fishery management decisions that cascade through marine peptide feedstock availability. Distribution runs through compounder networks in the Benelux corridor and direct-to-consumer fulfillment centers bypassing traditional pharmacy gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based peptide dosing regimens and auto-replenishment platforms represent a service-attach layer expanding faster than bulk ingredient supply, capturing lifetime value through personalized nutrition protocols and compliance monitoring.
For Market Incumbents: Shield market position by deepening captive supply of pharmaceutical-grade GMP synthesis capacity in the Swiss Basel corridor and accelerating ISO 17025 laboratory accreditation investments ahead of evolving peptide-allergen labeling requirements. Precision fermentation platforms threaten traditional enzymatic extraction economics; backward integration into recombinant production hosts defends margin structure against synthetic biology displacement. For New Entrants and Emerging Players: Lead with microbiome modulation applications in Japanese pediatric nutrition and South Korean senior digestive health segments, where regulatory pathways permit rapid ingredient registration compared to pharmaceutical development timelines. Direct-to-consumer collagen subscription models in German-speaking markets offer the most penetrable white space, with personalized dosing regimens and auto-replenishment capture enabling brand equity accumulation outside traditional retail gatekeepers. For Investors and Strategic Acquirers: Multi-kilogram GMP peptide synthesis houses with hospital formulary pre-qualification status offer defensible positioning as medical nutrition procurement committees unbundle enteral formulas from device contracts. Long-term viability hinges on regulatory science convergence around bioactivity characterization standards and the displacement timeline for enzymatic hydrolysis by precision fermentation. Watch EFSA guidance evolution on protein hydrolysate shelf-life validation as the inflection signal for compliance cost escalation across European functional food brands.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant peptide production via microbial hosts eliminates enzymatic hydrolysis variability for pharmaceutical-grade wound care specifications. |
| GMP Synthesis Capacity Expansion | Multi-kilogram solid-phase peptide synthesis investments in Swiss and German corridors capture hospital formulary unbundling demand. |
| Direct-to-Consumer Channel Development | Subscription-based collagen powder platforms bypass pharmacy gatekeepers and capture lifetime value through auto-replenishment models. |
| EFSA Health Claim Authorization Pursuit | Article 13.1 joint maintenance claims reduce regulatory friction for European functional food launches and accelerate brand pipeline commitments. |
| USP Reference Standard Pre-Positioning | Certified peptide calibrator procurement relationships shorten method validation timelines for pharmaceutical clients seeking CMC package completion. |
Research Methodology
The analysis maps collagen peptide hydrolysates, whey protein fractions, casein peptides, and precision fermentation platforms, each validated through regulatory affairs specialists at EFSA-notified bodies, hospital formulary procurement managers in German and Swiss acute care networks, and contract manufacturing officers at multi-kilogram GMP synthesis facilities. Primary interviews with nutraceutical brand managers, enzymatic hydrolysis plant engineers, and peptide therapeutics development executives combined with secondary validation against FDA New Dietary Ingredient notification databases, EFSA health claim authorization registers, and USP reference standard procurement records. Bottom-up volume estimates from production facility capacities and top-down demand segmentation from end-use procurement patterns underwent cross-triangulation for consistency.
External benchmark checks against customs trade flows and pharmaceutical ingredient import databases validated volume and value outputs across the projection horizon. The analytical framework modeled molecular weight distribution tiers, bioactivity signature specifications, regulatory pathway clusters, and geographic production hub concentrations. CAGRs derived from segment-level demand elasticity coefficients and supply-side capacity expansion schedules incorporated fish collagen input cost trajectories and precision fermentation yield improvement curves as industry-specific forecast inputs.
Underlying assumptions cover EFSA guidance stability on protein hydrolysate characterization, FDA NDI review timeline continuity, and North Atlantic fishery quota management patterns, with deviation risk concentrated in synthetic biology yield breakthroughs and peptide-allergen labeling litigation thresholds. Revision becomes warranted when precision fermentation production economics cross cost parity with enzymatic hydrolysis at commercial scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Influenza Vaccine Market