
 Human Insulin Market | 2026-2036
Human Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Human Insulin Market Intelligence
Biosimilar-grade insulin analog quality is unwinding cost barriers across emerging markets. Novo Nordisk A/S anchors European production standards while competing in vial and pen formats. Eli Lilly and Company specializes in rapid-acting analog R&D. Tonghua Dongbao Pharmaceutical Co., Ltd. dominates volume manufacturing for Asia-Pacific distribution.
Human insulin comprises recombinant DNA-derived polypeptide hormones formulated as rapid-acting, short-acting, intermediate-acting, or long-acting preparations for glycemic control in diabetes mellitus. Pen injector delivery mode leads in patient adherence metrics across home healthcare settings. Insulin Lispro and Insulin Aspart analog segments capture premium positioning in Type 1 Diabetes therapy areas. Regular Insulin vials retain cost-sensitive hospital procurement volumes.
FDA bioequivalence pathways and EMA biosimilar guidelines shape product approval timelines and interchangeability standards. India's CDSCO and PLI scheme accelerate domestic insulin manufacturing scale. China's NMPA GB standards govern import quality thresholds. Stakeholders must monitor regulatory divergence on biosimilar substitution policies and insulin pricing controls.
Market Dynamics
Hospital procurement of biosimilar insulin analogs is accelerating as India's PLI scheme expands domestic manufacturing capacity, shifting supply concentration from Western Europe toward Asia-Pacific production clusters.
Growth Catalysts
- India's PLI Scheme:India's Production Linked Incentive scheme subsidizes domestic insulin manufacturing scale, attracting contract manufacturing organizations to establish recombinant DNA production facilities in Gujarat and Maharashtra.
- Pen injector demand:Brazil's public health system SUS is converting vial-based diabetes programs to pen injector formats, driving device procurement volumes and patient adherence metrics in home healthcare settings.
- FDA bioequivalence pathways:The FDA's 505(b)(2) and biosimilar approval frameworks compress regulatory timelines for insulin analog entrants, enabling faster market access for follow-on biologics.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for recombinant insulin concentrates in China and South Korea, creating geopolitical exposure for Western formulation facilities.
- Cold chain infrastructure gaps:Temperature-controlled distribution networks remain underdeveloped across sub-Saharan Africa and rural Southeast Asia, limiting analog insulin shelf stability.
- EMA interchangeability delays:The European Medicines Agency's pending guidance on automatic pharmacist substitution of biosimilar insulins creates reimbursement uncertainty across EU member states.
Strategic Opportunities
- Connected pen devices:Bluetooth-enabled dose tracking and glucose monitoring integration is opening adherence data monetization channels for payers and health systems.
- Indonesia's JKN expansion:Indonesia's national health insurance program is adding Type 1 Diabetes coverage, creating reimbursement infrastructure for analog insulin in Southeast Asia's largest population.
- Continuous glucose monitor convergence:Closed-loop artificial pancreas systems are driving demand for rapid-acting insulin lispro formulations calibrated to sensor-augmented pump algorithms.
Industry Challenges
- Bioprocessing talent scarcity:Recombinant protein fermentation and downstream purification expertise concentrates at a handful of contract development organizations, constraining manufacturing expansion timelines.
- CDSCO facility inspection backlogs:India's Central Drugs Standard Control Organization faces staffing shortages for pre-approval inspections, delaying biosimilar insulin plant certifications by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Insulin Market |
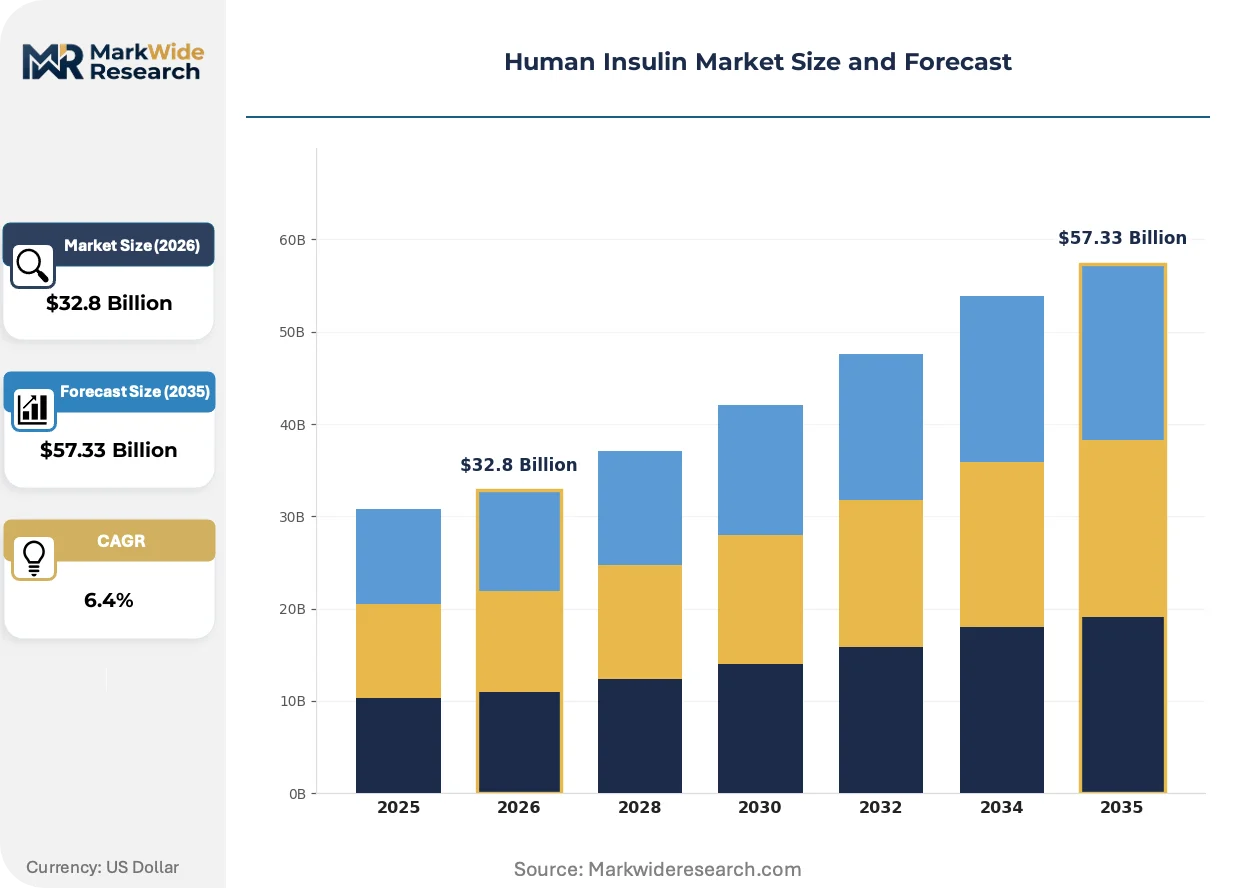
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
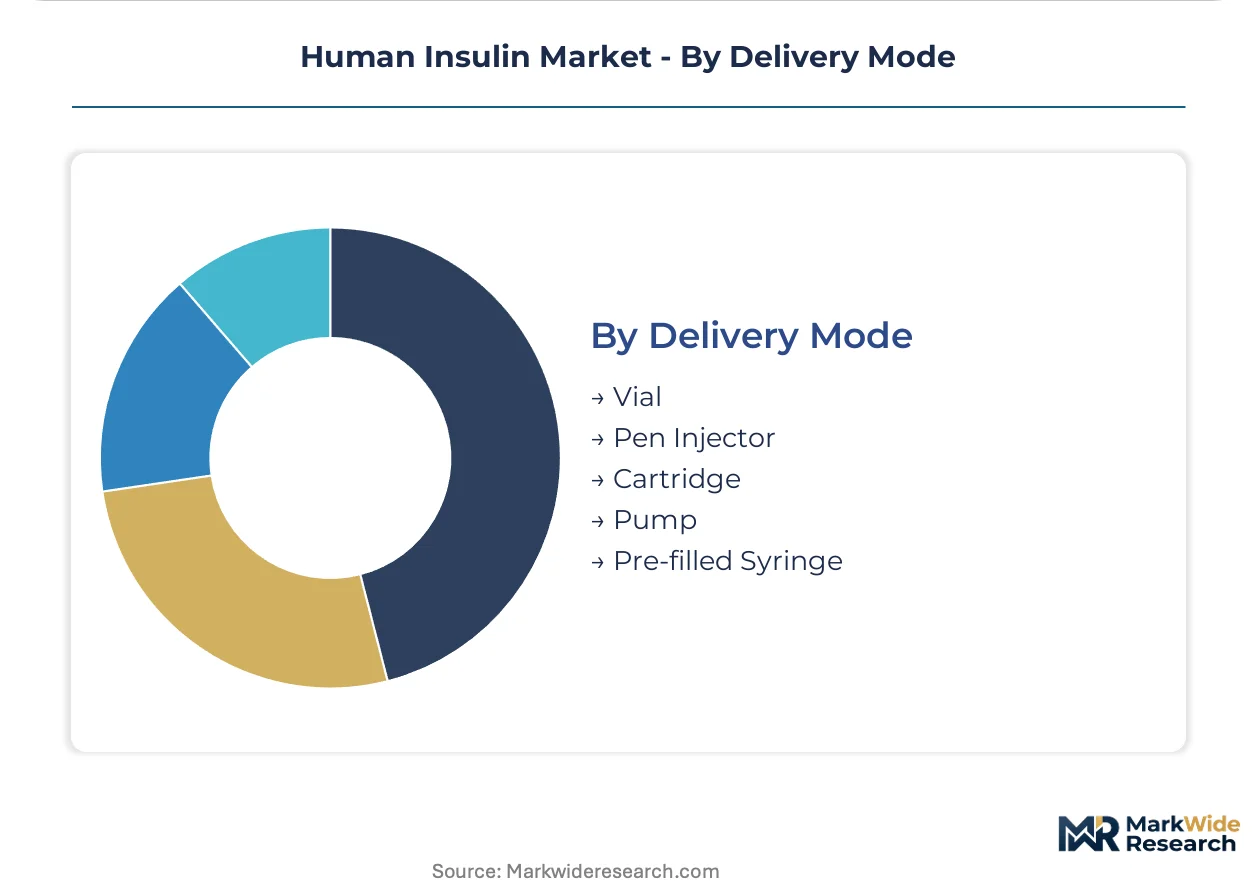
| Segmentation | Product Type: Regular Insulin, NPH Insulin, Insulin Lispro, Insulin Aspart, Insulin Glulisine Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Latent Autoimmune Diabetes, Diabetes Insipidus End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Healthcare, Diagnostic Laboratories Delivery Mode: Vial, Pen Injector, Cartridge, Pump, Pre-filled Syringe |
| Companies Covered | Biocon Biologics Ltd, Tonghua Dongbao Pharmaceutical Co., Ltd., Novo Nordisk A/S, Gan & Lee Pharmaceuticals, Julphar, Sanofi S.A., Wockhardt Ltd, Zhuhai United Laboratories Co., Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Insulin Market Strategic Shifts & Innovations
Insulin delivery technology is converging with digital health infrastructure, while regulatory frameworks adapt to biosimilar substitution and cold chain logistics face pressure from climate volatility.
Smart pen injector systems with embedded dose memory and smartphone connectivity are miniaturizing electronic components into disposable formats. Home healthcare patients in Germany and Japan are adopting these devices fastest, with reimbursement codes now covering connected pen formats. This technology is miniaturizing the cost barrier between premium analog pens and standard vial-syringe therapy, compressing price differentiation across delivery modes.
The FDA's forthcoming interchangeability guidance for biosimilar insulins is forcing state-level pharmacy board policy harmonization. Manufacturers must prepare for automatic substitution protocols that will accelerate price erosion for originator analogs. Rapid-acting insulin lispro segments face the steepest margin pressure as multiple interchangeable candidates approach approval.
Direct-to-clinic distribution models are bypassing wholesale intermediaries in Brazil and Mexico. Hospital pharmacy buyers now contract directly with insulin manufacturers for annual volume commitments, replacing tender-based procurement. This channel compression is most visible in São Paulo's state hospital network, where consolidated purchasing has cut distribution costs by eliminating regional distributor markups.
Human Insulin Market Segmentation

Insulin segmentation determines reimbursement codes, cold chain requirements, and manufacturing scale decisions. Product type and delivery mode classifications shape procurement patterns across hospital formularies and retail pharmacy networks.
Product Type:
Hospital procurement channels favor intermediate-acting formulations, while retail pharmacies and home healthcare channels concentrate rapid-acting analog volumes.
- Insulin Lispro:Rapid-acting recombinant analog with amino acid substitution at B28 reversing proline and lysine positions. Germany's Techniker Krankenkasse and Japan's reimbursement panels now cover connected pen formats for this segment, compressing price differentiation against vial-syringe therapy.
- Insulin Aspart:Fast-acting biosynthetic analog produced in Saccharomyces cerevisiae with aspartic acid substitution at B28. Brazil's SUS conversion programs and Southeast Asia's home healthcare expansion concentrate pen injector demand for this formulation.
- Regular Insulin:Short-acting crystalline zinc insulin suspension for intravenous and subcutaneous administration.
- NPH Insulin:Neutral Protamine Hagedorn intermediate-acting formulation with protamine complexation.
- Insulin Glulisine:Ultra-rapid analog with B3 lysine and B29 glutamic acid substitutions.
By volume, Regular Insulin leads. By growth pace, Insulin Lispro is expanding most quickly.
Therapy Area:
Cost tier stratification separates acute hospital management from chronic outpatient maintenance, with reimbursement intensity varying by diabetes classification.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring exogenous insulin for survival. Indonesia's JKN program expansion and Saudi Arabia's SFDA pediatric formulary updates are accelerating analog insulin access in national health systems.
- Type 2 Diabetes:Progressive insulin resistance with relative deficiency. India's PLI scheme domestic manufacturing and China's NMPA volume-based procurement are reshaping public hospital supply contracts for this largest-addressable population.
- Gestational Diabetes:Glucose intolerance first recognized during pregnancy.
- Latent Autoimmune Diabetes:Adult-onset autoimmune phenotype with slower progression.
- Diabetes Insipidus:Neurohypophyseal vasopressin deficiency unrelated to glycemic control.
Type 2 Diabetes captures the largest patient population. Type 1 Diabetes is gaining share fastest as closed-loop pump systems proliferate.
End User:
Customer type determines cold chain sophistication, with hospital networks requiring bulk cold storage and home healthcare emphasizing patient-portable temperature stability.
- Hospitals:Acute care facilities managing diabetic ketoacidosis and perioperative glycemic control. São Paulo's state hospital network consolidated purchasing and Mexico's IMSS direct-to-clinic contracts are eliminating regional distributor markups in Latin America.
- Home Healthcare:Patient-administered therapy with adherence monitoring. Germany's Techniker Krankenkasse and Japan's reimbursement codes now cover Bluetooth-enabled dose tracking devices, opening data monetization channels for payers.
- Clinics:Outpatient settings for stable patient monitoring.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited pharmacy infrastructure.
- Diagnostic Laboratories:Glucose tolerance testing and HbA1c monitoring sites.
Hospitals dominate procurement volumes. Home Healthcare shows the steepest expansion trajectory as pen injector formats proliferate.
Delivery Mode:
Supply concentration in pen manufacturing equipment creates margin pressure on vial-syringe formats, with device miniaturization compressing cost barriers.
- Pen Injector:Multi-dose disposable or reusable devices with dose-dialing mechanisms. Brazil's SUS conversion programs and Southeast Asia's patient adherence initiatives are displacing vial-based therapy in public health systems.
- Vial:Multi-dose glass containers for syringe withdrawal. India's CDSCO facility inspection backlogs and cold chain infrastructure gaps across sub-Saharan Africa limit analog shelf stability for this cost-sensitive format.
- Cartridge:Pen-compatible 3ml containers for reusable device systems.
- Pump:Continuous subcutaneous insulin infusion devices with algorithmic dosing.
- Pre-filled Syringe:Single-use fixed-dose administration for emergency settings.
Vial formats retain volume leadership in emerging markets. Pen Injector formats are climbing the fastest as reimbursement coverage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant insulin manufacturing clusters in Denmark, India, and China supply formulation facilities across three continents. National health insurance expansions and biosimilar substitution policies are redrawing procurement geography faster than production relocation.
United States
Medicaid rebate negotiations and Medicare Part D redesign are compressing list prices for rapid-acting analogs. FDA interchangeability guidance for biosimilar insulins is forcing state pharmacy boards toward automatic substitution protocols. Indianapolis anchors domestic formulation capacity for originator molecules.
India
CDSCO pre-approval inspection backlogs are delaying biosimilar plant certifications by 12-18 months despite PLI scheme subsidies. Gujarat and Maharashtra recombinant DNA facilities are attracting contract manufacturing organizations from Western Europe. Hospital procurement of domestically produced analogs is accelerating as import substitution targets tighten.
Germany
Techniker Krankenkasse reimbursement codes now cover Bluetooth-enabled insulin pens, opening adherence data monetization for sickness funds. EMA pending guidance on automatic pharmacist substitution creates formulary uncertainty across Länder hospital networks. Baden-Württemberg medical device clusters are miniaturizing disposable electronic components for smart pen formats.
Brazil
SUS conversion programs are displacing vial-based diabetes therapy with pen injector formats in public health systems. Direct-to-clinic distribution models in São Paulo's state hospital network are eliminating regional distributor markups through annual volume commitments. ANVISA accelerated pathways for biosimilar insulins are compressing approval timelines for Asian-origin products.
China
NMPA volume-based procurement is reshaping public hospital supply contracts for Type 2 diabetes populations. Yangtze River Delta bioprocessing clusters concentrate active pharmaceutical ingredient production for recombinant insulin. GB standards on import quality thresholds are tightening as domestic manufacturing scale expands under centralized purchasing.
Human Insulin Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with originator molecule specialists defending premium positioning against biosimilar volume manufacturers. The market structures around three tiers: European-origin innovators with full analog portfolios, Asian contract manufacturers leveraging PLI subsidies and scale, and regional formulation specialists capturing tender-based procurement. Consolidation pressure is concentrating pen device engineering capabilities while backward integration into recombinant fermentation is lengthening manufacturing expansion timelines.
Among Danish and European-origin innovators, Novo Nordisk A/S and Sanofi S.A. occupy positions defining formulation standards for rapid-acting and long-acting analogs. Eli Lilly and Company anchors the US-origin archetype with specialization in lispro molecule development. At the volume manufacturing tier, Tonghua Dongbao Pharmaceutical Co., Ltd. exemplifies Asia-Pacific production concentration for regional distribution networks.
| Leading Market Players |
|---|
| Biocon Biologics Ltd |
| Tonghua Dongbao Pharmaceutical Co., Ltd. |
| Novo Nordisk A/S |
| Gan & Lee Pharmaceuticals |
| Julphar |
| Sanofi S.A. |
| Wockhardt Ltd |
| Zhuhai United Laboratories Co., Ltd. |
| Eli Lilly and Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between hospital procurement consortia and biosimilar manufacturers lock in both supply access and price visibility across India's PLI-subsidized production clusters and Brazil's SUS conversion programs, compressing margin volatility for originator molecules while anchoring volume commitments for emerging market entrants.
Pricing Analysis
EMA interchangeability guidance dictates the pricing tier structure for biosimilar insulin substitution across EU member states, forcing three-tier pricing stratification across premium originator analogs, certified interchangeable biosimilars, and economy vial formats. Price differentiation rests on FDA bioequivalence certification tier and connected pen device bundling. Cost compression in rapid-acting lispro segments intensifies as multiple interchangeable candidates approach approval. Public hospital procurement in India and Brazil shows highest price sensitivity; Japan's reimbursement panels and Germany's sickness funds demonstrate lowest sensitivity to device premiums.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement networks in Germany and Japan, while strategic stockpiling prevails across India's CDSCO-inspected facilities and Brazil's SUS distribution hubs to buffer against cold chain disruption. API production draws from China, South Korea, and India, with recombinant DNA fermentation capacity concentrating in Gujarat and Maharashtra. Single-source vulnerability in bioprocessing equipment creates exposure for Western formulation facilities. Distribution runs through direct-to-clinic contracts in São Paulo and consolidated purchasing agreements in Mexico's IMSS network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected pen device services and adherence data monetization layers are expanding faster than insulin molecule manufacturing, creating recurring-revenue architectures that outpace hardware margins across Germany's Techniker Krankenkasse and Japan's reimbursement codes.
For Market Incumbents: Consolidate pen device engineering capabilities through captive production of Bluetooth-enabled dose tracking components, defending against biosimilar volume manufacturers capturing tender-based procurement in India and Southeast Asia. Backward integration into recombinant fermentation capacity in Denmark and North Carolina lengthens manufacturing timelines but secures API supply continuity against geopolitical exposure in China and South Korea. For New Entrants and Emerging Players: Lead with rapid-acting insulin lispro formulations calibrated to closed-loop artificial pancreas algorithms, targeting Indonesia's JKN expansion and Saudi Arabia's SFDA pediatric formulary updates where reimbursement infrastructure is newly established. Direct-to-clinic distribution partnerships with São Paulo's state hospital network bypass wholesale intermediaries and eliminate regional distributor markups. For Investors and Strategic Acquirers: Contract manufacturing organizations with CDSCO pre-approval inspection clearances and PLI scheme subsidies represent the most defensible acquisition archetype for exposure to India's domestic production scale. Watch EMA automatic substitution guidance finalization as the inflection signal for originator analog margin compression across European hospital formularies.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Pre-Approval Inspection Clearance | Accelerates biosimilar plant certifications by resolving India's 12-18 month facility inspection backlogs. |
| Connected Pen Device Reimbursement Strategy | Secures Techniker Krankenkasse and Japan sickness fund coverage for Bluetooth-enabled dose tracking. |
| Direct-to-Clinic Distribution Partnership | Eliminates regional distributor markups in São Paulo's consolidated hospital purchasing network. |
| API Backward Integration | Captures recombinant DNA fermentation capacity in Gujarat and Maharashtra under PLI subsidies. |
| Closed-Loop Algorithm Calibration | Aligns rapid-acting lispro formulations with sensor-augmented pump systems in Type 1 Diabetes. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across hospital procurement managers, formulary directors at Germany's sickness funds, CDSCO regulatory affairs leads, and bioprocessing engineers at contract manufacturing organizations. Secondary validation drew from FDA 505(b)(2) filings, EMA biosimilar submission databases, India's PLI scheme disclosure records, and Brazil's SUS tender documentation. Bottom-up volume modeling triangulated against top-down market sizing across pen injector device shipments and vial production volumes.
Across the analysis window, the forecast framework modeled insulin segmentation by product type, delivery mode, therapy area, and end-user channel, with regional regulatory clusters treated as distinct adoption curves. CAGRs derived from patient population growth, reimbursement expansion velocity, and biosimilar substitution policy implementation timelines. Specific inputs included Indonesia's JKN coverage expansion rates and China's NMPA volume-based procurement contract values.
The analysis sits within stated boundaries; outcomes outside EMA interchangeability guidance finalization, CDSCO inspection staffing resolutions, or sustained PLI subsidy continuity would require recalibration. Revision becomes warranted when biosimilar substitution policy crosses automatic pharmacist threshold levels across EU member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
6-Azauracil Market