
 Insulin Secretagogues Market | 2026-2036
Insulin Secretagogues Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Secretagogues Market Foresight
Next-generation cardiovascular safety profiling is reorganizing competitive priorities among insulin secretagogue developers. Novo Nordisk leads GLP-1 receptor agonist innovation with sustained R&D investment in cardioprotective efficacy endpoints. Sanofi leverages its European manufacturing footprint to anchor supply security for sulfonylurea formulations across hospital networks.
Insulin secretagogues comprise pharmacological agents that stimulate endogenous pancreatic beta-cell insulin release through distinct receptor-mediated mechanisms, with sulfonylureas binding SUR1 subunits of KATP channels and meglitinides operating through similar but shorter-acting pathways. DPP-4 inhibitors dominate current prescribing patterns due to favorable hypoglycemia risk profiles, while GLP-1 agonists capture accelerating demand in Type 2 diabetes management driven by demonstrable cardiovascular mortality reduction. Oral delivery modes retain the largest patient volume base, though smart device integration in injectable segments commands premium positioning.
FDA cardiovascular outcome trial mandates and EMA's periodic safety update reporting requirements shape clinical trial investment and post-market surveillance obligations for developers. China's NMPA streamlined review pathways for domestically manufactured meglitinides accelerate market access for Beijing Beilu Pharmaceutical and Wanbang Biopharma. Stakeholders must monitor evolving reimbursement thresholds for GLP-1 agonists against tightening glycemic control benchmarks in major health systems.

Market Dynamics
FDA cardiovascular outcome trial mandates are restructuring clinical development economics for insulin secretagogue developers, forcing resource reallocation toward long-term safety endpoints and away from traditional glycemic efficacy studies. This regulatory pivot compresses development timelines for cardioprotective agents while extending them for conventional sulfonylureas.
Growth Catalysts
- Hospital-based diabetes management programs:United States hospital networks are expanding formulary inclusion of GLP-1 receptor agonists within integrated care pathways, creating institutional demand pull through bundled reimbursement structures.
- NMPA streamlined review pathways:China's domestic meglitinide manufacturers benefit from accelerated regulatory timelines, reducing market access barriers for locally produced secretagogues in tier-one urban hospital networks.
- Cardiovascular mortality reduction data:Demonstrable cardioprotective outcomes from GLP-1 agonist trials are reshaping prescriber preference hierarchies in Type 2 diabetes management protocols.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for sulfonylurea formulations clusters in specific Asian manufacturing zones, exposing formulation specialists to single-source dependency risks.
- Hypoglycemia liability thresholds:EMA periodic safety update reporting requirements impose ongoing surveillance burdens on sulfonylurea marketers, elevating post-market compliance costs relative to DPP-4 inhibitors.
- GLP-1 agonist substitution pressure:Injectable cardioprotective agents are capturing patient volumes previously managed with oral secretagogues, compressing addressable market scope for traditional mechanisms.
Strategic Opportunities
- Smart device integration:Connected injection systems for GLP-1 agonists command premium positioning through adherence monitoring capabilities, opening hardware-software revenue stacking models.
- China's urban hospital networks:Rising diabetes prevalence in domestic tier-two and tier-three cities creates volume expansion potential for locally manufactured meglitinide formulations.
- Oral GLP-1 formulation development:Non-injectable delivery mechanisms for incretin mimetics represent unoccupied white space between current injectable GLP-1 agonists and traditional oral secretagogues.
Industry Challenges
- CVOT recruitment and retention:Cardiovascular outcome trial execution demands specialized clinical operations expertise and extended patient monitoring infrastructure that strains mid-cap developer resources.
- Legacy system integration:Hospital pharmacy information systems require substantial reconfiguration to accommodate smart device data streams and connected therapy workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Secretagogues Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfonylureas, Meglitinides, DPP-4 Inhibitors, GLP-1 Agonists Therapy Area: Type 2 Diabetes, Gestational Diabetes, Prediabetes, Hypoglycemia Delivery Mode: Oral, Injectable, Continuous Infusion, Smart Devices End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Sanofi, Novo Nordisk, Eli Lilly and Company, Merck & Co., Boehringer Ingelheim, Beijing Beilu Pharmaceutical, Wanbang Biopharma, Yangtze River Pharmaceutical Group, CSPC OUYI Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Secretagogues Market Shifts & Advancements
Connected drug delivery platforms are redefining competitive differentiation in the insulin secretagogue landscape, shifting value capture from molecule exclusivity toward integrated therapy ecosystems. Device-generated adherence data is becoming a core input for payer contracting negotiations.
Continuous glucose monitoring integration with smart insulin pens is displacing conventional self-monitoring blood glucose protocols in intensive diabetes management. Endocrinology practices in the United States are adopting these systems at accelerating rates. The technology is displacing legacy dose-titration methods that relied on patient-reported glucose logs.
EMA's tightened periodic safety update reporting requirements for sulfonylurea-containing products are extending pharmacovigilance obligations across the product lifecycle. Manufacturers must now maintain active surveillance infrastructure for hypoglycemia signal detection beyond initial marketing authorization. European hospital formularies are responding by elevating DPP-4 inhibitors in therapeutic positioning hierarchies.
Hospital procurement committees are consolidating vendor relationships for diabetes therapeutics around integrated supply agreements that bundle devices, consumables, and pharmaceuticals. Group purchasing organizations are replacing fragmented hospital-level contracting in the United States. This concentration is most visible in integrated delivery networks spanning multiple states.
Insulin Secretagogues Market Segmentation
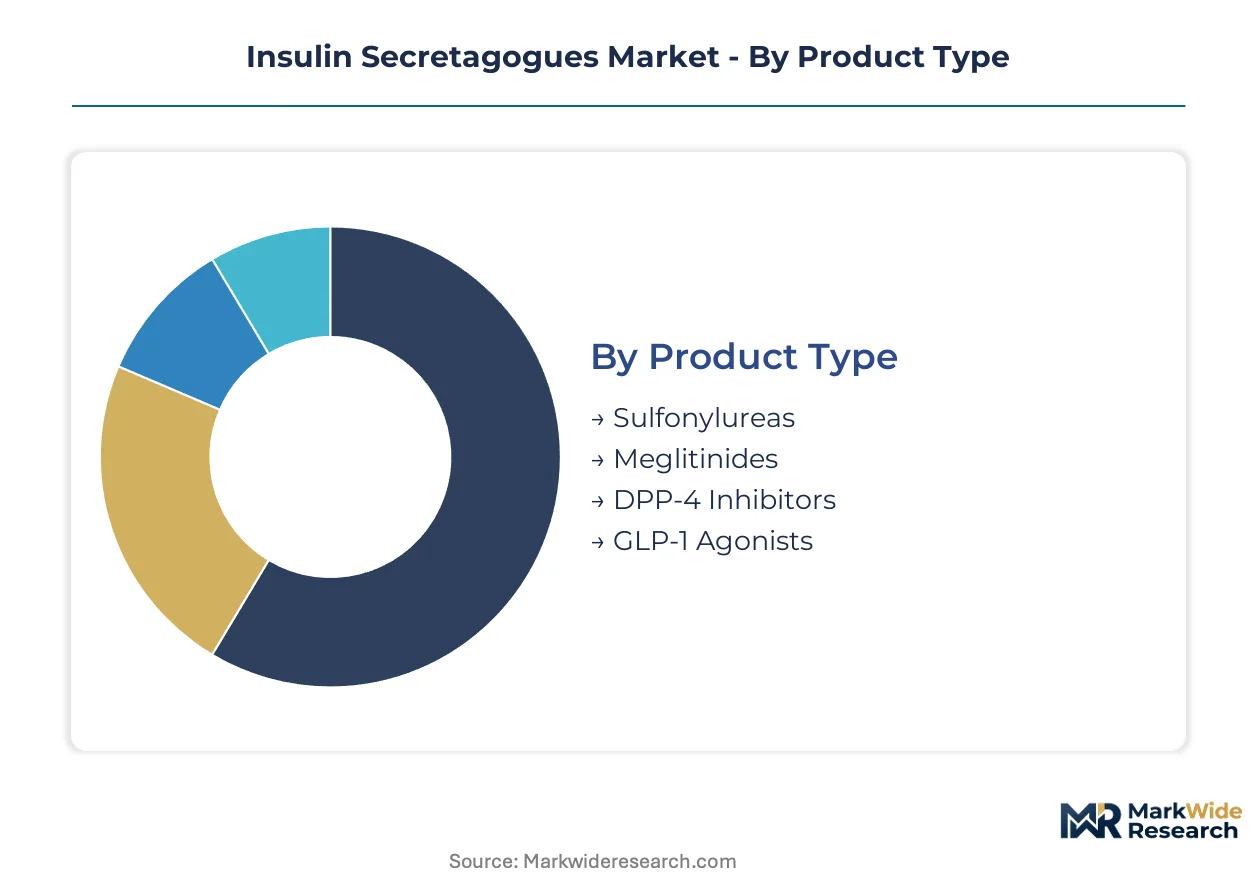
Insulin secretagogue prescribing patterns fragment sharply across mechanism classes and care settings, with reimbursement tiers and cardiovascular safety profiles driving physician selection hierarchies. Understanding these segment boundaries clarifies where formulation innovation, delivery technology, and channel economics create divergent competitive arenas.
Product Type:
FDA cardiovascular outcome trial mandates and EMA periodic safety updates have split this category into cardioprotective leaders and legacy agents carrying elevated surveillance burdens.
- GLP-1 Agonists:Injectable incretin mimetics demonstrate measurable cardiovascular mortality reduction in Type 2 diabetes populations. United States hospital formularies are elevating these agents within bundled diabetes management programs as cardioprotective efficacy data reshapes prescriber hierarchies.
- DPP-4 Inhibitors:Oral dipeptidyl peptidase-4 blockers offer favorable hypoglycemia risk profiles compared to sulfonylureas. China's urban hospital networks are expanding formulary access for these agents as domestic manufacturers scale production under NMPA streamlined review pathways.
- Sulfonylureas:ATP-sensitive potassium channel blockers remain the lowest-cost oral secretagogue option despite hypoglycemia liability.
- Meglitinides:Short-acting insulin secretagogues with rapid onset and shorter duration suit prandial glucose control.
DPP-4 inhibitors handle the majority of throughput; GLP-1 agonists are climbing the fastest on share.
Therapy Area:
Patient population characteristics determine dosing flexibility requirements and the acceptable trade-off between glycemic control intensity and hypoglycemia risk.
- Type 2 Diabetes:Progressive beta-cell dysfunction in this population creates sustained demand for secretagogue therapy across disease stages. United States integrated delivery networks are consolidating procurement around agents with demonstrated cardiovascular outcomes.
- Gestational Diabetes:Pregnancy-specific glycemic targets limit therapeutic options to agents with established maternal-fetal safety profiles. Clinics in tier-one Chinese cities are expanding screening programs that identify candidates for pharmacological intervention.
- Prediabetes:Pre-diagnostic glucose dysregulation represents a prevention-focused segment with limited pharmacological penetration.
- Hypoglycemia:Iatrogenic low glucose events drive agent switching and inform formulary exclusion decisions.
Type 2 Diabetes generates the dominant volume base; Gestational Diabetes is expanding most quickly as screening intensifies.
Delivery Mode:
Patient adherence economics and reimbursement complexity separate high-touch device-mediated administration from self-managed oral regimens.
- Oral:Tablet and capsule formulations retain the largest patient volume base due to self-administration convenience and lower per-dose cost. Pharmacies in China's tier-two cities are expanding distribution networks for domestically manufactured oral secretagogues.
- Injectable:Subcutaneous delivery of GLP-1 agonists commands premium positioning through demonstrable cardiovascular benefits. United States hospital networks are integrating these agents into step-therapy protocols for high-risk patients.
- Continuous Infusion:Pump-based insulin delivery systems occupy specialized niches requiring intensive monitoring infrastructure.
- Smart Devices:Connected injection systems with adherence monitoring capabilities create hardware-software revenue stacking opportunities.
Oral delivery handles the majority of throughput; Smart Devices are gaining share fastest through premium contracting.
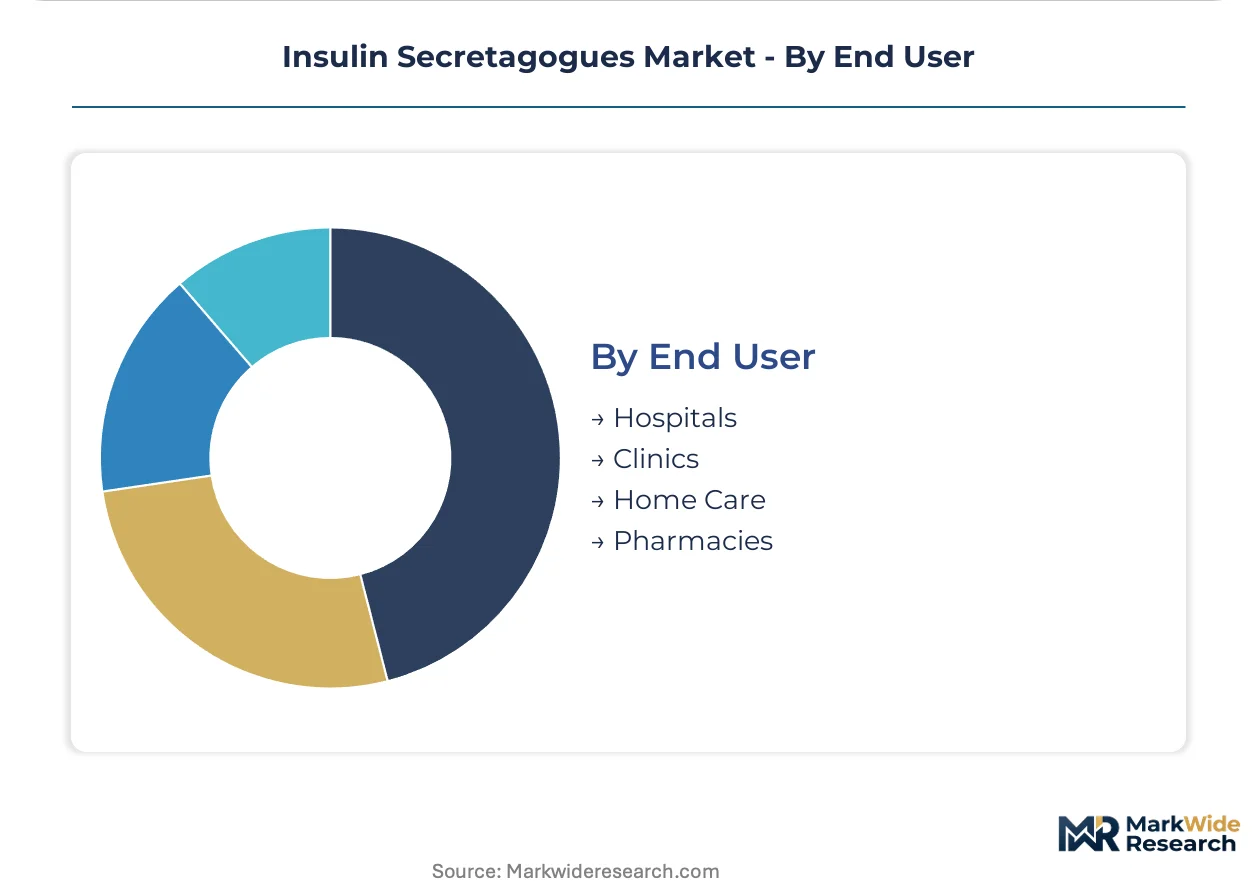
End User:
Procurement authority and patient acuity determine whether volume concentrates in institutional formulary decisions or disperses across retail channels.
- Hospitals:Institutional pharmacy committees control formulary placement for inpatient and outpatient diabetes management. United States group purchasing organizations are consolidating vendor relationships around integrated supply agreements bundling devices and pharmaceuticals.
- Clinics:Outpatient endocrinology practices drive GLP-1 agonist adoption through continuous glucose monitoring integration.
- Home Care:Self-administered therapy management shifts volume toward oral agents with simpler titration protocols.
- Pharmacies:Retail dispensing channels capture recurring prescription volume for maintenance therapy refills.
Hospitals anchor institutional demand; Clinics are expanding most quickly as ambulatory diabetes management intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports active pharmaceutical ingredients for sulfonylurea formulations to formulation specialists in Germany and the United States, anchoring a trade corridor that supplies hospital networks across North America and Europe.
United States
Hospital-based diabetes management programs and integrated delivery networks drive institutional demand for GLP-1 receptor agonists. FDA cardiovascular outcome trial mandates reshape prescriber hierarchies toward cardioprotective agents. Boston and Minneapolis anchor clinical trial operations for long-term safety endpoint studies.
Germany
EMA periodic safety update reporting requirements elevate post-market surveillance obligations for sulfonylurea marketers. German hospital formularies respond by elevating DPP-4 inhibitors in therapeutic positioning hierarchies. The Rhine-Ruhr region concentrates pharmacovigilance infrastructure for hypoglycemia signal detection.
China
Rising diabetes prevalence in tier-two and tier-three cities expands volume potential for domestically manufactured meglitinides. NMPA streamlined review pathways accelerate market access for Beijing Beilu Pharmaceutical and Wanbang Biopharma. Shanghai and Beijing anchor urban hospital networks where formulary inclusion decisions concentrate.
Japan
PMDA guidelines emphasize cardiovascular safety profiling in Type 2 diabetes therapy selection. METI industrial policy supports domestic pharmaceutical production scaling for oral secretagogue formulations. The Kanto region around Tokyo hosts endocrinology practices adopting continuous glucose monitoring integration.
India
CDSCO regulatory frameworks govern market authorization for insulin secretagogue imports and domestic manufacturing. Rising Type 2 diabetes prevalence in urban centers creates demand for affordable oral hypoglycemic agents. Mumbai and Hyderabad anchor pharmaceutical formulation clusters serving hospital procurement committees.
Insulin Secretagogues Market Competitive Landscape
Listed leaders compete with private specialists across cardiovascular safety credentialing and hospital formulary access. The market structure tiers around molecule exclusivity, manufacturing scale, and integrated device capabilities. Three archetypes dominate: multinational pharmaceutical conglomerates with cardioprotective portfolios, regional generics manufacturers with cost-optimized sulfonylurea production, and emerging domestic specialists leveraging streamlined regulatory pathways. Competitive moves concentrate on strategic partnerships for smart device integration and geographic expansion into China's urban hospital networks.
Within the multinational tier, Sanofi and Novo Nordisk exemplify divergent strategic positioning around delivery technology and cardiovascular outcome differentiation. Among China-based specialists, Beijing Beilu Pharmaceutical occupies a position representing domestic meglitinide production scaling under NMPA accelerated review frameworks. These anchors illustrate how regulatory pathway access and manufacturing geography shape competitive archetype boundaries.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk |
| Eli Lilly and Company |
| Merck & Co. |
| Boehringer Ingelheim |
| Beijing Beilu Pharmaceutical |
| Wanbang Biopharma |
| Yangtze River Pharmaceutical Group |
| CSPC OUYI Pharmaceutical |
| Others |
Supply & Pricing Matrix
GLP-1 agonist displacement of sulfonylureas in United States hospital formularies simultaneously redistributes API sourcing toward Chinese biotechnology zones and compresses pricing power for legacy oral secretagogue manufacturers. This substitution dynamic concentrates procurement leverage among integrated delivery networks while fragmenting residual demand across cost-optimized generic channels.
Pricing Analysis
Injectable GLP-1 agonists command substantial premiums over oral DPP-4 inhibitors and sulfonylureas, with smart device-enabled delivery systems occupying the highest pricing tier. Three-tier pricing structure across premium, standard, and economy levels separates connected injection systems from conventional prefilled pens and unbranded oral tablets. Cost compression in the sulfonylurea tier is intensifying because China's NMPA accelerated review pathways flood tier-two cities with domestically manufactured meglitinides. Hospital procurement committees demonstrate lowest price sensitivity for cardioprotective agents with demonstrated cardiovascular outcomes, while retail pharmacies face acute margin pressure on legacy oral secretagogues.
Supply Chain Analysis
Inventory lead times for GLP-1 agonist active pharmaceutical ingredients stretch longer than oral secretagogue replenishment cycles due to complex peptide synthesis requirements and cold-chain distribution mandates. API production draws from China, India, and South Korea for sulfonylurea intermediates, while GLP-1 peptide manufacturing concentrates in Denmark and the United States. Single-source vulnerability pervades the incretin mimetic segment where specialized bioreactor capacity remains limited to a handful of contract manufacturing organizations. Distribution runs through hospital group purchasing organizations in North America and tier-one urban hospital networks in China, with retail pharmacy chains capturing residual oral agent volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulin secretagogue market sits in a cyclical recovery phase driven by cardiovascular outcome trial data that resurrects prescriber confidence in pharmacological diabetes management. Hospital formulary consolidation around cardioprotective agents creates temporary margin expansion for innovators before generic substitution compresses returns.
For Market Incumbents: Shield formulary position in United States integrated delivery networks by securing exclusive smart device supply agreements that bundle adherence monitoring with pharmaceutical procurement. Deepen backward integration into peptide API production to reduce dependency on single-source contract manufacturers for GLP-1 agonist active ingredients. Accelerate cardiovascular outcome trial completion for next-generation oral incretin mimetics before FDA mandates tighten further. For New Entrants and Emerging Players: Anchor in China's tier-two and tier-three urban hospital networks where NMPA streamlined review pathways reduce regulatory barriers for domestically manufactured meglitinides. Target gestational diabetes as the most penetrable therapeutic segment given limited pharmacological options and expanding screening programs in tier-one Chinese cities. Pursue licensing partnerships with established device manufacturers to bypass capital-intensive smart injection system development. For Investors and Strategic Acquirers: The market sits at a late-expansion phase that favors acquisition of cardiovascular safety credentialing capabilities over de novo development. Long-term viability through the next decade hinges on positioning ahead of oral GLP-1 formulation breakthroughs that would displace injectable incumbents. Target domestic Chinese specialists with NMPA accelerated pathway experience and established tier-two hospital distribution. Watch FDA guidance on cardiovascular outcome trial design as the critical inflection signal for development economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | EMA and FDA mandates reshape competitive hierarchy toward cardioprotective efficacy endpoints. |
| Smart Device Integration Partnership | Connected injection systems with adherence monitoring command premium hospital contracting terms. |
| China NMPA Streamlined Pathway Utilization | Accelerated review timelines reduce market access barriers for domestically manufactured meglitinides. |
| Backward Integration into Peptide API Production | In-house bioreactor capacity mitigates single-source dependency risks for GLP-1 agonist supply. |
| Hospital System Bundled Supply Agreement | Group purchasing organization consolidation favors integrated device-pharmaceutical vendors. |
Research Methodology
Desk research of FDA cardiovascular outcome trial filings, EMA periodic safety update reports, ClinicalTrials.gov registries, and China NMPA approval databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Primary fieldwork with procurement managers at United States integrated delivery networks and tier-one Chinese urban hospitals validated secondary intelligence on pricing dynamics and supply chain configuration. Bottom-up patient volume modeling across mechanism classes and administration routes triangulated against top-down pharmaceutical revenue estimates.
Variance decomposition across product type, therapy area, delivery mode, and end user segments anchored the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and pricing elasticity assumptions incorporated cardiovascular outcome trial completion timelines and NMPA regulatory pathway acceleration effects. Forecast inputs included hospital formulary placement probabilities, smart device adoption curves in United States endocrinology practices, and domestic Chinese manufacturer capacity expansion plans.
Material uncertainties — regulatory guidance revisions on cardiovascular safety endpoints, API supply disruptions from manufacturing zone concentration, and GLP-1 oral formulation breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about prescriber behavior shifts and reimbursement threshold stability that could require substantial revision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market