
 3D Cell Culture Market | 2026-2036
3D Cell Culture Market Size, Share, and Industry Trends Forecast 2026-2036
3D Cell Culture Market Intelligence
Adherence to ISO 10993 biocompatibility standards is collapsing the divide between research-grade and clinical-grade biomaterials. Corning Incorporated specializes in advanced glass surfaces and extracellular matrix coatings for scaffolds. Thermo Fisher Scientific leverages its extensive portfolio of reagents and instrumentation for cell analysis. Merck KGaA competes through its comprehensive offering of cell culture media and bioprocessing technologies.
3D cell culture comprises methods that enable cells to grow in vitro within three-dimensional structures that mimic native tissue architecture. These systems often incorporate hydrogels or scaffolds made from materials like collagen or synthetic polymers. Their primary purpose is to create more physiologically relevant models for preclinical research. Scaffold-based products lead the market, but scaffold-free techniques like spheroid culture are gaining share in high-throughput screening for drug discovery.
Regulatory bodies including the US FDA and the European Medicines Agency (EMA) influence market adoption through their guidance on preclinical testing. The FDA Modernization Act 2.0, for instance, explicitly encourages alternatives to animal testing, creating opportunities for qualified 3D models. The central decision for developers is balancing the scalability of spheroid platforms with the predictive accuracy of complex organ-on-a-chip systems.
Market Dynamics
The imperative to develop alternatives to animal testing, codified by policies like the FDA Modernization Act 2.0, is the central force shaping the 3D cell culture market. This regulatory pressure accelerates the validation and adoption of more physiologically relevant in vitro models.
Growth Catalysts
- Regulatory Mandates:Policies from the US FDA and EMA encouraging non-animal testing methods directly stimulate demand from pharmaceutical and biotechnology firms for qualified 3D models in preclinical drug development and safety assessment.
- Organ-on-a-Chip Maturation:Advances in microfluidics and tissue engineering are yielding more predictive organ-on-a-chip systems, attracting significant R&D investment for complex disease modeling and personalized medicine applications within major biotechnology clusters.
- High-Throughput Screening:The scalability of spheroid and other scaffold-free techniques makes them suitable for high-throughput screening in drug discovery, meeting the needs of large pharmaceutical companies for rapid compound evaluation.
Market Restraints
- High Implementation Cost:The significant expense associated with specialized instrumentation, culture media, growth factors, and scaffolds restricts adoption, particularly among academic institutions and smaller biotechnology companies with limited budgets.
- Lack of Standardization:A deficit of universally accepted protocols for creating, maintaining, and analyzing 3D cultures leads to issues with reproducibility and data variability, slowing regulatory acceptance and cross-study comparisons.
- Technical Complexity:The intricate techniques required to culture and analyze 3D models, especially complex organoids, demand specialized expertise that is not widely available, creating a skills gap that hinders broader market penetration.
Strategic Opportunities
- Toxicology Testing Expansion:Growing restrictions on animal testing for cosmetics and chemicals, particularly in the European Union, create a substantial opportunity for 3D skin, corneal, and liver models as validated alternatives.
- AI-Powered Analytics:Integrating artificial intelligence and machine learning with high-content imaging of 3D cultures offers a pathway to automate complex analysis, identify novel biomarkers, and improve the predictive power of preclinical assays.
- Personalized Medicine:The use of patient-derived cells to create 3D organoids or tumoroids for testing individual drug responses represents a significant opportunity in oncology and rare diseases, enabling tailored therapeutic strategies.
Industry Challenges
- Scalability of Complex Models:While spheroid models are scalable, more complex organoid and organ-on-a-chip systems face significant hurdles in achieving the throughput required for large-scale pharmaceutical screening campaigns.
- Validation and Qualification Hurdles:The process of validating a 3D model as a replacement for a conventional animal test is lengthy and resource-intensive, requiring extensive data to convince regulatory bodies like the FDA or EMA.
- Data Management Infrastructure:The shift to high-content imaging and analysis of 3D cultures generates massive datasets that require sophisticated bioinformatics and data storage solutions, which many labs are not equipped to handle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Cell Culture Market |
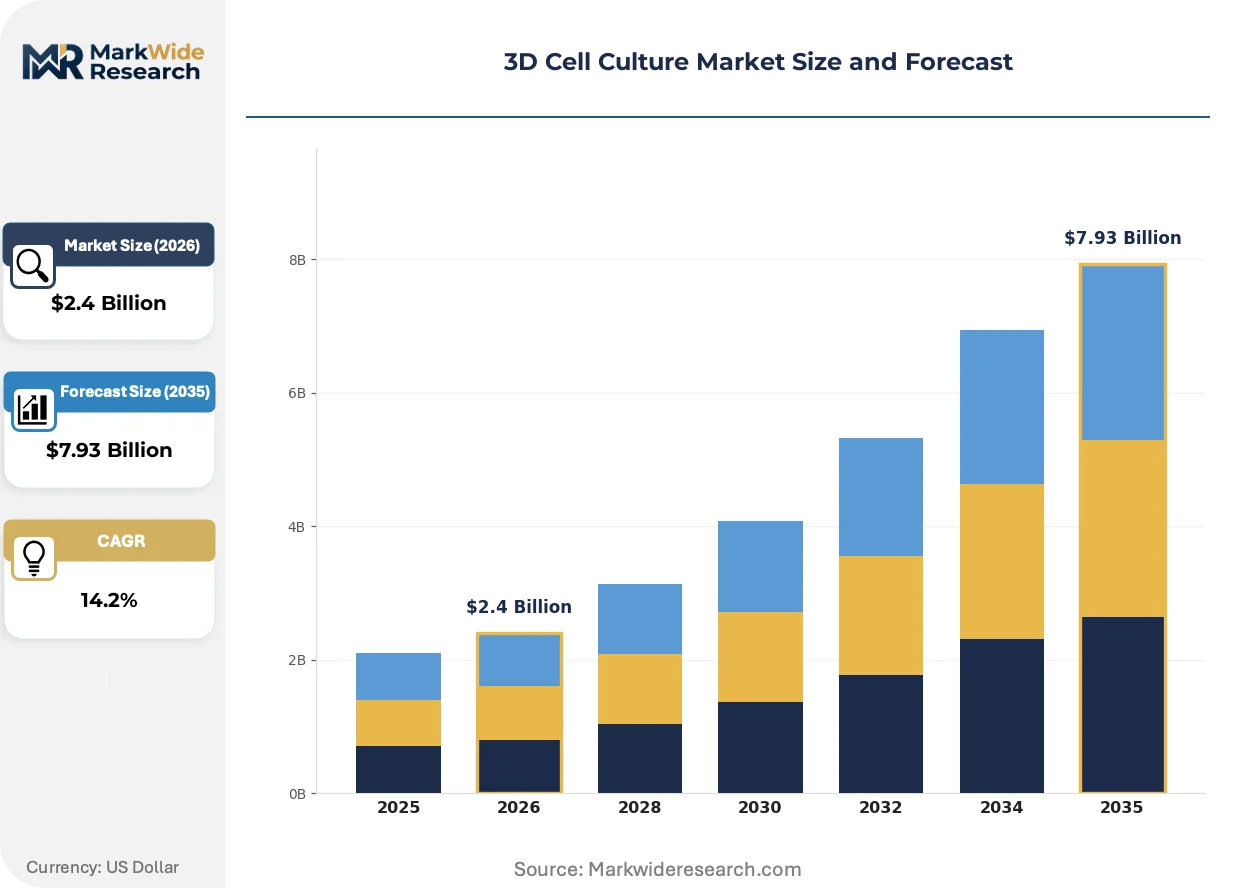
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.93 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffold-Based, Scaffold-Free, Bioreactors, Microcarriers, Hydrogels Technology: Hydrogel encapsulation, Spheroid culture, Organ-on-a-chip, Bioprinting, Microfluidics Application: Drug Discovery, Toxicology Testing, Stem Cell Research, Cancer Modeling, Tissue Engineering End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations, Regenerative Medicine Labs |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Corning Incorporated, Lonza, Sartorius AG, Tecan Trading AG, Avantor, Inc., InSphero, REPROCELL Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Cell Culture Market Strategic Shifts & Innovations
A fundamental shift toward greater physiological relevance is defining innovation in 3D cell culture. This involves moving beyond simple spheroids to more structured, functional tissues, a transition enabled by advances in biomaterials, microfluidics, and automated imaging platforms.
3D bioprinting enables the precise spatial arrangement of cells, biomaterials, and growth factors to construct intricate, tissue-like structures. Pharmaceutical developers and academic researchers are adopting this technology to build more accurate models for studying complex diseases like cancer. The availability of more accessible bioprinters is fragmenting the market away from a universal reliance on generic scaffolds and toward user-defined, application-specific tissue constructs.
The FDA Modernization Act 2.0 in the United States is a landmark policy shift that explicitly authorizes the use of certain alternatives to animal testing for drug and biosimilar development. This legislation reduces the perceived regulatory risk for pharmaceutical companies investing in advanced in vitro models. As a result, the drug discovery and toxicology testing segments are accelerating the integration of qualified organ-on-a-chip and organoid platforms into their preclinical workflows.
Research and development teams are increasingly prioritizing quantifiable, multiparametric data over simple qualitative observations from their cell models. This change in demand disrupts the use of basic culture methods and favors platforms that are compatible with automated high-content imaging and analysis. The trend is most visible in pharmaceutical toxicology, where robust, data-rich outputs from 3D liver or cardiac models are essential for making critical safety decisions.
3D Cell Culture Market Segmentation
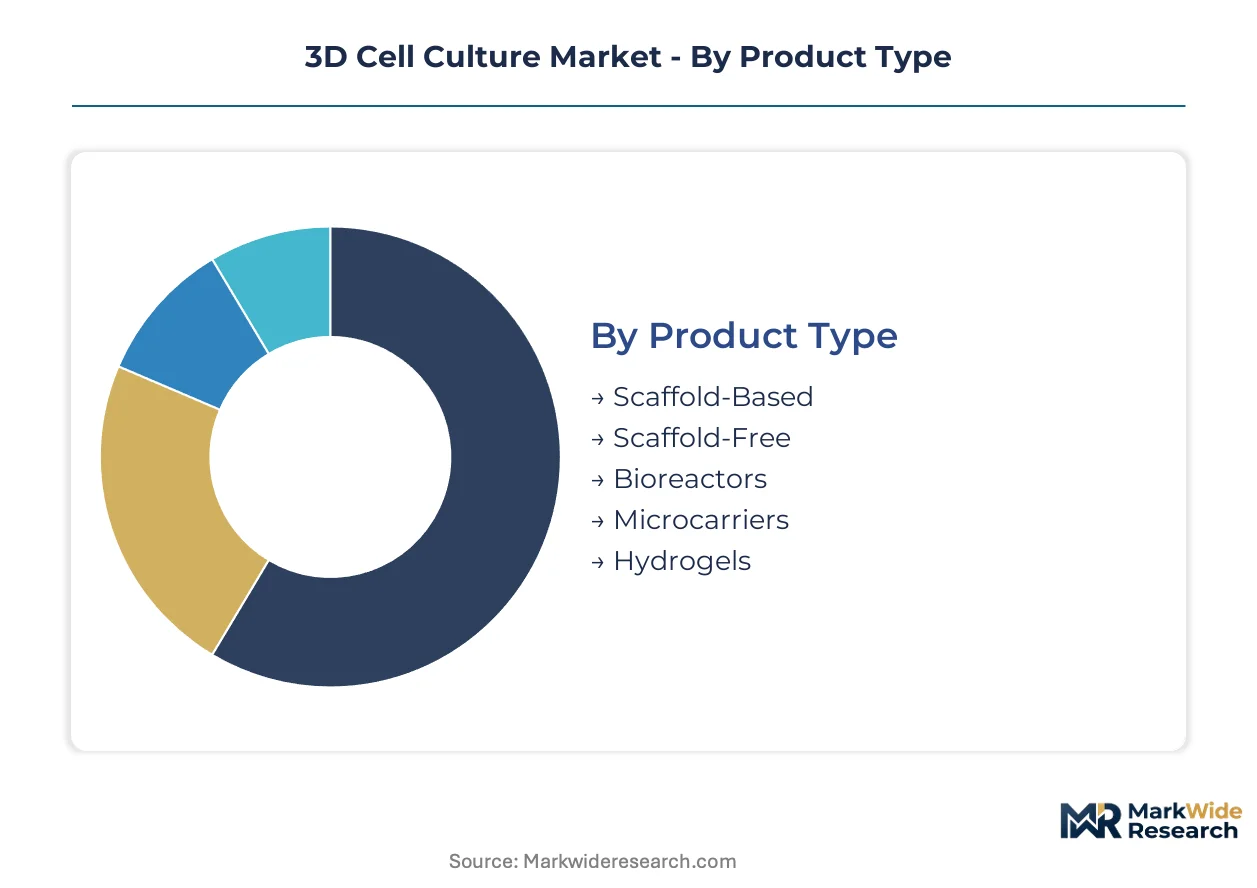
The 3D cell culture market categorizes diverse products, technologies, and applications, reflecting varied end-user needs and research priorities. This segmentation highlights the functional distinctions and commercial drivers influencing market dynamics and adoption patterns across the industry.
Product Type:
Scaffold-based products face substitution pressure from emerging scaffold-free methods and integrated systems offering greater experimental control.
- Scaffold-Based:Scaffold-Based products utilize solid or porous structures, often made from collagen or synthetic polymers, to support cell growth and mimic in vivo extracellular matrix. Demand remains high in academic research and early-stage drug discovery due to their established methodologies and structural integrity.
- Scaffold-Free:Scaffold-Free methods, such as spheroid and organoid cultures, allow cells to self-assemble into 3D structures without external support, offering higher throughput capabilities. Pharmaceutical companies increasingly adopt these models for high-throughput screening in drug discovery due to their scalability.
- Bioreactors:Bioreactors provide dynamic culture environments, controlling parameters like pH and oxygen, crucial for scaling up cell production in bioprocessing.
- Microcarriers:Microcarriers are small beads used in suspension cultures to provide surface area for cell attachment, supporting high-density cell growth in biopharmaceutical manufacturing.
- Hydrogels:Hydrogels are water-swollen polymeric networks providing a soft, tissue-like environment for cell encapsulation and growth, especially in regenerative medicine research.
Scaffold-Based products anchor the volume base while Scaffold-Free techniques gain share at the steepest rate.
Technology:
The choice of 3D cell culture technology directly influences the complexity and physiological relevance of the in vitro models for specific research applications.
- Organ-on-a-chip:Organ-on-a-chip systems integrate microfluidics with engineered tissue constructs to simulate organ-level physiology and function, including vascularization and mechanical forces. Pharmaceutical R&D departments in Germany and the United States adopt these for advanced disease modeling and toxicology testing.
- Bioprinting:Bioprinting enables the precise spatial arrangement of cells, biomaterials, and growth factors using additive manufacturing techniques to create complex 3D tissue constructs. Academic institutions and specialized biotechnology firms use this for creating patient-specific models and tissue engineering applications.
- Hydrogel encapsulation:Hydrogel encapsulation involves embedding cells within a hydrogel matrix, protecting them and providing a soft environment for growth in regenerative medicine.
- Spheroid culture:Spheroid culture allows cells to self-aggregate into compact, spherical 3D structures, widely used for high-throughput drug screening due to simplicity and scalability.
- Microfluidics:Microfluidics involves manipulating small volumes of fluids through micro-channels, enabling precise control over cell microenvironments in organ-on-a-chip and other advanced systems.
Spheroid culture maintains a strong adoption base, while organ-on-a-chip platforms demonstrate rapid expansion in high-value applications.
Application:
Different 3D cell culture applications cater to distinct research needs, influencing the types of models and analytical methods employed by various end-user groups.
- Drug Discovery:Drug Discovery utilizes 3D models to screen novel compounds, identify therapeutic targets, and evaluate efficacy in a more physiologically relevant context than 2D cultures. Pharmaceutical companies globally integrate these models to accelerate lead optimization and reduce preclinical failure rates.
- Toxicology Testing:Toxicology Testing employs 3D models, such as liver and cardiac spheroids, to assess the safety and potential adverse effects of new drugs and chemicals, often as alternatives to animal testing. Regulatory bodies like the US FDA and European Medicines Agency endorse these models, driving their adoption by contract research organizations.
- Stem Cell Research:Stem Cell Research uses 3D cultures to study stem cell differentiation, self-renewal, and tissue regeneration, advancing regenerative medicine and developmental biology.
- Cancer Modeling:Cancer Modeling leverages patient-derived organoids and tumoroids to mimic the tumor microenvironment, enabling personalized oncology and drug resistance studies.
- Tissue Engineering:Tissue Engineering aims to create functional biological tissues for therapeutic purposes or in vitro models, utilizing 3D cell culture techniques to assemble complex structures.
Drug Discovery applications command the largest market share, with Toxicology Testing demonstrating significant growth due to regulatory shifts.
End User:
The cost-effectiveness and technical complexity of 3D cell culture solutions vary significantly across different end-user segments, influencing their adoption patterns.
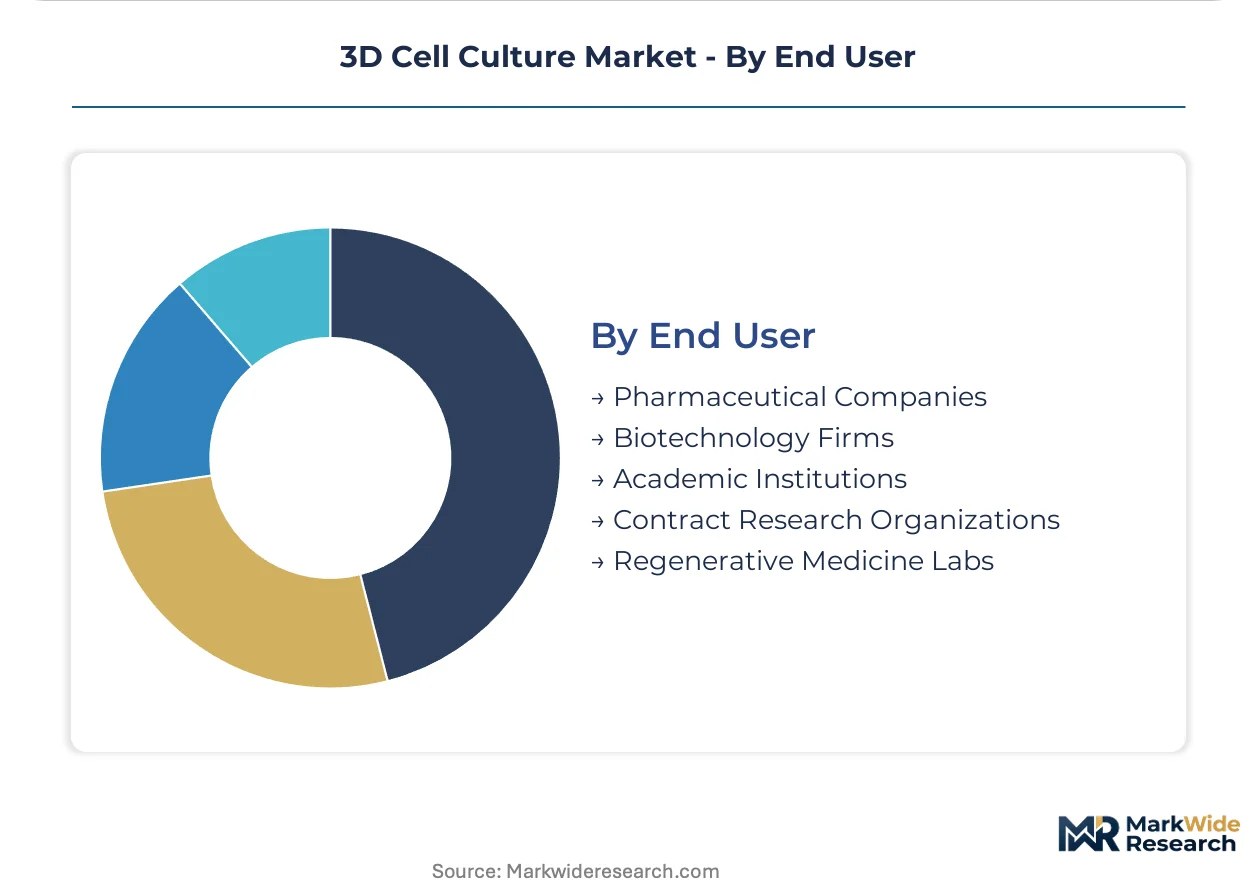
- Pharmaceutical Companies:Pharmaceutical Companies are primary end-users, integrating 3D cell culture models into their preclinical pipelines for drug screening, target validation, and safety assessment. Large pharmaceutical firms in the United States and Japan invest heavily in automated systems for high-throughput applications.
- Biotechnology Firms:Biotechnology Firms, particularly those focused on drug discovery and personalized medicine, adopt advanced 3D culture technologies like organ-on-a-chip and bioprinting. These firms often drive innovation in complex disease modeling and therapeutic development.
- Academic Institutions:Academic Institutions use 3D cell culture for fundamental research, disease mechanism studies, and training, often driven by grant funding and scientific exploration.
- Contract Research Organizations:Contract Research Organizations (CROs) offer 3D cell culture services to pharmaceutical and biotech clients, providing specialized expertise and infrastructure for preclinical testing.
- Regenerative Medicine Labs:Regenerative Medicine Labs utilize 3D cultures for developing tissue constructs, studying cell therapies, and advancing organ repair strategies.
Pharmaceutical Companies represent the most mature segment, while Regenerative Medicine Labs show substantial potential for future expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory initiatives encouraging non-animal testing methods significantly influence 3D cell culture market expansion across diverse geographies. Policies from agencies like the US FDA and European Medicines Agency accelerate the validation and adoption of advanced in vitro models. This global push for ethical and predictive preclinical research drives investment and technological innovation.
United States
United States pharmaceutical companies prioritize 3D models for drug discovery and safety assessment. The FDA Modernization Act 2.0 explicitly supports non-animal testing, accelerating adoption. Major biotechnology hubs in Boston and the San Francisco Bay Area lead in developing complex organoid platforms.
Germany
German pharmaceutical and biotechnology firms increasingly integrate 3D cell culture for advanced disease modeling. European Medicines Agency (EMA) guidelines shape preclinical testing protocols, fostering greater model adoption. Research institutions and biotech clusters in Munich and Berlin focus on developing scalable spheroid systems.
Japan
Japanese companies demonstrate strong interest in 3D cell culture for regenerative medicine and personalized drug screening. The Pharmaceuticals and Medical Devices Agency (PMDA) encourages advanced in vitro models. Research centers in Tokyo and Osaka are pioneering applications in 3D bioprinting and patient-derived organoid technologies.
United Kingdom
United Kingdom academic institutions and contract research organizations widely utilize 3D cell culture for fundamental research. Regulatory frameworks, often aligning with EMA guidance, promote advanced in vitro models. Life sciences clusters around Cambridge and Oxford are centers for developing and validating organ-on-a-chip platforms.
China
Chinese pharmaceutical companies are rapidly adopting 3D cell culture for drug discovery and toxicology testing. The National Medical Products Administration (NMPA) encourages modern preclinical methods. Innovation hubs in Shanghai and Beijing are rapidly expanding capabilities in automated high-throughput screening platforms.
3D Cell Culture Market Key Industry Players
Player mix skews toward established life science suppliers and specialized biotechnology firms. The market exhibits a tiered structure, with large conglomerates offering broad portfolios alongside niche innovators focusing on specific technologies. Strategic archetypes include diversified instrumentation providers, biomaterials specialists, and advanced model developers. Key competitive moves involve technology licensing, strategic partnerships to integrate diverse capabilities, and targeted capacity expansion. Portfolio diversification also remains a common strategy.
Within the diversified instrumentation and reagents tier, Thermo Fisher Scientific Inc. exemplifies a broad portfolio approach, leveraging its extensive product range for cell analysis. German-based Merck KGaA occupies a position as a comprehensive supplier of cell culture media and bioprocessing technologies, anchoring a significant portion of the market. Corning Incorporated, a US-based company, represents a specialist in advanced glass surfaces and extracellular matrix coatings, critical for scaffold-based and advanced 3D culture systems. These companies highlight the industry's reliance on both integrated solutions and specialized material science expertise. Their presence underscores the importance of a robust supply chain for various 3D cell culture components.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Corning Incorporated |
| Lonza |
| Sartorius AG |
| Tecan Trading AG |
| Avantor, Inc. |
| InSphero |
| REPROCELL Inc. |
| Others |
Cost & Logistics Intelligence
ISO 10993 biocompatibility standards gate both the qualification of biomaterial suppliers and the price differentiation of clinical-grade products. This regulatory scrutiny ensures material quality while enabling premium pricing for compliant components.
Pricing Analysis
Certification level (ISO/FDA-grade) creates the primary spread in 3D cell culture product pricing. The market features a hybrid pricing model, combining per-unit transactional sales for basic scaffolds and reagents with project-based contracts for complex organ-on-a-chip systems. Price differentiation stems from product complexity, customization capabilities, and the brand reputation of established suppliers like Thermo Fisher Scientific. Pricing pressure intensifies from academic institutions and smaller biotechnology firms due to budget constraints and the high implementation cost of advanced systems. Large pharmaceutical companies demonstrate lower price sensitivity for highly predictive models in critical drug development stages.
Supply Chain Analysis
Inventory management for specialized components requires careful planning due to varying lead times for advanced biomaterials. The supply chain for 3D cell culture products concentrates in the United States, Germany, and Japan, reflecting their R&D and manufacturing capabilities. Raw material dependencies include specialized biomaterials like medical-grade collagen and synthetic polymers, microfluidic components, and high-purity growth factors. Single-source vulnerability for highly specialized microfluidic chips or advanced surface coatings represents a structural risk. Distribution runs through a combination of direct sales channels from major suppliers and specialized distributors serving niche research applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment, particularly from policies like the FDA Modernization Act 2.0, creates a significant defensive moat for established players in the 3D cell culture market.
For Market Incumbents:
Consolidate market position by acquiring specialized organ-on-a-chip developers to integrate advanced predictive models. Invest heavily in standardized validation platforms to accelerate regulatory acceptance and counter the threat from emerging niche innovators. Further R&D into AI-powered analytics will enhance data interpretation for complex 3D models. Prioritize certification investment (e.g., ISO 10993 compliance) to maintain premium positioning and expand into clinical applications.
For New Entrants and Emerging Players:
Automated data analysis solutions for high-content imaging present a service-layer gap where incumbents under-serve. Target academic institutions and smaller biotechnology firms by offering user-friendly bioprinting platforms and comprehensive technical support. Develop cost-effective, scalable scaffold-free models for high-throughput screening to penetrate the drug discovery segment. A specific go-to-market angle involves bundling advanced 3D models with AI-driven software for streamlined data interpretation.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the complex model development segment, driven by R&D in organ-on-a-chip and bioprinting. The market offers strong long-term viability, propelled by regulatory shifts away from animal testing and the expansion of personalized medicine. Target acquisition archetypes include niche technology developers specializing in advanced microfluidics or AI-driven image analysis. Increased regulatory qualification of specific 3D models for toxicology testing serves as a key signal to watch for accelerated market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire specialized organ-on-a-chip firms | Integrates advanced predictive models and expands technology portfolios for incumbents. |
| Invest in standardized validation platforms | Accelerates regulatory acceptance and improves data reproducibility for broader market adoption. |
| Develop AI-driven analytics for 3D models | Automates complex data interpretation, enhancing the predictive power of preclinical assays. |
| Offer bundled bioprinting solutions with support | Lowers barriers to entry for academic and smaller biotech users, expanding market access. |
| Focus on cost-effective, scalable scaffold-free models | Addresses budget constraints for high-throughput screening in drug discovery applications. |
Research Approach
A standing panel of pharmaceutical R&D leads, contract research organization scientists, biomaterials engineers, and regulatory affairs specialists provided ongoing calibration. This primary research, combined with secondary validation from FDA guidance documents, EMA scientific guidelines, and peer-reviewed journals, informed market insights. Bottom-up and top-down triangulation ensured data accuracy across all segments.
Market volume and value outputs underwent consistency checks against external benchmarks across the analysis window. The analytical framework modeled dimensions including product type, technology, application, end user, and regional regulatory cluster. Compound annual growth rates were derived from historical trends, expert projections, and market sizing models. Regulatory timelines for new model acceptance and R&D investment trends in biotechnology clusters served as key forecast inputs.
Forecasts assume regulatory continuity in the US FDA and European Medicines Agency regimes; material policy shifts would require re-modeling. Unforeseen technological breakthroughs or significant shifts in funding for preclinical research represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Global Cell Dissociation Market