
 Global Staphylococcal Infection Drugs Market | 2026-2036
Global Staphylococcal Infection Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Staphylococcal Infection Drugs Market Foresight
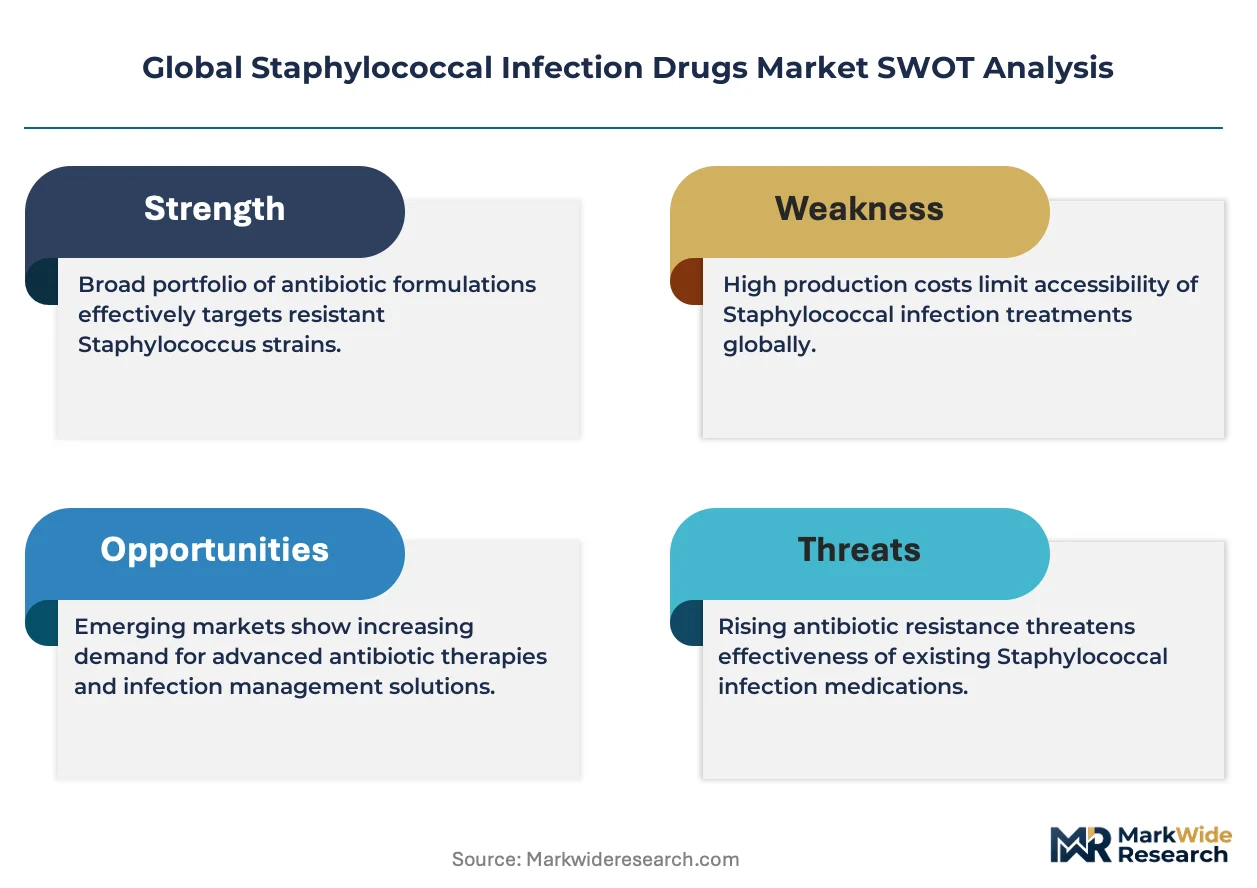
Fixed-dose combination bundling of beta-lactamase inhibitors with cephalosporins is restructuring hospital formulary decisions across acute care settings. Pfizer leverages its manufacturing scale to dominate intravenous vancomycin supply chains in North American health systems. Merck & Co. anchors its position through sustained R&D investment in novel oxazolidinone derivatives for resistant gram-positive pathogens.
Staphylococcal infection drugs comprise antibacterial agents engineered to inhibit cell wall synthesis, protein production, or DNA replication in Staphylococcus species, with minimum inhibitory concentration thresholds determining clinical efficacy against methicillin-resistant strains. These therapeutics serve to eradicate colonization, resolve active infections, and prevent sepsis progression in hospitalized and immunocompromised populations. Glycopeptide therapies occupy the largest revenue pool among drug classes due to entrenched vancomycin use in bloodstream infection protocols, while oxazolidinones represent the fastest-growing category driven by oral bioavailability advantages enabling outpatient step-down therapy. The hospital end-user segment controls the dominant share of value as parenteral administration requirements keep patients in institutional settings during initial treatment phases.
The FDA's Qualified Infectious Disease Product program and EMA's PRIME designation framework accelerate market access for novel staphylococcal agents, while WHO's AWaRe antibiotic stewardship guidelines constrain empirical prescribing patterns in acute care. These regulatory layers compel developers to demonstrate superior resistance profiles or reduced nephrotoxicity against existing standards to secure formulary placement. Stakeholders must monitor FDA breakthrough therapy designations and EMA accelerated assessment pathways to anticipate which novel mechanisms will reshape competitive dynamics before label expansion decisions finalize.
Market Dynamics
The FDA's Qualified Infectious Disease Product designation compresses clinical trial timelines for novel anti-MRSA agents, while WHO's AWaRe stewardship guidelines constrain empirical prescribing in acute care settings. This regulatory dualism forces developers to demonstrate superior resistance profiles or reduced nephrotoxicity against vancomycin standards to secure hospital formulary placement.
Growth Catalysts
- Surgical Site Infection Burden:Rising post-operative MRSA colonization rates in tertiary care centers drive procurement of targeted parenteral therapies. Hospital pharmacies prioritize agents with established minimum inhibitory concentration breakpoints against resistant strains.
- EMA PRIME Designation:Accelerated assessment pathways for novel oxazolidinone derivatives enable faster market access in European Union member states. Developers leverage this framework to compress regulatory review phases.
- Medicare Reimbursement Structure:United States inpatient payment policies favor parenteral antibiotic administration, keeping patients in institutional settings during initial treatment phases and sustaining hospital pharmacy demand.
Market Restraints
- Teicoplanin Supply Concentration:European glycopeptide manufacturing depends on a limited supplier base in Italy and Austria, creating vulnerability to production disruptions.
- Generic Vancomycin Price Compression:Intravenous formulation commoditization erodes margin structures for originator products across North American health systems.
- Nephrotoxicity Liability:Dose-dependent renal impairment with prolonged vancomycin therapy limits treatment duration in elderly populations with compromised renal function.
Strategic Opportunities
- Outpatient Step-Down Therapy:Oral bioavailability advantages of next-generation oxazolidinones enable transition from hospital to home-based care, capturing value from shortened length-of-stay incentives.
- Indian Hospital Sector Expansion:Private tertiary care chains in Maharashtra and Karnataka are upgrading infectious disease capabilities, creating demand for targeted gram-positive therapies.
- Dual Carbon Goals Alignment:China's NMPA incentives for green manufacturing processes favor developers with reduced solvent waste in active pharmaceutical ingredient synthesis.
Industry Challenges
- Antimicrobial Stewardship Compliance:Hospital pharmacy and therapeutics committees require extensive resistance surveillance data before formulary addition, extending sales cycles.
- Biomarker Development Timeline:Companion diagnostics for patient stratification by resistance mechanism face prolonged analytical validation phases at reference laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Staphylococcal Infection Drugs Market |
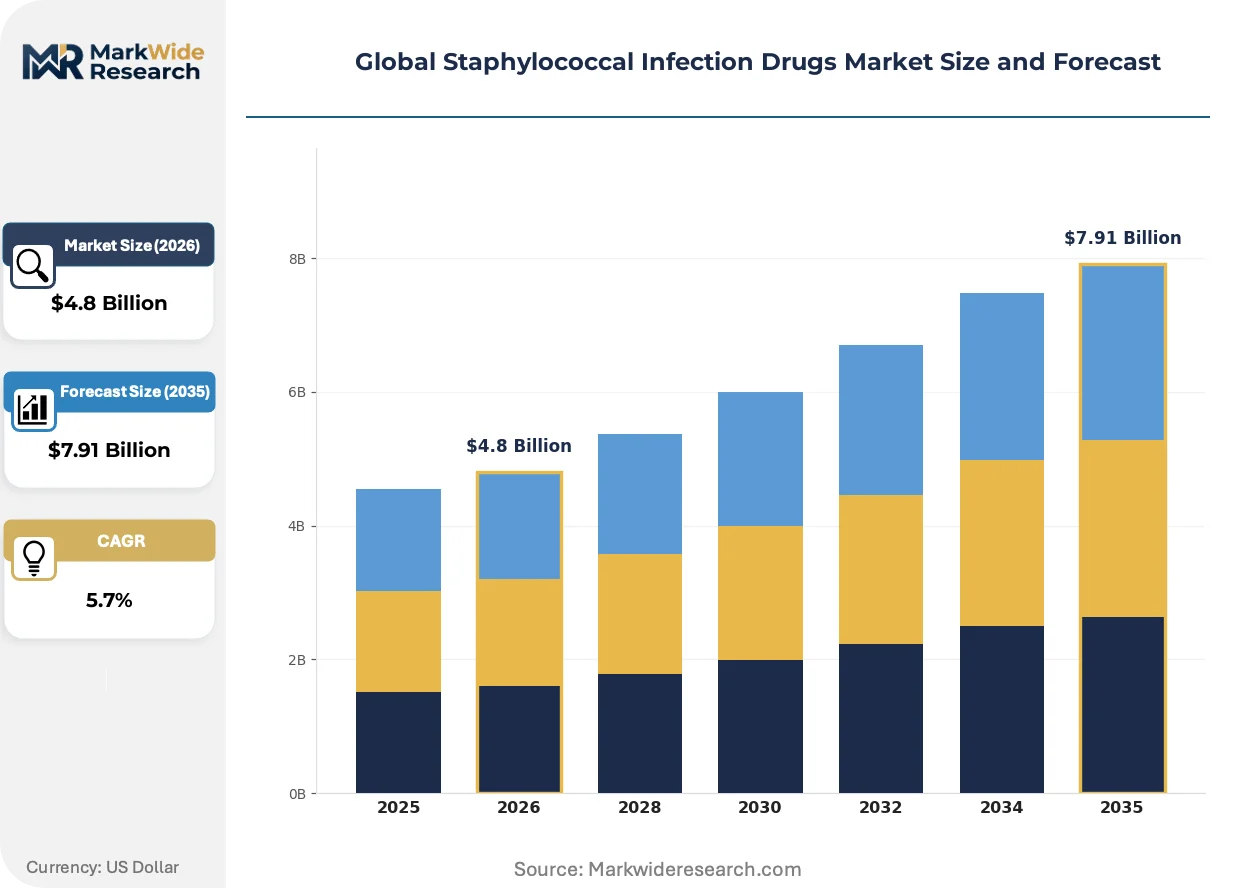
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Beta-lactams, Glycopeptides, Lincosamides, Oxazolidinones, Streptogramins Therapy Area: Skin Infections, Bloodstream Infections, Respiratory Infections, Bone & Joint Infections, Post-surgical Infections End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Healthcare Clinics, Long-term Care Facilities Administration Route: Oral, Intravenous, Intramuscular, Topical, Subcutaneous |
| Companies Covered | Pfizer, Merck & Co., AbbVie, Johnson & Johnson, Basilea Pharmaceutica, Theravance Biopharma, Cumberland Pharmaceuticals, Melinta Therapeutics, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Staphylococcal Infection Drugs Market Shifts & Advancements
Fixed-dose combination engineering is restructuring therapeutic decision-making across acute care settings, with beta-lactamase inhibitor bundling emerging as the dominant formulation strategy. Three convergent developments are compressing competitive timelines and reshaping value capture.
Next-generation cephalosporin-beta-lactamase inhibitor combinations are expanding into bloodstream infection protocols previously dominated by glycopeptide monotherapy. Hospital infectious disease specialists in the United States and Germany are adopting these agents for empirical coverage of suspected MRSA bacteremia. The technology is expanding into step-down therapy pathways, enabling earlier transition from intravenous vancomycin to oral alternatives and compressing total treatment costs.
The EMA's PRIME designation framework and FDA's breakthrough therapy pathway are compressing development timelines for novel mechanisms targeting resistant gram-positive pathogens. Developers in Switzerland and the United Kingdom are leveraging these accelerated channels to secure conditional approvals based on Phase II efficacy data. Small-molecule candidates with novel protein synthesis inhibition mechanisms are benefiting most from this regulatory flexibility.
Japanese university hospitals are unbundling antibiotic procurement from traditional group purchasing organizations, establishing direct tender relationships with manufacturers of narrow-spectrum agents. This channel disintermediation enables formulary committees to negotiate indication-specific contracts rather than accepting bundled portfolios. The shift is most visible in Kanto and Kansai region academic medical centers with dedicated infectious disease departments.
Global Staphylococcal Infection Drugs Market Segmentation
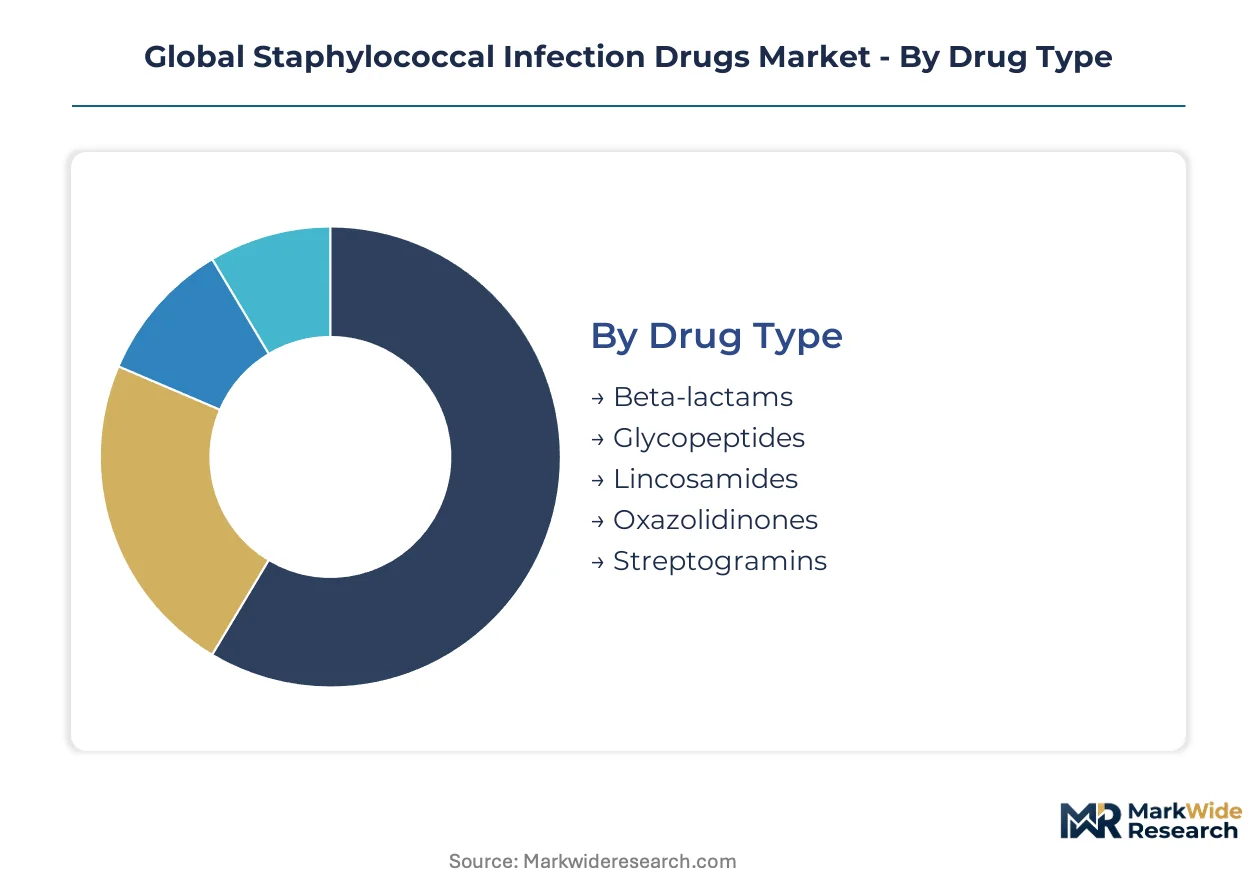
Drug class selection determines reimbursement pathways and formulary placement in institutional settings. Route of administration shapes patient eligibility for outpatient step-down protocols. End-user channel structure influences procurement contract terms and inventory management requirements across health systems.
Drug Type:
Hospital pharmacy committees prioritize minimum inhibitory concentration breakpoints and resistance profiles when selecting agents for empirical therapy protocols.
- Glycopeptides:Vancomycin and teicoplanin dominate bloodstream infection protocols through established efficacy against methicillin-resistant strains. United States tertiary care centers maintain these agents as first-line empirical therapy for suspected MRSA bacteremia, though nephrotoxicity monitoring requirements constrain prolonged use in elderly populations with compromised renal function.
- Oxazolidinones:Linezolid and next-generation derivatives enable oral step-down therapy with bioavailability matching intravenous formulations. German and Swiss hospitals are expanding outpatient parenteral antimicrobial therapy programs around these agents to reduce length-of-stay metrics under DRG reimbursement frameworks.
- Beta-lactams:Penicillinase-resistant penicillins and cephalosporins retain utility in methicillin-susceptible infections.
- Lincosamides:Clindamycin serves skin and soft tissue infection protocols where anaerobic coverage is required.
- Streptogramins:Quinupristin-dalfopristin addresses vancomycin-resistant Enterococcus coinfections in intensive care settings.
Volume sits with glycopeptides; growth tilts toward oxazolidinones.
Therapy Area:
Site of infection determines dosing intensity, treatment duration, and monitoring requirements that shape total cost of care calculations.
- Skin Infections:Cellulitis and abscess presentations drive outpatient prescribing volume in community settings. United States urgent care centers and emergency departments manage these cases with oral agents or single-dose parenteral therapy, reducing admission rates under value-based care contracts.
- Bloodstream Infections:Bacteremia and endocarditis require prolonged parenteral therapy with therapeutic drug monitoring. Japanese university hospitals have established dedicated infectious disease consultation services to manage these complex cases, extending treatment courses to six weeks or longer.
- Respiratory Infections:Nosocomial pneumonia in ventilated patients demands broad-spectrum coverage including anti-MRSA activity.
- Bone & Joint Infections:Osteomyelitis and septic arthritis require surgical debridement combined with extended antibiotic courses.
- Post-surgical Infections:Surgical site infections trigger enhanced surveillance and targeted prophylaxis protocols in cardiac and orthopedic service lines.
Bloodstream infections command the highest per-patient revenue; skin infections generate the largest prescription volume.
End User:
Channel structure determines formulary negotiation leverage and inventory carrying costs across institutional and ambulatory settings.
- Hospitals:Inpatient pharmacies control procurement of parenteral formulations with restricted distribution status. Academic medical centers in India—particularly Maharashtra and Karnataka—are upgrading infectious disease capabilities and expanding targeted gram-positive therapy formularies.
- Ambulatory Care Centers:Outpatient parenteral antimicrobial therapy programs enable home-based administration of long-acting agents. United States infusion centers are capturing step-down volume from hospital discharge planning.
- Diagnostic Laboratories:Reference labs provide resistance surveillance data supporting antimicrobial stewardship decisions.
- Healthcare Clinics:Primary care settings manage uncomplicated skin infections with oral first-line agents.
- Long-term Care Facilities:Skilled nursing facilities face heightened regulatory scrutiny for antibiotic prescribing patterns.
Hospitals retain dominant value share; ambulatory care centers are expanding most quickly.
Administration Route:
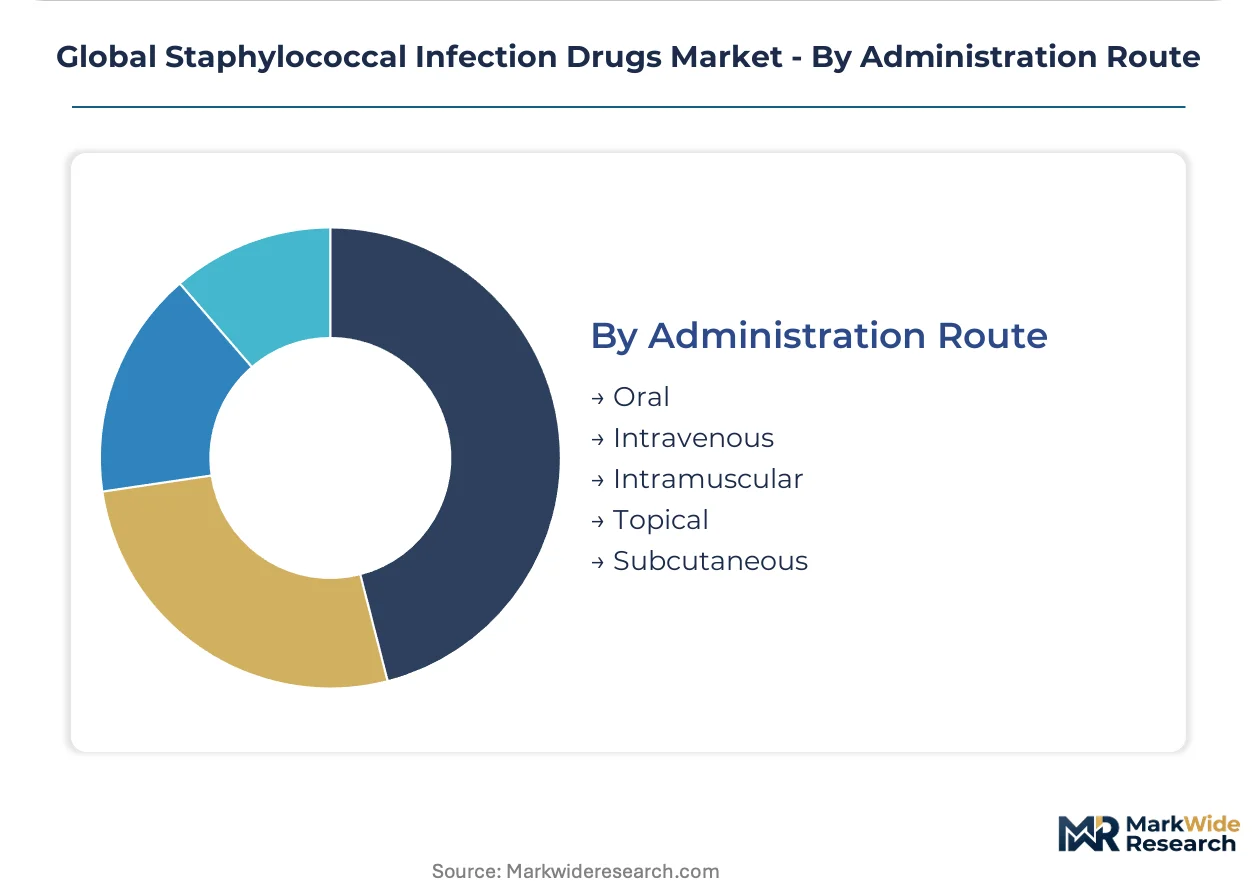
Delivery mechanism determines site-of-care requirements and patient eligibility for early discharge protocols.
- Intravenous:Continuous or intermittent infusion dominates initial therapy for serious infections requiring rapid bactericidal activity. Medicare reimbursement structures in the United States favor inpatient parenteral administration, sustaining hospital pharmacy demand for glycopeptide and lipopeptide agents.
- Oral:Bioavailable agents enable transition to outpatient settings with equivalent pharmacokinetic profiles. EMA PRIME-designated oxazolidinones are accelerating this shift in European Union member states.
- Intramuscular:Depot formulations support adherence in substance use disorder populations.
- Topical:Mupirocin and retapamulin address localized nasal colonization and superficial skin infections.
- Subcutaneous:Novel long-acting agents are entering development for outpatient administration.
Intravenous routes dominate acute revenue; oral formulations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical ingredients concentrates in China and India, while consumption of branded anti-MRSA therapies clusters in the United States, Germany, and Japan. This geographic split shapes regulatory compliance requirements and supply chain risk profiles across the value chain.
United States
Medicare reimbursement policies favor inpatient parenteral antibiotic administration, sustaining hospital pharmacy procurement volumes. The FDA's Qualified Infectious Disease Product designation accelerates development timelines for novel agents. Tertiary care centers in Boston and Houston maintain vancomycin as first-line empirical therapy for suspected MRSA bacteremia.
Germany
DRG reimbursement frameworks incentivize shortened length-of-stay metrics, driving adoption of oral step-down protocols. The EMA's PRIME designation enables faster market access for oxazolidinone derivatives. Academic medical centers in Berlin and Munich are expanding outpatient parenteral antimicrobial therapy programs.
China
NMPA incentives for green manufacturing processes favor developers with reduced solvent waste in API synthesis. Dual carbon goals alignment shapes procurement criteria for hospital pharmacy committees. Pharmaceutical clusters in Jiangsu and Zhejiang provinces are upgrading fermentation capacity for glycopeptide production.
India
Private tertiary care chains in Maharashtra and Karnataka are upgrading infectious disease capabilities, creating demand for targeted gram-positive therapies. CDSCO accelerated approval pathways compress regulatory review for novel anti-MRSA agents. Mumbai and Bangalore academic medical centers are establishing dedicated infectious disease consultation services.
Switzerland
Swissmedic's accelerated assessment pathways support conditional approvals based on Phase II efficacy data for novel mechanisms. Basel-based research institutions anchor early-stage development of protein synthesis inhibitors. The country's precision medicine infrastructure enables biomarker-driven patient stratification trials.
Global Staphylococcal Infection Drugs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the staphylococcal infection drugs landscape. The market structure tilts toward consolidation among large-cap pharmaceutical firms with established hospital formulary relationships, while mid-tier developers concentrate on resistance-resistant mechanisms. Two strategic archetypes dominate: diversified giants leveraging manufacturing scale and regulatory expertise, and specialized biotechs pursuing novel targets. Competitive dynamics center on M&A activity to acquire resistance-resistant pipelines and strategic partnerships to secure distribution through integrated health systems.
Within the diversified pharmaceutical tier, Pfizer and Merck & Co. anchor global supply chains for intravenous glycopeptides and oxazolidinones respectively. AbbVie occupies a position among integrated health science conglomerates with hospital-focused portfolios. These three entities exemplify the scale-driven archetype that dominates procurement contracts with group purchasing organizations and direct tender relationships with academic medical centers.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co. |
| AbbVie |
| Johnson & Johnson |
| Basilea Pharmaceutica |
| Theravance Biopharma |
| Cumberland Pharmaceuticals |
| Melinta Therapeutics |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Fermentation specialists in Jiangsu and Zhejiang provinces anchor active pharmaceutical ingredient production, with labor-cost differentials between coastal China and inland India widening pricing-tier spreads for glycopeptide and oxazolidinone therapies across hospital procurement contracts.
Pricing Analysis
Margin tightening in intravenous vancomycin traces to generic formulation commoditization across North American health systems. Three-tier pricing structure across originator, authorized generic, and commodity injectable levels stratifies by FDA bioequivalence certification and therapeutic drug monitoring bundling. Cost-down pressure on standard-tier products accelerates because group purchasing organizations consolidate contract volumes. Academic medical centers exhibit lowest price sensitivity due to formulary stickiness; community hospitals face highest procurement scrutiny.
Supply Chain Analysis
Direct-to-hospital pharmacy channels handle parenteral antibiotic demand from integrated health systems in the United States and Germany. API manufacturing draws from fermentation capacity in China, chemical synthesis clusters in India, and specialized biologics production in Switzerland. Teicoplanin supply rests on Italian and Austrian supplier concentration. Single-source vulnerability in glycopeptide intermediate production exposes formularies to disruption risk. Distribution runs through regional wholesaler networks with cold-chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The staphylococcal infection drugs market sits in a technology-transition phase, with next-generation oxazolidinone derivatives displacing legacy glycopeptide monotherapy in bloodstream infection protocols.
For Market Incumbents: Anchor formulary position through backward integration into beta-lactamase inhibitor API supply and sustained R&D investment in nephrotoxicity-sparing mechanisms. Generic vancomycin price erosion threatens margin structures; defend through therapeutic drug monitoring service bundling and resistance surveillance data partnerships with hospital pharmacy committees. For New Entrants and Emerging Players: Enter via outpatient parenteral antimicrobial therapy programs in German and Swiss DRG reimbursement environments where length-of-stay compression incentives favor oral bioavailable agents. Private tertiary care chains in Maharashtra and Karnataka present the most penetrable geography. Pursue CDSCO accelerated approval pathways with indication-specific tender positioning. For Investors and Strategic Acquirers: The window for entry favors developers with Phase II oxazolidinone candidates holding EMA PRIME or FDA breakthrough therapy designations. Long-term viability hinges on resistance-resistant mechanisms and biomarker companion diagnostic potential. Watch FDA Qualified Infectious Disease Product designation velocity as inflection signal for competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II efficacy data accelerates EMA conditional approval pathways for novel protein synthesis inhibitors. |
| Regulatory Approval Pathway | FDA Qualified Infectious Disease Product designation compresses development timelines for anti-MRSA agents. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Jiangsu province secures glycopeptide API supply for hospital formularies. |
| Hospital System Partnership | Direct tender relationships with Japanese academic medical centers bypass traditional group purchasing organizations. |
| Pipeline Diversification | Beta-lactamase inhibitor combinations expand into bloodstream infection protocols previously reserved for vancomycin. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors combined with FDA filings, EMA submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up prescription volume modeling and top-down revenue estimates underwent triangulation validation.
Data-stream reconciliation across patient population segments, administration routes, therapy areas, and regional regulatory clusters produced volume and value outputs over the projection horizon. CAGRs derived from segment-level growth rate convergence analysis. Resistance surveillance trends and reimbursement policy shifts served as pharmaceutical-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under antimicrobial stewardship mandate acceleration or API supply disruption scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
HIV Market