
 Cell Culture Media Market | 2026-2036
Cell Culture Media Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Culture Media Market Intelligence
Media-as-a-service subscription models is recalibrating how biomanufacturers procure cell culture inputs. Thermo Fisher Scientific leverages its global distribution network to anchor recurring revenue streams across pharmaceutical accounts. Sartorius AG differentiates through integrated bioreactor-media bundles that reduce process variability for gene therapy producers. Merck KGaA competes on chemically defined formulations that sustain compliance with tightening biosafety standards in Europe and Asia.
Cell culture media comprises nutrient-rich solutions formulated with amino acids, vitamins, salts, and growth factors that support in vitro mammalian, insect, or microbial cell propagation under controlled pH and osmolarity conditions. Serum-free media now dominates commercial procurement as biopharmaceutical manufacturers eliminate lot-to-lot variability and bovine spongiform encephalopathy risks inherent in fetal bovine serum. Chemically defined media commands premium positioning in gene therapy applications where regulatory scrutiny of trace contaminants intensifies, while ready-to-use liquid formats reduce preparation labor in high-throughput contract research organization workflows.
FDA biologics guidance, EMA biosafety standards, and ISO 13485 quality management frameworks collectively mandate traceability and absence of adventitious agents in media destined for therapeutic cell lines. These requirements accelerate displacement of animal-origin media by protein-free and chemically defined alternatives across GMP manufacturing suites. Stakeholders must monitor evolving pharmacopeial standards for raw material qualification and decide between in-house media formulation investments versus outsourced supply agreements as therapy modalities diversify.
Market Dynamics
Serum-free media formulations are displacing animal-origin alternatives as FDA and EMA biosafety guidelines harden traceability requirements for therapeutic cell lines, compressing formulation choices across GMP manufacturing suites.
Growth Catalysts
- EMA biosafety standards:Chemically defined media procurement accelerates as European manufacturers eliminate bovine spongiform encephalopathy risks from fetal bovine serum-dependent workflows.
- Cell and gene therapy manufacturing:Viral vector production scales drive specialized media demand for HEK293 and CHO cell line expansion in CDMO facilities.
- CDMO cluster concentration:United States, Germany, and China procurement hubs consolidate purchasing power for high-volume serum-free formulations.
Market Restraints
- Amino acid and vitamin input volatility:Pharmaceutical-grade raw material costs fluctuate with agricultural commodity markets and purification grade availability.
- Supplier concentration risk:Critical growth factor production concentrates among limited recombinant protein specialists, creating single-source dependencies for chemically defined formulations.
- ISO 13485 compliance friction:Quality management system certification timelines extend 12-18 months for new media manufacturers entering therapeutic-grade supply chains.
Strategic Opportunities
- India biopharma manufacturing:CDSCO regulatory alignment with ICH Q5D guidelines creates openings for serum-free media localization in emerging biosimilar production hubs.
- Media-as-a-service subscriptions:Recurring revenue models displace spot purchasing for contract research organizations managing high-throughput screening workflows.
- Perfusion bioreactor convergence:Continuous manufacturing platforms demand specialized feed formulations that sustain cell density over extended culture durations.
Industry Challenges
- Formulation scientist scarcity:Protein chemistry and cell physiology expertise gaps constrain in-house media development teams at mid-scale biomanufacturers.
- Legacy equipment incompatibility:New chemically defined media chemistries require pH and osmolarity sensor recalibration in established stainless-steel bioreactor installations.
- Adventitious agent testing bottlenecks:Extended qualification timelines for mycoplasma and viral contamination assays delay batch release for GMP media production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Culture Media Market |
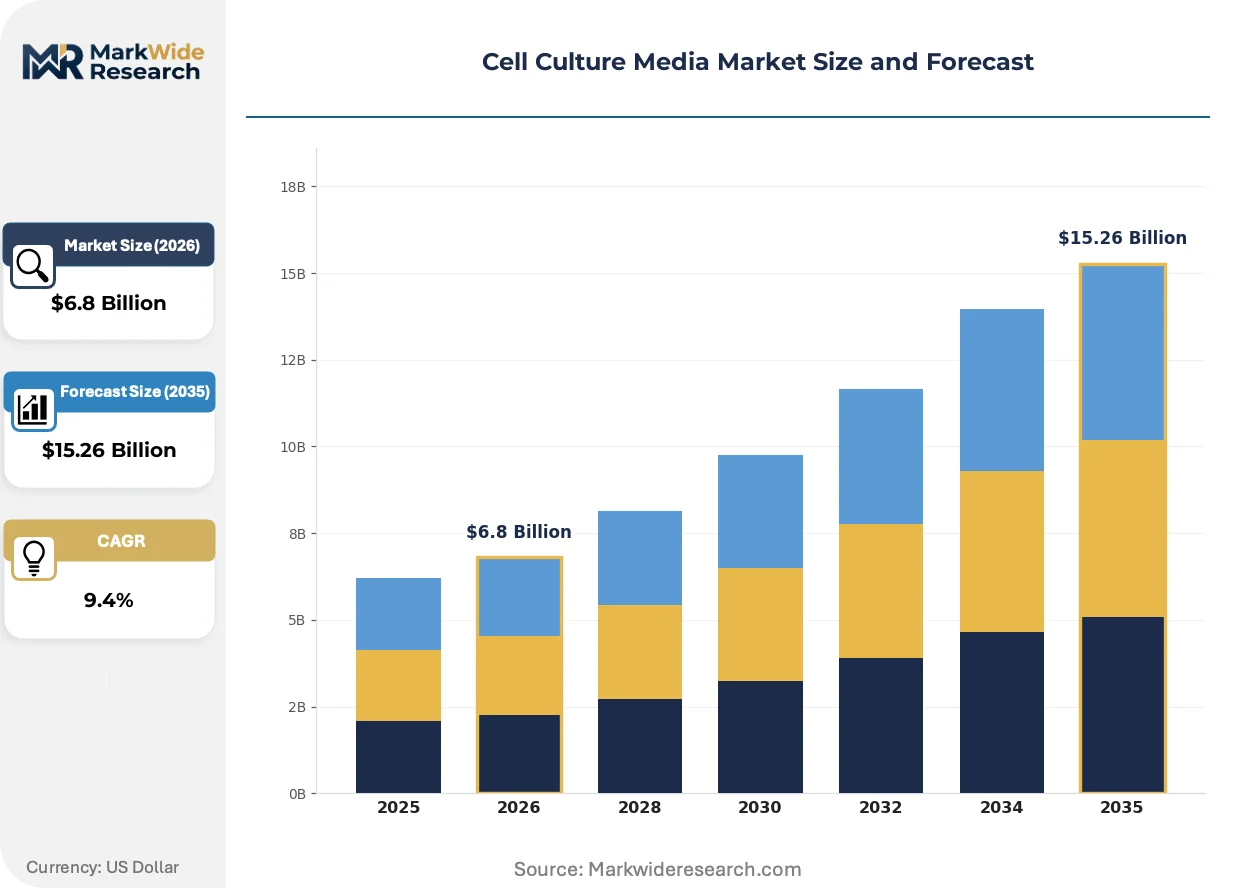
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum-Free Media, Protein-Free Media, Animal-Origin Media, Chemically Defined Media, Supplemented Media Application: Biopharmaceutical Production, Vaccine Development, Gene Therapy, Tissue Engineering, Stem Cell Research End User: Biotech Firms, Contract Research Organizations, Academic Institutions, Pharmaceutical Companies, Diagnostic Laboratories Form: Frozen, Liquid, Ready-to-Use Powder, Dry Powder, Concentrated Solution |
| Companies Covered | Sartorius AG, Corning Incorporated, Thermo Fisher Scientific, Becton, Dickinson and Company, FUJIFILM Corporation, Merck KGaA, Lonza Group, HiMedia Laboratories, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Culture Media Market Strategic Shifts & Innovations
Artificial intelligence is reshaping how media formulations optimize nutrient composition for specific cell lines, compressing development cycles that previously required months of empirical testing.
Machine learning algorithms analyze metabolic flux data to predict amino acid depletion rates in CHO cell cultures. Gene therapy producers at CDMOs adopt these platforms to reduce fed-batch optimization from twelve weeks to three. This capability is converging with automated bioreactor sampling systems that generate real-time nutrient consumption datasets.
EMA's tightening guidance on TSE/BSE risk materials now mandates documented absence of animal-origin components in media for advanced therapy medicinal products. Manufacturers reformulate legacy serum-containing products to protein-free alternatives ahead of 2027 compliance deadlines. European gene therapy developers accelerate chemically defined media validation to preempt regulatory rejection of Investigational Medicinal Product Dossiers.
Consolidated procurement through integrated bioreactor-media bundles displaces standalone media purchasing at cell therapy facilities. Sartorius and Thermo Fisher anchor these arrangements through multi-year service contracts that lock in formulation consistency. This pattern concentrates most visibly in United States coastal manufacturing corridors where CDMOs prioritize process standardization over supplier diversification.
Cell Culture Media Market Segmentation
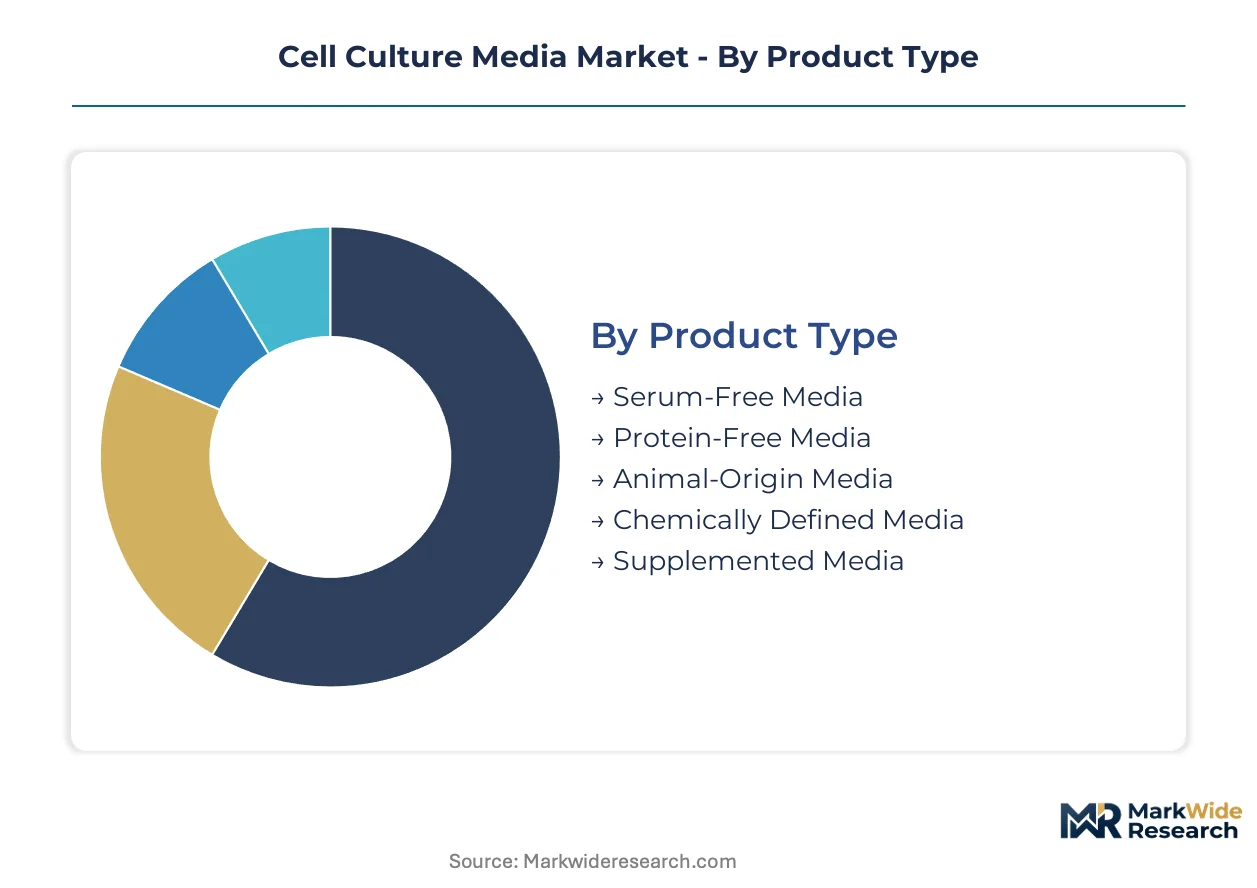
Cell culture media segmentation reflects divergent technical requirements across therapeutic modalities. Formulation complexity, regulatory stringency, and manufacturing scale together determine procurement patterns among biopharmaceutical producers.
Product Type:
Standardization versus customization tensions shape formulation choices, with chemically defined media commanding premium positioning while serum-free alternatives dominate volume procurement.
- Chemically Defined Media:Every constituent is identified by chemical formula and concentration, eliminating lot-to-lot variability. Gene therapy manufacturers at CDMOs in the United States and Germany adopt these formulations to satisfy EMA and FDA traceability mandates for advanced therapy medicinal products.
- Serum-Free Media:Eliminates fetal bovine serum while retaining recombinant growth factors and hydrolysates. Biopharmaceutical producers across CHO cell lines for monoclonal antibody manufacturing specify these formulations to mitigate bovine spongiform encephalopathy documentation burdens.
- Protein-Free Media:Synthetic formulations without peptide additives, minimizing immunogenic contamination risks in downstream purification.
- Animal-Origin Media:Traditional formulations incorporating bovine serum albumin and other animal-derived components, now restricted to research-grade applications outside GMP therapeutic manufacturing.
- Supplemented Media:Base formulations enhanced with proprietary growth factor cocktails optimized for specific cell line productivity.
Most installed capacity flows through Serum-Free Media. Expansion is steepest in Chemically Defined Media.
Application:
Process economics and regulatory classification stratify demand intensity across therapeutic categories, with cell and gene therapy applications imposing the most stringent formulation specifications.
- Gene Therapy:Viral vector production in HEK293 and suspension-adapted packaging cell lines requires media free of adventitious agents and replication-competent virus contaminants. CDMOs in Boston and San Francisco metropolitan corridors drive specialized procurement for AAV and lentiviral manufacturing campaigns.
- Biopharmaceutical Production:Fed-batch and perfusion cultures for monoclonal antibodies and recombinant proteins constitute the volume anchor. Chinese manufacturers expanding biosimilar capacity source high-tonnage serum-free formulations through consolidated supplier agreements.
- Vaccine Development:Cell-based influenza and viral vaccine substrates employ chemically defined alternatives to egg-based production, particularly for immunocompromised patient indications.
- Tissue Engineering:Three-dimensional scaffold cultures for regenerative medicine applications demand media formulations supporting extracellular matrix deposition.
- Stem Cell Research:Pluripotent and adult stem cell propagation requires specialized cytokine supplementation for lineage maintenance and directed differentiation.
Biopharmaceutical Production absorbs the greatest media tonnage. Gene Therapy is gaining share fastest.
End User:
Purchasing sophistication and quality system maturity segment the customer base, with large pharmaceutical companies leveraging multi-year contracts against spot-buying patterns at academic facilities.
- Pharmaceutical Companies:Integrated biomanufacturers with captive GMP suites negotiate formulation exclusivity and audit rights into supply agreements. Pfizer and Roche anchor demand through direct sourcing relationships with media formulators.
- Biotech Firms:Venture-funded developers outsourcing manufacturing to CDMOs specify media through technology transfer protocols, constraining supplier substitution.
- Contract Research Organizations:High-throughput screening operations prioritize ready-to-use liquid formats minimizing preparation labor and contamination exposure.
- Academic Institutions:Research laboratories balance cost constraints against publication-grade reproducibility, often selecting supplemented media with documented batch certificates.
- Diagnostic Laboratories:Cell-based assay providers require consistent performance across extended reagent stability windows for regulatory-compliant test kits.
Pharmaceutical Companies command the deepest formulation customization. Biotech Firms are expanding procurement most quickly.
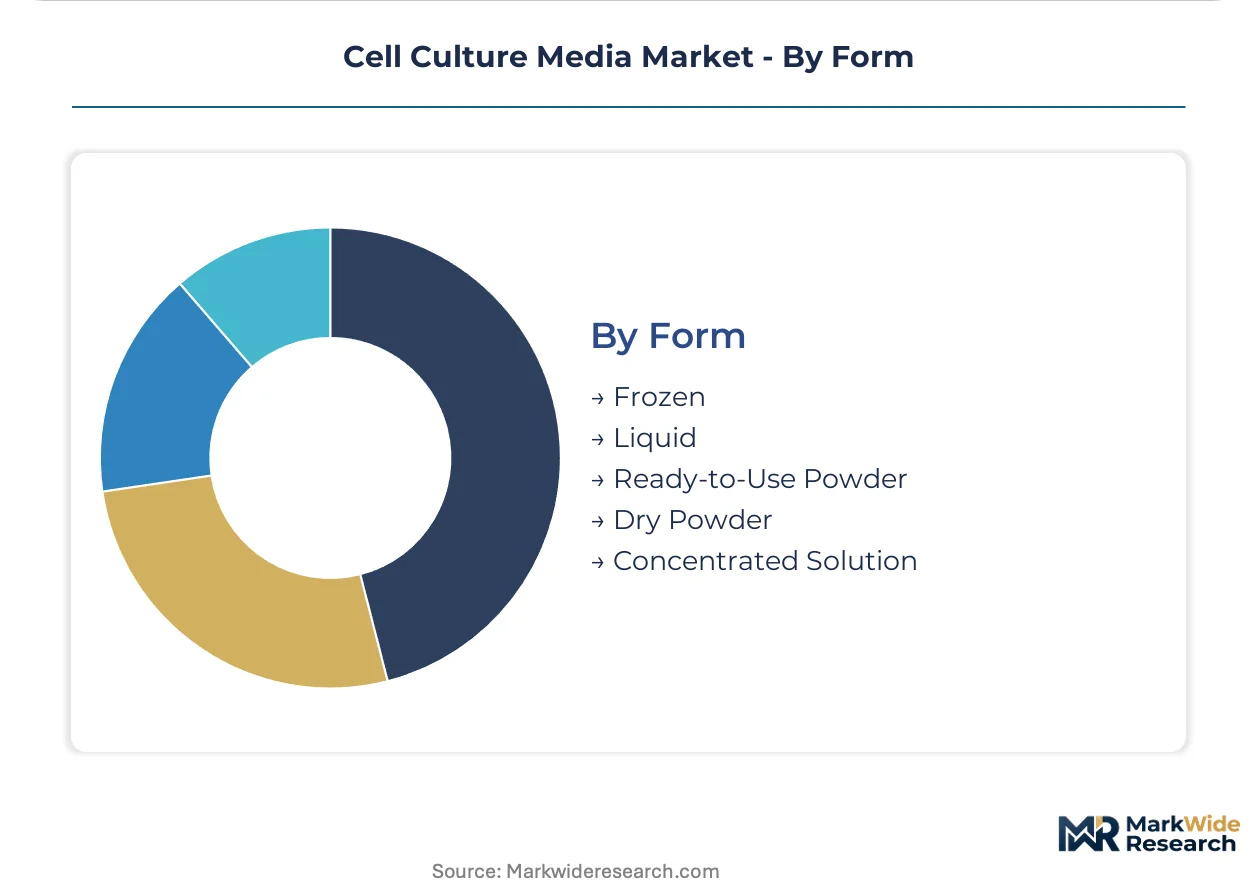
Form:
Supply chain configuration and facility infrastructure dictate format preferences, with liquid concentrates reducing preparation burden while powders minimize cold-chain expenditure.
- Liquid:Sterile-filtered, ready-to-use solutions eliminate hydration and pH adjustment steps. CDMOs with validated sterile connection operations specify liquid for closed-system bioreactor loading.
- Ready-to-Use Powder:Pre-weighed, pre-formulated dry blends dissolve directly into water-for-injection, reducing compounding errors in high-volume manufacturing.
- Concentrated Solution:Ten-fold or fifty-fold concentrates reduce shipping volumes and cold-chain costs, requiring dilution at point-of-use.
- Dry Powder:Bulk formulations for in-house media kitchens at large biomanufacturing campuses, offering maximum flexibility and minimum per-liter cost.
- Frozen:Temperature-stable storage extends shelf life for formulations with labile growth factors, common in specialized stem cell and primary cell applications.
Liquid formats dominate current purchasing. Ready-to-Use Powder is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's biopharmaceutical manufacturing expansion outpaces regulatory infrastructure development, while the United States maintains stricter FDA oversight that slows but does not stop capacity growth. These divergent trajectories shape how serum-free media suppliers allocate technical support and quality assurance resources across manufacturing corridors.
United States
Gene therapy CDMOs in Greater Boston and the San Francisco Bay Area drive specialized media demand for HEK293 viral vector production. FDA biologics guidance on adventitious agent testing extends batch qualification timelines, favoring established suppliers with validated quality systems. The Research Triangle Park corridor in North Carolina anchors high-volume serum-free procurement for monoclonal antibody manufacturing.
Germany
EMA biosafety standards on transmissible spongiform encephalopathy risks accelerate chemically defined media adoption across Bavarian and Baden-Württemberg biomanufacturing clusters. The country's national pharmaceutical regulator enforces documented absence of animal-origin components for advanced therapy medicinal products. Heidelberg and Munich metropolitan areas concentrate gene therapy developers reformulating legacy serum-dependent workflows ahead of 2027 compliance deadlines.
China
Biosimilar production scale-up in Shanghai and Suzhou industrial parks generates high-tonnage demand for serum-free CHO cell culture formulations. NMPA alignment with ICH Q5D guidelines on cell line qualification creates regulatory pathways for imported chemically defined media. Yangtze River Delta CDMO clusters negotiate consolidated supply agreements to reduce per-liter costs in fed-batch manufacturing campaigns.
India
CDSCO regulatory harmonization with ICH quality standards opens procurement channels for serum-free media in Hyderabad and Bengaluru biosimilar facilities. The country's national pharmaceutical regulator accelerates GMP certification timelines for contract manufacturers serving export markets. Maharashtra's biopharma manufacturing corridor attracts media localization investments from suppliers seeking tariff advantages in regional supply chains.
Switzerland
Swissmedic oversight of cell and gene therapy manufacturing imposes stringent traceability requirements that favor premium chemically defined formulations. Basel's pharmaceutical innovation cluster drives specialized media development for continuous bioprocessing applications. The Lake Geneva region anchors R&D partnerships between media formulators and biotech ventures developing novel viral vector platforms.
Cell Culture Media Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated life science conglomerates commanding therapeutic-grade supply chains while regional laboratories serve research applications. Three tiers structure competitive positioning: multinational corporations with global distribution networks, mid-scale specialists with formulation customization capabilities, and regional distributors with logistics advantages in emerging markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers seek to lock in multi-year service contracts with CDMOs scaling gene therapy manufacturing.
Among diversified life science conglomerates, Thermo Fisher Scientific and Danaher Corporation occupy positions anchored by global distribution infrastructure and recurring revenue service models. Sartorius AG exemplifies the European specialist archetype, with integrated bioreactor-media bundles reducing process variability for gene therapy producers. Merck KGaA represents the chemically defined formulation leader, competing on compliance with tightening EMA and FDA biosafety standards across European and Asian manufacturing suites.
| Leading Market Players |
|---|
| Sartorius AG |
| Corning Incorporated |
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| FUJIFILM Corporation |
| Merck KGaA |
| Lonza Group |
| HiMedia Laboratories |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
EMA's tightening TSE/BSE risk material guidelines gate qualified supply for chemically defined media, restricting premium-tier pricing access to manufacturers with documented absence of animal-origin components and validated ISO 13485 quality systems.
Pricing Analysis
Capacity additions in China are reshaping price floors for serum-free CHO cell culture formulations, compressing margins on standard-grade products while premium chemically defined media retains pricing power through EMA compliance certification. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated formulations from research-grade alternatives, with customization level and certification tier as primary differentiation drivers. Price erosion runs through high-volume biosimilar manufacturing contracts as Chinese CDMOs consolidate purchasing power. Academic institutions exhibit highest price sensitivity; gene therapy CDMOs demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Cold-chain logistics costs for liquid media concentrates concentrate supply chain investment around regional distribution hubs in the United States, Germany, and China. Pharmaceutical-grade amino acid purification and recombinant growth factor production draws from specialized suppliers in Switzerland, South Korea, and the United States. Single-source vulnerability for critical cytokine inputs creates procurement risk for chemically defined formulations. Distribution runs through direct supplier-to-CDMO contractual relationships with multi-year service agreements, bypassing traditional distributor channels for therapeutic-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
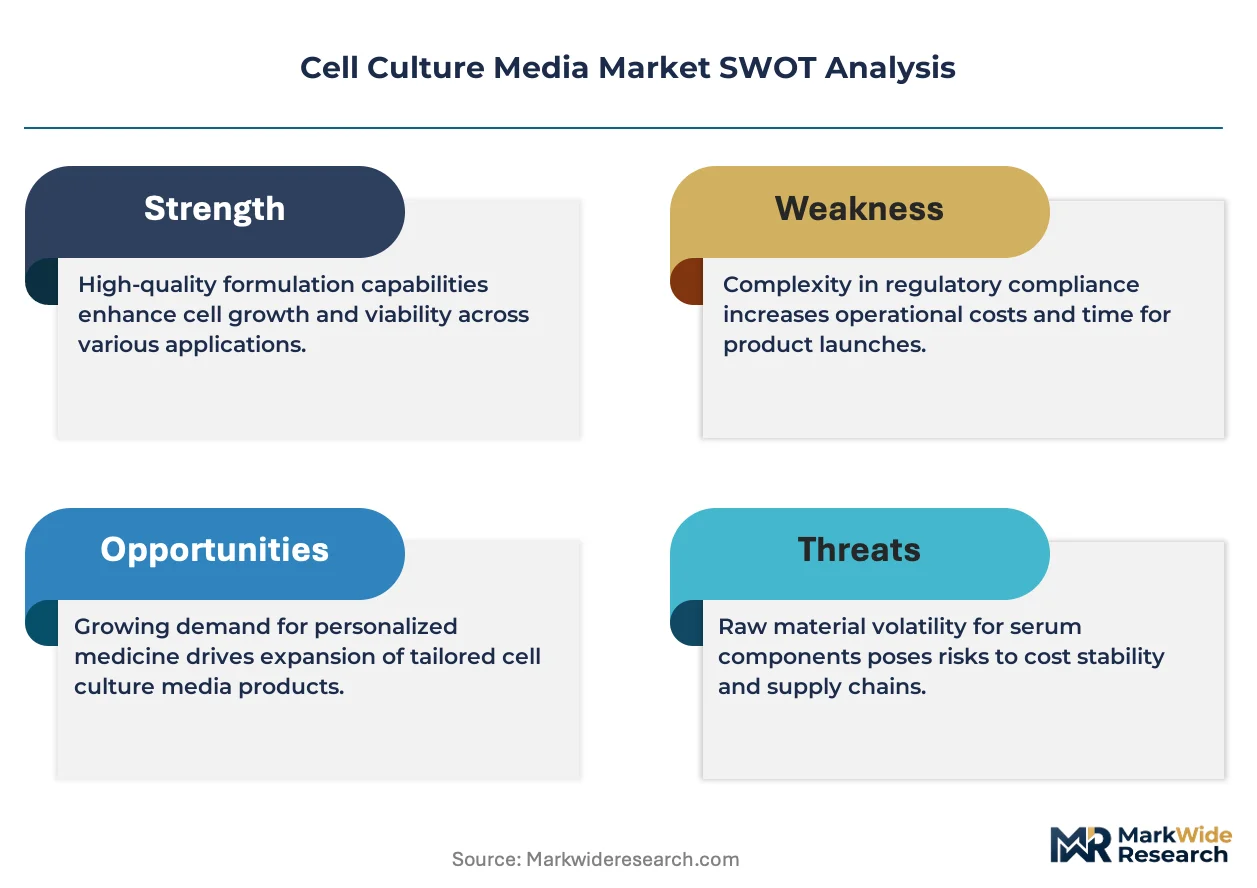
This market reads as a late-cycle quality story: EMA's 2027 compliance deadline for advanced therapy medicinal products is forcing rapid demand migration toward premium chemically defined formulations with full traceability documentation.
For Market Incumbents: Anchor formulation consistency through captive supply of recombinant growth factors, insulating against single-source supplier concentration risk that threatens batch release timelines. Deepen backward integration into pharmaceutical-grade amino acid purification to defend margin position against agricultural commodity volatility. Lock CDMO accounts into integrated bioreactor-media bundles that raise switching costs as gene therapy manufacturing scales. For New Entrants and Emerging Players: Direct-to-biotech digital procurement platforms offer white-space entry points for ready-to-use powder formats targeting venture-funded developers with limited in-house formulation capacity. India's CDSCO-aligned GMP certification pathway represents the most penetrable geography for serum-free media localization. Lead with media-as-a-service subscription pricing to displace spot purchasing at high-throughput contract research organizations. For Investors and Strategic Acquirers: Roll-up economics work for regional media specialists with formulation customization capabilities because CDMO consolidation is concentrating purchasing power and favoring multi-supplier redundancy strategies. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity chemistry. Watch for EMA investigational medicinal product dossier rejection rates as the inflection signal for chemically defined media demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Perfusion bioreactor feed formulation investments capture continuous manufacturing demand from CDMOs in Boston and San Francisco corridors. |
| Regulatory Approval Pathway | ISO 13485 quality system certification opens GMP therapeutic-grade supply chains blocked to research-grade competitors. |
| Backward Integration | In-house recombinant growth factor production reduces single-source dependency risks flagged by FDA biologics guidance. |
| Long-term Supply Agreement | Multi-year media-as-a-service contracts with CDMO clusters in Germany and China lock in recurring revenue streams. |
| Platform Integration | AI-driven formulation optimization platforms compress fed-batch development cycles for gene therapy viral vector producers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioprocess engineers at CDMO facilities, regulatory affairs leads at media formulators, procurement directors at pharmaceutical companies, and quality assurance officers at GMP manufacturing suites with secondary validation against FDA biologics guidance documents, EMA biosafety standards, ISO 13485 certification databases, and NMPA cell line qualification filings. Bottom-up media volume estimates by formulation type and application triangulated against top-down biopharmaceutical manufacturing capacity expansion data.
Historical reference periods anchored the projection horizon through metabolic flux modeling of nutrient consumption rates across fed-batch and perfusion culture platforms. Segmentation dimensions spanned formulation complexity, therapeutic application modality, end-user quality system maturity, and regional regulatory cluster alignment. CAGRs derived from slope-log regression of capacity expansion trajectories and substitution elasticity estimates for serum-free versus chemically defined media adoption, incorporating viral vector manufacturing scale-up assumptions and CDMO concentration patterns.
The model assumes a particular technology adoption path; alternative pathways for AI-driven formulation optimization would alter the outlook if machine learning platforms accelerate media development cycle compression beyond current metabolic flux analysis capabilities. Forecasts reflect assumptions about EMA compliance deadline adherence and NMPA-ICH Q5D alignment timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Antibodies Contract Manufacturing Market