
 Latin America Insulin Pens Market | 2026-2036
Latin America Insulin Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Insulin Pens Market Insights
Subscription-based connected pen services is broadening what manufacturers monetize beyond hardware. Novo Nordisk A/S leverages digital ecosystem partnerships to sustain recurring revenue from dose-tracking platforms. Sanofi S.A. anchors its position through specialized diabetes care networks that extend across major Latin American metropolitan markets. Eli Lilly and Company competes on manufacturing scale, positioning its prefilled pen portfolio for tender-driven procurement channels.
Insulin pens are handheld injection devices designed to deliver precise, repeatable doses of insulin via a disposable or replaceable cartridge system, typically featuring click-dose adjustment mechanisms accurate to one-unit increments. Their primary purpose centers on enabling self-administration by diabetic patients outside clinical settings, reducing dependency on syringe-and-vial protocols. Prefilled pens currently dominate volume across Latin America due to convenience and lower infection risk, while smart pens integrating dose logging represent the fastest-expanding margin pool as wireless connectivity penetrates homecare segments. Reusable pens retain substantial share in price-sensitive markets where cartridge replacement economics outperform disposable alternatives.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia each enforce medical device registration requirements that determine market access timelines and clinical data obligations for pen manufacturers. These frameworks shape competitive dynamics by favoring sponsors with established regulatory infrastructure and local quality management certifications. Stakeholders must monitor how impending harmonization of Latin American medical device standards affects dossier requirements and inspection reciprocity across the region's major jurisdictions.
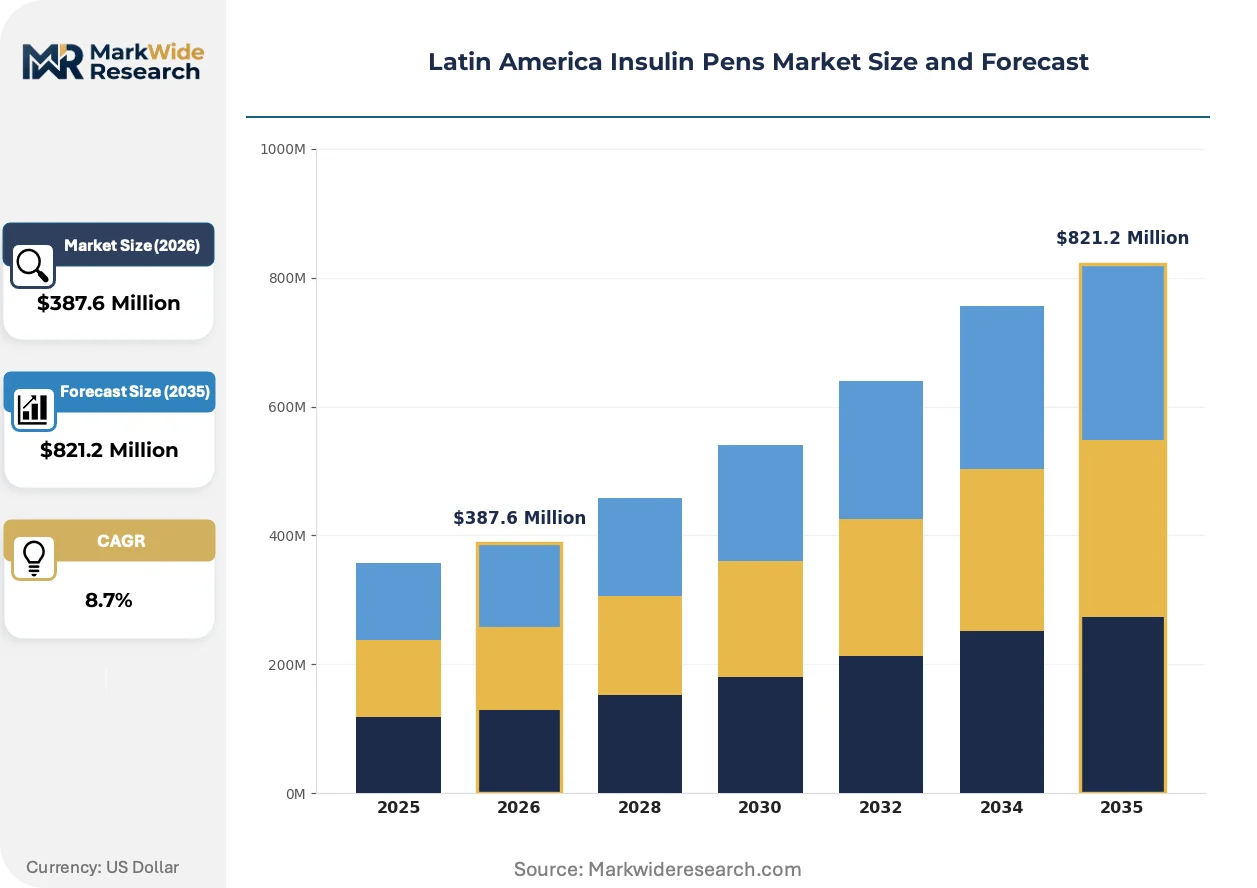
Market Dynamics
Digital dose-logging platforms are absorbing capital allocation across Latin American insulin pen portfolios, converting hardware vendors into recurring-revenue service providers as Brazil's homecare expansion accelerates patient data monetization.
Growth Catalysts
- Brazil ANVISA Streamlining:The regulator's consolidated medical device registration pathways compress market entry timelines for pen manufacturers, reducing clinical data resubmission burdens for established sponsors.
- Homecare Self-Administration:Diabetic patients across metropolitan São Paulo and Mexico City are migrating from syringe-vial protocols to prefilled pen systems, driven by infection risk reduction and dosing precision.
- Connected Pen Ecosystems:Bluetooth-enabled dose trackers integrate with mobile health platforms, enabling remote glycemic monitoring that expands reimbursable service categories for endocrinology practices.
Market Restraints
- Import Tariff Cascades:Argentine customs duties on finished medical devices inflate landed costs for disposable pen systems, compressing margins on volume-tier products.
- Single-Source Cartridge Supply:Concentrated API manufacturing in Asian contract facilities creates vulnerability to shipping disruptions affecting prefilled pen availability across Latin American distribution channels.
- Reusable Pen Durability:Mechanical click-dose mechanisms in legacy reusable systems exhibit calibration drift after extended cycling, limiting reliability in high-frequency injection regimens.
Strategic Opportunities
- Colombia INVIMA Fast-Track:The regulator's priority review designation for diabetes devices with digital connectivity components accelerates approval timelines relative to conventional pen submissions.
- Public Tender Digitization:Brazil's SUS procurement platform is transitioning to electronic reverse auction formats, creating transparency advantages for manufacturers with localized quality certifications.
- Smart Pen Subscription Models:Hardware-as-a-service frameworks bundle disposable cartridges with data analytics platforms, capturing lifetime value from chronic patients in private insurance networks.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity validation queues at ANVISA-recognized laboratories extend pre-market timelines for novel pen materials.
- Legacy ERP Integration:Dose-logging platforms require middleware adaptation to interface with hospital information systems prevalent across Mexican public health institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Insulin Pens Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefilled Pens, Reusable Pens, Disposable Pens, Smart Pens End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Electromechanical, Manual, Wireless, Digital Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Novo Nordisk A/S, Sanofi S.A., Eli Lilly and Company, Medtronic Plc, Biocon, Biocorp, Owen Mumford Ltd., F. Hoffmann-La Roche AG, BD, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Insulin Pens Market Trends and Innovations
Wireless connectivity modules are penetrating insulin pen architectures at accelerating rates, transforming injection devices into data capture endpoints within integrated diabetes management workflows across Brazilian and Mexican healthcare networks.
Near-field communication chips embedded in disposable pen housings is absorbing authentication and adherence-tracking functions previously requiring separate smartphone applications. Endocrinology clinics in Rio de Janeiro and São Paulo are piloting these systems for remote patient monitoring. The technology is absorbing compliance verification burdens from clinical staff while generating real-world evidence streams for payer negotiations.
ANVISA's forthcoming software-as-medical-device guidance is formalizing validation requirements for dose-logging algorithms, establishing precedent for Latin American digital health regulation. Manufacturers must demonstrate cybersecurity resilience and clinical accuracy across cloud-connected pen platforms. Prefilled pen portfolios with integrated connectivity are prioritizing compliance investments to secure first-mover positioning in Brazil's evolving framework.
Pharmacy chain consolidation across Mexico and Colombia is compressing distribution layers, with direct-to-patient subscription channels bypassing traditional wholesale markups. Diabetes patients in Buenos Aires and Santiago are migrating to automated refill programs linked to continuous glucose monitor data. Brazil's private insurance sector exhibits the most pronounced channel shift, where integrated digital health benefits packages bundle pen delivery with remote physician consultations.
Latin America Insulin Pens Market Segmentation
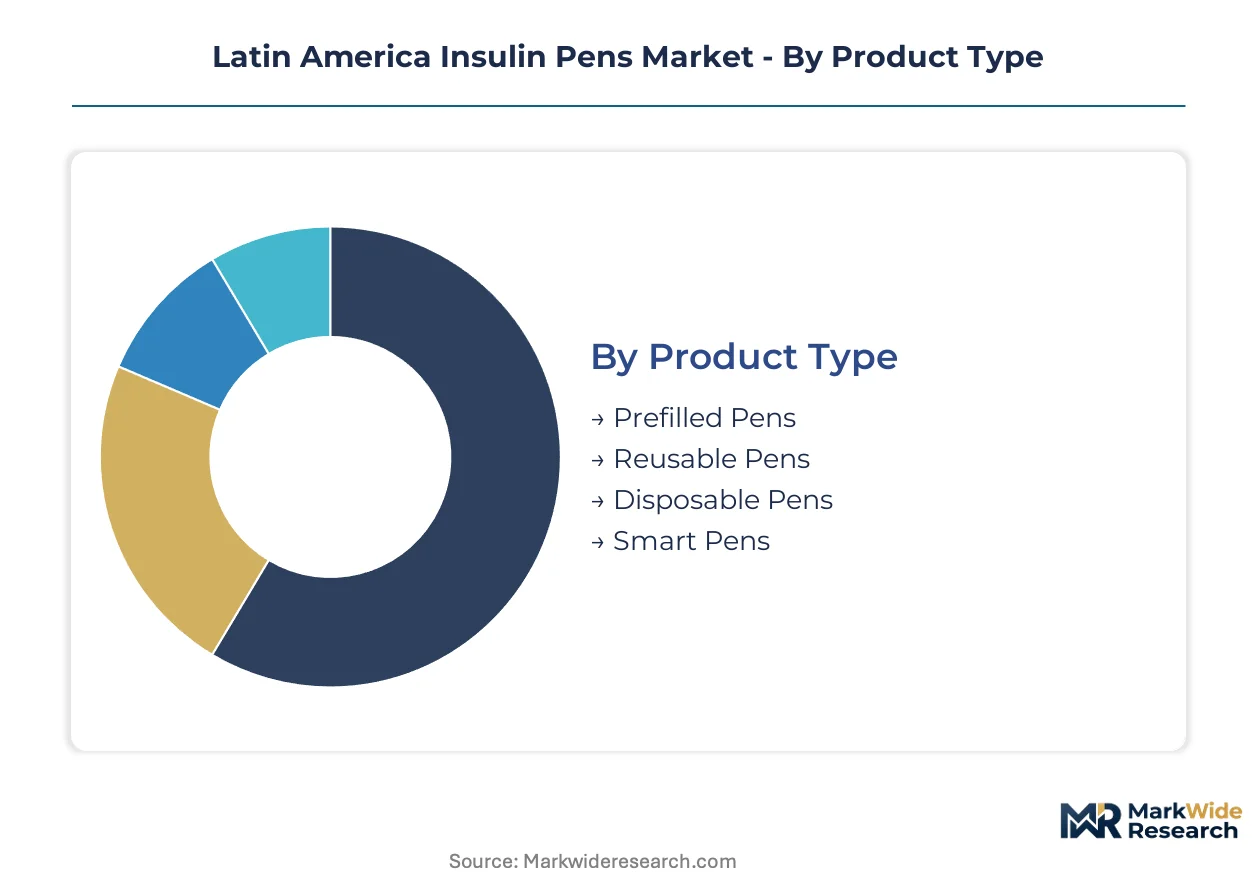
Insulin pen segmentation across Latin America reveals distinct capital requirements and margin architectures that determine manufacturer portfolio priorities. Each dimension—product format, care setting, technology platform, and channel structure—carries specific investment thresholds and regulatory burdens that shape competitive positioning in Brazil, Mexico, and Argentina.
Product Type:
Prefilled and smart pen systems demand substantially higher upfront capital allocation than reusable alternatives, driven by cartridge manufacturing infrastructure and embedded electronics development costs.
- Prefilled Pens:These devices integrate insulin cartridges within sealed, ready-to-use housings that eliminate vial-transfer contamination risk. Homecare adoption across São Paulo and Mexico City concentrates demand for these systems, where infection control protocols and dosing convenience drive procurement decisions in both public tenders and private insurance networks.
- Smart Pens:Bluetooth-enabled dose trackers with cloud connectivity require software validation investments and ongoing platform maintenance expenditures. Brazilian endocrinology practices in Rio de Janeiro are absorbing these systems fastest, where remote glycemic monitoring expands reimbursable service categories and generates real-world evidence for payer negotiations.
- Reusable Pens:Mechanical cartridge-replacement systems retain substantial share in Argentine price-sensitive markets where landed import costs inflate disposable alternatives.
- Disposable Pens:Single-use devices with pre-loaded insulin volumes serve acute care transitions and travel-oriented patient segments across Colombian pharmacy chains.
Prefilled pens absorb the bulk of installed capacity; smart pens are expanding most quickly.
End User:
Care setting segmentation tracks the migration of diabetes management from institutional sites to patient-controlled environments, with capital deployment shifting accordingly toward homecare logistics and direct-to-patient platforms.
- Homecare:Self-administration by diabetic patients outside clinical settings now dominates volume across Brazil's aging population corridors. São Paulo metropolitan expansion of continuous glucose monitor integration with pen-based delivery creates infrastructure demands for remote monitoring platforms and automated refill systems.
- Hospitals:Acute care facilities in Mexico City and Buenos Aires maintain concentrated procurement for inpatient glycemic management, where standardized dosing protocols and formulary control govern device selection.
- Clinics:Outpatient endocrinology practices across Santiago and Bogotá serve as prescription gatekeepers and adherence monitoring hubs.
- Pharmacies:Retail dispensing points in Brazilian pharmacy chain consolidation capture patient touchpoints for device education and cartridge replenishment.
Homecare settings command the dominant patient volume; hospital procurement maintains the highest per-unit pricing power.
Technology:
Technology tiering separates electromechanical precision systems from basic manual devices, with wireless and digital platforms absorbing disproportionate R&D investment relative to their current volume share.
- Wireless:Near-field communication and Bluetooth modules embedded in pen housings enable dose logging without separate smartphone applications. Rio de Janeiro clinics pilot these systems for compliance verification and real-world evidence generation, absorbing authentication burdens from clinical staff.
- Digital:Cloud-connected platforms with algorithmic dose recommendations require ANVISA software-as-medical-device validation, creating compliance investment barriers that favor established sponsors with regulatory infrastructure.
- Electromechanical:Motorized dose delivery systems with electronic displays serve vision-impaired patient segments and high-frequency injection regimens.
- Manual:Mechanical click-dose mechanisms with tactile feedback retain cost advantages in public tender channels across price-sensitive markets.
Manual technology retains volume leadership; wireless platforms are gaining share fastest.
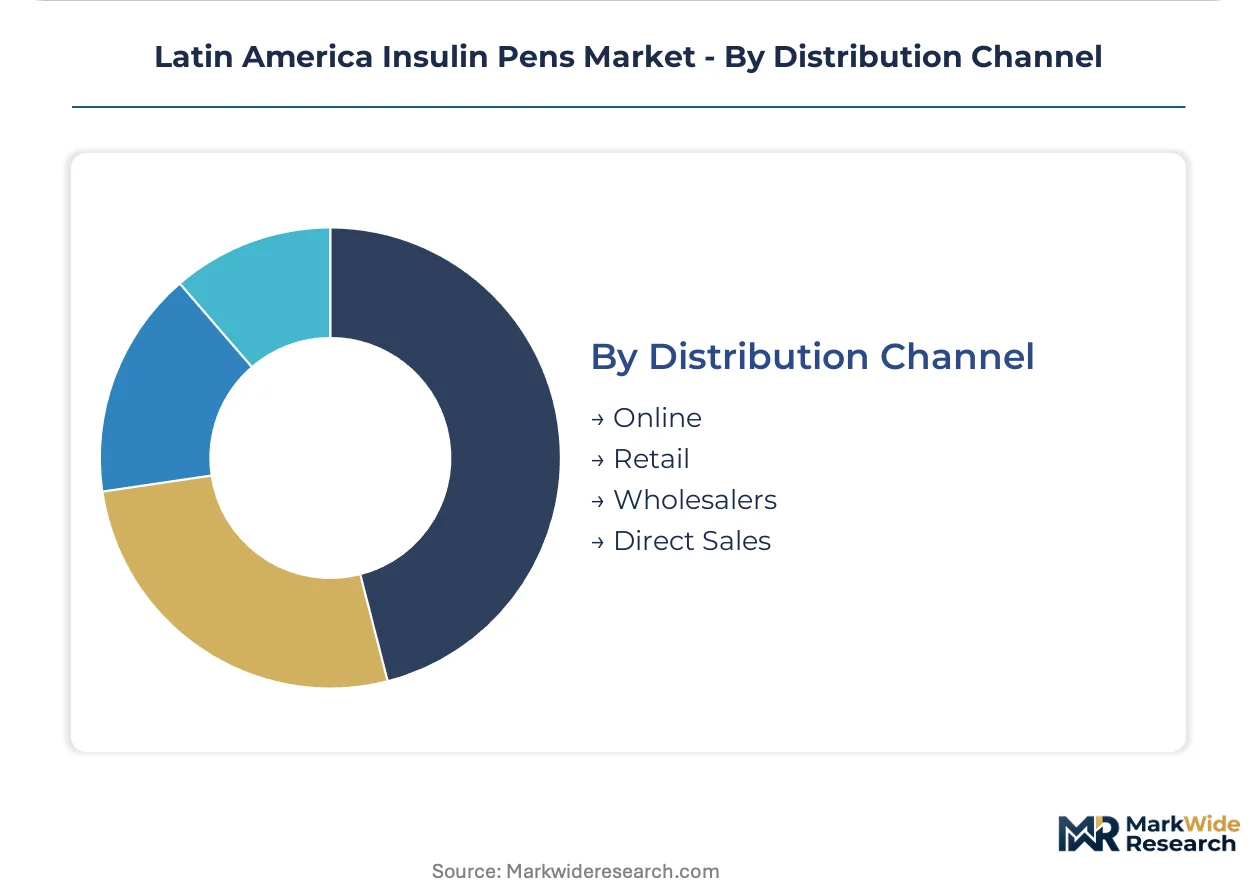
Distribution Channel:
Channel structure determines working capital intensity and margin capture, with direct and online platforms requiring fulfillment infrastructure investments that diverge from traditional wholesale relationships.
- Direct Sales:Manufacturer-to-institution relationships govern public tender participation in Brazil's SUS procurement platform, where electronic reverse auction formats reward localized quality certifications and transparent pricing.
- Retail:Pharmacy chain consolidation across Mexico and Colombia compresses distribution layers, with storefront networks providing patient education and device troubleshooting.
- Online:Subscription-based automated refill programs linked to continuous glucose monitor data are penetrating Brazil's private insurance sector, where integrated digital health benefits packages bundle pen delivery with remote physician consultations.
- Wholesalers:Traditional distribution intermediaries maintain presence in Argentine markets with fragmented pharmacy infrastructure and import logistics complexity.
Retail channels handle the majority of transaction volume; online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin American insulin pen consumption outpaces regional manufacturing capacity, with finished devices and API inputs flowing primarily from European and Asian production centers. Brazil absorbs the largest import volume, while Mexico serves as a secondary distribution hub for Central American markets.
Brazil
ANVISA's consolidated registration pathways compress approval timelines for pen manufacturers entering the public procurement system. São Paulo's metropolitan corridor drives homecare adoption through integrated continuous glucose monitor networks. Rio de Janeiro endocrinology clinics pilot near-field communication-enabled dose verification systems.
Mexico
COFEPRIS maintains medical device registration requirements that favor sponsors with established quality management certifications. Mexico City anchors demand for prefilled pen systems across private insurance networks. Pharmacy chain consolidation in Nuevo León compresses distribution layers toward direct-to-patient subscription channels.
Argentina
Import tariff structures on finished medical devices inflate landed costs for disposable pen systems. Buenos Aires concentrates the addressable patient base within metropolitan diabetes care networks. Provincial public health institutions outside the capital maintain reusable pen procurement due to cartridge replacement economics.
Colombia
INVIMA's priority review designation for digitally connected diabetes devices accelerates approval timelines relative to conventional submissions. Bogotá outpatient endocrinology practices serve as prescription gatekeepers for pen-based delivery systems. Pharmacy retail networks in Medellín capture patient touchpoints for device education and automated refill enrollment.
Chile
The national pharmaceutical regulator enforces ISO 13485 quality system certifications for pen device importers. Santiago's private insurance sector exhibits pronounced channel shift toward integrated digital health benefits packages. Northern mining regions generate concentrated demand for durable pen systems in remote occupational health settings.
Latin America Insulin Pens Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through digital ecosystem integration, while mid-scale specialists compete on manufacturing scale and tender-driven procurement channels. The market structure consolidates around three strategic archetypes: connected-device platform sponsors, high-volume prefilled pen manufacturers, and regional quality-certified distributors. Competitive moves concentrate on strategic partnerships with pharmacy chains and localized regulatory infrastructure investments.
Among European-origin pharmaceutical sponsors, Novo Nordisk A/S and Sanofi S.A. exemplify the connected-device archetype through digital health platform positioning. Eli Lilly and Company occupies a scale-driven position within prefilled pen manufacturing. These three entities represent divergent strategic vectors: ecosystem monetization, specialized diabetes care networks, and tender-optimized production capacity.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi S.A. |
| Eli Lilly and Company |
| Medtronic Plc |
| Biocon |
| Biocorp |
| Owen Mumford Ltd. |
| F. Hoffmann-La Roche AG |
| BD |
| Others |
Pricing and Supply Chain Analysis
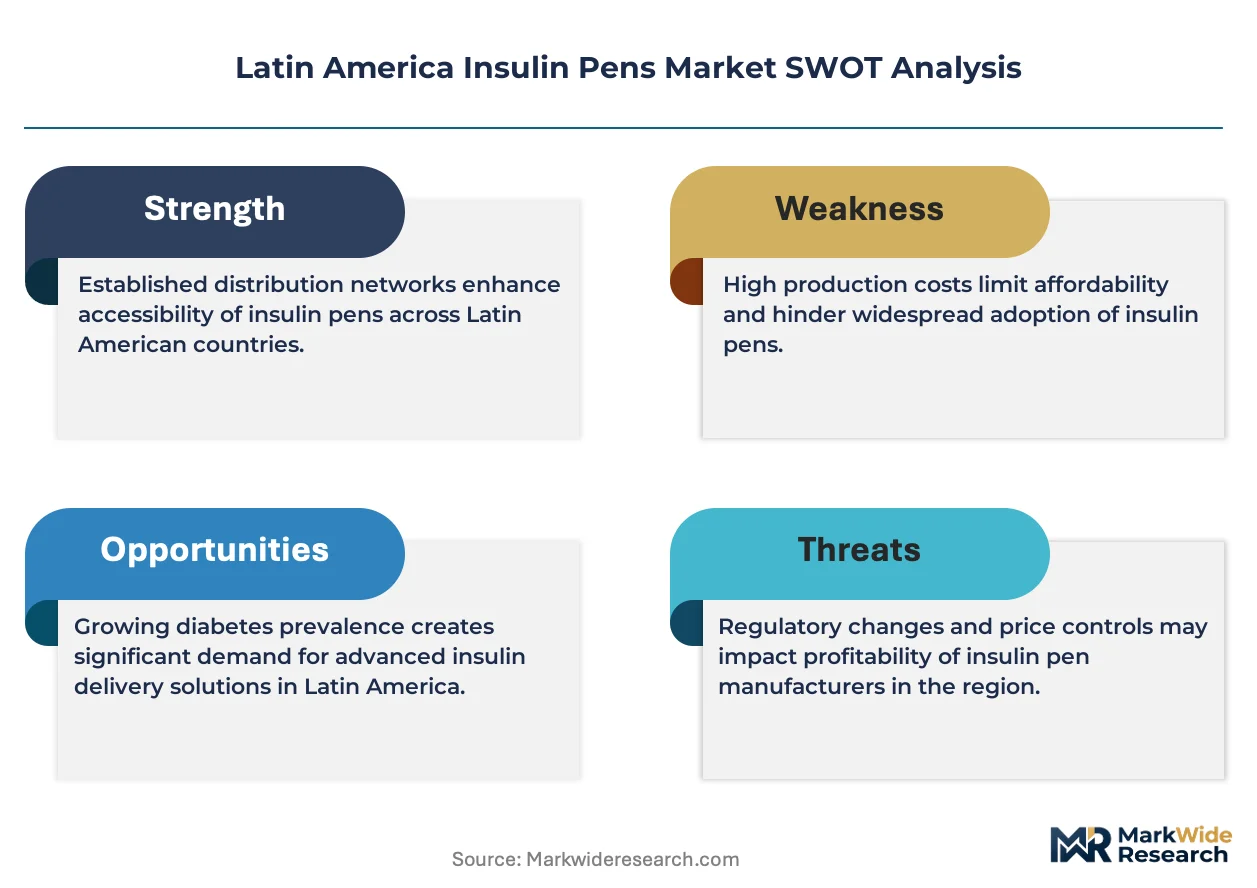
API feedstock price indices for recombinant insulin and biocompatible polymers cascade through Latin American insulin pen supply chains, compressing margins on prefilled disposable systems while amplifying pricing power for connected-device sponsors with software-recovery mechanisms.
Pricing Analysis
Margin tightening in standard-tier prefilled pens reflects concentrated API manufacturing in Asian contract facilities and Argentine import tariff structures on finished devices. Three-tier pricing structure across premium smart pens, standard prefilled systems, and economy reusable alternatives separates sponsors by digital ecosystem maturity and ANVISA quality certification status. Cost-down pressure on disposable pen portfolios accelerates because pharmacy chain consolidation in Mexico and Colombia squeezes wholesale markups. Public tender channels exhibit highest price sensitivity; private insurance networks with bundled digital health benefits show lowest.
Supply Chain Analysis
Direct-to-hospital channels handle concentrated procurement from Brazil's SUS electronic reverse auction platform, while retail pharmacy networks manage fragmented patient-level demand across metropolitan São Paulo and Mexico City. Finished device manufacturing concentrates in Germany, Denmark, and Ireland; API production draws from South Korean, Chinese, and Indian biologics facilities. Single-source cartridge supply from Asian contract manufacturers creates vulnerability to shipping disruptions affecting prefilled pen availability. Distribution runs through manufacturer-direct tenders, consolidated pharmacy chains, and emerging subscription-based direct-to-patient platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's software-as-medical-device guidance and ISO 10993 biocompatibility testing requirements erect substantial compliance moats that favor established sponsors with localized quality infrastructure and regulatory affairs capabilities.
For Market Incumbents: To counter emerging connected-pen platform entrants from European pharmaceutical sponsors, incumbents should deepen backward integration into cartridge manufacturing capacity within Mercosur trade zones to deflect Argentine tariff exposure, while accelerating ANVISA software validation investments to secure first-mover positioning in dose-logging algorithm approvals.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Brazilian homecare settings creates white-space entry opportunities for mid-tier reusable pen systems with simplified electromechanical dosing. New entrants should target provincial public health institutions outside Buenos Aires where cartridge replacement economics outperform disposable alternatives, deploying localized quality certification partnerships as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with ANVISA-established quality management systems in Brazilian secondary cities. Long-term viability across the analysis window hinges on digital health platform integration capabilities; investors should monitor INVIMA fast-track approval velocity for connected diabetes devices as the inflection signal for platform monetization readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Software-as-Medical-Device Validation | Establishes regulatory precedent for dose-logging algorithm compliance in Brazil's evolving framework. |
| Backward Integration into Cartridge Manufacturing | Captures margin compression from API feedstock volatility and reduces Argentine tariff exposure. |
| Pharmacy Chain Direct Distribution Partnerships | Bypasses wholesale markups in Mexico and Colombia's consolidating retail networks. |
| Subscription-Based Hardware-as-a-Service Launch | Converts chronic patient relationships into recurring revenue streams within private insurance networks. |
| Near-Field Communication Pen Architecture | Absorbs adherence verification burdens from Rio de Janeiro and São Paulo clinical staff. |
Research Methodology
Independent corroboration across endocrinology practice administrators, ANVISA regulatory consultants, hospital procurement managers at SUS-affiliated institutions, and pharmacy chain category buyers underwrites the qualitative findings. Secondary validation draws from ANVISA medical device registration databases, COFEPRIS approval filings, INVIMA priority review designations, and GPO contract repositories. Bottom-up patient-volume modeling and top-down pharmaceutical sponsor revenue triangulation converge on segment-level estimates.
Rate-of-change decomposition across product type, care setting, technology platform, and distribution channel dimensions structures the analytical framework. CAGRs derive from patient population growth trajectories, diabetes prevalence curves, and connected device penetration assumptions. Forecast inputs incorporate ANVISA registration pathway timelines, pharmacy chain consolidation velocity, and private insurance digital benefits adoption patterns.
Inputs from regulatory filing databases and hospital procurement platforms were available through the study window; gaps in real-world connected pen adherence data introduce uncertainty bands around software-as-medical-device revenue projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Polyclonal Antibodies Market