
 Biopharmaceuticals Packaging Market | 2026-2036
Biopharmaceuticals Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharmaceuticals Packaging Market Outlook
Contract manufacturers are rotating toward higher-complexity containment formats as biologics developers outsource fill-finish operations. Gerresheimer AG anchors European supply of borosilicate glass vials through captive tubing operations. West Pharmaceutical Services differentiates via integrated delivery systems combining elastomeric closure with prefillable syringe platforms. Schott AG dominates high-value cyclic olefin polymer packaging for sensitive protein formulations.
Biopharmaceuticals packaging encompasses sterile primary containers, secondary cartoning, and cold-chain distribution systems engineered to maintain product integrity across temperature excursions from minus eighty degrees Celsius to controlled room temperature. Its commercial purpose centers on preventing contamination, ensuring dose accuracy, and enabling regulatory traceability from manufacturing through patient administration. Vials and prefillable syringes lead volume within packaging type as injectable biologics expand, while glass sustains premium positioning despite polymer inroads in break-risk applications. Composites and coated plastics represent the fastest-growing material category where barrier performance must match metalized alternatives at reduced weight.
The FDA enforces current Good Manufacturing Practice standards for container closure integrity, while the EMA's Annex 1 revision mandates barrier-isolation technology for sterile product contact surfaces. These frameworks elevate capital requirements for new entrants and reward incumbents with validated aseptic processing lines. ISO 15378 certification has become a baseline qualifier for supplier qualification audits across major pharmaceutical buyers. Stakeholders must monitor how evolving serialization deadlines and sustainability mandates reshape material selection and regional sourcing strategies.
Market Dynamics
Serialization mandates from the FDA and EMA are compressing supplier qualification timelines while biologics developers demand integrated containment-delivery systems that merge primary packaging with administration devices.
Growth Catalysts
- Annex 1 Barrier Isolation:The EMA's revised sterile manufacturing rules mandate isolator technology for aseptic filling, forcing contract manufacturers to upgrade lines and expand procurement of validated containment systems.
- Cold-Chain Biologics Expansion:Cell and gene therapies requiring minus eighty degrees Celsius distribution are multiplying demand for validated thermal shippers and temperature-assured primary containers across North American and European logistics networks.
- Prefillable Syringe Conversion:Self-administration trends in chronic disease management are accelerating format shifts from vial-and-needle toward integrated syringe systems in rheumatology and diabetes care segments.
Market Restraints
- Borosilicate Glass Supply Concentration:Captive tubing operations in Germany and India control premium glass supply, creating vulnerability for converters without backward integration into furnace operations.
- ISO 15378 Certification Burden:Pharmaceutical buyer audits require quality management certification that demands eighteen-to-twenty-four-month implementation timelines, excluding smaller converters from qualified supplier lists.
- Metalized Film Substitution Pressure:High-barrier aluminum laminates face displacement from cyclic olefin polymer and coated plastic alternatives in break-sensitive applications, compressing margins for legacy foil converters.
Strategic Opportunities
- Smart-Label Integration:Near-field communication and printed electronics embedded in secondary packaging enable real-time cold-chain monitoring, creating service-revenue streams beyond commodity container sales.
- Sustainability-Driven Material Pivots:The EU Green Deal's packaging waste directives are accelerating demand for bio-based barrier coatings and mono-material structures that maintain oxygen and moisture protection without multi-layer complexity.
- Biosimilar Volume Surge:Patent expirations for reference biologics are expanding addressable patient populations in emerging markets, requiring cost-optimized packaging formats that preserve sterile integrity at reduced per-dose cost.
Industry Challenges
- Aseptic Processing Talent Scarcity:Qualified engineers for isolator qualification and media-fill validation are concentrated among incumbent contract manufacturers, constraining capacity expansion timelines for new market entrants.
- Serialization System Integration:Line-level aggregation software must interface with enterprise track-and-trace platforms across multiple national databases, creating implementation complexity for mid-sized packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharmaceuticals Packaging Market |
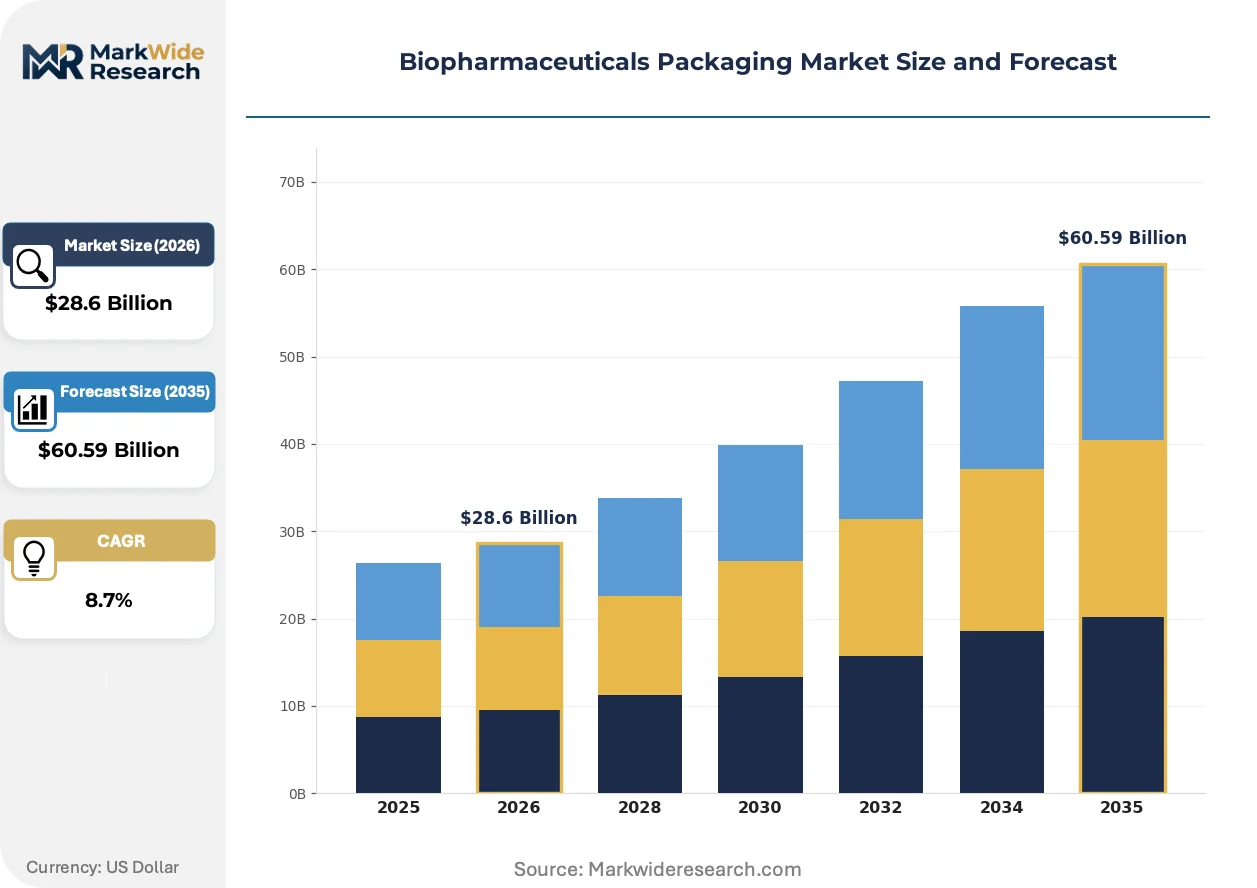
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Vials, Syringes, Ampoules, Bags Material: Glass, Plastics, Aluminum, Composites End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Healthcare Facilities Application: Injectable Drugs, Oral Medications, Biologics, Vaccines |
| Companies Covered | Schott AG, Gerresheimer AG, West Pharmaceutical Services, Becton Dickinson & Co., Amcor Plc, AptarGroup, Berry Global, WestRock Company, SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharmaceuticals Packaging Market Strategic Shifts
Digital integration of primary containers with distribution monitoring systems is collapsing the traditional separation between packaging and logistics infrastructure.
Cyclic olefin polymer is decomposing the historical glass monopoly in protein formulation packaging by combining break resistance with low extractable profiles. Biologics developers in ophthalmology and emergency medicine are adopting COP vials for field-use scenarios where glass fracture risk is unacceptable. This material shift is compressing the addressable market for Type I borosilicate in risk-sensitive applications while expanding polymer converter margins.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer barrier coatings from European pharmaceutical packaging specifications. The ECHA's persistent organic pollutant listings have forced converters to accelerate qualification of silicone oxide and plasma-enhanced chemical vapor deposition alternatives. High-value parenteral applications in Germany and Switzerland are now prioritizing PFAS-free barrier certification in supplier selection criteria.
Biologics developers are consolidating procurement authority at the platform level rather than sourcing containers, closures, and delivery devices separately. Integrated supplier contracts covering fill-finish through final assembly are displacing component-level purchasing in monoclonal antibody and vaccine segments. This concentration is most visible in Massachusetts and North Carolina clusters where contract manufacturers negotiate single-source agreements for complete containment systems.
Biopharmaceuticals Packaging Market Segmentation
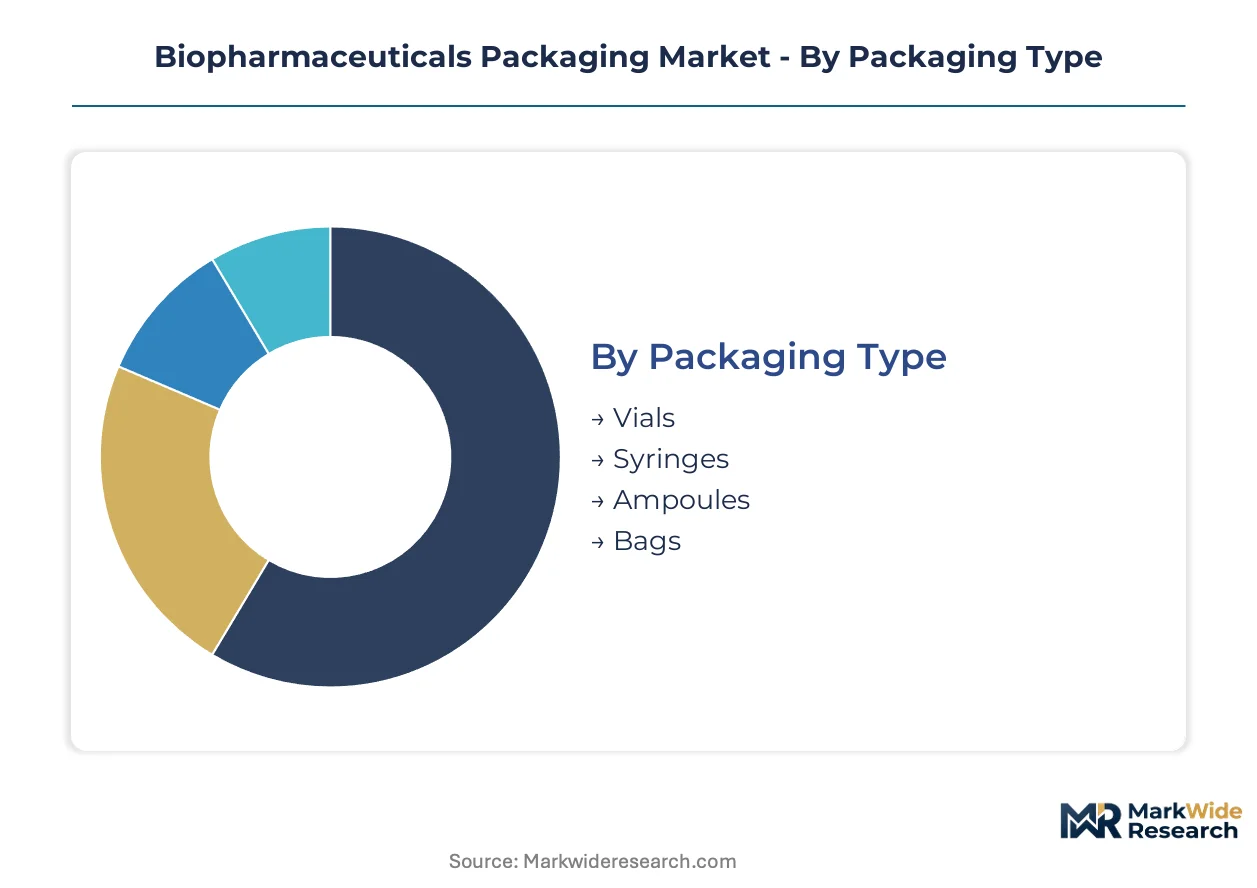
Packaging format selection in biopharmaceuticals hinges on sterilization compatibility, barrier performance, and administration route. Regulatory filing requirements for container closure systems create path dependency once formats are validated, locking developers into specific segment choices through product lifecycles.
Packaging Type:
FDA container closure integrity guidelines and EMA Annex 1 isolator mandates differentiate formats by aseptic processing compatibility and human-factor engineering for administration.
- Vials:Borosilicate glass or cyclic olefin polymer containers with elastomeric closures dominate monoclonal antibody and vaccine storage. Demand concentrates in Massachusetts and North Carolina fill-finish clusters where contract manufacturers operate validated aseptic lines for sterile injectables.
- Syringes:Prefillable systems integrate primary containment with patient-ready administration, eliminating vial-to-syringe transfer steps. Self-administration trends in rheumatology and diabetes care are accelerating format conversion from vial-based regimens in United States chronic disease management.
- Ampoules:Single-dose glass containers with score-break necks serve emergency medicine and field deployment scenarios requiring minimal preparation.
- Bags:Flexible intravenous containers handle large-volume parenteral solutions and diluent storage for reconstitution protocols.
Vials handle the majority of throughput; syringes are gaining share fastest as integrated delivery systems disassemble multi-step administration workflows.
Material:
Cost tier stratification separates premium barrier performance from economy-scale commodity supply, with certification requirements widening the gap between qualified and unqualified converter tiers.
- Glass:Type I borosilicate delivers chemically inert surfaces with documented extractable profiles for protein stability. Gerresheimer AG and Schott AG furnace operations in Germany anchor premium supply, while India-based tubing plants serve cost-optimized biosimilar packaging.
- Plastics:Cyclic olefin polymer and polyethylene terephthalate glycol provide break resistance for field-use and ophthalmic applications. REACH PFAS restrictions are accelerating silicone oxide barrier coating qualification to replace fluoropolymer laminates in European specifications.
- Aluminum:Metalized laminates and cold-form foils maintain ultra-high moisture and oxygen barriers for hygroscopic oral solid doses.
- Composites:Multi-layer structures combining polymer substrates with vapor-deposited barriers deliver metalized performance at reduced weight for cold-chain distribution.
Glass commands premium positioning in validated biologics; plastics are expanding most quickly as break-risk applications diversify beyond traditional glass strongholds.
End User:
Customer procurement maturity determines specification stringency, with pharmaceutical buyers enforcing ISO 15378 certification that excludes smaller converters from qualified supplier lists.
- Pharmaceutical Companies:Originators of novel biologics specify container closure systems during clinical development, creating decade-long supply relationships through regulatory filing lock-in.
- Contract Manufacturers:Lonza, Catalent, and Samsung Biologics aggregate packaging demand across multiple developer clients, negotiating platform-level contracts for integrated containment systems rather than component sourcing.
- Research Institutions:Academic and government laboratories require small-batch sterile containers for investigational compound stability studies and preclinical formulation work.
- Healthcare Facilities:Hospital pharmacies and infusion centers source ready-to-administer formats that minimize compounding steps and reduce medication error risk.
Contract manufacturers concentrate procurement volume; research institutions are climbing the fastest as cell and gene therapy pipelines deepen academic-industry collaboration.
Application:
Administration route and temperature sensitivity dictate barrier specifications, with cold-chain requirements creating material performance thresholds that filter converter participation.
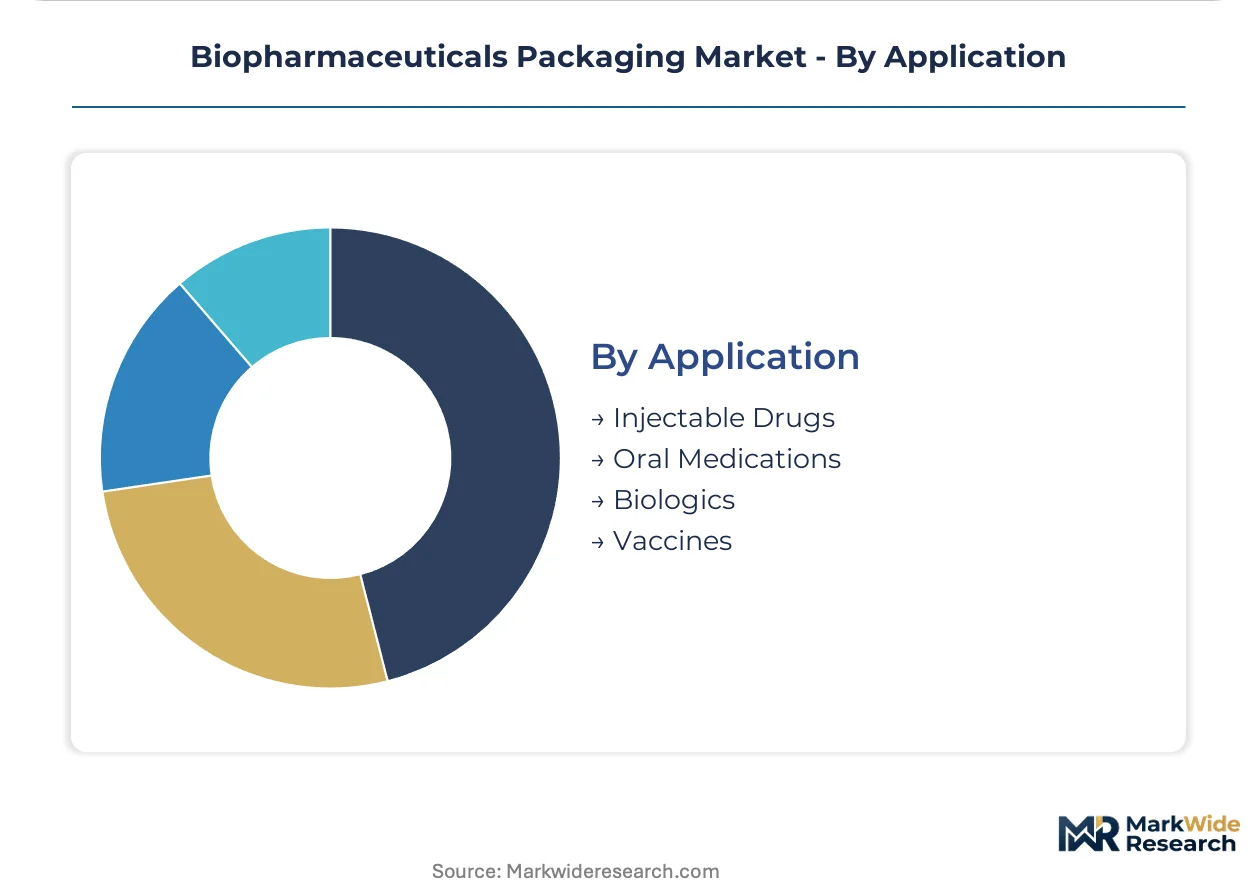
- Injectable Drugs:Parenteral formulations demand absolute container closure integrity validated through dye ingress and microbial challenge testing per USP standards.
- Oral Medications:Solid dose and liquid oral products prioritize moisture protection and child-resistant functionality over aseptic processing compatibility.
- Biologics:Protein-based therapeutics require low-extractable surfaces and demonstrated compatibility with sensitive active ingredients across shelf-life duration.
- Vaccines:Temperature excursions from minus eighty degrees Celsius to controlled room temperature require validated thermal shippers and primary containers with demonstrated stability across excursion profiles.
Injectable drugs anchor volume demand; vaccines are expanding most steeply as mRNA and viral vector platforms proliferate through global immunization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German furnace operations export borosilicate tubing to fill-finish clusters in Massachusetts and North Carolina, establishing a transatlantic supply corridor that anchors premium container sourcing for sterile injectable production.
United States
FDA serialization deadlines and cell therapy cold-chain requirements are accelerating procurement of validated thermal shippers. The Massachusetts biotech corridor concentrates demand for integrated syringe systems as contract manufacturers expand isolator-equipped lines. Lonza and Catalent operations in North Carolina are negotiating platform-level contracts for complete containment systems.
Germany
EMA Annex 1 isolator mandates and REACH PFAS restrictions are reshaping converter qualification criteria. Gerresheimer AG and Schott AG furnace operations in Bavaria and Mainz control captive borosilicate supply for European biologics developers. The country's packaging converters are accelerating silicone oxide barrier coating adoption to replace fluoropolymer laminates.
Switzerland
Swissmedic oversight of high-value parenteral applications and precision manufacturing standards sustain premium positioning for local packaging specialists. Basel's pharmaceutical cluster demands PFAS-free barrier certification in supplier selection criteria. Domestic converters serve as qualification partners for global biologics originators seeking European regulatory alignment.
India
CDSCO alignment with international serialization standards and biosimilar volume expansion are driving cost-optimized format demand. Hyderabad and Bangalore clusters host contract manufacturing organizations scaling sterile injectable capacity for export markets. Domestic tubing plants are serving cost-sensitive biosimilar packaging requirements while upgrading ISO 15378 certification coverage.
China
NMPA traceability mandates and domestic biologics pipeline expansion are accelerating smart-label integration requirements. Shanghai and Suzhou biopharma clusters are localizing supply chains for prefillable syringe components. State-backed capacity investments in cyclic olefin polymer conversion are reducing import dependence for break-resistant primary containers.
Biopharmaceuticals Packaging Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and integration depth. The market structures around three concentration layers: furnace-integrated glass producers, platform-level system integrators, and component-specialist converters. Strategic archetypes include backward-integrated tubing operators, delivery-system integrators, and barrier-coating technology licensors. Capacity expansion in isolator-compatible lines and acquisition of smart-packaging capabilities represent the dominant competitive moves reshaping supplier positioning.
Within the furnace-integrated tier, Schott AG and Gerresheimer AG exemplify archetypes combining captive borosilicate supply with validated pharmaceutical-grade production. West Pharmaceutical Services occupies a position bridging primary containment with integrated delivery systems. These three anchors illustrate how European-headquartered specialists with AG and GmbH structures have consolidated premium positioning through regulatory certification depth and backward integration into material production.
| Leading Market Players |
|---|
| Schott AG |
| Gerresheimer AG |
| West Pharmaceutical Services |
| Becton Dickinson & Co. |
| Amcor Plc |
| AptarGroup |
| Berry Global |
| WestRock Company |
| SGD Pharma |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month ISO 15378 certification timelines concentrate pricing power among furnace-integrated glass producers in Germany and India, while compressing margins for converters lacking backward integration into borosilicate tubing operations. Pharmaceutical buyer audits enforce quality management standards that exclude smaller suppliers from qualified vendor lists, creating tiered procurement access that stratifies pricing across certification grades.
Pricing Analysis
Glass-to-polymer technology-generation pricing gaps separate premium borosilicate vials from cost-optimized cyclic olefin polymer alternatives and emerging bio-based barrier coatings. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15378 certification status, furnace integration depth, and validated aseptic processing line availability. Cost compression in standard-tier glass containers is intensifying because Indian tubing plants are scaling biosimilar supply without matching European barrier-performance specifications. Contract manufacturers demonstrate highest price sensitivity due to platform-level procurement consolidation, while originator pharmaceutical companies accept premium positioning for regulatory filing lock-in security.
Supply Chain Analysis
Inbound logistics costs from German furnace operations to Massachusetts fill-finish clusters hinge on transatlantic container availability and pharmaceutical-grade cold-chain integrity requirements. Captive borosilicate supply concentrates in Germany and India, while cyclic olefin polymer conversion capacity expands in China and South Korea. Raw material dependencies encompass soda ash, boron compounds, and elastomeric closure formulations. Single-source vulnerability from German furnace concentration creates supply risk during isolator line qualification delays. Distribution runs through validated cold-chain logistics networks serving contract manufacturing clusters in Massachusetts, North Carolina, and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopharmaceuticals packaging is entering a cyclical recovery phase as EMA Annex 1 isolator mandates force contract manufacturer capacity upgrades and deepen procurement of validated containment systems.
For Market Incumbents: Fortify isolator-compatible line capacity in North Carolina and Massachusetts clusters to capture contract manufacturer platform-level procurement consolidation. Deepen backward integration into borosilicate furnace operations or secure captive tubing agreements with Gerresheimer AG and Schott AG to defend against Indian cost-optimized supply expansion. ISO 15378 certification depth remains the priority defensive lever. For New Entrants and Emerging Players: Differentiate on PFAS-free barrier coating technology for European REACH compliance, targeting Swiss and German high-value parenteral applications where regulatory alignment commands procurement priority. The most penetrable white space sits in smart-label integration combining near-field communication with cold-chain monitoring for cell and gene therapy distribution. Pursue partnership-based qualification with academic research institutions climbing fastest in cell therapy pipeline collaboration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial packaging parents seeking to divest pharmaceutical-specialist units lacking ISO 15378 certification coverage. Long-term viability centers on regulatory certification moats and isolator technology integration depth over commodity container scale. Watch for inflection signals in EMA serialization deadline enforcement and EU Green Deal packaging waste directive implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Line Qualification | EMA Annex 1 mandates barrier-isolation technology for sterile product contact surfaces, forcing capital deployment. |
| PFAS-Free Barrier Certification | REACH restrictions eliminate fluoropolymer coatings, accelerating silicone oxide and plasma-enhanced alternatives in Europe. |
| Smart-Label Integration | Near-field communication embedded in secondary packaging creates service-revenue streams beyond commodity container sales. |
| Platform-Level Contract Consolidation | Integrated supplier agreements covering fill-finish through final assembly displace component-level purchasing in monoclonal antibody segments. |
| Cyclic Olefin Polymer Capacity Expansion | Break-resistant COP vials decompose glass monopoly in protein formulations for ophthalmology and emergency medicine applications. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs directors at contract manufacturing organizations, pharmaceutical packaging procurement leads, and aseptic processing engineers, then refined through secondary validation against FDA container closure integrity guidance documents, EMA Annex 1 revision drafts, and ISO 15378 certification audit records. Bottom-up demand modeling triangulated with top-down market sizing across packaging format, material grade, and end-user procurement maturity segments.
Variance decomposition across the projection horizon isolates volume drivers by packaging type, material barrier performance tier, and regional regulatory cluster stringency. CAGRs were derived from segment-level growth rate reconciliation against macro biologics pipeline expansion and cold-chain infrastructure investment patterns. Forecast inputs incorporate EMA serialization deadline phasing, REACH PFAS restriction timelines, and contract manufacturer capacity expansion announcements.
Forecasts assume regulatory continuity in FDA current Good Manufacturing Practice enforcement and EMA Annex 1 implementation; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated EU Green Deal packaging waste directives, borosilicate glass supply disruption from furnace operational incidents, and biosimilar volume surge timing in emerging markets. Recalibration cycles align with material shifts in serialization mandate enforcement and sustainability-driven material pivot adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
East Africa Generic Drug Market