
 A - Estradiol Market | 2026-2036
A - Estradiol Market Size, Share, and Industry Trends Forecast 2026-2036
A - Estradiol Market Analytics
Aftermarket service revenue from patient compliance programs and refill logistics is narrowing as pharmaceutical manufacturers internalize these functions to capture lifetime value per prescription. Pfizer Inc. leverages its specialty pharmacy networks to sustain direct-to-patient delivery models. Bayer AG anchors European distribution through wholesaler partnerships that control hospital formulary access. Novartis AG competes on biosimilar estradiol development, positioning its pipeline for post-patent substitution.
A - Estradiol is the primary endogenous estrogen, a C18 steroid hormone synthesized from cholesterol via aromatase conversion of testosterone, with therapeutic applications centered on restoring estrogenic activity in hypoestrogenic states. Injectable formulations command premium pricing due to compounding pharmacy requirements and parenteral administration protocols, while transdermal patches represent the fastest-expanding segment as patients and clinicians prioritize steady-state plasma levels over hepatic first-pass metabolism. Oral tablets remain the mature volume base, though margin pools are migrating toward intravaginal rings where localized delivery reduces systemic exposure and supports extended dosing intervals.
FDA bioequivalence guidelines and EMA quality standards for estradiol drug products shape formulation development timelines and generic entry pathways across the United States and European markets. The EPA monitors pharmaceutical manufacturing discharge, adding environmental compliance costs to active pharmaceutical ingredient production facilities. Stakeholders must monitor evolving reimbursement criteria for compounded versus manufactured estradiol products as payers recalibrate coverage policies.
Market Dynamics
Transdermal patch manufacturing scale-up is compressing oral tablet margins as hormone replacement therapy clinics prioritize steady-state pharmacokinetics over cost-minimization, forcing formulation portfolios toward localized delivery systems.
Growth Catalysts
- FDA Bioequivalence Standards:Tightening requirements for generic estradiol products are accelerating investment in advanced transdermal matrix technologies that demonstrate therapeutic equivalence through pharmacokinetic studies.
- Germany's Reimbursed Access Expansion:Statutory health insurance coverage for intravaginal ring formulations is pulling volume toward extended-interval localized delivery systems in hospital outpatient settings.
- Aromatase Inhibition Reversal Protocols:Oncology adjuvant therapy programs are creating sustained demand for parenteral estradiol in breast cancer survivor populations requiring hormonal restoration.
Market Restraints
- Soy-Derived Phytosterol Input Volatility:Agricultural commodity price swings in Brazilian soybean harvests are destabilizing semi-synthetic estradiol precursor costs for generic manufacturers.
- EPA Pharmaceutical Discharge Monitoring:Environmental compliance mandates for active pharmaceutical ingredient production facilities are adding fixed-cost burdens to fermentation-based synthesis operations.
- Compounded Pharmacy Substitution:Custom-dosed parenteral formulations from 503B outsourcing facilities are fragmenting demand away from standardized manufactured products in cash-pay segments.
Strategic Opportunities
- Menopausal Symptom Digital Therapeutics Bundling:Integration of connected patch delivery systems with remote patient monitoring platforms is opening subscription revenue streams in United States value-based care contracts.
- Biosimilar Estradiol Development Pathways:EMA biosimilar guidance for complex hormone products is creating regulatory clarity for follow-on developers targeting European hospital tender markets.
- Long-Acting Injectable Depots:Polymeric microsphere encapsulation technologies enabling quarterly administration are addressing compliance gaps in rural and aging patient populations.
Industry Challenges
- Bioanalytical Method Transfer Complexity:Cross-laboratory validation of estradiol metabolite assays is extending clinical trial timelines for novel formulation submissions to FDA.
- Cold Chain Integrity for Biologic Combinations:Temperature-controlled distribution requirements for estradiol-progestin combination therapies are constraining pharmacy network expansion in warmer climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A - Estradiol Market |
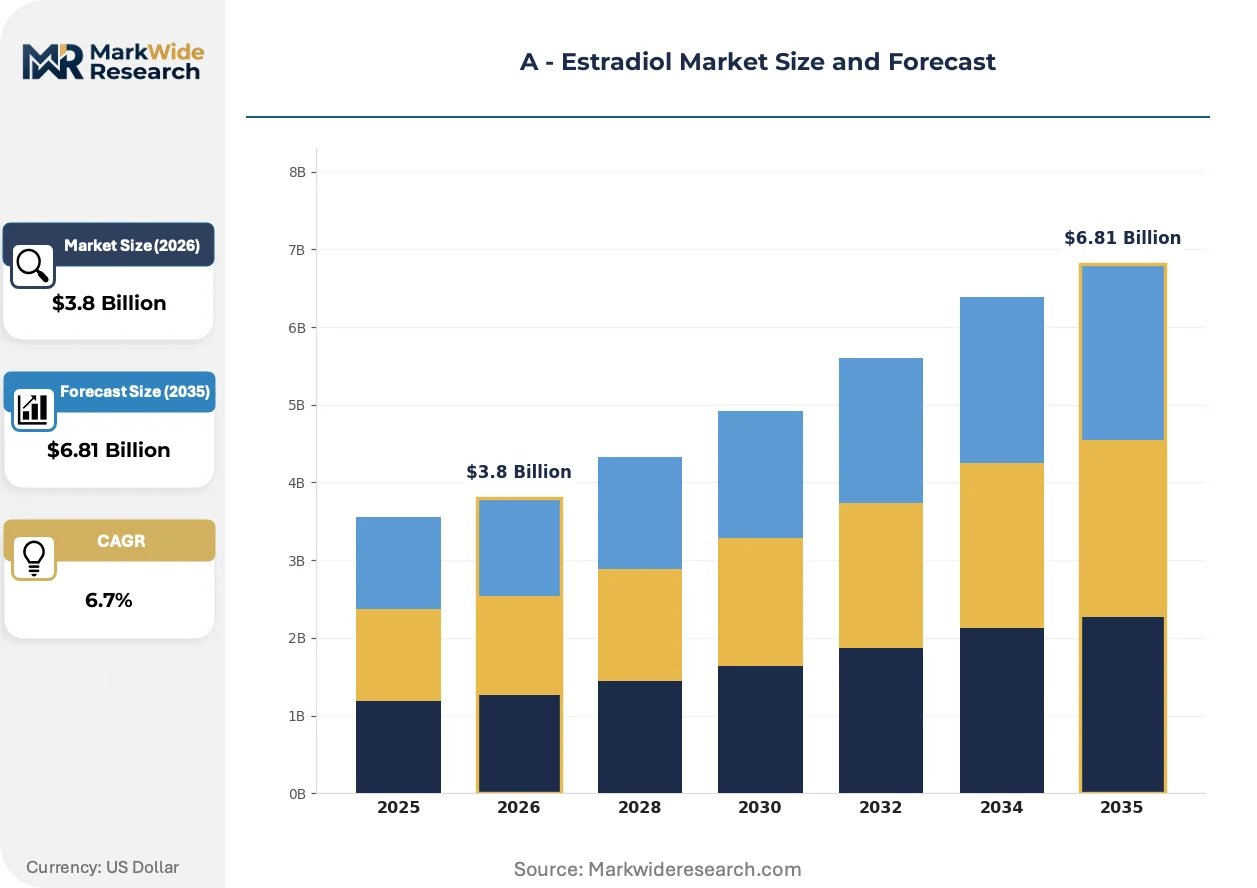
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Tablets, Transdermal Patches, Intravaginal Rings End User: Clinics, Hospitals, Pharmacies, Research Labs Therapy Area: Menopause, Hormone Replacement, Contraception, Hormonal Disorders Distribution Channel: Direct Sales, Online Pharmacies, Wholesalers, Retail Pharmacies |
| Companies Covered | Pfizer Inc., Bayer AG, AbbVie Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Novo Nordisk A/S, Viatris Inc., Merck KGaA, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A - Estradiol Market Evolving Landscape
Matrix-type transdermal patches with enhanced skin adhesion polymers are displacing reservoir designs as the dominant platform, while digital therapeutics integration is reshaping how adherence data flows back to prescribing clinicians.
Microneedle array patches for intradermal estradiol delivery are rendering obsolete conventional transdermal systems that rely on passive diffusion through stratum corneum barriers. Academic medical centers in the United States are piloting these devices for patients with adhesive sensitivities. The technology is compressing time-to-therapeutic onset while eliminating residue-related discontinuation.
EMA's revised guideline on quality of transdermal patches is mandating in vitro release testing standardization that harmonizes with FDA dissolution specifications. Generic manufacturers must now demonstrate equivalence across multiple batch scales before European market authorization. The patch segment is responding by consolidating analytical capabilities through contract research organization partnerships.
Specialty pharmacy direct-to-patient distribution is displacing traditional wholesaler-retail channel flows for reimbursed transdermal products. United States Medicare Part D plans are steering beneficiaries toward mail-order fulfillment with 90-day supply incentives. This channel shift is most pronounced in Florida and Arizona retirement corridors where clinic proximity constraints favor home delivery.
A - Estradiol Market Segmentation
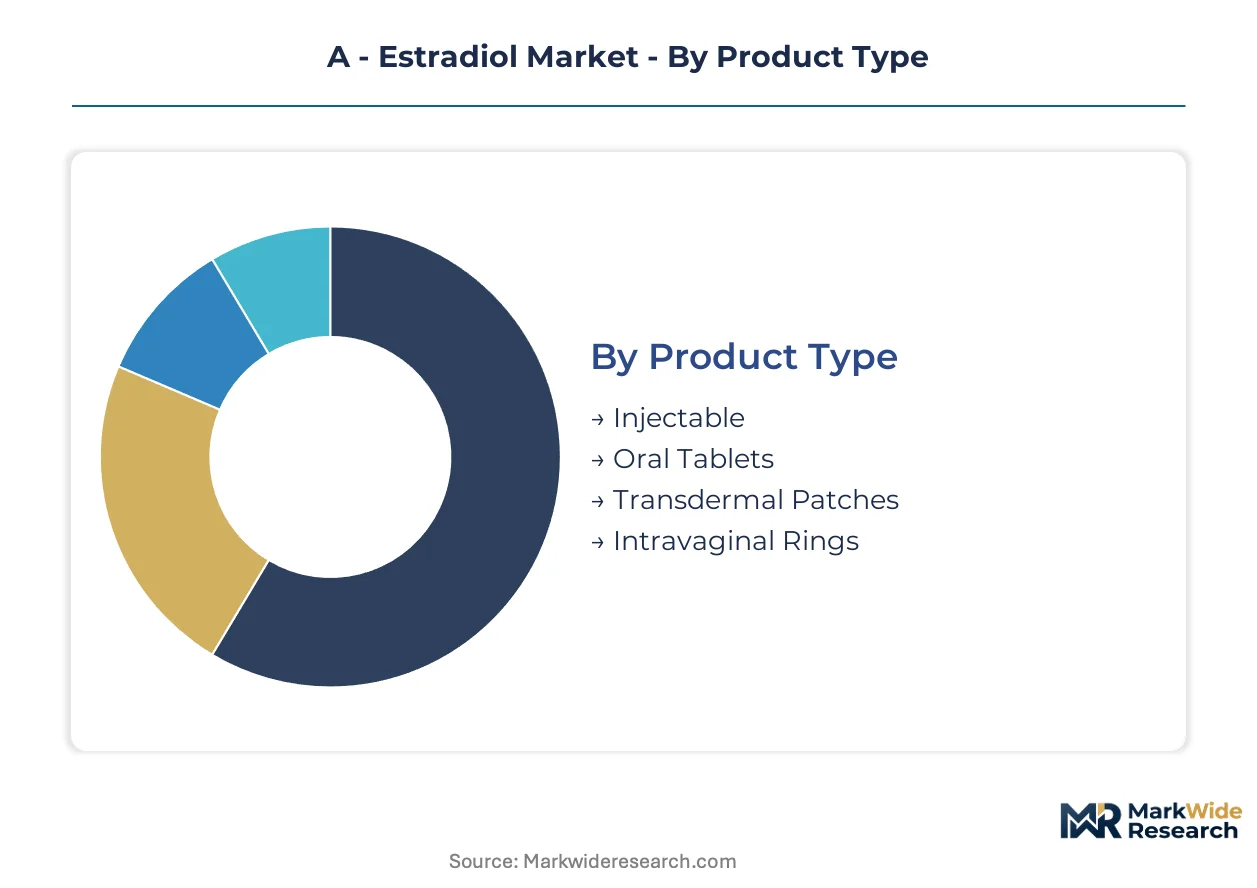
Estradiol formulation diversity creates distinct margin pools and regulatory pathways. Each segment carries unique manufacturing complexity, reimbursement dynamics, and patient compliance profiles that shape competitive positioning.
Product Type:
Mature oral formats coexist with emerging localized delivery systems that command premium positioning through reduced systemic exposure.
- Injectable:Parenteral formulations require compounding pharmacy protocols and cold chain integrity for oil-based suspensions. Demand concentrates in oncology adjuvant settings across United States academic medical centers where aromatase inhibition reversal requires precise dosing control.
- Transdermal Patches:Matrix-type designs with enhanced adhesion polymers now dominate over reservoir architectures. Germany's statutory health insurance expansion for extended-interval products is pulling volume toward patches that bypass hepatic first-pass metabolism.
- Oral Tablets:First-generation tablet formats remain the volume base despite margin compression from generic saturation.
- Intravaginal Rings:Localized delivery systems reduce systemic exposure while supporting quarterly dosing intervals.
Oral tablets handle the majority of throughput; transdermal patches are gaining share fastest through reimbursement tailwinds.
End User:
Customer concentration varies sharply by therapy urgency and prescription authority, with institutional buyers wielding formulary control.
- Clinics:Hormone replacement therapy clinics prioritize steady-state pharmacokinetics and direct-to-patient fulfillment models. United States specialty pharmacy networks now internalize refill logistics that manufacturers previously outsourced.
- Hospitals:Inpatient and outpatient settings anchor European tender markets where EMA biosimilar guidance shapes procurement criteria.
- Pharmacies:Retail and mail-order channels face margin pressure from 90-day supply incentives in Medicare Part D structures.
- Research Labs:Preclinical and clinical trial supply represents a specialized procurement segment with distinct quality documentation requirements.
Hospitals dominate European volume; clinics are expanding most quickly in United States value-based care contracts.
Therapy Area:
Indication breadth spans elective symptom management to oncological necessity, creating tiered pricing tolerance.
- Menopause:Vasomotor symptom management represents the largest addressable population. Digital therapeutics bundling with connected patch systems is opening subscription revenue streams in United States markets.
- Hormone Replacement:Hypoestrogenic restoration across surgical and natural menopause drives sustained demand for personalized dosing protocols.
- Contraception:Estradiol-progestin combinations require cold chain distribution that constrains pharmacy network expansion in warmer climates.
- Hormonal Disorders:Rare endocrine indications command premium pricing through orphan drug pathways.
Menopause commands the largest patient pool; hormone replacement shows the steepest expansion trajectory through survivor population growth.
Distribution Channel:
Channel structure is fragmenting as manufacturers capture lifetime value through direct patient relationships.
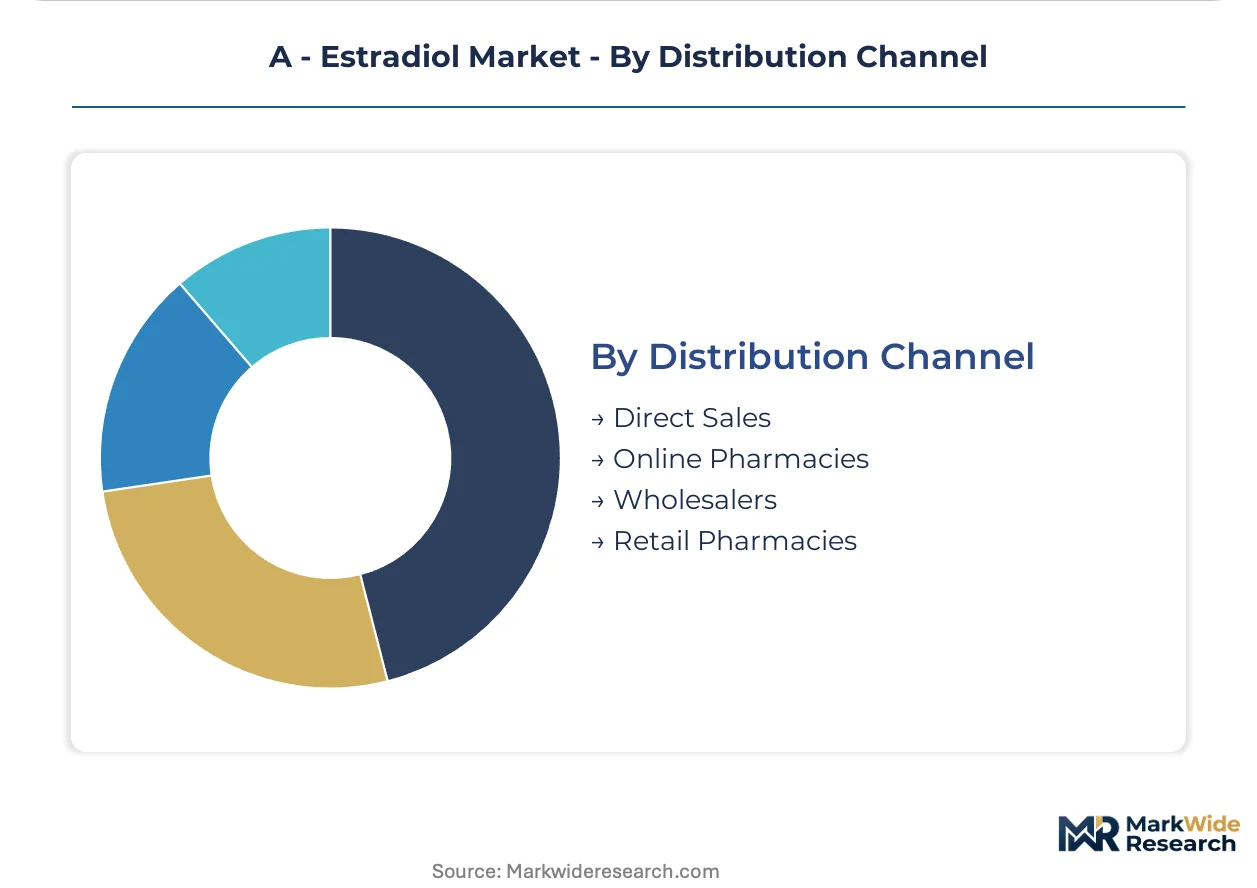
- Direct Sales:Manufacturer-controlled specialty pharmacy networks now handle reimbursed transdermal products in United States retirement corridors where clinic proximity constraints favor home delivery.
- Online Pharmacies:Digital fulfillment platforms are capturing cash-pay segments, particularly for compounded formulations.
- Wholesalers:European hospital formulary access remains controlled through Bayer AG's distribution partnerships.
- Retail Pharmacies:Traditional storefront channels face displacement as 90-day mail-order incentives reshape beneficiary behavior.
Wholesalers retain European institutional dominance; direct sales channels are climbing the fastest through Medicare Part D steering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States favors transdermal patches through Medicare Part D steering, while Germany concentrates volume in intravaginal rings via statutory reimbursement expansion. Japan maintains parenteral preference for oncology adjuvant protocols.
United States
Specialty pharmacy networks and hormone replacement therapy clinics drive patch adoption through 90-day mail-order incentives. FDA bioequivalence standards for generic transdermal products compress development timelines for matrix-technology entrants. Florida and Arizona retirement corridors concentrate demand where clinic proximity constraints favor home delivery models.
Germany
Hospital outpatient settings and statutory health insurance expansion pull volume toward extended-interval localized delivery systems. EMA quality standards for transdermal patches mandate in vitro release testing harmonization with FDA specifications. The Rhine-Ruhr industrial cluster anchors fermentation-based active pharmaceutical ingredient production for European supply.
Japan
Oncology adjuvant therapy programs and breast cancer survivor populations sustain demand for precise-dose parenteral formulations. PMDA guidance on complex hormone product biosimilars shapes post-patent substitution pathways. The Kanto region around Tokyo concentrates academic medical center procurement for aromatase inhibition reversal protocols.
China
Domestic generic manufacturers scale semi-synthetic estradiol production from phytosterol precursors amid agricultural commodity volatility. NMPA quality consistency evaluations for hormone products accelerate consolidation among fermentation-based synthesis operators. The Yangtze River Delta cluster houses active pharmaceutical ingredient facilities serving both domestic and export markets.
India
Contract research organizations and analytical service providers support bioanalytical method transfer for generic formulation submissions. CDSCO requirements for transdermal patch bioequivalence studies align with evolving FDA dissolution specifications. Hyderabad and Bangalore clusters specialize in clinical trial supply and reference standard production for multinational development programs.
A - Estradiol Market Competitive Landscape
Capability concentration sits with innovation-focused developers of advanced delivery systems; scale advantage sits with established pharmaceutical manufacturers with specialty pharmacy networks. The market structure tiers between multinational corporations with direct-to-patient distribution infrastructure and generic manufacturers competing on bioequivalence demonstration. Two strategic archetypes dominate: matrix-technology patch developers capturing reimbursement tailwinds, and biosimilar estradiol developers positioning for European hospital tender markets. Competitive moves center on specialty pharmacy network expansion and contract research organization partnerships for analytical capability consolidation.
Within the multinational tier, Pfizer Inc. and Bayer AG exemplify divergent channel strategies. Pfizer leverages United States specialty pharmacy networks to sustain direct-to-patient delivery models, while Bayer anchors European distribution through wholesaler partnerships controlling hospital formulary access. Novartis AG occupies a position on the biosimilar development vector, with its pipeline oriented toward post-patent substitution under EMA regulatory frameworks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| AbbVie Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Novo Nordisk A/S |
| Viatris Inc. |
| Merck KGaA |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese fermentation-based active pharmaceutical ingredient facilities is compressing contract manufacturing margins and forcing suppliers toward long-term offtake agreements with European and North American formulation developers. This utilization dynamic concentrates pricing power with buyers who can guarantee volume commitments across multi-year horizons.
Pricing Analysis
Long-term offtake contracts dominate estradiol active pharmaceutical ingredient procurement, with spot markets limited to distressed inventory or qualification batches. Pricing stratifies across premium, standard, and economy tiers based on FDA DMF filing status and EMA CEP certification level. Cost compression in oral tablet generics is intensifying because Brazilian soybean harvest volatility destabilizes phytosterol precursor costs. Hormone replacement therapy clinics exhibit lowest price sensitivity due to reimbursed access, while cash-pay compounded pharmacy segments face acute margin pressure.
Supply Chain Analysis
Export control regimes for dual-use fermentation technology limit equipment flows to Indian and Chinese active pharmaceutical ingredient facilities, constraining capacity expansion timelines. Supply concentrates in China, India, and Germany for fermentation-based synthesis; Brazil and Argentina for soy-derived phytosterol precursors. Raw material dependencies include cholesterol substrates, aromatase enzymes, and specialized fermentation media. Single-source vulnerability persists for high-purity estradiol reference standards. Distribution runs through specialty pharmacy networks in the United States and wholesaler partnerships in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The A - Estradiol market represents early-cycle expansion driven by menopausal population growth and reimbursement expansion for localized delivery systems. Transdermal patch adoption in United States value-based care contracts provides the foundational tailwind.
For Market Incumbents: Build regulatory data exclusivity moats through FDA bioequivalence studies on novel matrix-technology patches. Defend against biosimilar substitution by securing hospital formulary lock-in via 90-day mail-order contracts. Capacity addition in the Rhine-Ruhr cluster anchors European supply security against phytosterol input volatility. For New Entrants and Emerging Players: Mid-market hormone replacement therapy clinics in the United States retirement corridors represent the most penetrable entry point, as these buyers prioritize steady-state pharmacokinetics over established brand relationships. Digital therapeutics bundling with connected patch systems offers a differentiated go-to-market angle against commoditized oral tablet competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialty pharmacy network control determines lifetime prescription value capture in reimbursed segments. Target acquisition archetypes include contract research organizations with validated estradiol metabolite assay capabilities. Monitor EMA biosimilar guidance finalization as the inflection signal for European hospital tender market entry.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Bioequivalence Pathway Advancement | Matrix-technology patch developers secure generic substitution barriers through pharmacokinetic study investments. |
| Specialty Pharmacy Network Expansion | Direct-to-patient distribution captures refill logistics revenue previously outsourced to third parties. |
| EMA Biosimilar Development Positioning | Follow-on developers target European hospital tender markets under clarified regulatory frameworks. |
| Long-Acting Injectable Depot Pipeline | Polymeric microsphere technologies address compliance gaps in rural and aging patient populations. |
| Digital Therapeutics Platform Integration | Connected patch systems open subscription revenue streams in United States value-based care contracts. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing provide triangulation checks across the analysis window.
Calibration against historical approval timelines and reimbursement adoption curves shapes the analytical framework. Segmentation dimensions include formulation type, therapy area, end-user setting, and regional regulatory cluster. CAGRs derive from patient population projections, pricing trajectory assumptions, and volume share shift modeling across oral, transdermal, and intravaginal delivery systems.
Practitioners should monitor FDA bioequivalence guideline revisions, EMA quality standard updates, and Brazilian agricultural commodity indices for early signals. Forecasts reflect assumptions on reimbursement policy stability and fermentation capacity expansion timelines. Material shifts in statutory health insurance coverage criteria or phytosterol precursor supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Purified Protein Derivative Market