
 Echinocandins Market | 2026-2036
Echinocandins Market Size, Share, and Industry Trends Forecast 2026-2036
Echinocandins Market Foresight
EU MDR and FDA antimicrobial stewardship mandates are pivoting hospital procurement toward guideline-concordant antifungal therapy. Merck sustains manufacturing scale across intravenous echinocandin portfolios, while Pfizer leverages hospital formulary relationships to anchor distribution in acute care networks. Fresenius Kabi competes through generic injectable specialization, occupying a cost-sensitive tier that appeals to group purchasing organizations.
Echinocandins are semisynthetic lipopeptide antifungal agents that inhibit beta-1,3-D-glucan synthase in the fungal cell wall, manufactured through fermentation-derived precursor modification followed by semisynthetic acylation to optimize pharmacokinetic profiles. Caspofungin leads hospital consumption as the established first-line agent for invasive aspergillosis salvage therapy, while micafungin commands premium positioning in neonatal candidiasis protocols where its safety database differentiates clinical choice. The injection formulation dominates acute care delivery, though powder presentations for reconstitution concentrate margin pools in institutional settings where pharmacy compounding controls costs.
FDA, EMA, and WHO antifungal resistance surveillance frameworks shape demand by mandating susceptibility testing documentation and restricting empiric broad-spectrum azole use. These standards compel manufacturers to maintain robust pharmacovigilance systems and real-world evidence programs. Stakeholders must monitor glucan synthase mutation surveillance data and health technology assessment evolution to anticipate shifts in first-line therapy designation.
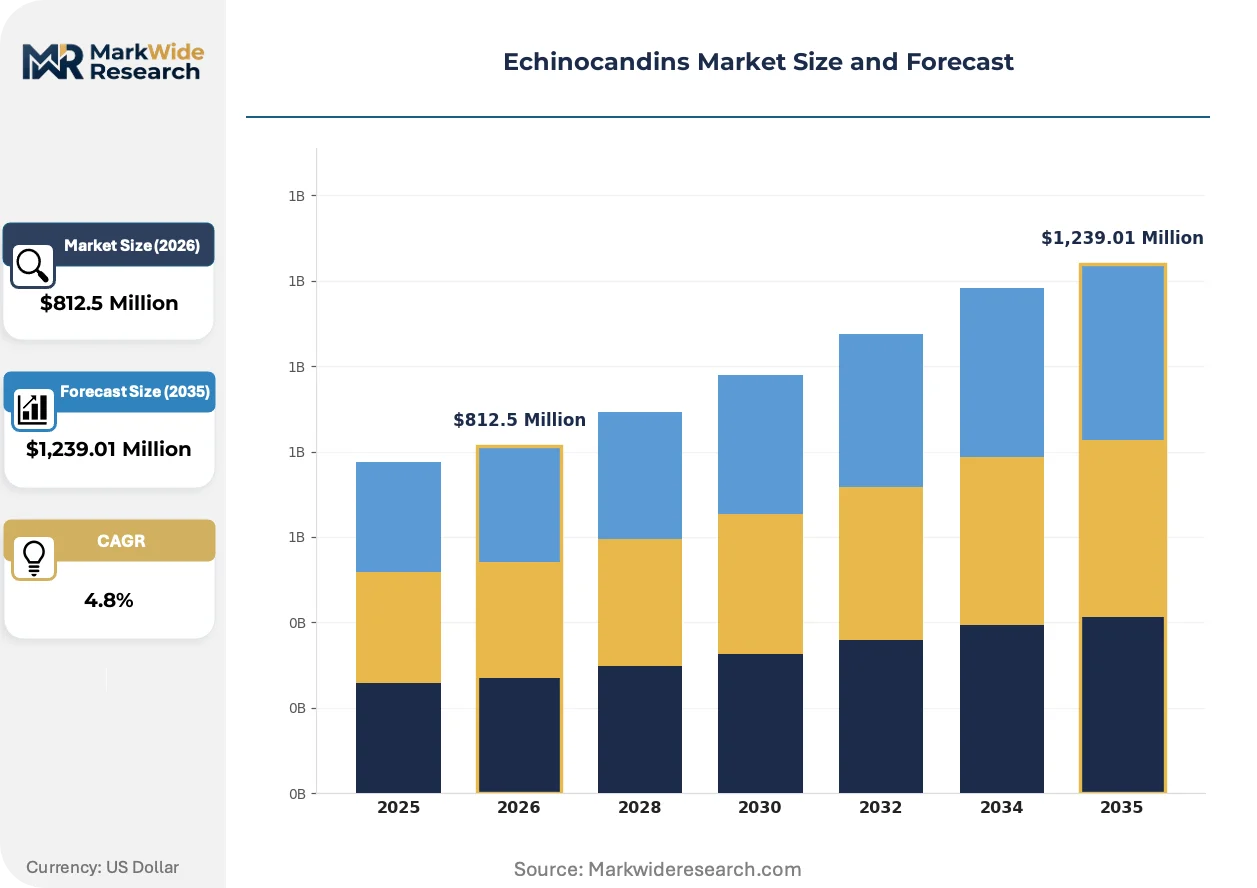
Market Dynamics
Antimicrobial stewardship mandates from FDA and EMA are compressing empiric azole prescribing and elevating echinocandin protocols in ICU bloodstream infection management, restructuring hospital formulary hierarchies and procurement criteria across acute care networks.
Growth Catalysts
- FDA Antifungal Resistance Surveillance Framework:Mandatory susceptibility testing documentation drives guideline-concordant echinocandin first-line adoption in US hospital systems.
- Neonatal ICU candidiasis protocols:Specialized safety databases for micafungin expand prophylactic use in premature infant populations across tertiary care centers.
- Fermentation-derived manufacturing:Semisynthetic lipopeptide production methods yield scalable supply chains for intravenous formulations.
Market Restraints
- Input cost volatility:Fermentation precursor availability fluctuates with agricultural commodity markets, squeezing margin pools on powder-for-reconstitution presentations.
- Supply concentration risk:Active pharmaceutical ingredient synthesis clusters in limited fermentation facility networks, creating geographic vulnerability to manufacturing disruptions.
- Substitution threat from isavuconazole:Azole class advancement in invasive aspergillosis first-line therapy challenges echinocandin salvage positioning.
Strategic Opportunities
- Outpatient infusion center expansion:Step-down candidiasis therapy protocols create channel migration from inpatient to ambulatory settings.
- WHO Essential Medicines List inclusion momentum:Global health framework prioritization opens procurement pathways for low-resource hospital systems.
- Pharmacokinetic modeling convergence:Therapeutic drug monitoring integration with beta-1,3-D-glucan biomarker testing enables precision dosing protocols.
Industry Challenges
- Specialized fermentation workforce scarcity:Lipopeptide semisynthesis expertise concentrates in legacy antibiotic manufacturing regions, constraining capacity expansion timelines.
- Pharmacovigilance system capex intensity:Real-world evidence infrastructure requirements for resistance surveillance compliance demand sustained IT and clinical data investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Echinocandins Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,239.01 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anidulafungin, Caspofungin, Micafungin, Rezafungin End User: Hospitals, Clinics, Long-term Care Facilities, Research Institutions Formulation: Injection, Oral, Powder, Solution Sales Channel: Direct Sales, Distributors, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Xellia Pharmaceuticals, Hikma Pharmaceuticals, Merck, Fresenius Kabi, Apotex, Astellas, Teva Pharmaceutical Industries, Pfizer, Endo International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Echinocandins Market Shifts & Advancements
Hospital procurement criteria are pivoting toward resistance surveillance alignment, compressing legacy empiric prescribing patterns and elevating pharmacoeconomic validation for antifungal stewardship investments.
Continuous manufacturing technology is integrating into echinocandin powder production lines, enabling real-time quality release and reduced batch cycle times. Contract development and manufacturing organizations serving generic injectable portfolios are adopting these platforms to meet group purchasing organization cost targets. This integration is compressing traditional batch validation timelines and enabling just-in-time inventory models for hospital pharmacy compounding operations.
EU MDR pharmacovigilance requirements are mandating post-market surveillance studies for systemic antifungals, compelling manufacturers to maintain active safety databases beyond initial registration. The regulation forces alignment between clinical trial endpoints and real-world evidence collection infrastructure. Hospital formulary committees in Germany and France are now requiring documented resistance surveillance compliance as a procurement precondition.
Group purchasing organization consolidation is compressing supplier tiers and unbundling traditional distributor service packages. Acute care networks in the United States are negotiating direct manufacturer contracts for high-volume echinocandin SKUs, bypassing wholesale intermediaries. This channel restructuring is most visible in multi-hospital systems with centralized pharmacy and therapeutics committees.
Echinocandins Market Segmentation
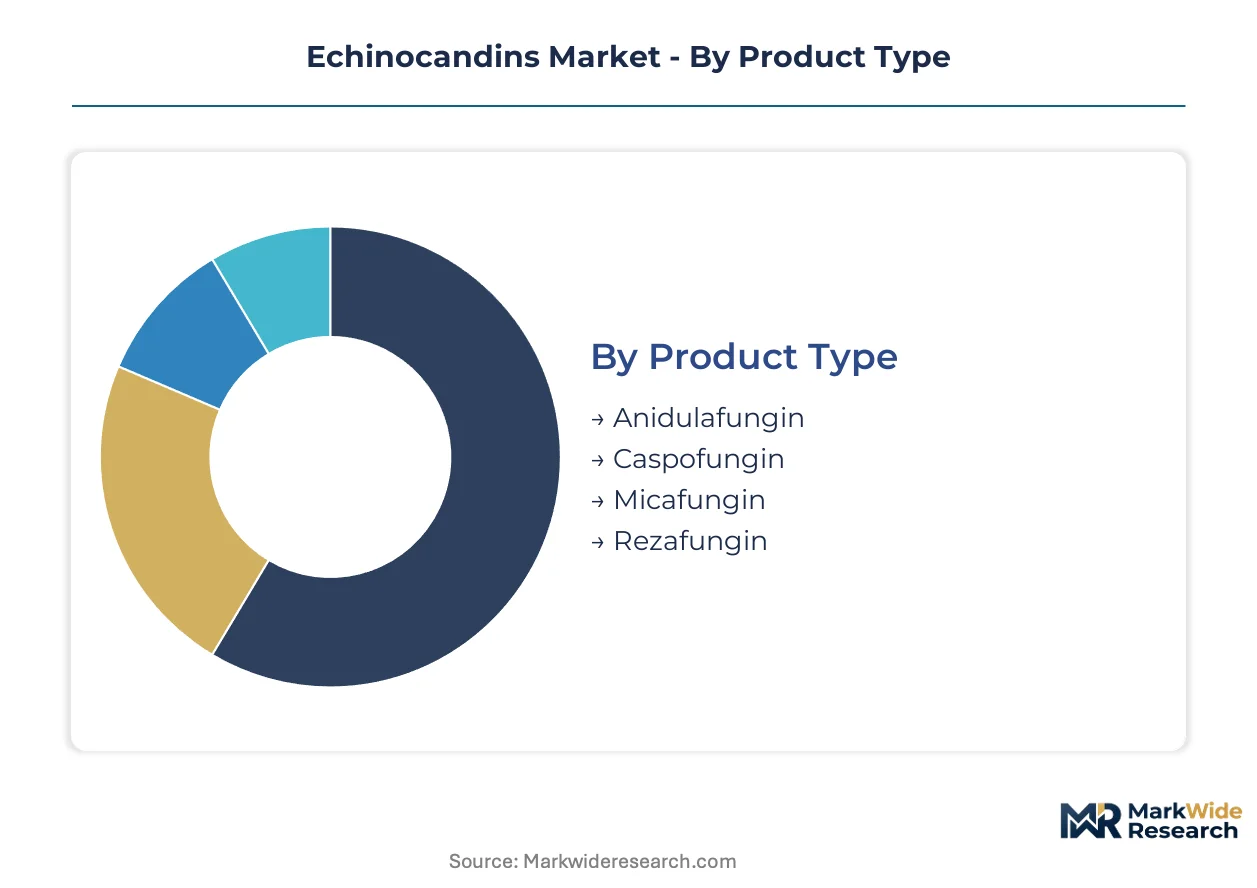
Echinocandin market segmentation reveals distinct procurement hierarchies across acute care networks. Product differentiation, end-user concentration, and channel restructuring each reshape competitive positioning within antimicrobial stewardship frameworks.
Product Type:
Volume consumption clusters in established intravenous agents with decades of safety documentation, while premium positioning concentrates in newer entrants with differentiated pharmacokinetic profiles.
- Caspofungin:Fermentation-derived semisynthetic lipopeptide with established first-line designation in invasive aspergillosis salvage protocols. Hospital formularies in the United States anchor procurement volumes here due to extensive ICU safety databases and therapeutic drug monitoring integration.
- Micafungin:Echinocandin with specialized neonatal candidiasis labeling and prophylactic use authorization in premature infant populations. Tertiary care centers prioritize this agent where narrow therapeutic indices demand precise pharmacokinetic control.
- Anidulafungin:Once-daily dosing regimen simplifies pharmacy compounding workflows in high-throughput infusion centers.
- Rezafungin:Weekly dosing interval targets outpatient step-down therapy and ambulatory infusion center expansion.
Mature deployment sits with Caspofungin. Newer deployment is concentrated in Rezafungin.
End User:
Procurement authority concentrates in centralized pharmacy and therapeutics committees, with cost-tier differentiation separating acute care networks from ambulatory and research settings.
- Hospitals:Acute care networks with antimicrobial stewardship mandates drive bulk purchasing through group purchasing organization contracts. ICU bloodstream infection protocols in the United States prioritize echinocandin first-line therapy, concentrating demand in tertiary and quaternary centers with dedicated infectious disease pharmacy specialists.
- Clinics:Outpatient infusion centers and specialty infectious disease practices manage step-down candidiasis therapy. Expansion of ambulatory parenteral antimicrobial therapy programs creates channel migration from inpatient to community-based administration.
- Long-term Care Facilities:Skilled nursing facilities with on-site infusion capabilities represent emerging demand for extended-duration antifungal regimens.
- Research Institutions:Academic medical centers with clinical trial infrastructure support pharmacokinetic modeling and resistance surveillance studies mandated by FDA and EMA frameworks.
Procurement volume clusters in Hospitals. Margin expansion concentrates in Research Institutions.
Formulation:
Supply concentration in sterile injectable manufacturing shapes availability across presentation types, with powder-for-reconstitution dominating institutional cost-control strategies.
- Injection:Ready-to-use liquid formulations command premium positioning in emergency department and ICU settings where compounding time constraints limit pharmacy flexibility. Fresenius Kabi and generic injectable specialists compete on unit cost within this presentation tier.
- Powder:Lyophilized presentations for reconstitution concentrate margin pools in institutional settings where pharmacy compounding controls per-dose costs. Hospital systems with centralized sterile compounding facilities prefer this format for bulk procurement and inventory management.
- Oral:Limited bioavailability restricts echinocandin oral development; azole class agents dominate oral antifungal therapy.
- Solution:Diluted presentations for extended infusion protocols support therapeutic drug monitoring integration in specialized centers.
Cost-sensitive procurement favors Powder. Time-critical deployment concentrates in Injection.
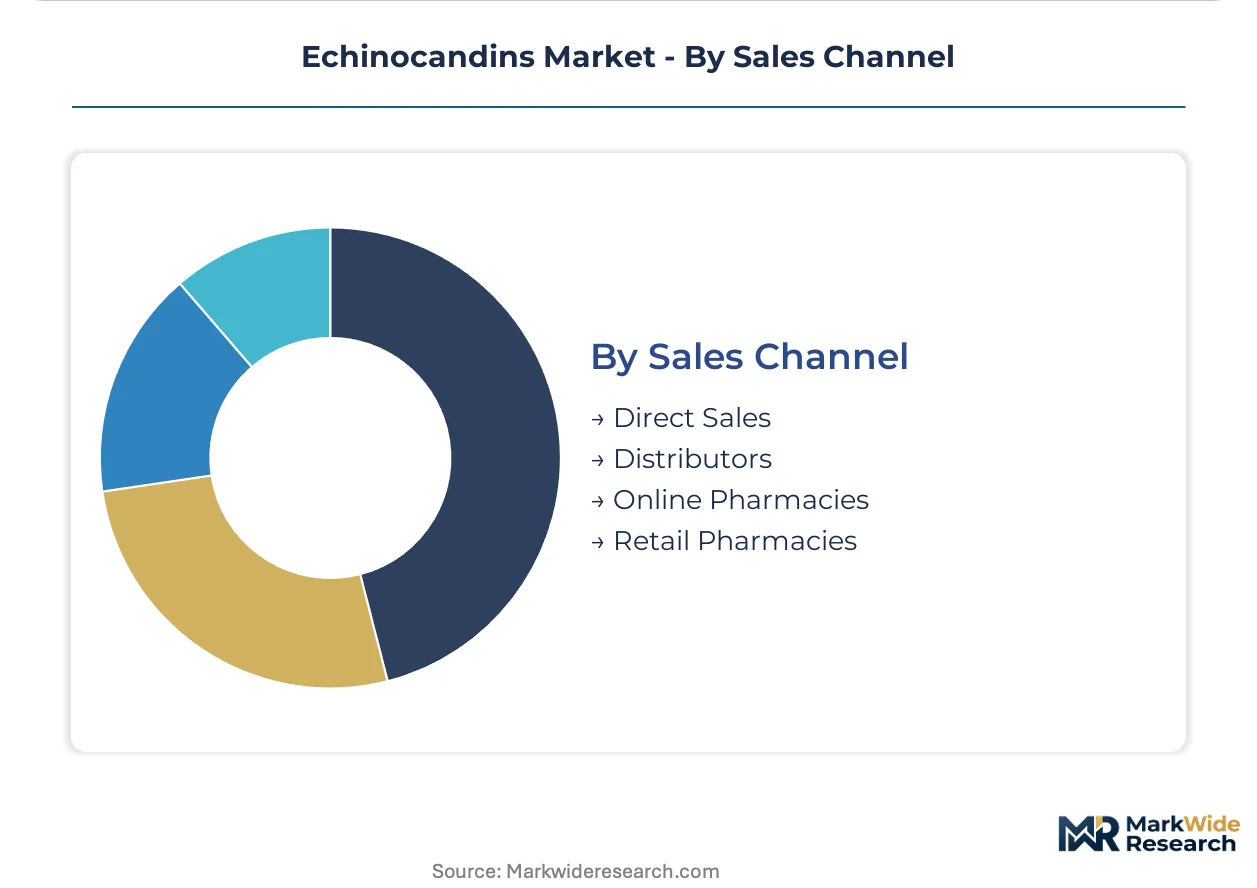
Sales Channel:
Channel restructuring separates direct manufacturer relationships from traditional wholesale intermediaries, with digital procurement platforms emerging in select segments.
- Direct Sales:Multi-hospital systems with centralized pharmacy committees negotiate manufacturer contracts bypassing wholesale intermediaries. Merck and Pfizer leverage hospital formulary relationships to anchor distribution in acute care networks through dedicated account management.
- Distributors:Traditional wholesale networks maintain relevance in smaller hospital systems and regional acute care clusters without centralized procurement authority.
- Online Pharmacies:Digital procurement platforms serve outpatient infusion centers and long-term care facilities with established electronic prescribing workflows.
- Retail Pharmacies:Limited role given parenteral administration requirements; primarily supports oral antifungal adjunct therapy and discharge prescription coordination.
Volume concentration sits with Direct Sales. Digital migration is expanding fastest in Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors echinocandin consumption through its dense concentration of tertiary medical centers with specialized infectious disease units and antimicrobial stewardship programs that drive protocol-driven prescribing.
United States
ICU bloodstream infection protocols and FDA antifungal resistance surveillance mandates concentrate demand in tertiary care networks. The Centers for Medicare & Medicaid Services tie reimbursement to stewardship compliance, accelerating formulary standardization. The Research Triangle Park corridor in North Carolina hosts clinical trial infrastructure supporting pharmacokinetic modeling for neonatal candidiasis protocols.
Germany
Hospital procurement centralization through regional purchasing alliances elevates guideline-concordant therapy adoption. EU MDR pharmacovigilance requirements mandate post-market surveillance studies that reshape manufacturer-hospital relationships. The Rhine-Main cluster around Frankfurt anchors distribution logistics for sterile injectable supply chains serving Central European acute care networks.
Japan
PMDA guidance on antifungal susceptibility testing documentation drives diagnostic-therapeutic integration in university hospitals. The national health insurance price listing system creates predictable reimbursement pathways for established echinocandin agents. The Kansai region around Osaka concentrates generic injectable manufacturing capacity serving domestic hospital procurement.
India
CDSCO regulatory pathways for complex injectable generics expand domestic manufacturing participation in hospital procurement. The country's national pharmaceutical pricing authority caps ceiling prices for essential medicines, compressing margin pools on established agents. The Hyderabad-Visakhapatnam pharmaceutical corridor hosts fermentation-derived API synthesis facilities supplying regional acute care networks.
Brazil
ANVISA antimicrobial stewardship guidelines for hospital accreditation create compliance-driven demand for documented susceptibility testing. The unified health system procurement framework concentrates volume in public hospital networks with centralized pharmacy committees. The São Paulo metropolitan region anchors private hospital consumption where insurance-reimbursed ICU therapy protocols prioritize first-line echinocandin use.
Echinocandins Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established hospital formulary relationships. Tiered positioning separates originator manufacturers with proprietary fermentation platforms from generic injectable specialists competing on unit cost and supply reliability. Three archetypes dominate: integrated Big Pharma with stewardship program partnerships, mid-scale generic houses with CDMO relationships, and fermentation-focused API suppliers with backward integration into sterile manufacturing. Consolidation pressure and capacity expansion in lipopeptide semisynthesis represent the dominant competitive vectors.
Among integrated pharmaceutical conglomerates, Merck and Pfizer exemplify archetypes with hospital formulary anchoring strategies, while Fresenius Kabi occupies a position within the generic injectable specialist tier. These three entities represent contrasting approaches to antimicrobial stewardship program engagement and supply chain configuration for intravenous antifungal delivery.
| Leading Market Players |
|---|
| Xellia Pharmaceuticals |
| Hikma Pharmaceuticals |
| Merck |
| Fresenius Kabi |
| Apotex |
| Astellas |
| Teva Pharmaceutical Industries |
| Pfizer |
| Endo International |
| Others |
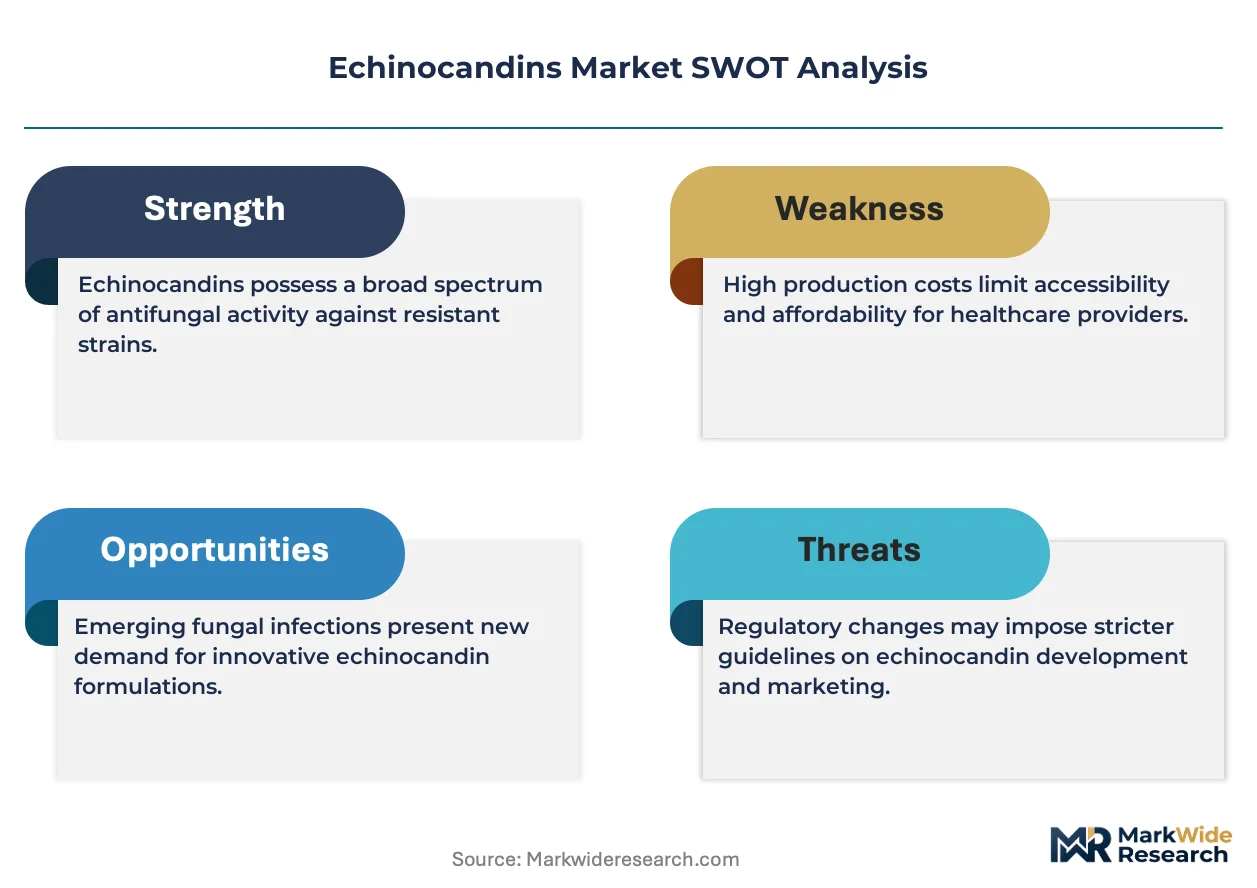
Supply & Pricing Matrix
EMA pharmacovigilance mandates for systemic antifungals gate qualified supply by compelling manufacturers to maintain active safety databases beyond initial registration, simultaneously restricting premium-tier pricing access to those with documented resistance surveillance compliance and real-world evidence infrastructure.
Pricing Analysis
Value-based pricing anchors on therapeutic drug monitoring integration and neonatal safety database differentiation, with micafungin commanding premium positioning in premature infant protocols where narrow therapeutic indices justify outcome-linked contracts. Three-tier pricing structure across originator, authorized generic, and commodity injectable levels separates Merck and Pfizer formulary relationships from Fresenius Kabi cost-tier competition. Pricing pressure stems from group purchasing organization consolidation unbundling traditional distributor service packages and compressing unit costs on powder-for-reconstitution presentations. Research institutions exhibit lowest price sensitivity due to grant-funded procurement, while long-term care facilities with emerging infusion capabilities represent the most price-constrained buyer archetype.
Supply Chain Analysis
Single-source vulnerability sits with fermentation-derived precursor availability clustering in legacy antibiotic manufacturing regions of the United States, Germany, and India, where specialized lipopeptide semisynthesis expertise constrains capacity expansion timelines. Active pharmaceutical ingredient synthesis draws from agricultural commodity markets for fermentation feedstocks, semisynthetic acylation reagents, and sterile injectable packaging components. Supply chain risk centers on geographic concentration of fermentation facility networks exposed to regulatory inspection backlogs and workforce scarcity. Distribution runs through direct manufacturer contracts with multi-hospital systems bypassing wholesale intermediaries, alongside traditional distributor networks serving regional acute care clusters without centralized procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The echinocandins market functions as a vertical-integration race where backward integration into fermentation-derived API synthesis and captive sterile manufacturing capacity determines supply security and margin defense against generic injectable specialists.
For Market Incumbents: Deepen proprietary fermentation platform investments to secure lipopeptide precursor supply against agricultural commodity volatility, while expanding real-world evidence infrastructure to maintain EMA and FDA pharmacovigilance compliance as a formulary gate. Anchor hospital relationships through antimicrobial stewardship program partnerships that resist group purchasing organization tier compression. For New Entrants and Emerging Players: Outpatient infusion centers with step-down candidiasis protocols represent the most penetrable buyer archetype, as channel migration from inpatient to ambulatory settings outpaces established manufacturer coverage models. Target long-term care facilities with on-site infusion capabilities through digital procurement platforms, leveraging electronic prescribing workflow integration as the primary go-to-market angle. For Investors and Strategic Acquirers: CDSCO regulatory pathway acceleration for complex injectable generics is the leading indicator that Indian fermentation-to-finished-dose vertically integrated assets will command scarcity premiums. Position acquisitions around mid-scale generic houses with backward integration into API synthesis and sterile manufacturing, monitoring WHO Essential Medicines List inclusion momentum as the signal for low-resource hospital system procurement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation API Synthesis | Captive lipopeptide precursor supply insulates margin pools from agricultural commodity volatility. |
| Real-World Evidence Infrastructure Investment | Active safety databases satisfy EMA pharmacovigilance mandates for formulary access retention. |
| Outpatient Infusion Center Channel Development | Step-down candidiasis protocols enable margin expansion beyond inpatient commoditization. |
| Antimicrobial Stewardship Program Partnership | Hospital formulary anchoring resists group purchasing organization tier compression. |
| CDSCO Regulatory Pathway Navigation | Complex injectable generic approval unlocks Indian domestic manufacturing participation. |
Research Methodology
Document review covered FDA antifungal resistance surveillance frameworks, EMA pharmacovigilance guidance, and hospital formulary databases, complemented by interviews with infectious disease pharmacy specialists, group purchasing organization contract managers, sterile compounding facility directors, and fermentation manufacturing engineers. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement data, and EU MDR post-market surveillance study registries. Bottom-up demand modeling across acute care networks triangulated against top-down pharmaceutical procurement expenditure estimates.
Market size outputs reflect segment-level modeling across product type, end user concentration, formulation presentation, and sales channel structure, with CAGRs derived from protocol adoption curve analysis and antimicrobial stewardship mandate implementation timelines. Projection inputs incorporated therapeutic drug monitoring integration rates, neonatal ICU candidiasis protocol expansion, and resistance surveillance compliance cost trajectories throughout the forecast period.
Revisions become necessary when glucan synthase mutation surveillance data shifts first-line therapy designation, fermentation facility regulatory actions disrupt API supply, or health technology assessment evolution redirects hospital procurement criteria. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Global Human Recombinant Insulin Market