
 Global Levofloxacin Market | 2026-2036
Global Levofloxacin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Levofloxacin Market Analysis
India's active pharmaceutical ingredient capacity expansion is reshaping supply economics for generic fluoroquinolone manufacturers. Dr. Reddy's Laboratories leverages backward integration into key starting materials to protect margin structures against input volatility. Lupin Limited anchors its position through sustained hospital formulary penetration across North American and European markets. Sun Pharmaceutical Industries Ltd. competes on manufacturing scale, operating multi-ton API facilities that supply both captive formulations and external customers.
Levofloxacin is a synthetic fluoroquinolone antibiotic with a molecular formula of C18H20FN3O4, functioning as the pure S-enantiomer of ofloxacin and exhibiting broad-spectrum bactericidal activity through DNA gyrase and topoisomerase IV inhibition. The compound serves primarily as a second-line or combination therapy for respiratory, urinary, and soft-tissue infections where first-line agents prove inadequate. Injectable formulations command premium positioning in hospital settings due to their critical role in sepsis and severe pneumonia protocols, while tablet demand from retail pharmacies faces pressure from stewardship restrictions. Respiratory infection applications retain the largest volume share, though urinary tract infection use is contracting in markets where local resistance thresholds trigger automatic formulary restrictions.
FDA safety communications and EMA PRAC recommendations on fluoroquinolone adverse effects have tightened prescribing controls across outpatient settings, redirecting volume toward supervised hospital administration. India's CDSCO and China's NMPA maintain divergent bioequivalence standards for generic levofloxacin approvals, creating asymmetric market access conditions for multinational filings. WHO Essential Medicines List inclusion sustains procurement eligibility for developing-market health systems, though Watch Group classification signals stewardship obligations. Stakeholders must monitor how national essential medicine committees reconcile access mandates with antimicrobial resistance containment targets.
Market Dynamics
Antimicrobial stewardship mandates from FDA and EMA are compressing outpatient prescribing volumes while hospital procurement protocols tighten formulary access, redirecting demand toward supervised injectable administration.
Growth Catalysts
- Hospital Sepsis Protocols:Injectable levofloxacin retains critical placement in ICU bundles for severe pneumonia and bloodstream infections across tertiary care centers in India and the United States.
- CDSCO Streamlined Approvals:India's bioequivalence pathway for generic fluoroquinolones accelerates manufacturer entry and expands affordable supply for public health programs.
- API Capacity Concentration:Dr. Reddy's Laboratories and Lupin Limited anchor backward integration into key starting materials, insulating formulation output from intermediate price volatility.
Market Restraints
- Fluoroquinolone Safety Labeling:FDA's boxed warning updates for tendon rupture and peripheral neuropathy trigger automatic prior authorization requirements in US outpatient settings.
- Resistance Threshold Triggers:Local antibiogram data in European markets automatically restricts urinary tract infection indications once Escherichia coli susceptibility falls below institutional thresholds.
- Starting Material Concentration:China's Zhejiang and Jiangsu provinces control over 60 percent of global levofloxacin API output, creating single-source vulnerability for downstream formulators.
Strategic Opportunities
- Centralized Hospital Procurement in China:NMPA volume-based purchasing creates tender access for manufacturers meeting domestic bioequivalence standards at scale.
- Combination Therapy Formulations:Co-formulation with beta-lactamase inhibitors addresses emerging resistance in respiratory pathogens and differentiates hospital offerings.
- WHO Prequalification Pathway:Essential Medicines List Watch Group classification sustains developing-market procurement eligibility for suppliers meeting international quality benchmarks.
Industry Challenges
- Stewardship Compliance Talent:Hospital pharmacy departments require specialized antimicrobial pharmacists to navigate formulary restrictions and dosing optimization protocols.
- Multi-Site Bioequivalence Studies:Divergent CDSCO, NMPA, and FDA requirements for generic approvals extend clinical trial timelines and registration costs for multinational filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Levofloxacin Market |
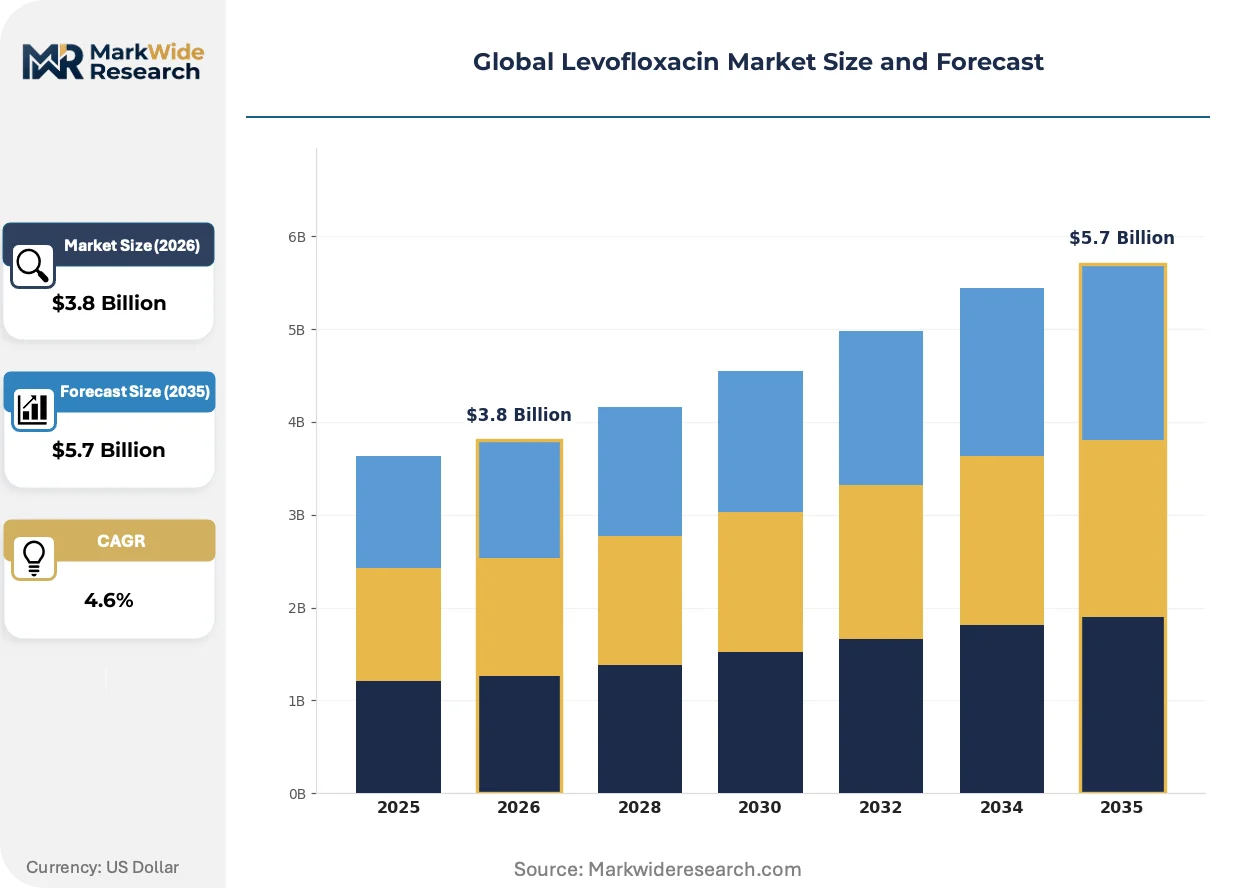
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectables, Oral Solution, Eye Drops Application: Respiratory Infections, Urinary Tract Infections, Skin Infections, Bone Infections End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Dr. Reddy's Laboratories Limited, Lupin Limited, Glenmark Pharmaceuticals Limited, MacLeods Pharmaceuticals Ltd., Sun Pharmaceutical Industries Ltd., Cipla Limited, Zydus Lifesciences Limited, Aurobindo Pharma Ltd., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Levofloxacin Market Emerging Trajectories
Formulation technology and regulatory science are converging to reshape competitive positioning, with manufacturing scale and quality certification becoming primary differentiators in procurement decisions.
Continuous manufacturing platforms for oral solid dosage forms are migrating from batch processing toward real-time release testing. Dr. Reddy's Laboratories and Sun Pharmaceutical Industries deploy these systems to compress cycle times and reduce in-process inventory. Hospital buyers in North America and Europe increasingly specify ICH Q12-compliant manufacturing in tender evaluations, favoring suppliers with demonstrated process analytical technology integration.
EMA's PRAC recommendations on fluoroquinolone adverse effects have triggered systematic prescription audits across EU member states. Outpatient clinicians face mandatory documentation of first-line agent failure before levofloxacin dispensing. French and German hospital formularies have responded by concentrating respiratory infection use within supervised infusion centers, compressing retail pharmacy volume.
China's National Healthcare Security Administration bundles injectable antibiotics into diagnosis-related group payment categories. Hospital pharmacy committees negotiate annual volume commitments with manufacturers, replacing transactional purchasing with multi-year supply agreements. This concentration of procurement authority favors domestic API-integrated formulators with NMPA green channel certification.
Global Levofloxacin Market Segmentation
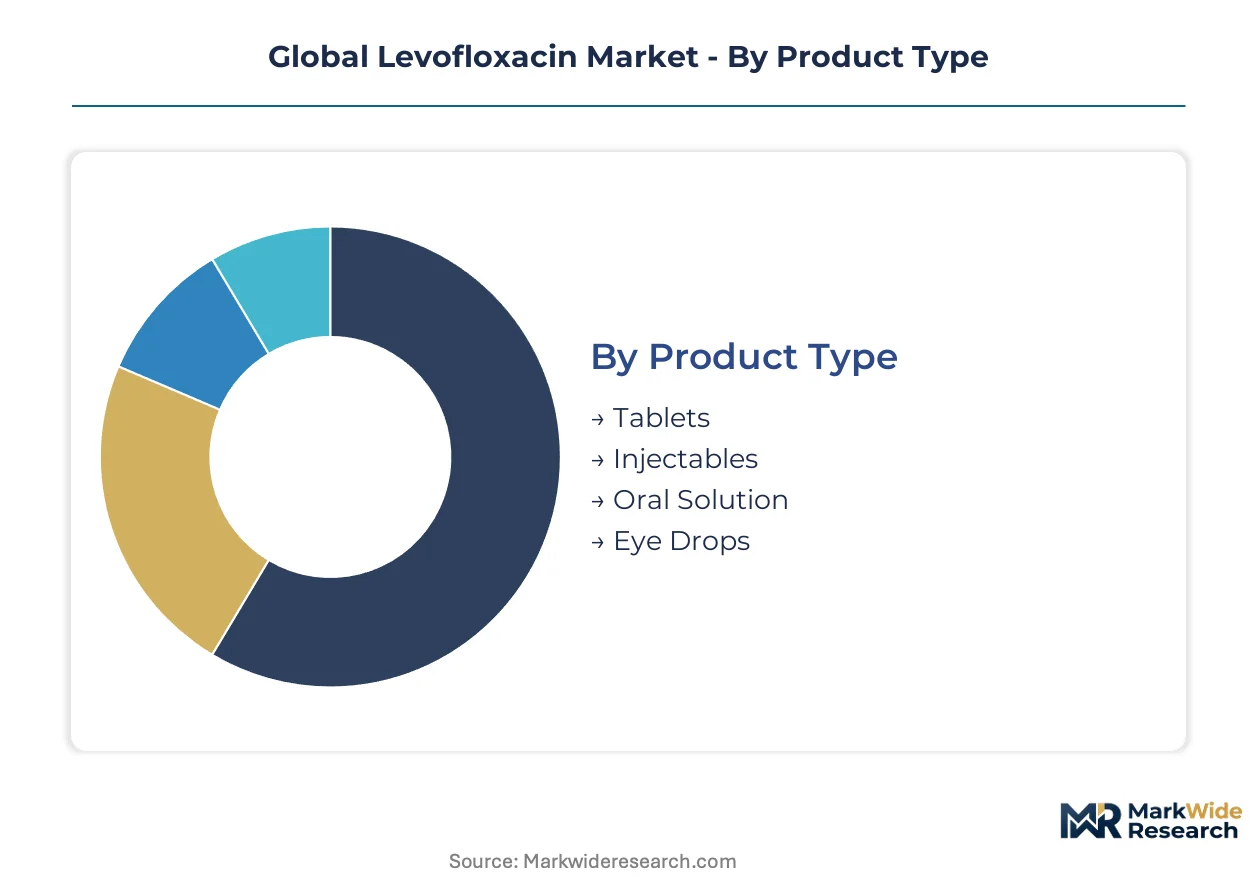
Levofloxacin demand fragments across administration routes, infection sites, and procurement channels with uneven intensity. Hospital injectables concentrate value while retail tablets face stewardship compression. Understanding segment-specific regulatory exposure and channel economics separates viable positions from stranded inventory.
Product Type:
Cost tier differentiation separates premium sterile manufacturing from commoditized oral solids, with bioequivalence standards and cold-chain requirements determining margin architecture.
- Injectables:Sterile aqueous solutions for intravenous or intramuscular administration require aseptic filling and endotoxin control per FDA and EMA GMP annexes. Demand concentrates in Indian and US hospital ICUs where sepsis protocols mandate rapid bactericidal plasma levels. Injectable formulations command procurement premiums due to manufacturing complexity and critical-care placement.
- Tablets:Film-coated oral solid dosage forms containing 250mg, 500mg, or 750mg levofloxacin base face compressed outpatient prescribing in Germany and France where EMA PRAC restrictions trigger prior authorization. Retail pharmacy volume is rotating down as stewardship programs redirect appropriate cases to hospital supervision.
- Oral Solution:Liquid formulations for pediatric or dysphagic patients carry stability challenges and shorter shelf lives than solid dosage forms.
- Eye Drops:Ophthalmic solutions for bacterial conjunctivitis compete with generic ofloxacin and tobramycin alternatives in crowded retail markets.
Injectables hold installed capacity. Oral Solution is rotating up the share rankings as pediatric formulary access expands.
Application:
Clinical indication determines reimbursement tier and resistance surveillance exposure, with respiratory protocols retaining priority placement against contracting urology use.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis represent the largest volume indication where levofloxacin serves as second-line therapy after beta-lactam failure. Indian tertiary hospitals and US infusion centers sustain demand through ICU bundle compliance and atypical pathogen coverage requirements.
- Urinary Tract Infections:Complicated UTIs and pyelonephritis face automatic formulary restrictions in European markets where Escherichia coli susceptibility thresholds trigger alternative agent mandates. CDSCO and NMPA maintain broader approval scopes, preserving access in Asian public health programs.
- Skin Infections:Diabetic foot and complicated soft-tissue infections compete with linezolid and daptomycin in hospital antibiotic stewardship hierarchies.
- Bone Infections:Osteomyelitis applications require prolonged IV-to-oral step-down protocols with limited first-line positioning.
Respiratory Infections holds installed capacity. Skin Infections is rotating up the share rankings as diabetic population burden expands.
End User:
Customer type determines supervision intensity and regulatory documentation burden, with institutional procurement concentrating volume against fragmented retail dispersion.
- Hospitals:Tertiary care centers and district hospitals in China, India, and the United States aggregate demand through centralized pharmacy committees and diagnosis-related group procurement. Injectable administration within supervised settings satisfies FDA boxed warning requirements for tendon rupture and neuropathy monitoring.
- Clinics:Outpatient infusion centers in France and Germany concentrate respiratory infection treatment under EMA-mandated prescription audit systems.
- Home Care:Post-discharge oral step-down therapy faces adherence monitoring challenges and reimbursement complexity.
- Pharmacies:Community and hospital outpatient dispensaries confront prior authorization requirements and generic substitution pressure.
Hospitals holds installed capacity. Clinics is rotating up the share rankings as infusion center networks expand.
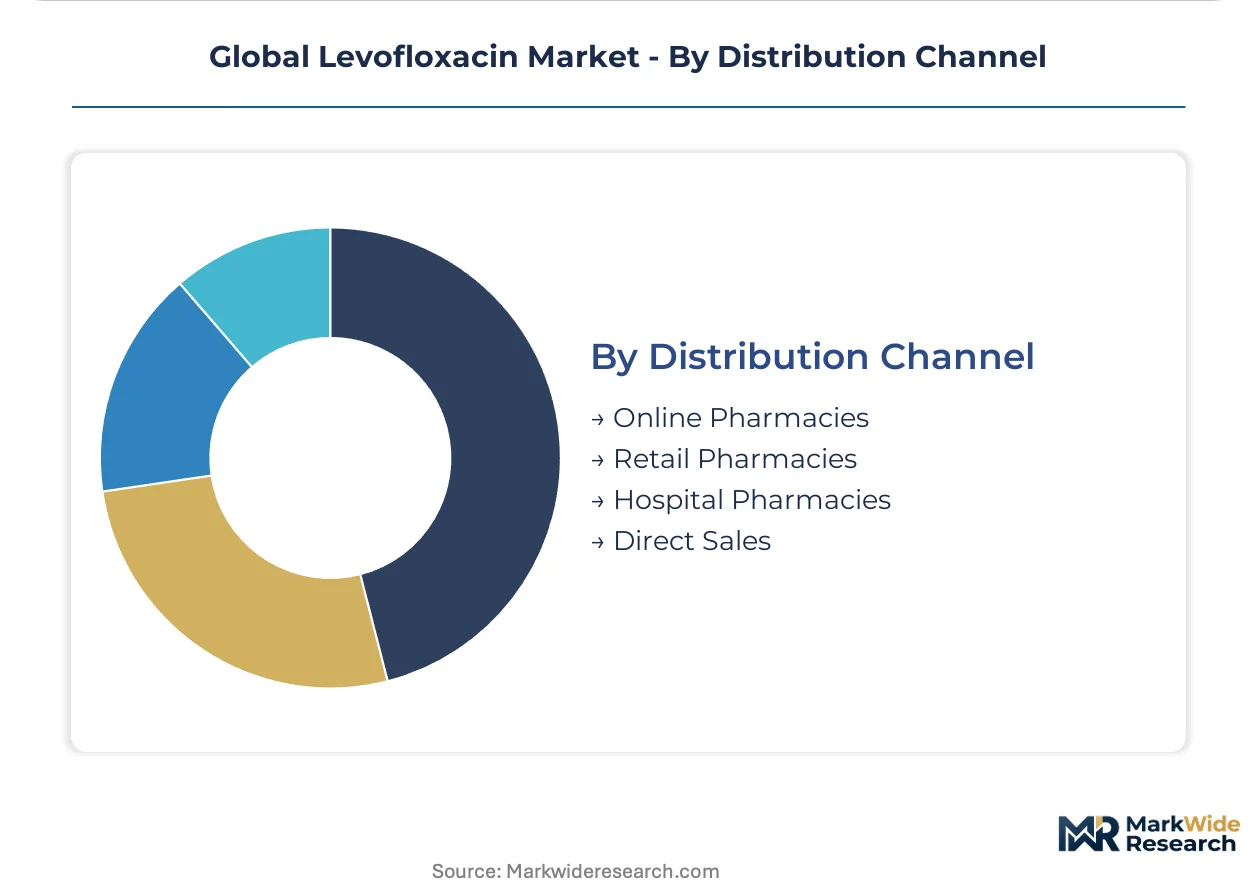
Distribution Channel:
Channel structure determines price realization and inventory risk allocation, with direct hospital contracting displacing wholesale intermediaries in concentrated markets.
- Hospital Pharmacies:Internal procurement departments negotiate annual volume commitments with manufacturers under China's NMPA volume-based purchasing and US group purchasing organization contracts. This channel captures the majority of injectable volume through tender-based supplier selection.
- Retail Pharmacies:Independent and chain dispensaries in India and the United States face compressed levofloxacin margins due to generic saturation and stewardship-driven prescription decline.
- Online Pharmacies:E-commerce platforms face regulatory scrutiny for antibiotic dispensing compliance in jurisdictions with prescription verification requirements.
- Direct Sales:Manufacturer-to-institution contracts for large hospital systems reduce intermediary costs and enable custom packaging.
Hospital Pharmacies holds installed capacity. Direct Sales is rotating up the share rankings as integrated delivery networks consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific pharmaceutical logistics, handling bulk API shipments that feed formulation plants across Zhejiang and Jiangsu provinces. This maritime infrastructure underwrites China's dominance in levofloxacin intermediate supply chains.
United States
Hospital group purchasing organizations concentrate injectable procurement through three dominant GPOs covering over 90 percent of acute care beds. FDA's boxed warning updates for fluoroquinolone adverse effects trigger prior authorization requirements in outpatient settings. New Jersey and North Carolina host sterile manufacturing facilities supplying East Coast hospital networks.
China
NMPA volume-based purchasing bundles antibiotics into diagnosis-related group payment categories, compressing margins while expanding volume commitments. Zhejiang province controls over 60 percent of global levofloxacin API output through integrated chemical parks in Taizhou and Shaoxing. Domestic manufacturers with green channel certification capture tender awards in centralized hospital procurement.
India
CDSCO streamlined bioequivalence pathways accelerate generic fluoroquinolone approvals for public health program supply. Maharashtra's Baddi-Barotiwala-Nalagarh corridor hosts formulation plants serving export markets to Africa and Southeast Asia. Telangana's Genome Valley cluster concentrates API manufacturing with backward integration into key starting materials.
Germany
EMA PRAC recommendations on fluoroquinolone adverse effects mandate systematic prescription audits across outpatient settings. Bavaria and North Rhine-Westphalia operate hospital pharmacy committees that restrict urinary tract infection indications based on local Escherichia coli susceptibility thresholds. German hospital formularies concentrate respiratory infection use within supervised infusion centers.
Japan
PMDA maintains stringent bioequivalence requirements for generic levofloxacin approvals, limiting multinational market entry. Kanto region's Tokyo-Osaka pharmaceutical corridor hosts formulation facilities supplying domestic hospital networks. Japanese antimicrobial stewardship programs restrict outpatient prescribing through mandatory first-line agent documentation.
Global Levofloxacin Market Vendor Landscape
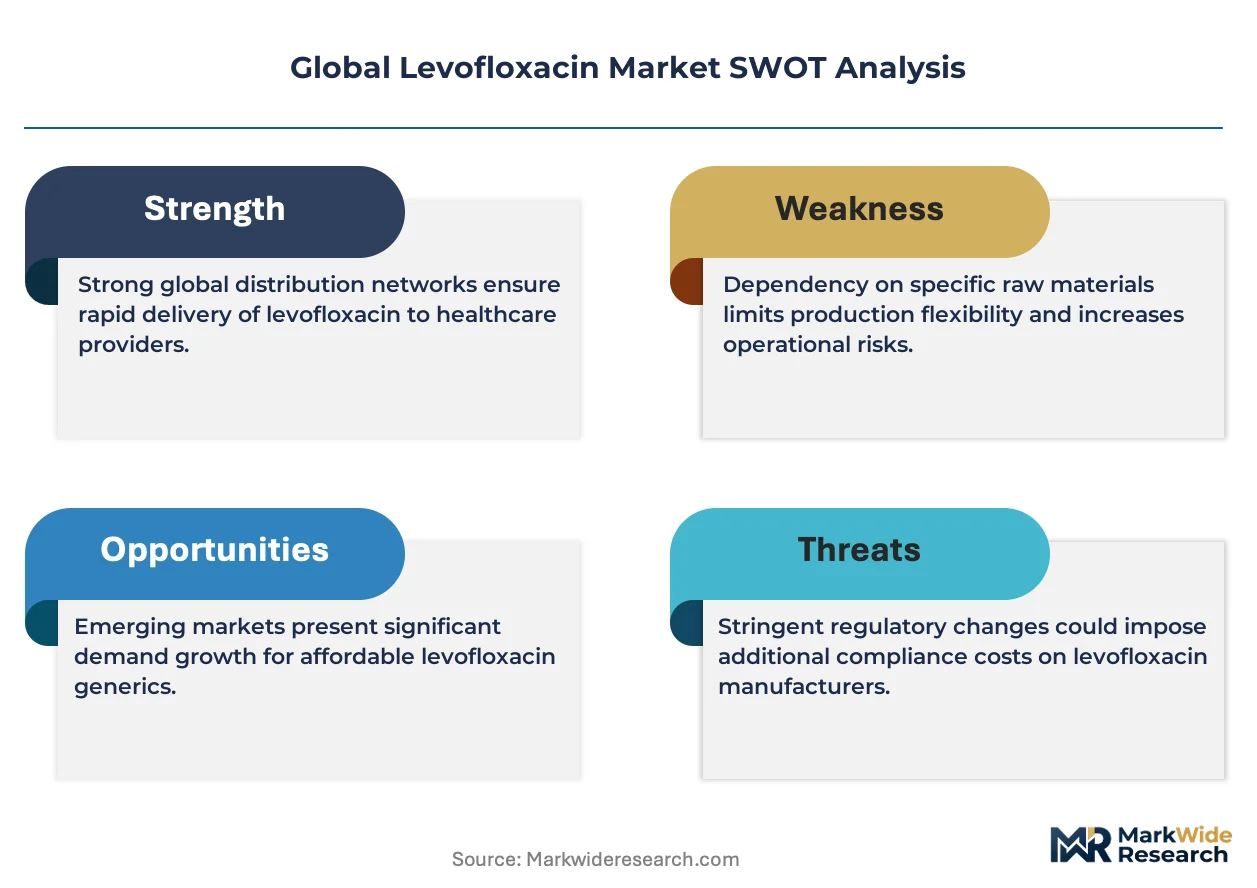
Platform integrators command the system tier; component specialists sit upstream with API and intermediate supply. The market structures around three tiers: integrated manufacturers with captive API production, formulation-focused generics houses, and research-oriented originators with legacy brand positions. Competitive moves concentrate on backward integration into key starting materials and sterile manufacturing capacity expansion for hospital injectable supply.
Among Indian pharmaceutical conglomerates, Dr. Reddy's Laboratories, Lupin Limited, and Sun Pharmaceutical Industries occupy positions reflecting distinct strategic archetypes. Dr. Reddy's exemplifies the backward-integrated model with in-house production of critical intermediates. Lupin represents sustained hospital formulary penetration across regulated markets. Sun Pharmaceutical anchors the scale-driven tier with multi-ton API facilities supplying both captive formulations and external customers.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories Limited |
| Lupin Limited |
| Glenmark Pharmaceuticals Limited |
| MacLeods Pharmaceuticals Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Limited |
| Zydus Lifesciences Limited |
| Aurobindo Pharma Ltd. |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's chemical parks in Taizhou and Shaoxing control over sixty percent of global levofloxacin API output, concentrating upstream margin capture among Chinese intermediate manufacturers while downstream formulators in India and the United States compete on sterile manufacturing certification and hospital tender access.
Pricing Analysis
FDA's boxed warning updates for fluoroquinolone adverse effects dictate the pricing tier structure across administration routes. Injectable formulations command premium positioning in hospital procurement due to aseptic manufacturing complexity and ICU protocol placement, while oral tablets face compression from generic saturation and stewardship-driven prescription decline. Price differentiation hinges on ICH Q12 compliance status and sterile certification tier, with outpatient buyers exhibiting highest sensitivity to per-unit costs. Cost compression in oral solids is intensifying because CDSCO streamlined approvals expand affordable supply for Indian public health programs.
Supply Chain Analysis
Contract manufacturing capacity for sterile injectables concentrates among Dr. Reddy's Laboratories, Lupin Limited, and Sun Pharmaceutical Industries with multi-ton API facilities. Raw material dependencies draw from N-methylpiperazine, ethyl levofloxacin carboxylate, and specialized solvents sourced primarily from Zhejiang and Jiangsu provinces in China. Single-source vulnerability in intermediate supply creates exposure to regulatory inspection delays or export restriction events. Distribution runs through hospital group purchasing organizations in the United States, NMPA volume-based purchasing in China, and direct tender awards to integrated API-formulator houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in antimicrobial stewardship consulting and hospital pharmacy formulary management are expanding faster than commodity formulation supply, creating recurring revenue layers for manufacturers with clinical pharmacology expertise.
For Market Incumbents: Pre-empt formulary exclusion by embedding clinical pharmacists within hospital pharmacy committees to navigate dosing optimization protocols and resistance surveillance requirements. Anchor backward integration into key starting materials to protect margin structures against intermediate price volatility from Zhejiang supply concentration. Defensive moves must address EMA PRAC prescription audit systems compressing outpatient volume across German and French markets. For New Entrants and Emerging Players: Southeast Asian hospital procurement networks present underpenetration where CDSCO-approved manufacturers can leverage existing bioequivalence documentation for accelerated market entry. Target respiratory infection applications in Indian district hospitals where sepsis protocol compliance sustains injectable demand. White-space capture requires WHO Prequalification pathway investment to access developing-market essential medicines procurement. For Investors and Strategic Acquirers: Capital is best deployed toward API-integrated formulators with NMPA green channel certification and established hospital tender relationships in China's volume-based purchasing system. Long-term viability rests on antimicrobial resistance containment mandates redirecting demand toward supervised hospital administration. Monitor CDSCO and NMPA bioequivalence standard convergence as inflection signal for multinational filing cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Starting Materials | Insulates Dr. Reddy's Laboratories and Lupin Limited from Zhejiang intermediate price volatility. |
| Sterile Manufacturing Capacity Expansion | Captures ICU bundle placement premiums in US hospital group purchasing organization contracts. |
| WHO Prequalification Pathway Investment | Sustains developing-market procurement eligibility despite Essential Medicines List Watch Group classification. |
| Antimicrobial Stewardship Service Attach | Differentiates hospital offerings through embedded clinical pharmacist support for formulary navigation. |
| Combination Therapy Formulation Development | Addresses emerging respiratory pathogen resistance through beta-lactamase inhibitor co-formulation. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, formulary directors, regulatory affairs leads, and antimicrobial stewardship pharmacists; and secondary validation through FDA filings, EMA PRAC recommendations, CDSCO approval databases, and NMPA volume-based purchasing tender records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to anchor forecast outputs.
Forecast inputs include administration route segmentation, infection site indication, regional regulatory cluster differentiation, and bioequivalence pathway complexity across the projection horizon. CAGRs were derived from hospital procurement volume trajectories and stewardship program implementation timelines. Modeled dimensions span dosage form, end-user institution type, and distribution channel concentration.
Practitioners should monitor CDSCO-NMPA regulatory harmonization progress and EMA prescription audit enforcement intensity for early signals of generic approval timeline compression or outpatient prescribing restriction expansion. Quarterly review of hospital formulary restriction triggers and API export licensing patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Plasma Protein System Market