
 Global Branded Generics Market | 2026-2036
Global Branded Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Branded Generics Market Intelligence
The divergence in capital allocation for brand development versus pure manufacturing scale is unwinding the traditional generic business model. Teva Pharmaceutical Industries Ltd. leverages its established brand presence in specific therapeutic areas to maintain physician loyalty. Sun Pharmaceutical Industries Ltd. differentiates through a portfolio that includes complex generics requiring specialized manufacturing. Sandoz Group AG competes by combining its large-scale production efficiencies with targeted marketing efforts in key European and North American markets.
Branded generics are off-patent drug formulations sold under a proprietary trade name rather than their international nonproprietary name. These products contain the same active pharmaceutical ingredient and must demonstrate bioequivalence to the original innovator drug, offering a trusted, lower-cost alternative. Oral solid dosage forms like tablets and capsules lead the product type segment because of manufacturing efficiency and patient acceptance. Cardiology remains a high-volume therapy area, with procurement concentrated in both hospital and retail pharmacies.
Regulatory frameworks, including the FDA's 505(b)(2) pathway and the EMA's hybrid application procedure, define the specific approval processes for these modified generic products. In parallel, national bodies such as India's CDSCO enforce stringent manufacturing and quality standards, governing market entry and supply chain integrity. Success for market participants will hinge on balancing price-based competition with the necessary investments in brand differentiation and building physician trust.
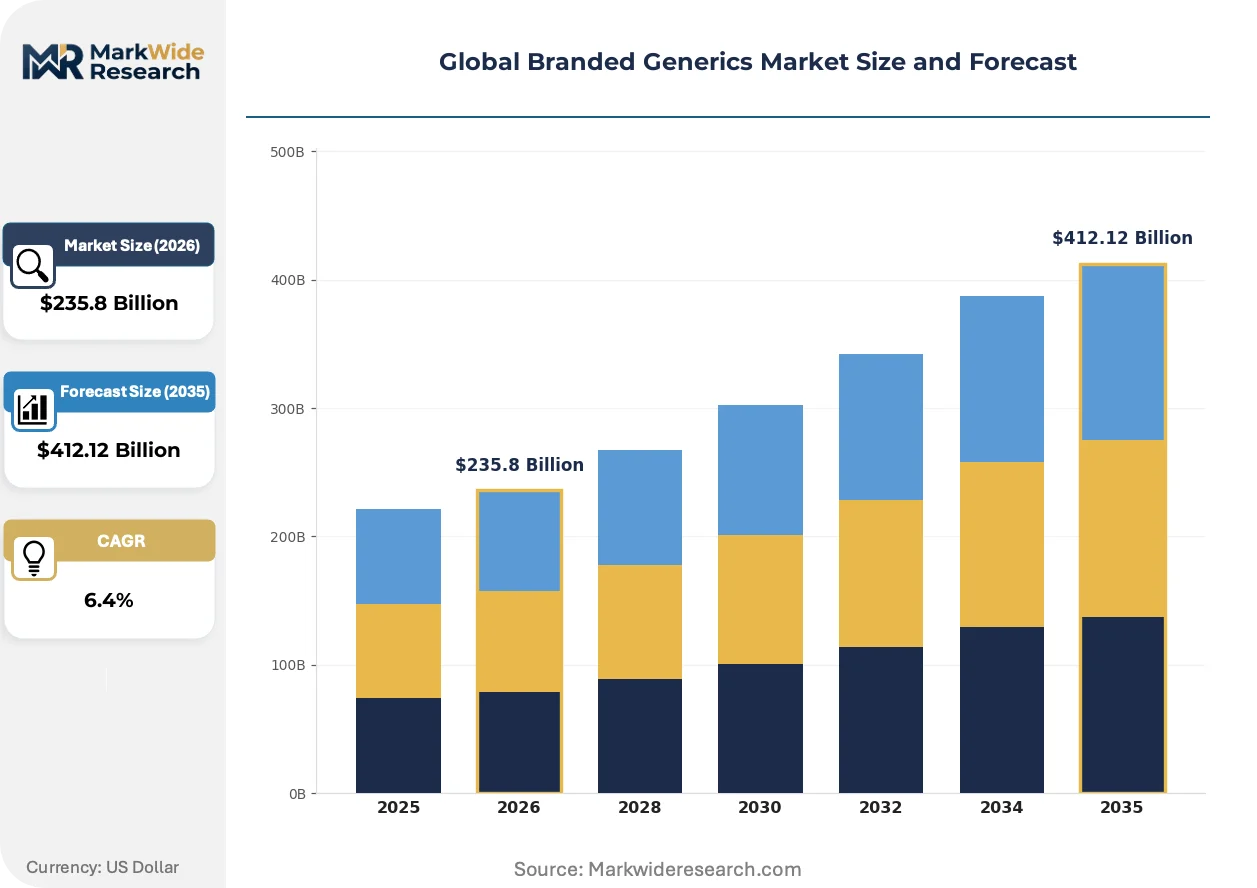
Market Dynamics
The central dynamic in the branded generics market is the strategic pivot from pure price competition to value-based differentiation. This shift is driven by physician and patient demand for trusted, affordable alternatives to innovator drugs, forcing manufacturers to invest in brand equity.
Growth Catalysts
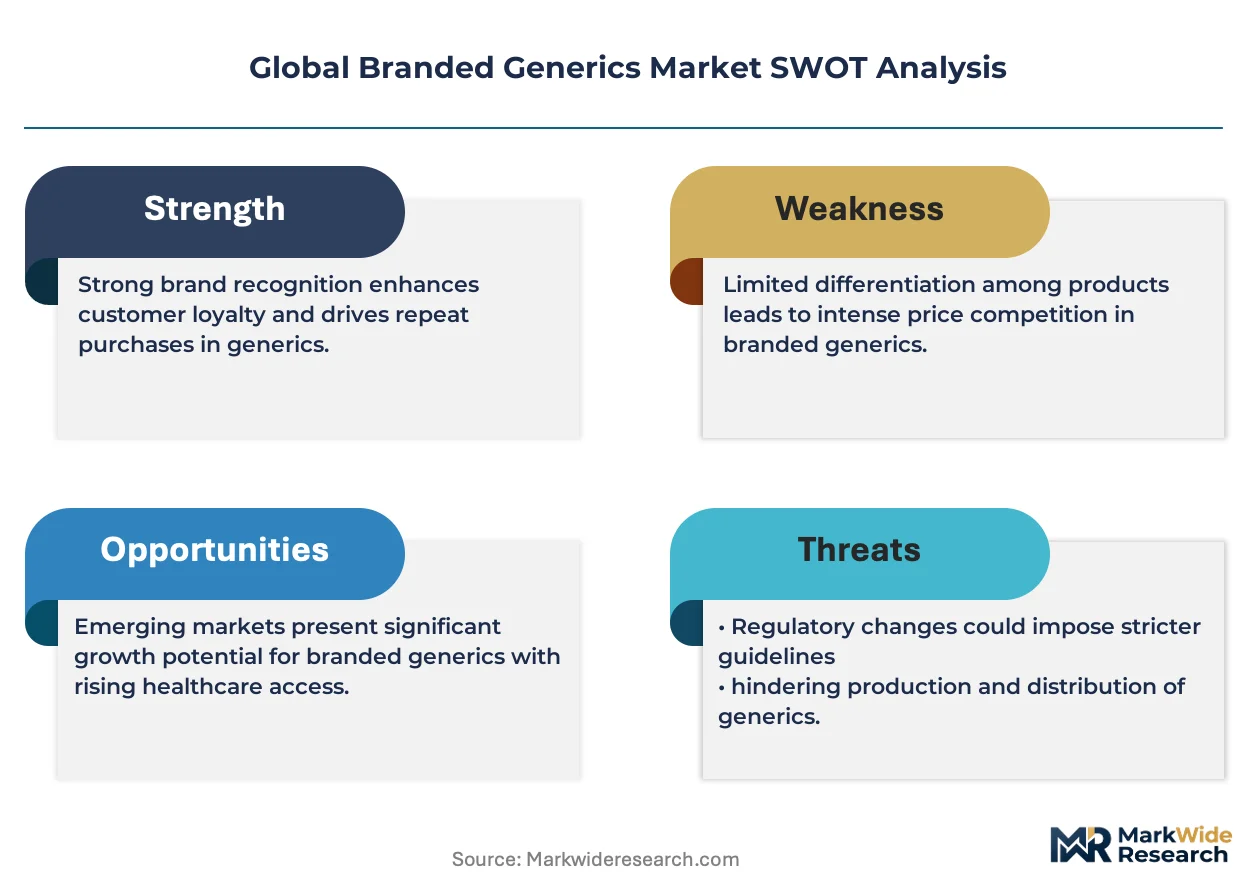
- Regulatory Frameworks for Brand Security:Mandates such as the EU's Falsified Medicines Directive, which requires unique identifiers and anti-tampering devices on packaging, enhance brand integrity and patient trust, thereby supporting premium positioning over unbranded alternatives.
- Expanding Healthcare Access in Emerging Economies:Countries like India and Brazil, with their large patient populations and increasing healthcare expenditure, provide a high-volume demand base for branded generics, which offer a balance of cost-effectiveness and perceived quality.
- High Prevalence of Chronic Diseases:The sustained incidence of cardiovascular diseases, diabetes, and other chronic conditions globally ensures a consistent, large-scale demand for established therapies, with the cardiology segment being a primary volume driver for branded generics.
Market Restraints
- Intense Price Erosion from Unbranded Generics:The primary restraint is direct competition from commodity generics, which exert constant downward price pressure and can erode the market share of branded versions if brand loyalty is not sufficiently established.
- Complex and Lengthy Regulatory Pathways:Approval processes like the FDA's 505(b)(2) pathway or the EMA's hybrid application, while enabling differentiation, can be more complex and costly than standard generic submissions, creating barriers to entry.
- High Marketing and Brand-Building Costs:Establishing physician trust and patient recognition requires significant investment in marketing, salesforce detailing, and medical education, adding substantial costs not borne by traditional generic manufacturers.
Strategic Opportunities
- Expansion into Complex Formulations:Developing branded generics for complex products, such as injectables, transdermal patches, or inhalers, offers an opportunity to enter higher-margin segments with fewer competitors due to specialized manufacturing requirements.
- Focus on Biosimilar Crossovers:As biologic patents expire, companies can leverage their brand-building expertise to market biosimilars under a proprietary name, capturing physician trust in a manner similar to small-molecule branded generics.
- Penetration of CNS and Oncology Segments:Targeting central nervous system (CNS) disorders and oncology presents a significant opportunity, as patent cliffs for major drugs in these therapeutic areas open the door for branded generic alternatives.
Industry Challenges
- Maintaining Supply Chain Integrity:Ensuring a secure and traceable supply chain to prevent counterfeiting is a major operational challenge, requiring investment in serialization and track-and-trace technologies compliant with regulations in multiple jurisdictions.
- Navigating Patent Thickets:Innovator companies often protect their products with numerous secondary patents on formulations, delivery methods, or methods of use, creating a complex legal landscape that branded generic firms must navigate to avoid litigation.
- Building Physician Loyalty:A key challenge is persuading physicians to prescribe a branded generic over both the original innovator drug and cheaper, unbranded generics, which requires sustained and effective medical marketing efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Branded Generics Market |
| Market Size in 2026 | $235.8 Billion |
| Market Size in 2035 | $412.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injection, Syrup, Ointment Therapy Area: Cardiology, Neurology, Dermatology, Gastroenterology, Pulmonology End User: Hospitals, Clinics, Pharmacies, Diagnostic Centers, Ambulatory Surgical Centers Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales, Wholesale Distributors |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Viatris Inc., Sandoz Group AG, Dr. Reddy’s Laboratories Ltd., Cipla Ltd., Aurobindo Pharma Ltd., Lupin Ltd., Torrent Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Branded Generics Market Strategic Shifts & Innovations
Product evolution is moving beyond simple bioequivalence to incorporate value-added features that improve patient compliance and therapeutic outcomes. This strategic focus on differentiation is redefining the competitive landscape, creating a distinct market tier between innovator drugs and commodity generics.
Advanced formulation technology, including fixed-dose combinations (FDCs) and modified-release delivery systems, is a key innovation. These technologies are being adopted rapidly in chronic disease management for conditions like hypertension and diabetes to simplify patient regimens. This trend is decomposing the traditional boundary between a generic and a value-added medicine, allowing manufacturers to establish a defensible brand identity.
Regulatory bodies are creating specific pathways that encourage such differentiation. India's Central Drugs Standard Control Organisation (CDSCO), for instance, has clear guidelines for the approval of FDCs, scrutinizing their therapeutic justification. This policy encourages rational combinations that provide distinct clinical benefits, pushing the market toward more innovative product development. The cardiology and anti-infective segments are most affected as companies reformulate existing molecules into more effective combination therapies.
A notable behavioral shift is occurring in how hospital and pharmacy chains make purchasing decisions. Large group purchasing organizations (GPOs) and pharmacy benefit managers (PBMs) are increasingly creating preferred formularies that prioritize branded generics. This model disrupts traditional physician-focused marketing by consolidating decision-making power. This pattern is most evident in the United States, where these large entities leverage their scale to negotiate favorable pricing on branded generics that offer a trusted, cost-effective alternative to innovator brands.
Global Branded Generics Market Segmentation
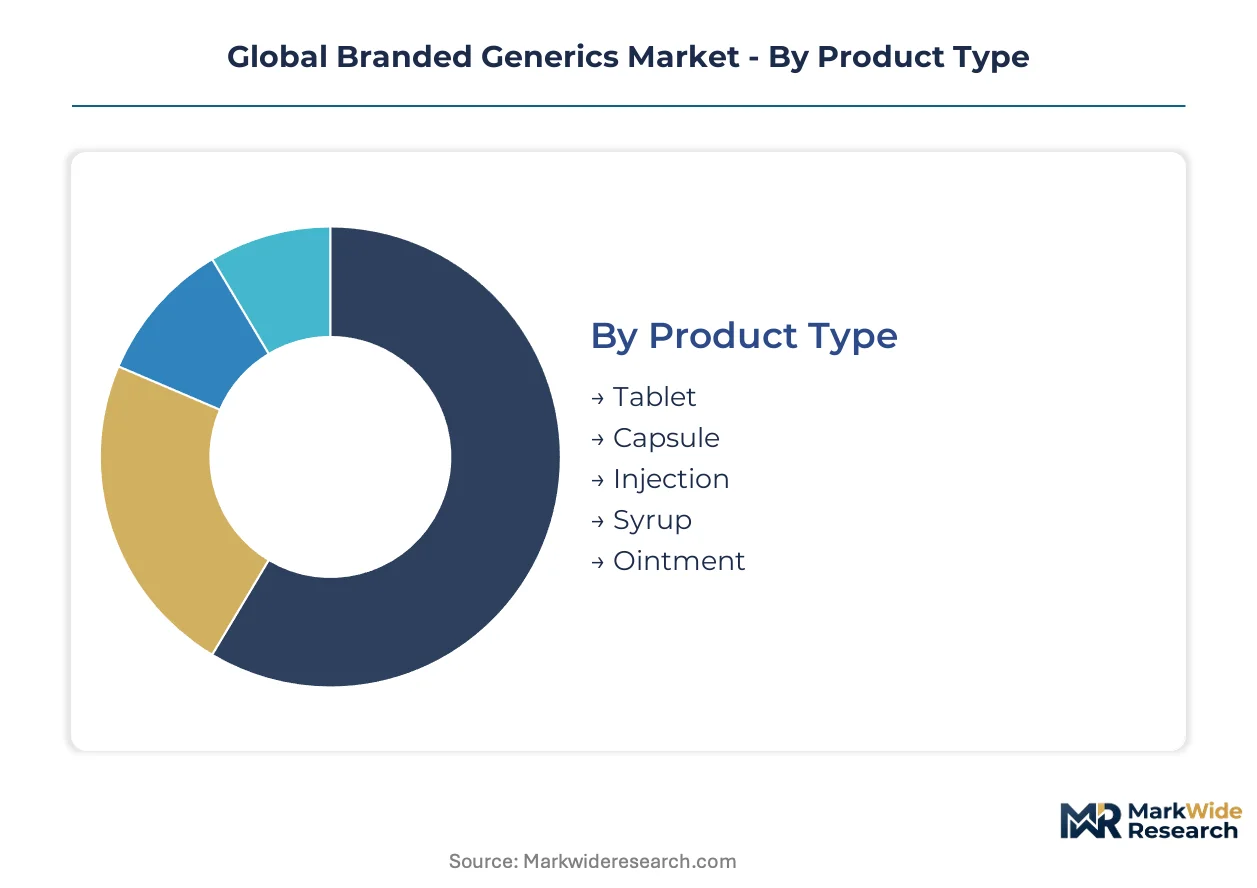
Segmentation provides a granular view of the Global Branded Generics Market, revealing distinct demand patterns and competitive dynamics. Understanding these segments allows manufacturers to tailor product development and market entry strategies. This detailed breakdown highlights areas of specific patient needs and evolving procurement models.
Product Type:
Margin pools within product types often concentrate in formulations offering enhanced patient compliance or specialized delivery. Oral solid dosage forms, due to their manufacturing efficiency and broad patient acceptance, capture significant market value.
- Tablet:This oral solid dosage form represents a cornerstone of branded generics, offering manufacturing efficiency and widespread patient acceptance. Demand for tablets remains consistently high across chronic disease management, particularly in cardiology.
- Capsule:Capsules provide advantages for specific active pharmaceutical ingredients, including taste masking and controlled release mechanisms. These formulations often target therapeutic areas requiring precise drug delivery, such as certain neurological conditions.
- Injection:Injectable branded generics cater to acute care settings and specialized therapies, requiring sterile manufacturing and specific administration protocols.
- Syrup:Liquid formulations like syrups primarily serve pediatric and geriatric patient populations, offering ease of administration.
- Ointment:Topical ointments address dermatological conditions, providing localized treatment with branded generic options for various skin ailments.
Tablet formulations hold significant installed capacity globally. Capsule products are rotating up the share rankings due to advanced formulation technologies.
Therapy Area:
Application demand for branded generics is highest in therapeutic areas with a high prevalence of chronic conditions and expiring patents for innovator drugs. These segments provide consistent, large-scale patient populations.
- Cardiology:This segment commands a substantial share of the branded generics market due to the sustained incidence of cardiovascular diseases globally. Procurement concentrates in both hospital and retail pharmacies for conditions like hypertension and hyperlipidemia.
- Neurology:Branded generics for neurological disorders address conditions such as epilepsy, depression, and Alzheimer's disease, often requiring long-term treatment. Demand for these specialized products is growing as patent expirations increase.
- Dermatology:Branded generic dermatological products offer cost-effective solutions for various skin conditions, including eczema, psoriasis, and acne.
- Gastroenterology:This segment includes branded generics for digestive system disorders, such as acid reflux, irritable bowel syndrome, and inflammatory bowel disease.
- Pulmonology:Pulmonology branded generics treat respiratory conditions like asthma, COPD, and allergies, often incorporating advanced delivery systems.
The cardiology segment consistently drives market volume. Neurology is demonstrating accelerated market responsiveness to new branded generic entrants.
End User:
Customer type and purchasing power significantly influence branded generic sales, with large institutional buyers often dictating procurement terms. Patient access and physician prescribing patterns also shape demand across various end-user settings.
- Hospitals:Hospitals represent a major end-user segment for branded generics, driven by institutional procurement and formulary inclusion decisions. Group purchasing organizations in the United States influence bulk purchasing for hospital systems.
- Pharmacies:Retail and hospital pharmacies serve as primary points of patient access for branded generics, facilitating direct sales and prescription fulfillment. Physician prescribing patterns directly impact sales through this channel.
- Clinics:Clinics, including physician offices and specialized outpatient centers, utilize branded generics for patient treatment and dispensing.
- Diagnostic Centers:While not direct prescribers, diagnostic centers support the identification of conditions that require branded generic therapies.
- Ambulatory Surgical Centers:These centers use branded generics for perioperative care and post-surgical treatment, focusing on cost-effective drug options.
Hospitals maintain significant purchasing influence. Pharmacies are evolving quickly with expanded patient counseling roles.
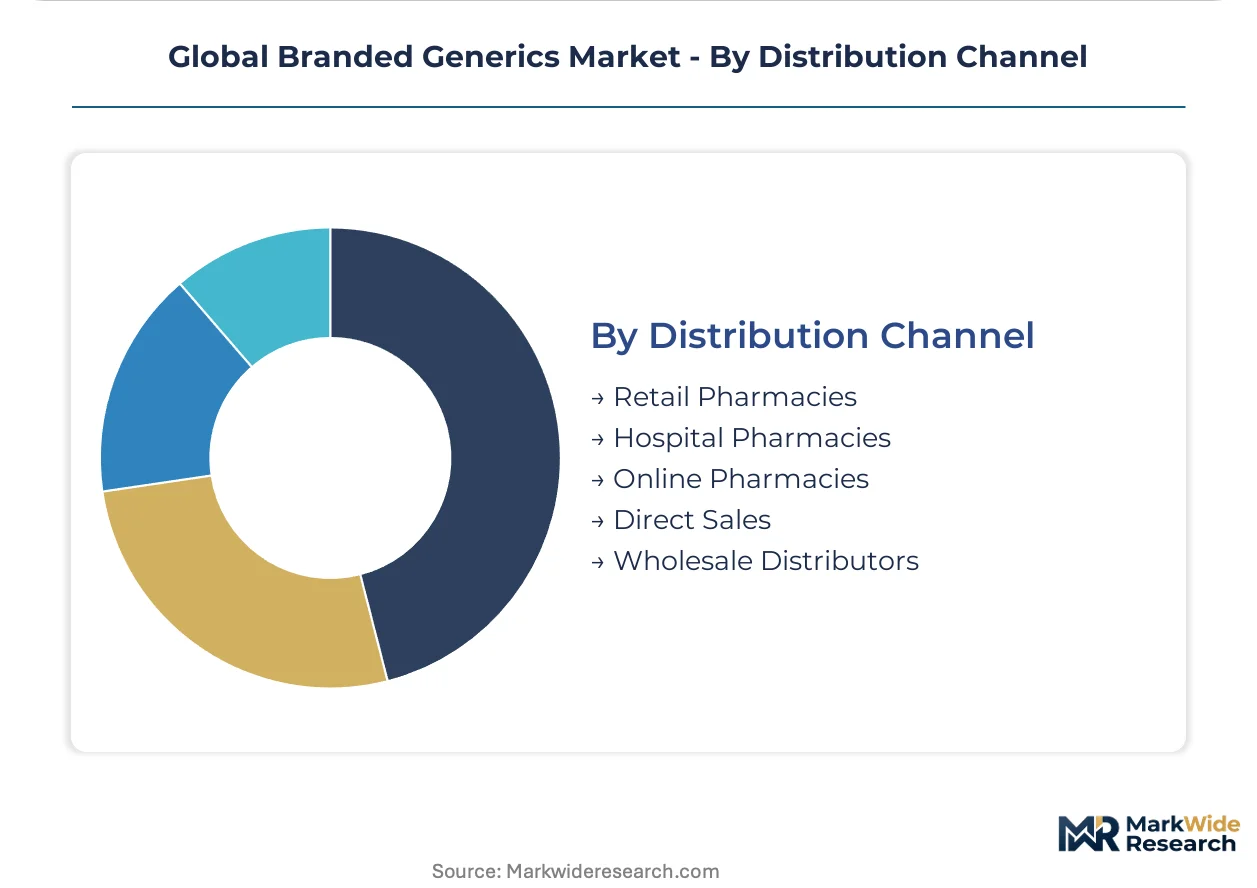
Distribution Channel:
Supply concentration within distribution channels determines market reach and pricing power for branded generics manufacturers. The shift towards consolidated purchasing entities impacts channel dynamics.
- Retail Pharmacies:This channel provides widespread patient access to branded generics, driven by physician prescriptions and direct consumer purchases. Brand visibility and patient trust are critical for success in retail settings.
- Hospital Pharmacies:Hospital pharmacies manage the procurement and dispensing of branded generics within institutional healthcare settings. Their purchasing decisions are often influenced by hospital formularies and cost-effectiveness.
- Online Pharmacies:The online channel offers convenience and competitive pricing, expanding access to branded generics for a growing consumer base. Digital platforms are gaining traction in several markets, including India.
- Direct Sales:Some manufacturers engage in direct sales to large healthcare systems or government entities, bypassing intermediaries for specific product lines.
- Wholesale Distributors:Wholesalers act as crucial intermediaries, facilitating the efficient movement of branded generics from manufacturers to various end-users.
Retail pharmacies remain the most accessible distribution channel. Online pharmacies are gaining share fastest due to convenience and price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global branded generics market exhibits a nuanced export-import balance, with major manufacturing hubs like India supplying a significant portion of the world's demand, while developed economies focus on consumption and specialized product development. This dynamic creates distinct regional market structures and competitive pressures for market participants. Emerging economies are simultaneously increasing their local production capabilities.
India
India's demand for branded generics is propelled by its vast patient population and the need for affordable, trusted medicines. The CDSCO enforces stringent manufacturing and quality standards, governing market entry and supply chain integrity. Pharmaceutical clusters in Gujarat and Maharashtra are increasing production capacity to meet both domestic and international needs.
United States
The United States market is driven by high healthcare expenditure and a strong preference for trusted pharmaceutical brands, even for off-patent drugs. The FDA's 505(b)(2) pathway defines specific approval processes for modified generic products, encouraging differentiation. Large group purchasing organizations in cities like Chicago and New York influence procurement decisions for hospital systems.
Germany
German demand for branded generics stems from an aging population and a well-established healthcare system prioritizing therapeutic efficacy and cost-effectiveness. The EMA's hybrid application procedure guides the approval of these modified generic products across Europe. Pharmaceutical research and manufacturing hubs in Bavaria and North Rhine-Westphalia are focusing on advanced formulations.
Brazil
Brazil's market expansion is fueled by increasing healthcare access and a growing middle class seeking reliable, cost-effective drug alternatives. ANVISA, the national health surveillance agency, regulates the approval and commercialization of branded generics. Production facilities in São Paulo and Rio de Janeiro are expanding to serve the domestic and Latin American markets.
China
China's market for branded generics is experiencing significant growth due to healthcare reforms and a rising incidence of chronic diseases. The NMPA oversees drug approvals and quality control, aiming to elevate domestic pharmaceutical standards. Manufacturing bases in the Yangtze River Delta region are rapidly developing advanced generic drug production capabilities.
Global Branded Generics Market Key Industry Players
Concentration sits with established pharmaceutical giants leveraging extensive distribution networks and brand recognition. The market structure is tiered, featuring large multinational players alongside regional specialists and emerging local manufacturers. Strategic archetypes include diversified pharmaceutical conglomerates, specialized generic producers, and innovation-focused biopharmaceutical firms. Dominant competitive moves involve portfolio diversification into complex generics and geographic expansion into high-growth emerging markets.
Diversified pharmaceutical companies like Teva Pharmaceutical Industries Ltd. and Sandoz Group AG exemplify global scale and broad therapeutic portfolios. Sun Pharmaceutical Industries Ltd., based in India, represents a strong regional player with a focus on specialized manufacturing capabilities. These companies occupy positions that balance large-scale production efficiencies with targeted marketing efforts in key therapeutic areas.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Sandoz Group AG |
| Dr. Reddy’s Laboratories Ltd. |
| Cipla Ltd. |
| Aurobindo Pharma Ltd. |
| Lupin Ltd. |
| Torrent Pharmaceuticals Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for active pharmaceutical ingredients (APIs) lock in consistent supply access and provide critical price visibility for branded generic manufacturers.
Pricing Analysis
Hospital group purchasing organizations anchor contract-based long-term offtake agreements for branded generics. Price differentiation stems from brand premium and consistent bioequivalence, ensuring patient trust. Downward pricing pressure arises from intense competition with commodity generics, particularly for high-volume oral solids. Retail pharmacies demonstrate the highest price sensitivity among end-users, while GPOs balance cost with perceived quality.
Supply Chain Analysis
API manufacturing concentration in India and China underwrites the global branded generics supply chain. This relies heavily on key raw materials like active pharmaceutical ingredients and specialized excipients. Single-source vulnerability for critical APIs poses a structural risk, alongside complex regulatory compliance. Distribution runs primarily through wholesale distributors to retail and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among large group purchasing organizations and pharmacy benefit managers is shifting buyer power in the branded generics market. This necessitates strategic adjustments from all market participants.
For Market Incumbents: Fortify existing brand equity through continuous investment in advanced formulation R&D, such as fixed-dose combinations and modified-release systems. This defends against intense price erosion from unbranded generics by offering clear value differentiation. Leverage specialized manufacturing capabilities to maintain a competitive edge in complex product segments. Strengthen physician loyalty through targeted medical education and consistent product quality.
For New Entrants and Emerging Players: Differentiate on specialized formulation expertise, targeting high-margin segments like complex injectables and biosimilar crossovers. Emerging economies, particularly India and Brazil, represent the most penetrable geographies due to expanding healthcare access. A successful go-to-market angle involves strategic partnerships with established local distributors to navigate regional regulatory landscapes and build trust rapidly.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized generic producers with strong brand recognition in specific therapeutic areas. Long-term viability in this market is driven by the sustained incidence of chronic diseases, ensuring consistent demand over the next five to ten years. Target acquisition archetypes include firms possessing niche formulation technologies or robust regional distribution networks. The signal to watch is the acceleration of regulatory pathways for value-added generic products.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Formulation R&D | Drives brand differentiation and patient compliance in chronic disease management. |
| Geographic Market Expansion | Captures demand from growing patient populations in emerging economies like India. |
| Biosimilar Development | Leverages brand-building expertise to enter higher-value biologic-adjacent segments. |
| Digital Channel Integration | Enhances patient access and price transparency through online pharmacies. |
| Supply Chain Serialization | Ensures brand integrity and regulatory compliance with directives like the Falsified Medicines Directive. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, CDSCO guidelines, and industry association reports. This involved extensive interviews with regulatory affairs leads, hospital procurement managers, pharmacy chain executives, and pharmaceutical R&D directors. Both bottom-up and top-down triangulation approaches were applied to ensure data accuracy and market coverage.
Product type, therapy area, end user, distribution channel, and regional regulatory cluster formed the segmentation dimensions modeled across the analysis window. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included patent expiration schedules and chronic disease prevalence rates over the projection horizon.
Forecasts assume regulatory continuity in US FDA, EU EMA, and India CDSCO regimes; material policy shifts would require re-modeling. Projections reflect current market dynamics, acknowledging potential impacts from unforeseen drug pricing policy changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Bioequivalence Studies Market