
 Global Long Read Sequencing Market | 2026-2036
Global Long Read Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Long Read Sequencing Market Intelligence
Platform licensing revenue from bioinformatics workflows is reconfiguring margin distribution across the sequencing value chain. Pacific Biosciences leverages its HiFi chemistry ecosystem to anchor high-margin consumable sales in human genomics. Oxford Nanopore Technologies competes through portable device deployment that extends field-based sequencing into resource-limited settings. Element Biosciences differentiates on cost-per-run economics that undercut incumbent pricing in core research markets.
Long read sequencing employs single-molecule detection to generate contiguous reads exceeding 10 kilobases, overcoming the assembly limitations of short-read platforms in repetitive genomic regions. The technology serves critical functions in de novo genome assembly, structural variant detection, and epigenetic characterization where phasing and contiguity determine biological interpretability. DNA sequencers occupy the dominant hardware margin pool, while nanopore sequencing technology represents the fastest-expanding modality driven by real-time analysis and minimal capital requirements. Academic research institutes constitute the largest installed base, though clinical laboratories represent the emerging growth corridor as reimbursement frameworks mature for diagnostic applications.
FDA oversight of next-generation sequencing-based oncology companion diagnostics shapes product development roadmaps and clinical trial design requirements for platform manufacturers. The EMA's In Vitro Diagnostic Regulation and Japan's PMDA guidance on genomic testing standards create parallel compliance obligations that filter market access across major jurisdictions. Stakeholders must monitor evolving reimbursement determinations from the CMS and analogous national payers, as coverage decisions for long read-based tests will determine whether clinical demand converts to sustainable revenue at scale.
Market Dynamics
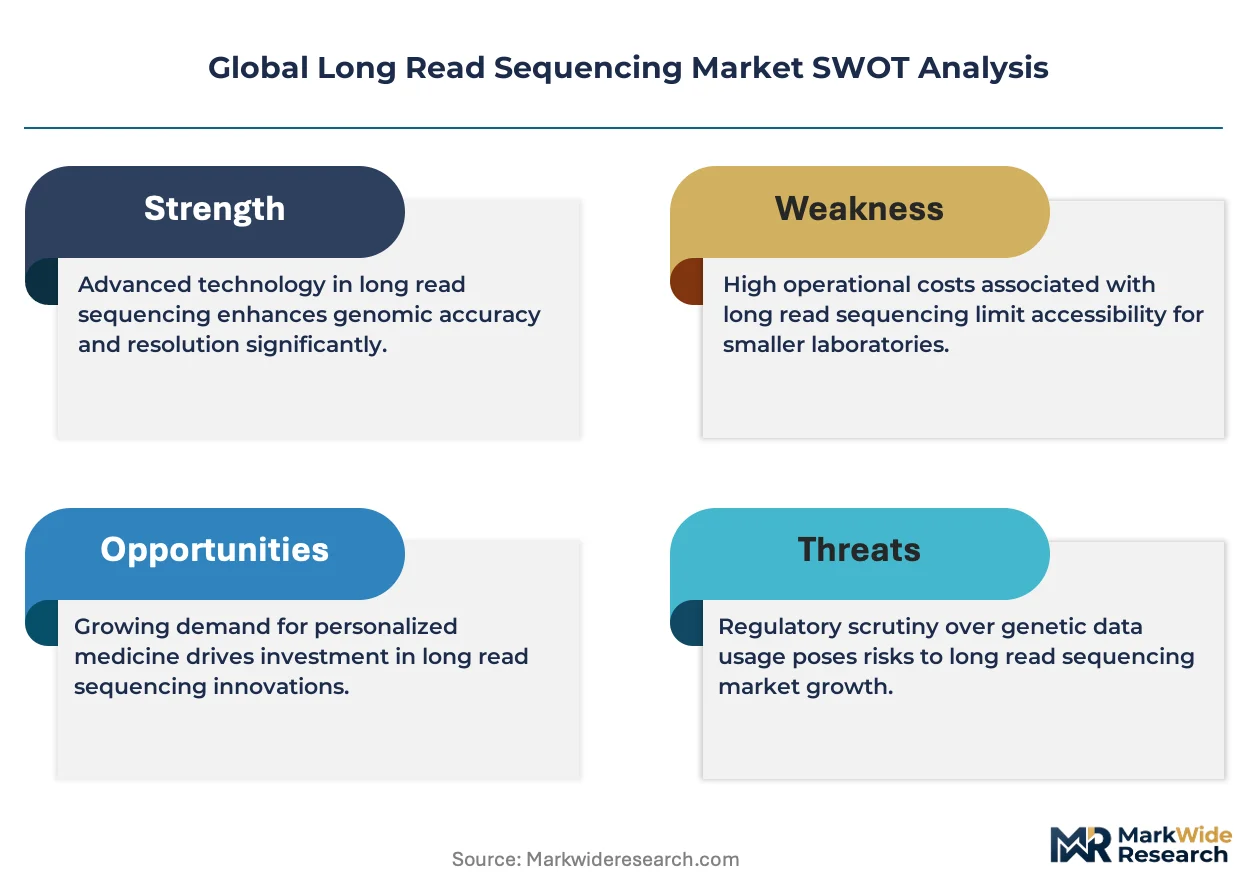
Platform manufacturers face intensifying pressure from the FDA's evolving guidance on next-generation sequencing-based oncology diagnostics, which is compressing clinical validation timelines and forcing upstream integration into bioinformatics workflows.
Growth Catalysts
- NIH Precision Medicine Initiatives:Federal funding streams in the United States are expanding installed base capacity at academic medical centers, creating pull-through demand for high-throughput long read systems.
- Structural Variant Detection Applications:Oncology laboratories are adopting contiguous read technologies to resolve complex genomic rearrangements that short-read platforms miss entirely.
- Epigenetic Characterization Workflows:Research institutes are deploying native DNA methylation detection capabilities to advance developmental biology and neurodegenerative disease studies.
Market Restraints
- Consumable Cost Structure:Single-molecule reagent kits command premium pricing that constrains budget-constrained research programs from scaling experiment volume.
- Capital Equipment Concentration:DNA sequencer manufacturing relies on specialized optical component suppliers concentrated in East Asian precision electronics clusters.
- Technical Read Accuracy Trade-offs:Nanopore sequencing modalities exhibit elevated indel error rates that limit deployment in clinical diagnostic settings requiring variant confirmation.
Strategic Opportunities
- Field-Based Deployment Models:Portable sequencing devices are penetrating infectious disease surveillance networks in sub-Saharan African countries lacking centralized laboratory infrastructure.
- Companion Diagnostic Reimbursement Pathways:CMS coverage determinations for long read-based oncology tests could unlock sustainable clinical revenue streams at scale.
- Artificial Intelligence Integration:Basecalling algorithms are converging with deep learning architectures to compress analysis timelines and reduce computational infrastructure requirements.
Industry Challenges
- Bioinformatics Talent Scarcity:Commercial laboratories face acute shortages of computational biologists capable of optimizing assembly pipelines for heterogeneous sample types.
- Multi-Jurisdictional Compliance Burden:Platform manufacturers must synchronize FDA premarket submissions with EMA In Vitro Diagnostic Regulation technical documentation and Japan PMDA genomic testing standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Long Read Sequencing Market |
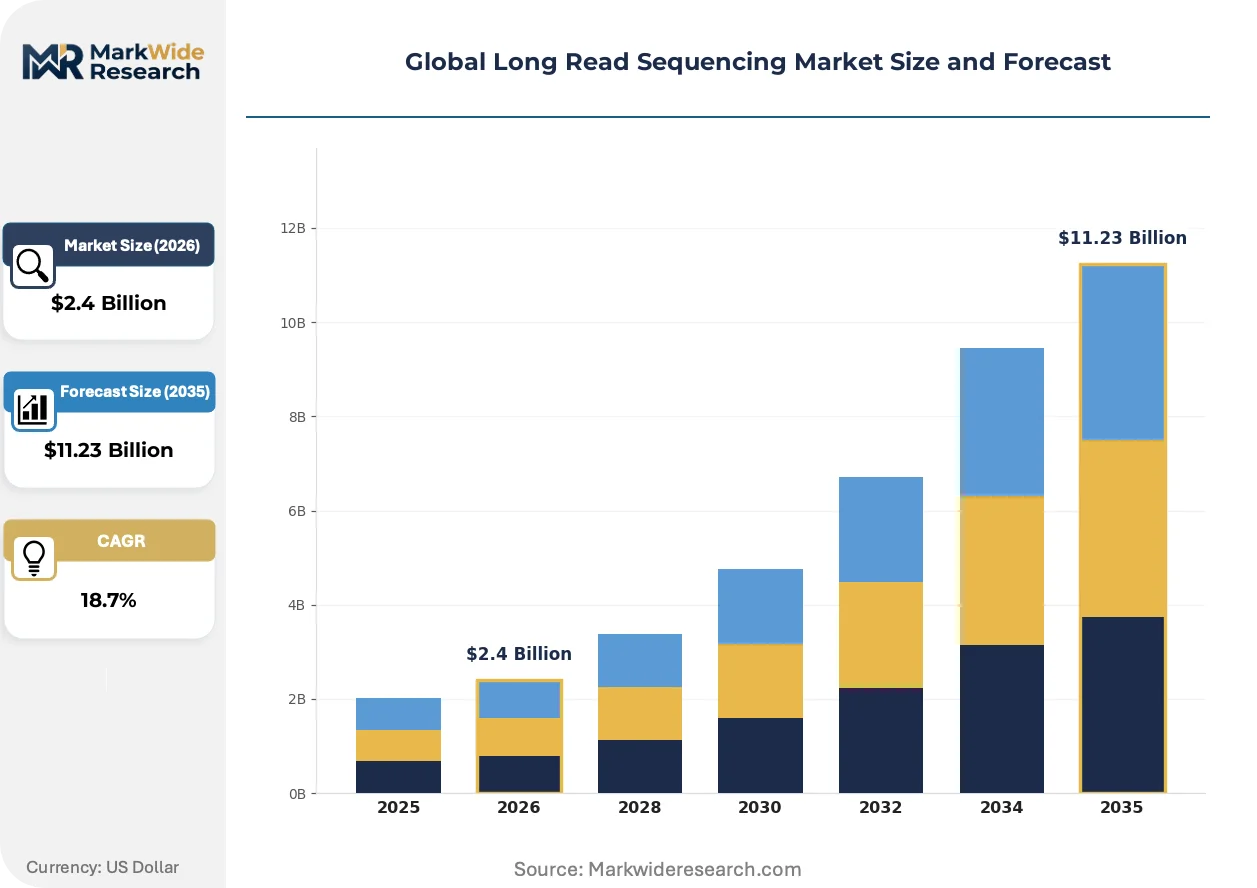
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencers, RNA Sequencers, Accessories, Software Technology: Single-Molecule Real-Time, Nanopore Sequencing, Synthetic Long Reads, Others End User: Academic Research Institutes, Clinical Laboratories, Pharmaceutical Companies, Biotechnology Firms Application: Oncology Research, Genetic Disorders, Infectious Diseases, Agricultural Genomics |
| Companies Covered | Pacific Biosciences, Oxford Nanopore Technologies, Illumina Inc., F. Hoffmann-La Roche Ltd., Agilent Technologies, Inc., Element Biosciences, BGI Genomics, Eurofins Genomics, New England Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Long Read Sequencing Market Strategic Shifts & Innovations
Long read sequencing is undergoing functional convergence with artificial intelligence and cloud computing architectures, compressing the gap between raw signal acquisition and clinically actionable variant interpretation.
HiFi chemistry workflows are hybridizing with real-time basecalling architectures to deliver contiguous reads exceeding 25 kilobases at accuracy thresholds matching short-read platforms. Pharmaceutical toxicology groups are adopting these hybrid systems for off-target CRISPR editing detection at preclinical stages. The structural consequence is collapsing the traditional segmentation between research-grade and clinical-grade sequencing infrastructure, forcing vendors to certify single platforms across both use cases.
EMA's In Vitro Diagnostic Regulation is imposing new post-market surveillance obligations on sequencing platform manufacturers selling into European Union member states. Device makers must now maintain systematic performance monitoring and periodic safety reporting that parallels pharmaceutical product vigilance requirements. Clinical laboratories in Germany and France are responding by consolidating vendor relationships to reduce compliance documentation burden across multiple instrument fleets.
Service contract unbundling is fragmenting traditional sequencing platform procurement models as buyers separate hardware acquisition from maintenance and bioinformatics support. Academic core facilities are migrating toward per-run pricing arrangements with external service providers rather than capital ownership. This shift is most visible in United Kingdom research institutes facing constrained capital allocation from frozen block grant funding mechanisms.
Global Long Read Sequencing Market Segmentation
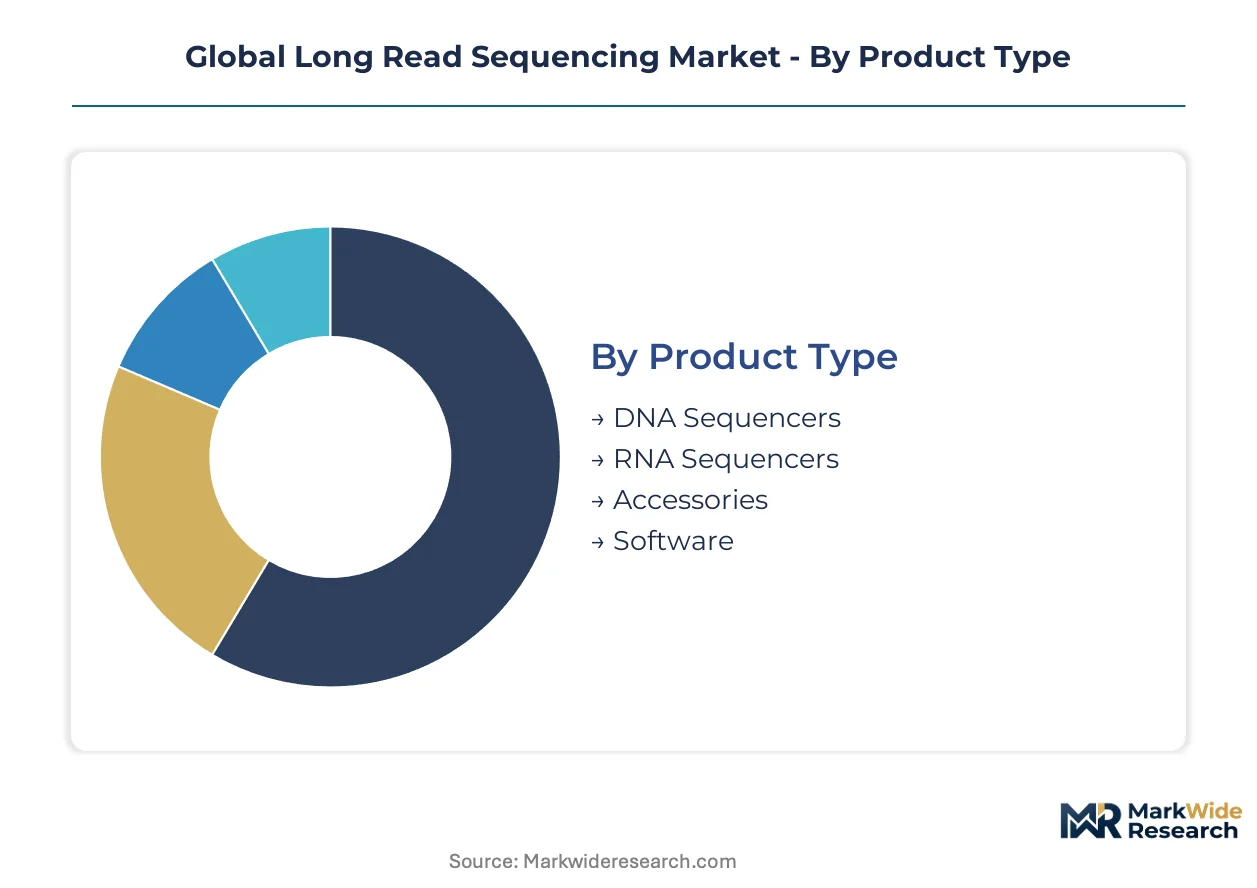
Long read sequencing markets fragment across hardware, chemistry, and software layers with divergent margin profiles and replacement cycles. Understanding these segment boundaries clarifies where vendor competition intensifies and where pricing power concentrates.
Product Type:
After-sales service intensity varies sharply across product categories, with instrumentation demanding field engineering support while software relies on remote updates and tiered subscription management.
- DNA Sequencers:Capital equipment generating contiguous reads exceeding 10 kilobases through single-molecule detection optics. Demand concentrates at NIH-funded academic medical centers in the United States where precision medicine initiatives mandate high-throughput infrastructure.
- RNA Sequencers:Platforms optimized for full-length transcript isoform resolution and direct RNA sequencing without reverse transcription artifacts. Pharmaceutical toxicology groups in Germany and Japan deploy these systems for preclinical biomarker discovery where isoform-level quantification determines regulatory submission quality.
- Accessories:Flow cells, library preparation kits, and consumable cartridges with compressed replacement cycles relative to instrument lifespans.
- Software:Basecalling algorithms, assembly pipelines, and variant interpretation modules delivered through cloud or on-premise licensing.
By volume, DNA Sequencers leads. By growth pace, Software is expanding most quickly.
Technology:
Cost tier differentiation separates premium single-molecule platforms from emerging synthetic approaches that sacrifice read length for capital accessibility.
- Single-Molecule Real-Time:Zero-mode waveguide detection enabling simultaneous observation of DNA polymerase activity with HiFi accuracy thresholds. Clinical laboratories in California and Massachusetts adopt these systems for structural variant confirmation in oncology diagnostics where indel resolution determines therapeutic selection.
- Nanopore Sequencing:Protein nanopore-based strand translocation delivering real-time signal acquisition with minimal capital requirements. Infectious disease surveillance networks in Nigeria and Kenya deploy portable devices for field-based pathogen characterization where laboratory infrastructure remains absent.
- Synthetic Long Reads:Short-read assembly-based approaches generating pseudo-long contiguous sequences through barcoding and computational reconstruction.
- Others:Emerging modalities including circular consensus sequencing adaptations and hybridization-based long-range mapping technologies.
By installed base, Nanopore Sequencing leads. By revenue per run, Single-Molecule Real-Time commands premium positioning.
End User:
Customer type determines procurement complexity, with pharmaceutical buyers demanding validated workflows and academic purchasers prioritizing publication flexibility over regulatory documentation.
- Academic Research Institutes:Core facilities and departmental laboratories constituting the dominant installed base with fragmented purchasing authority across principal investigators. Max Planck Institutes in Germany and RIKEN centers in Japan anchor regional demand for de novo genome assembly applications.
- Clinical Laboratories:CAP-accredited and CLIA-certified operations emerging as the fastest-expanding customer segment. United States-based reference laboratories in Texas and North Carolina build long read capacity ahead of anticipated CMS reimbursement determinations for oncology companion diagnostics.
- Pharmaceutical Companies:Integrated drug discovery and toxicology operations with centralized procurement and stringent vendor qualification requirements.
- Biotechnology Firms:Venture-backed developers of cell therapies and gene editing platforms with concentrated demand for off-target detection and clonal validation.
By unit shipments, Academic Research Institutes leads. By average selling price, Pharmaceutical Companies drives premium configuration uptake.
Application:
Application maturity varies from established oncology research workflows to nascent agricultural deployment where regulatory frameworks remain undefined across major jurisdictions.
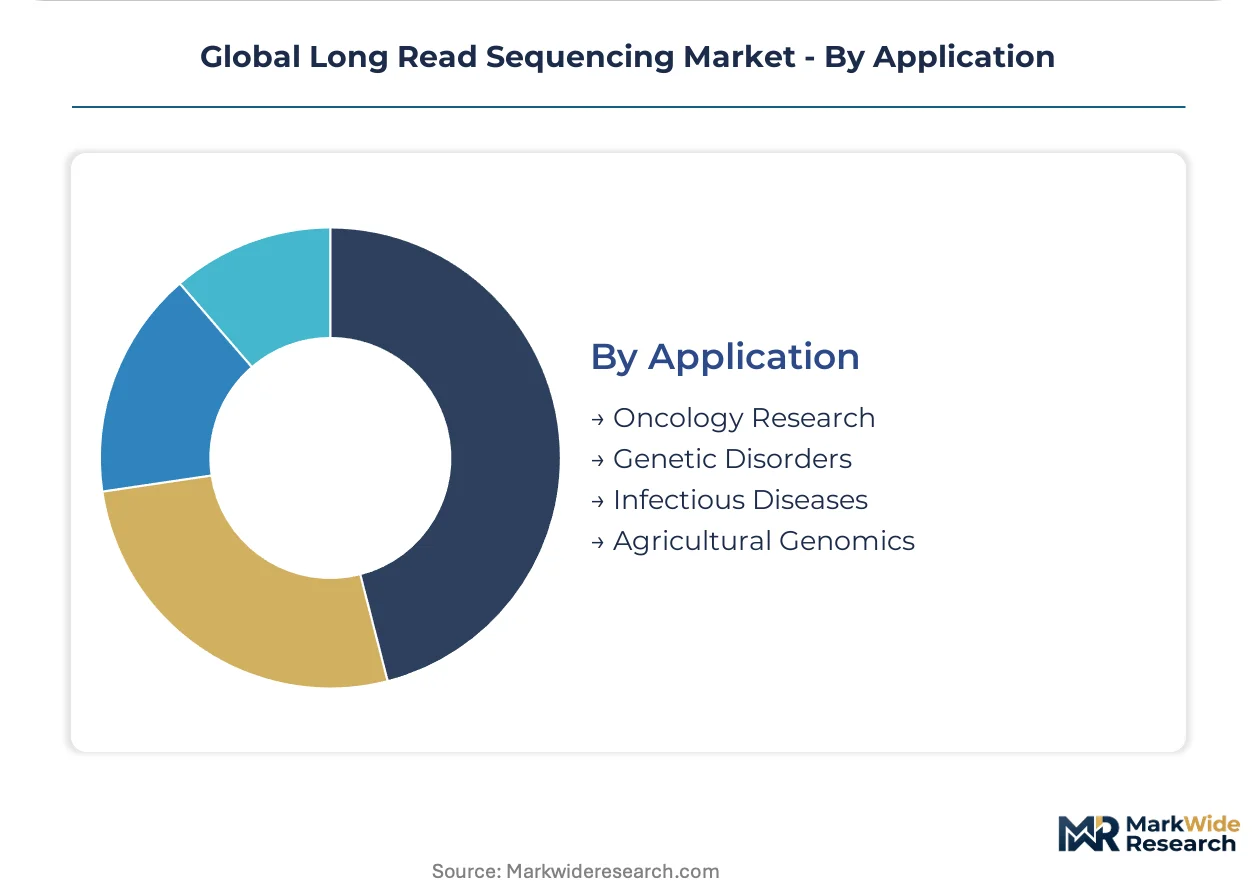
- Oncology Research:Structural variant detection, fusion gene identification, and tumor heterogeneity characterization through phased mutation analysis. Comprehensive cancer centers at MD Anderson and Memorial Sloan Kettering in the United States concentrate demand for circulating tumor DNA long read profiling.
- Genetic Disorders:Rare disease diagnosis through pathogenic variant resolution in repetitive and segmental duplication regions inaccessible to short-read platforms. Clinical genetics services at Great Ormond Street Hospital in the United Kingdom and Karolinska Institutet in Sweden deploy these capabilities for unresolved exome-negative cases.
- Infectious Diseases:Real-time pathogen surveillance, antimicrobial resistance gene mapping, and outbreak source tracing.
- Agricultural Genomics:Crop and livestock breeding applications including complex trait mapping and pangenome construction for diversity panels.
By current revenue, Oncology Research leads. By expansion trajectory, Infectious Diseases is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical component suppliers for DNA sequencers cluster in East Asian precision electronics manufacturing hubs, creating geographic interdependence between hardware assembly and downstream platform deployment. This concentration shapes regional market access patterns and regulatory compliance sequencing across major jurisdictions.
United States
NIH precision medicine initiatives channel federal funding toward academic medical centers in California and Massachusetts, expanding installed base capacity for high-throughput systems. FDA guidance on next-generation sequencing-based oncology diagnostics compresses clinical validation timelines for platform manufacturers. Comprehensive cancer centers at MD Anderson in Texas and Memorial Sloan Kettering in New York concentrate demand for circulating tumor DNA profiling applications.
Germany
Max Planck Institutes anchor regional demand for de novo genome assembly workflows, while pharmaceutical toxicology groups in Baden-Württemberg deploy full-length transcript isoform resolution systems. EMA In Vitro Diagnostic Regulation imposes post-market surveillance obligations that parallel pharmaceutical product vigilance requirements. Clinical laboratories in Berlin and Munich consolidate vendor relationships to reduce compliance documentation burden across instrument fleets.
China
BGI Genomics and domestic sequencing service providers scale manufacturing capacity for consumable cartridges and flow cell production. NMPA regulatory frameworks for genomic testing standards create parallel compliance pathways for platform certification. Research institutes in Beijing and Shenzhen prioritize cost-per-run economics in procurement decisions for population-scale genomics projects.
United Kingdom
Academic core facilities migrate toward per-run pricing arrangements with external service providers rather than capital ownership. Clinical genetics services at Great Ormond Street Hospital deploy long read capabilities for unresolved exome-negative rare disease cases. Frozen block grant funding mechanisms constrain capital allocation at research institutes in Cambridge and Oxford, accelerating service-based procurement models.
Japan
RIKEN centers anchor demand for structural variant detection in neurodegenerative disease studies, while pharmaceutical companies in Kansai region integrate long read platforms into preclinical toxicology workflows. PMDA guidance on genomic testing standards shapes product development roadmaps for manufacturers seeking market access. Reference laboratories in Tokyo build capacity ahead of anticipated reimbursement framework maturation for diagnostic applications.
Global Long Read Sequencing Market Key Industry Players
Single-molecule detection specialists and portable device manufacturers split the market between premium accuracy positioning and field-deployment accessibility. The vendor landscape organizes around chemistry-anchored platform ecosystems versus minimal-capital sequencing modalities. Two strategic archetypes dominate: integrated hardware-consumable vendors capturing recurring revenue through reagent lock-in, and modular platform providers enabling third-party bioinformatics integration. Competitive intensity concentrates on M&A activity targeting bioinformatics workflow capabilities and strategic partnerships with pharmaceutical toxicology groups.
Within the integrated ecosystem tier, Pacific Biosciences and Oxford Nanopore Technologies occupy positions representing contrasting technical approaches to single-molecule detection. Element Biosciences exemplifies the cost-disruption archetype, challenging incumbent pricing structures in core research markets. Among diversified life science conglomerates, F. Hoffmann-La Roche Ltd. and Agilent Technologies, Inc. sit within broader analytical instrumentation portfolios that cross-subsidize sequencing platform development.
| Leading Market Players |
|---|
| Pacific Biosciences |
| Oxford Nanopore Technologies |
| Illumina Inc. |
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies, Inc. |
| Element Biosciences |
| BGI Genomics |
| Eurofins Genomics |
| New England Biolabs |
| Others |
Cost & Logistics Intelligence
East Asian precision electronics clusters concentrate optical component manufacturing for DNA sequencers, anchoring margin pools in consumable chemistry and bioinformatics software licensing downstream. HiFi reagent kits and flow cell cartridges command recurring revenue premiums that offset hardware capital intensity, while nanopore modalities disrupt through minimal-instrument economics.
Pricing Analysis
FDA guidance on next-generation sequencing-based oncology diagnostics dictates the pricing tier structure across clinical-grade and research-grade configurations. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited laboratories from academic core facilities and field-deployed surveillance networks. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard tier intensifies because Element Biosciences and emerging synthetic long read providers undercut incumbent consumable pricing. Academic research institutes exhibit highest price sensitivity, while pharmaceutical toxicology groups absorb premium positioning for validated workflow documentation.
Supply Chain Analysis
Contract manufacturing capacity for zero-mode waveguide substrates and protein nanopore membranes concentrates with specialized semiconductor foundries in Taiwan, South Korea, and Japan. Optical detection modules and precision fluidics draw from Japanese and German component specialists. Single-source vulnerability pervades the flow cell polymer supply, where proprietary surface chemistry formulations remain captive to Pacific Biosciences and Oxford Nanopore internal manufacturing. Distribution runs through direct field service organizations for clinical installations and distributor networks for research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA premarket submission requirements and EMA In Vitro Diagnostic Regulation technical documentation create multi-year certification barriers that protect incumbent installed bases from displacement.
For Market Incumbents: Build switching-cost moats through deeper integration into pharmaceutical toxicology workflows and CAP-accredited clinical laboratory LIMS systems. Pacific Biosciences and Oxford Nanopore should anchor backward integration into captive flow cell polymer production to neutralize supply vulnerability. Threat from synthetic long read and cost-disruption entrants like Element Biosciences demands accelerated per-run pricing innovation for budget-constrained academic segments. For New Entrants and Emerging Players: Pursue white-space penetration in infectious disease surveillance networks across Nigeria, Kenya, and sub-Saharan African countries lacking centralized laboratory infrastructure. Field-deployable nanopore modalities represent the most penetrable application corridor. Go-to-market positioning should emphasize minimal-capital deployment and real-time pathogen characterization capabilities against incumbent high-throughput systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed bioinformatics workflow developers holding FDA-aligned variant interpretation modules. Long-term viability over the five-to-ten year horizon rests on CMS reimbursement determinations for oncology companion diagnostics converting clinical demand to sustainable revenue. Signal to watch is coverage policy publication for structural variant detection assays.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Partnership | FDA submission alignment with MD Anderson and Memorial Sloan Kettering accelerates companion diagnostic pathway. |
| Bioinformatics Acquisition | Assembly pipeline and basecalling algorithm capabilities compress time-to-interpretation for clinical laboratories. |
| Consumable Manufacturing Scale-Up | Flow cell polymer production in East Asian clusters reduces cost-per-run exposure to supply disruption. |
| Field Deployment Network | Portable device distribution through Nigerian and Kenyan infectious disease surveillance extends addressable market. |
| Reimbursement Strategy Development | CMS coverage determination alignment unlocks sustainable clinical revenue at Texas and North Carolina reference laboratories. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with platform manufacturers, clinical laboratory directors, and pharmaceutical toxicology executives; and secondary validation through FDA 510(k) filings, EMA technical documentation, ClinicalTrials.gov oncology sequencing protocols, and NIH precision medicine initiative budget disclosures. Bottom-up triangulation across instrument shipment data, consumable revenue recognition patterns, and bioinformatics licensing flows converged with top-down market sizing across the analysis window.
Forecast inputs considered technology modality segmentation, end-user procurement authority concentration, and application maturity curves across oncology research, genetic disorders, infectious diseases, and agricultural genomics. CAGRs were derived from installed base expansion modeling and replacement cycle compression assumptions. Structural variant detection reimbursement trajectories and epigenetic characterization workflow adoption patterns served as industry-specific demand drivers throughout the projection horizon.
Sensitivities concentrate around FDA guidance evolution on next-generation sequencing-based oncology diagnostics, CMS coverage determination timing, and EMA post-market surveillance obligation implementation. Forecasts reflect assumptions on regulatory pathway standardization and consumable cost compression rates. Quarterly review of NIH funding allocation patterns, pharmaceutical toxicology group platform integration announcements, and NMPA certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Kearns-Sayre Syndrome Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Agrigenomics Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Global NGS Sample Preparation Market
Genomics
United States Cancer Biomarkers Market
Genomics
Global Digital PCR Market
Genomics
AI in Genomics Market
Genomics
Global Genotyping Assay Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Microarray Scanners Market
Genomics
Global Lab Automation in Genomics Market