
 On-Board Charger Market | 2026-2036
On-Board Charger Market Size, Share, and Industry Trends Forecast 2026-2036
On-Board Charger Market Intelligence
The EU F-Gas Regulation is realigning thermal management costs for onboard charger suppliers. BorgWarner Inc. leverages its power electronics integration to sustain margin on high-voltage platforms. Hyundai Mobis Co., Ltd. anchors Korean OEM supply chains through captive design-to-manufacture capabilities. Delta Electronics, Inc. competes across AC and bidirectional segments with tier-one certification depth.
An onboard charger converts grid AC power to DC for battery storage, typically operating at 3.3 kW to 22 kW with power factor correction and galvanic isolation as core functional parameters. Bidirectional charger architectures enable vehicle-to-grid energy return, a capability that commands premium positioning as utility participation models mature. Fast Charging speed tiers now dominate OEM specification sheets, while Level 1 residential units face margin compression from commoditization. Electric Vehicles as an end user category absorbs the majority of volume, though Commercial Fleets represent a concentrated margin pool due to durability and warranty requirements.
EMA's MDR framework and REACH chemical restrictions shape material selection for European-sourced units, while China's GB standards and MIIT certification govern access to the world's largest EV production base. The US NHTSA and EPA jointly influence onboard charger safety and efficiency benchmarks through Federal Motor Vehicle Safety Standards and emissions-linked compliance pathways. Stakeholders must monitor harmonization gaps between regional charging protocols and thermal refrigerant phase-down schedules.
Market Dynamics
Electric vehicle manufacturers are scaling procurement of higher-kilowatt onboard units to support faster AC-to-DC conversion, creating a structural pull toward integrated power electronics and advanced thermal architectures.
Growth Catalysts
- GB/T charging interface standards:China's MIIT certification mandates are accelerating domestic OEM adoption of domestically certified onboard charger platforms, locking in supplier relationships for export-capable manufacturers.
- Fleet electrification mandates:Commercial fleet operators across Germany, France, and the Netherlands are specifying 22 kW units with extended warranty terms, concentrating demand in the high-reliability tier.
- Silicon carbide (SiC) power semiconductors:This material substitution is enabling higher switching frequencies and reduced thermal losses, allowing suppliers to compress converter volume by 30-40 percent.
Market Restraints
- Copper and rare earth magnet cost volatility:Input price swings for winding materials and permanent magnet components are compressing gross margins on 6.6 kW and 11 kW platforms.
- Supply concentration in East Asian power semiconductor foundries:Foundry capacity constraints for high-voltage MOSFETs and IGBTs are extending lead times for European and North American charger integrators.
- Technical limitation in bidirectional grid synchronization:Vehicle-to-grid certification complexity under IEEE 1547 and local utility interconnection rules is delaying commercial rollout of two-way capable units.
Strategic Opportunities
- Underpenetrated commercial vehicle segment:Medium-duty truck and bus platforms in India and Southeast Asia remain specification-light, offering first-mover positioning for 22 kW liquid-cooled architectures.
- EU F-Gas Regulation phase-down:The refrigerant transition timeline is creating replacement demand for thermal management subsystems, opening retrofit and upgrade revenue streams.
- Technology convergence of onboard charging and DC-DC conversion:Integrated power electronics modules that combine AC-DC and high-voltage-to-low-voltage functions are capturing BOM reduction value.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized skill in magnetics design and EMC compliance is concentrated among a small pool of experienced practitioners, inflating recruitment costs.
- Multi-jurisdiction certification timeline compression:Simultaneous pursuit of UL 2202, IEC 61851, and GB/T compliance is stretching validation resources and delaying program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Board Charger Market |
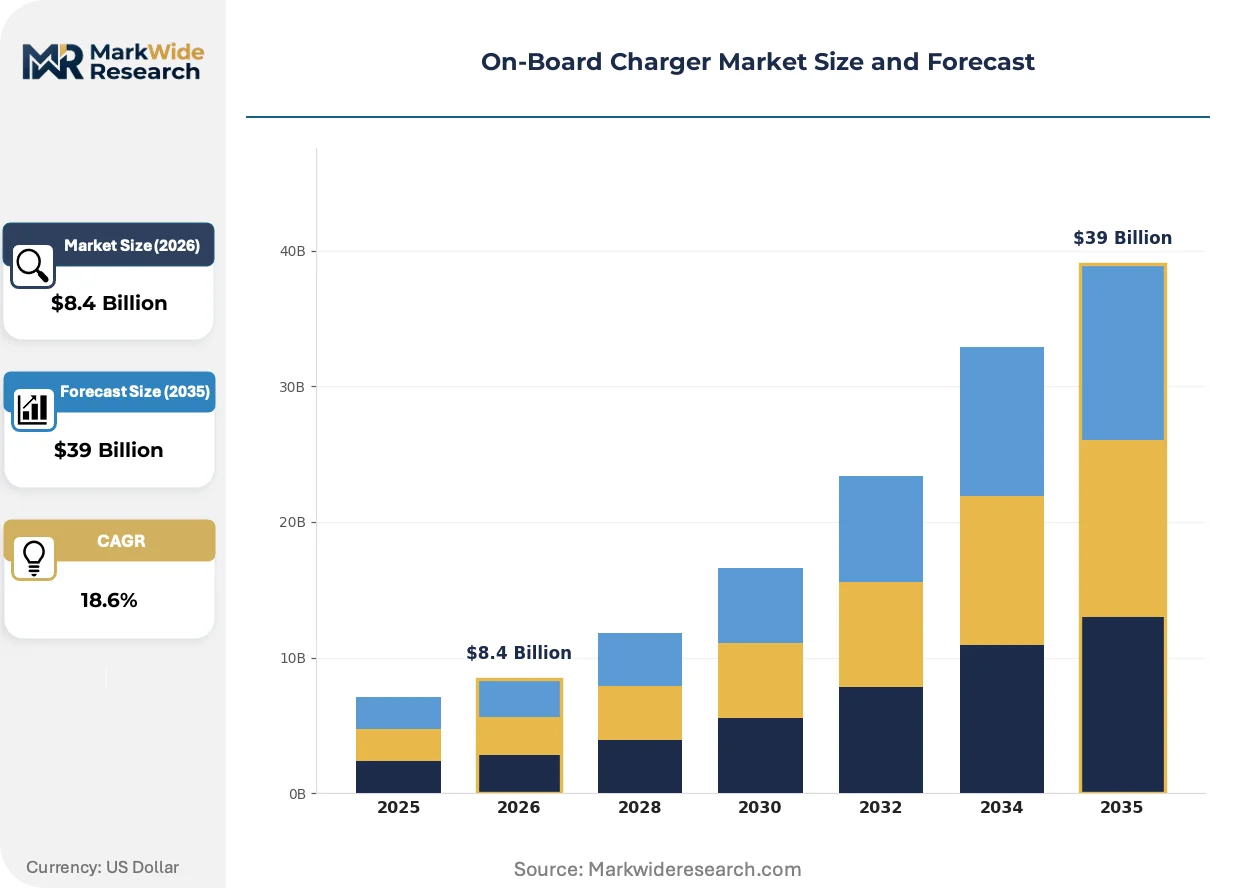
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Charger, DC Charger, Bidirectional Charger, Portable Charger Charging Speed: Level 1, Level 2, Fast Charging, Ultra-Fast Charging End User: Electric Vehicles, Hybrid Vehicles, Commercial Fleets, Residential Users Installation Type: Wall-Mounted, Portable, Onboard, Networked Charging Stations |
| Companies Covered | BorgWarner Inc., Hyundai Mobis Co., Ltd., LG Electronics, Valeo SE, Delta Electronics, Inc., Ficosa International S.A, Bel Fuse Inc., STMicroelectronics, Toyota Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Board Charger Market Strategic Shifts & Innovations
Silicon carbide semiconductors, regulatory pressure on refrigerants, and fleet procurement centralization are converging to reshape product specifications and supplier selection criteria across the onboard charger value chain.
Silicon carbide MOSFETs are replacing silicon IGBTs in 11 kW and 22 kW converter stages, enabling higher efficiency at elevated switching frequencies. European premium OEMs and Korean mass-market producers are adopting SiC-based designs for 2027-2028 vehicle platforms. This transition is absorbing engineering resources from legacy silicon programs and compressing the viable supply base to semiconductor houses with automotive-qualified SiC capacity.
The EU F-Gas Regulation is mandating phased reduction of hydrofluorocarbon refrigerants in thermal management circuits. Charger suppliers must redesign cold plates and heat exchangers to accommodate lower-global-warming-potential alternatives. German and French automotive supplier corridors are experiencing the tightest compliance timelines, with Tier-1 integrators accelerating qualification of CO2-based cooling subsystems.
Fleet procurement centralization is consolidating specification authority among a smaller set of commercial vehicle operators with dedicated electrification teams. These buyers are unbundling charger supply from vehicle purchase, issuing standalone RFQs with 8-10 year durability requirements. The shift is most visible in Germany's logistics hub cities and the Netherlands' port-connected distribution networks, where total-cost-of-ownership modeling dominates supplier selection.
On-Board Charger Market Segmentation
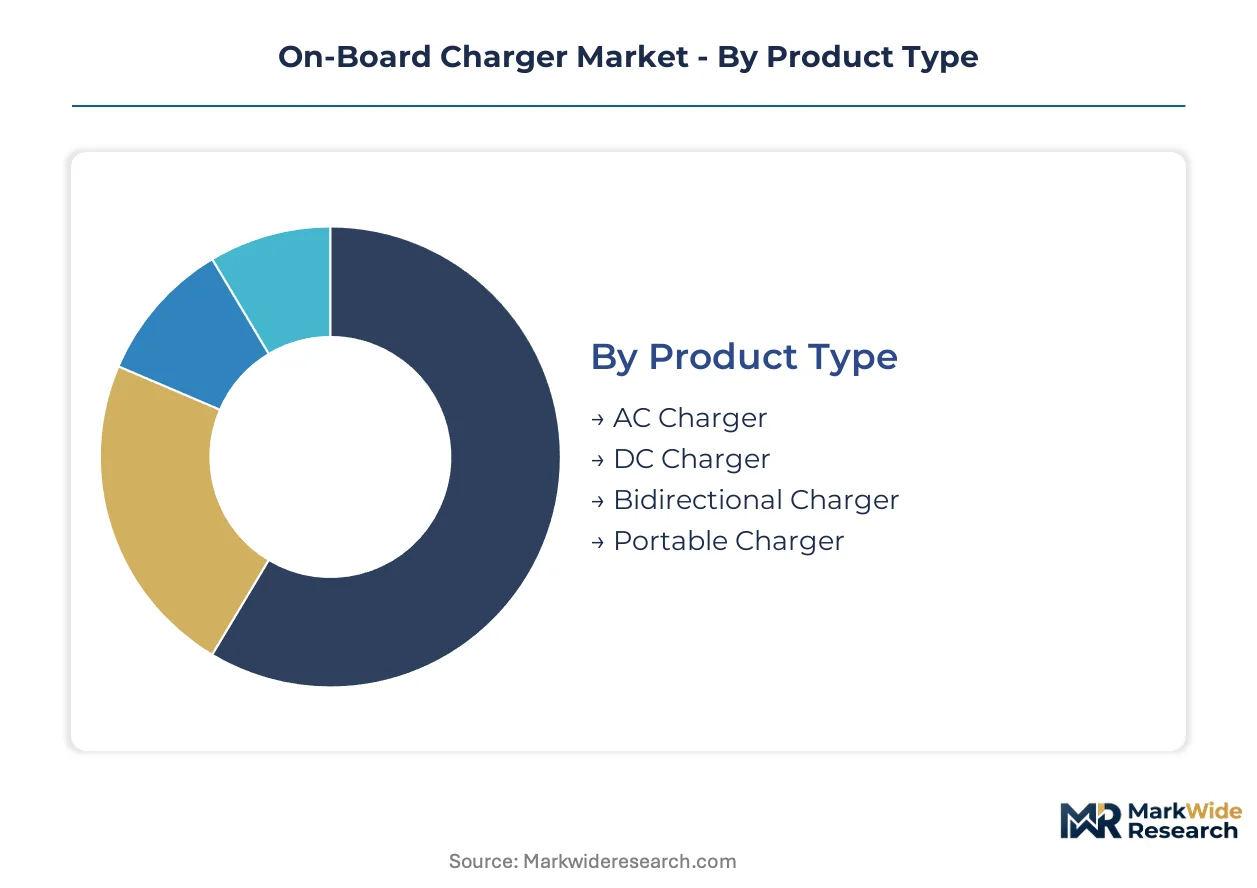
On-board charger procurement patterns diverge sharply between passenger OEMs optimizing for unit cost and fleet operators prioritizing durability. Specification authority concentrates with vehicle manufacturers for integrated units, while aftermarket channels serve replacement demand. Understanding these splits enables suppliers to align R&D investment with margin structure.
Product Type:
AC chargers dominate unit volume, while bidirectional architectures capture premium positioning through grid-interactive capabilities.
- AC Charger:Converts grid alternating current to battery direct current at 3.3 kW to 22 kW ratings. Chinese OEMs in Shenzhen and Guangzhou specify these for mass-market electric sedans under GB/T certification mandates.
- DC Charger:Handles direct current input from external fast-charging infrastructure, requiring robust power conditioning. Demand clusters with German premium manufacturers integrating 800-volt architectures around Stuttgart.
- Bidirectional Charger:Enables vehicle-to-grid energy return through two-way power flow. IEEE 1547 certification complexity delays rollout, though Dutch fleet operators pilot commercial deployments.
- Portable Charger:Detachable units for emergency or travel use with lower power ratings. Residential users in Japan and South Korea adopt these for supplemental charging flexibility.
Mature deployment sits with AC Charger. Newer deployment is concentrated in Bidirectional Charger.
Charging Speed:
Speed tier selection directly correlates with battery capacity and dwell-time economics across use cases.
- Level 1:120-volt residential charging at 1.4 kW to 1.9 kW using standard outlets. North American home garages represent the primary installation base, though long charge cycles limit appeal.
- Level 2:240-volt infrastructure delivering 3.3 kW to 19.2 kW for overnight or workplace charging. Workplace installations in France and Germany specify these for employee fleet programs.
- Fast Charging:22 kW to 50 kW AC-to-DC conversion for reduced dwell times. European commercial fleet depots in Rotterdam and Hamburg mandate these for logistics vehicle turnaround.
- Ultra-Fast Charging:Exceeds 50 kW with specialized thermal management requirements. Korean OEM platforms target this tier for premium SUV segments with large battery packs.
Volume concentrates in Level 2. Margin expansion is fastest in Ultra-Fast Charging.
End User:
Customer type determines warranty terms, durability specifications, and procurement channel structure.
- Electric Vehicles:Battery-electric platforms requiring onboard AC-DC conversion for every charging event. German and Chinese OEMs integrate 11 kW units as baseline specification for new passenger models.
- Hybrid Vehicles:Smaller battery capacities enable lower-power charger integration. Japanese manufacturers specify 3.3 kW units for plug-in hybrid architectures to manage cost and packaging.
- Commercial Fleets:Centralized procurement with 8-10 year durability requirements and unbundled RFQs. Dutch distribution networks and German logistics hubs drive specification for 22 kW liquid-cooled units.
- Residential Users:Individual consumers selecting replacement or upgrade chargers for existing vehicles. Aftermarket sales concentrate through automotive retail channels in the US and Europe.
Procurement standardization sits with Electric Vehicles. Specification unbundling is advancing in Commercial Fleets.
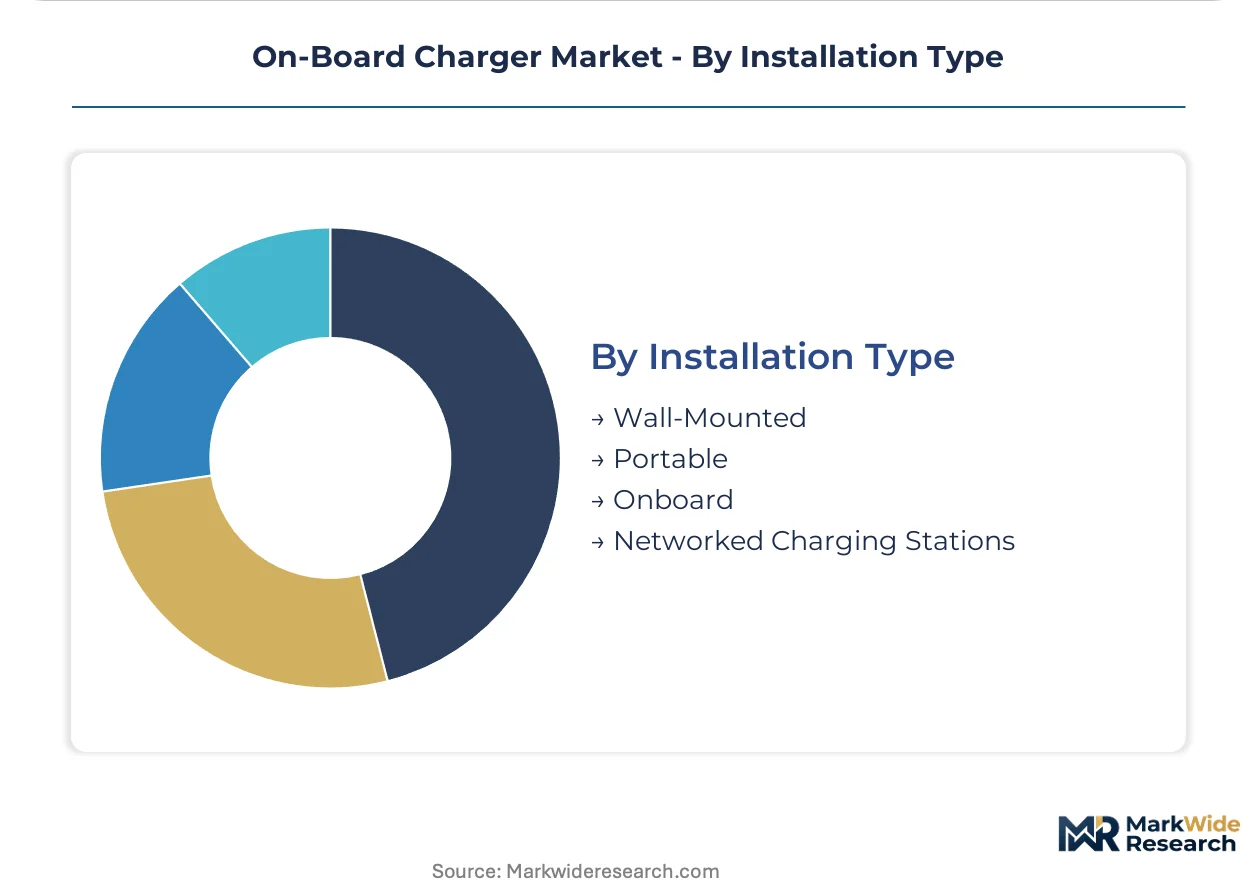
Installation Type:
Physical integration depth shapes supplier relationships and replacement economics.
- Wall-Mounted:Fixed external units for residential or commercial garage installation. US residential construction standards increasingly pre-wire for these in new single-family homes.
- Portable:Detachable units stored in-vehicle for opportunistic charging. Southeast Asian markets favor these for infrastructure-gap coverage in Indonesia and Vietnam.
- Onboard:Factory-integrated chargers within the vehicle powertrain. OEM captive supply chains dominate this segment, with BorgWarner and Hyundai Mobis holding tier-one positions.
- Networked Charging Stations:Grid-connected systems with remote monitoring and load management. Smart city deployments in Singapore and Barcelona prioritize these for public infrastructure.
Integration depth peaks with Onboard. Infrastructure flexibility is expanding fastest in Networked Charging Stations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-certified special economic zones around Shenzhen and Guangzhou concentrate EV component manufacturing, pulling supplier investment toward GB/T-compliant production hubs.
China
Domestic OEMs in Shenzhen and Guangzhou specify 11 kW and 22 kW units under MIIT certification mandates. GB/T charging interface standards lock supplier relationships for export-capable manufacturers. The Pearl River Delta hosts concentrated production of silicon carbide power modules for next-generation platforms.
Germany
Premium manufacturers around Stuttgart integrate 800-volt architectures requiring advanced thermal management. The EU F-Gas Regulation accelerates redesign of cold plates and heat exchangers for lower-GWP refrigerants. Munich's automotive supplier corridor anchors development of liquid-cooled 22 kW units for commercial fleet deployment.
United States
Workplace charging installations in California and Texas specify Level 2 units for employee fleet programs. NHTSA and EPA jointly influence safety and efficiency benchmarks through Federal Motor Vehicle Safety Standards. Detroit's engineering centers drive integration of bidirectional chargers for vehicle-to-grid pilot programs.
South Korea
Mass-market producers adopt silicon carbide-based designs for 2027-2028 vehicle platforms. Korean OEM supply chains rely on captive design-to-manufacture capabilities for high-voltage platforms. Seoul's power electronics cluster concentrates SiC MOSFET qualification resources for automotive applications.
Netherlands
Distribution networks in Rotterdam and port-connected logistics hubs mandate 22 kW fast-charging for vehicle turnaround. Fleet operators issue standalone RFQs with 8-10 year durability requirements unbundled from vehicle purchase. Dutch utility participation models pilot commercial vehicle-to-grid deployments.
On-Board Charger Market Key Industry Players
German and French tier-one integrators anchor one tier; East Asian electronics specialists hold scale positions in power semiconductor integration. The market structures around three strategic archetypes: automotive supplier conglomerates with captive power electronics divisions, independent charger specialists with tier-one certification depth, and semiconductor houses with automotive-qualified silicon carbide capacity. Competitive moves concentrate on backward integration into magnetics manufacturing and geographic expansion through MIIT certification partnerships in China.
Among automotive supplier conglomerates, BorgWarner Inc. and Hyundai Mobis Co., Ltd. occupy positions exemplifying integrated power electronics capabilities. Delta Electronics, Inc. sits within the tier-one certification tier. These anchors represent the dominant competitive vectors: captive supply chain control for Korean and German OEM programs, and cross-segment certification spanning AC and bidirectional charger architectures.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hyundai Mobis Co., Ltd. |
| LG Electronics |
| Valeo SE |
| Delta Electronics, Inc. |
| Ficosa International S.A |
| Bel Fuse Inc. |
| STMicroelectronics |
| Toyota Industries Corporation |
| Others |
Cost & Logistics Intelligence
Captive design-to-manufacture capabilities anchor Korean and German tier-one suppliers in premium pricing positions while commoditized 3.3 kW platforms face margin compression from outsourced Asian production. This integration choice concentrates pricing power with semiconductor-qualified integrators and squeezes independent specialists dependent on spot magnetics procurement.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to SiC MOSFET-qualified 22 kW units as foundry capacity constraints extend delivery schedules for European and North American integrators. Three-tier pricing structure across premium bidirectional, standard 11 kW, and economy 3.3 kW levels reflects certification depth and thermal architecture complexity. Pricing pressure stems from copper and rare earth magnet cost volatility compressing gross margins on mid-tier platforms. Commercial fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership modeling, while residential aftermarket buyers drive spot-market discounting.
Supply Chain Analysis
Dual-sourcing requirements from German premium OEMs mandate multi-supplier qualification for silicon carbide power modules and magnetics assemblies, fragmenting procurement across qualified vendors. Manufacturing concentrates in China for GB/T-certified platforms, South Korea for captive OEM supply, and Germany for 800-volt thermal management subsystems. Raw material dependencies center on copper windings, neodymium permanent magnets, and high-purity silicon carbide substrates. Single-source vulnerability in East Asian semiconductor foundries threatens supply continuity for 11 kW and 22 kW converter programs. Distribution runs through tier-one automotive supplier corridors with direct OEM integration dominating volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around semiconductor-integrated power electronics specialists as multi-jurisdiction certification timelines and SiC capacity scarcity force weaker magnetics-dependent players toward exit.
For Market Incumbents: Deepen backward integration into automotive-qualified SiC sourcing through foundry partnerships or captive wafer capacity commitments to defend against semiconductor house forward-integration. Lock in 8-10 year fleet supply contracts with Dutch and German logistics operators before bidirectional certification complexity opens entry points for systems-integrator challengers. For New Entrants and Emerging Players: The mid-tier 6.6 kW to 11 kW price-point gap between premium liquid-cooled architectures and economy air-cooled units offers white-space positioning for India and Southeast Asian commercial vehicle platforms still specification-light on durability requirements. Target medium-duty truck retrofit programs with 22 kW liquid-cooled architectures and local assembly partnerships to bypass tier-one certification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by automotive supplier conglomerates seeking power electronics integration depth, with Korean and German OEM captive units as primary acquirer archetypes. Five-to-ten year viability favors semiconductor-qualified integrators with MIIT certification and GB/T platform experience. Watch SiC foundry capacity expansion announcements as inflection signal for margin compression timing in premium converter tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures automotive-qualified MOSFET supply for 22 kW platform ramps amid East Asian capacity constraints. |
| MIIT Certification Acceleration | Unlocks access to Shenzhen and Guangzhou OEM supply chains under GB/T charging interface mandates. |
| Liquid-Cooled Thermal Architecture Development | Addresses EU F-Gas Regulation phase-down timelines for lower-GWP refrigerant compliance in German premium segments. |
| Bidirectional Grid Synchronization Investment | Enables IEEE 1547-compliant vehicle-to-grid commercialization as Dutch utility participation models mature. |
| Fleet-First Specification Unbundling | Captures standalone RFQ opportunities from Rotterdam and Hamburg logistics operators with 8-10 year durability terms. |
Research Approach
Regulatory filings from NHTSA, EPA, and MIIT, automotive production databases, and tier-one supplier technical documentation formed the secondary backbone for market sizing and technology trend validation. Primary interviews with OEM platform engineers, Tier 1 procurement leads, power semiconductor foundry planning officers, and commercial fleet electrification managers supplied forward-looking specification and adoption intelligence. Bottom-up unit shipment estimates by power rating and vehicle class triangulated against top-down EV production forecasts across the analysis window.
Historical trendline analysis of onboard charger content per vehicle tracked adoption curves from 3.3 kW baseline through 11 kW mainstream and 22 kW premium penetration. Segmentation modeling incorporated power rating tier, propulsion architecture, thermal management approach, bidirectional capability, and regional regulatory cluster. CAGRs derived from slope analysis of technology substitution curves and fleet procurement cycle timing. Forecast inputs included silicon carbide cost-down trajectories, GB/T certification mandate rollout schedules, and EU F-Gas Regulation compliance timelines.
Inputs from OEM product planning disclosures and foundry capacity announcements were available through the study window; gaps in pre-2027 vehicle platform specification finalization introduce uncertainty bands around bidirectional adoption rates. Forecasts reflect assumptions on semiconductor supply continuity, regulatory harmonization progress, and fleet operator total-cost-of-ownership model stability. A model refresh is warranted upon material change in SiC foundry capacity allocation or IEEE 1547 certification timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market