
 Global Automotive Electrical Distribution System Market | 2026-2036
Global Automotive Electrical Distribution System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Electrical Distribution System Market Intelligence
Mexico's expanding role in automotive assembly is tilting the supply chain for electrical harnesses and components toward North American production hubs. Yazaki Corporation leverages its extensive manufacturing footprint in the region to serve major OEMs. Lear Corporation sustains its market position through deep integration with vehicle platforms. Aptiv PLC competes by specializing in high-voltage and active safety system architectures, catering to the growing complexity of modern vehicles.
An automotive electrical distribution system comprises the network of wiring, connectors, and protection devices that manage power and data flow within a vehicle. These systems are engineered to handle voltages ranging from standard 12V circuits to over 800V in modern electric vehicle architectures. Wiring Harnesses constitute the largest product segment by value, forming the backbone of the entire network. While Passenger Vehicles remain the dominant application, the Electric Vehicles category represents the fastest-growing segment due to its demand for complex, high-voltage components.
Regulatory mandates from bodies like the US EPA and China's MIIT, which promote electrification, directly influence system design complexity. Concurrently, material standards such as Europe's REACH regulation govern the composition of plastics and metals used in connectors and wiring insulation. Key stakeholders must now decide on architectures, balancing the cost benefits of centralized power distribution against the modularity of decentralized zonal systems.
Market Dynamics
The fundamental shift toward high-voltage electrical architectures, driven by electric and software-defined vehicles, is the central structural force governing the market. This transition necessitates a complete rethinking of power distribution, from basic wiring to sophisticated, software-managed zonal systems.
Growth Catalysts
- EV Mandates:Government policies, such as China's MIIT regulations promoting New Energy Vehicles, create non-negotiable demand for high-voltage harnesses, battery management system wiring, and DC-DC converters.
- 48-Volt Systems:The widespread adoption of 48V mild-hybrid architectures in internal combustion engine vehicles to meet emissions targets requires upgraded wiring, fuses, and power distribution components capable of handling higher power loads.
- Autonomous Driving Hardware:The proliferation of sensors, ECUs, and redundant power pathways for ADAS and autonomous driving functions dramatically increases the density and complexity of a vehicle's electrical distribution network.
Market Restraints
- Material Cost Volatility:System cost structures are highly sensitive to price fluctuations in core commodities, particularly copper for conductors and specialty polymers for high-voltage insulation, impacting supplier margins.
- Thermal Management Complexity:High-voltage systems generate significant heat, creating a technical barrier that requires advanced and costly thermal management solutions to ensure safety and component longevity, especially in compact designs.
- Supply Chain Concentration:A reliance on a limited number of specialized suppliers for high-voltage connectors and automotive-grade semiconductors creates potential bottlenecks and grants significant pricing power to those vendors.
Strategic Opportunities
- Zonal Architectures:The move toward decentralized zonal E/E architectures opens a significant opportunity for suppliers to offer integrated modules that combine power distribution, data processing, and actuator control in a single unit.
- Aluminum Wiring:Developing and validating high-performance aluminum wiring systems presents an opportunity to offer a lighter, cost-effective alternative to copper, particularly for high-voltage power cables in electric vehicles.
- Smart Fuses and Breakers:There is an underserved market for solid-state, intelligent circuit protection devices that can be controlled via software, enabling dynamic load management and improved diagnostics for EVs and advanced vehicles.
Industry Challenges
- High-Voltage Engineering Talent:A pronounced shortage of systems engineers with expertise in designing, validating, and integrating systems operating above 400V poses a significant operational constraint for both OEMs and Tier-1 suppliers.
- Legacy System Integration:Ensuring seamless interoperability and data communication between new high-voltage zonal architectures and existing 12V legacy systems within the same vehicle platform is a major integration challenge.
- Standardization Gaps:The absence of universal standards for components like high-voltage connectors and data protocols for zonal systems leads to design fragmentation, increasing development costs and limiting component interchangeability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Electrical Distribution System Market |
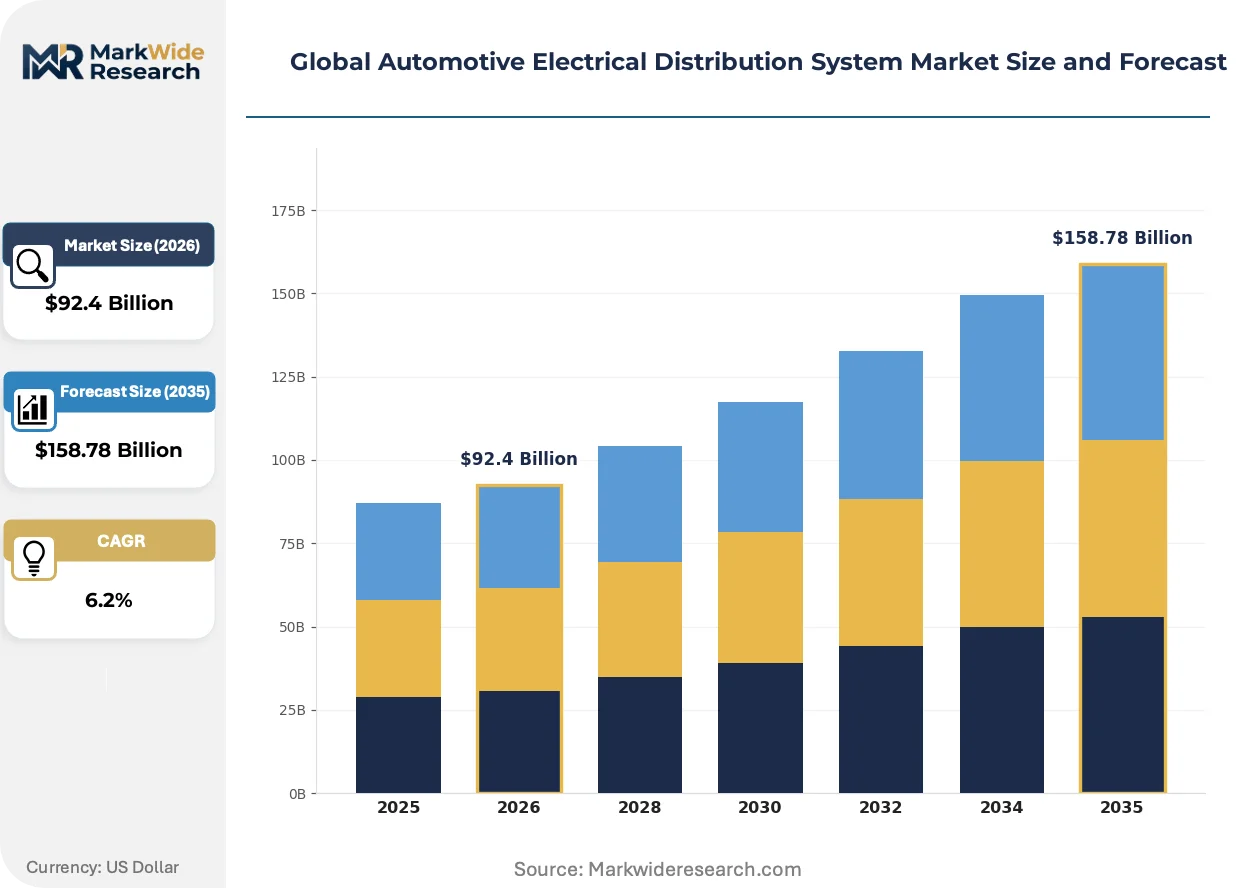
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wiring Harness, Fuse Box, Relay, Circuit Breaker, Connectors, Switches Technology: Passive Electrical Distribution, Active Electrical Distribution, Intelligent Power Distribution, Smart Wiring, Signal Transmission Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles, Autonomous Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Repair Shops |
| Companies Covered | Lear Corporation, Yazaki Corporation, Sumitomo Electric Industries, Aptiv PLC, Draexlmaier Group, Furukawa Electric, Eaton Corporation, Leoni AG, Littelfuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Electrical Distribution System Market Strategic Shifts & Innovations
The industry's architectural philosophy is undergoing a significant transformation, defined by the shift from centralized, component-based designs to decentralized, software-enabled systems. This evolution is driven by the need to manage the immense power and data requirements of modern vehicles.
Zonal architecture is a key technological evolution that decentralizes a vehicle's electrical system into physical zones, each with its own power and data hub. Premium electric vehicle manufacturers are the earliest adopters, integrating this approach to simplify wiring and enable over-the-air updates. As a result, the design paradigm is migrating from a single, complex wiring harness to a more logical, modular network resembling a server-on-wheels.
Europe's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory development. The directive compels large companies to provide detailed disclosures on supply chain sustainability, including material sourcing and carbon footprint. This directly impacts electrical system suppliers, who must now track and report the environmental lifecycle of copper, aluminum, and plastics, pushing the entire value chain toward greater transparency and circularity.
A notable behavioral shift is occurring in how OEMs source electrical systems, moving from transactional procurement to deep co-development partnerships with Tier-1 suppliers. This collaborative model replaces the traditional RFQ process for discrete components, especially for complex EV platforms. The trend is most visible in North American and European automotive clusters, where automakers rely on suppliers' systems-level expertise from the earliest stages of vehicle design.
Global Automotive Electrical Distribution System Market Segmentation
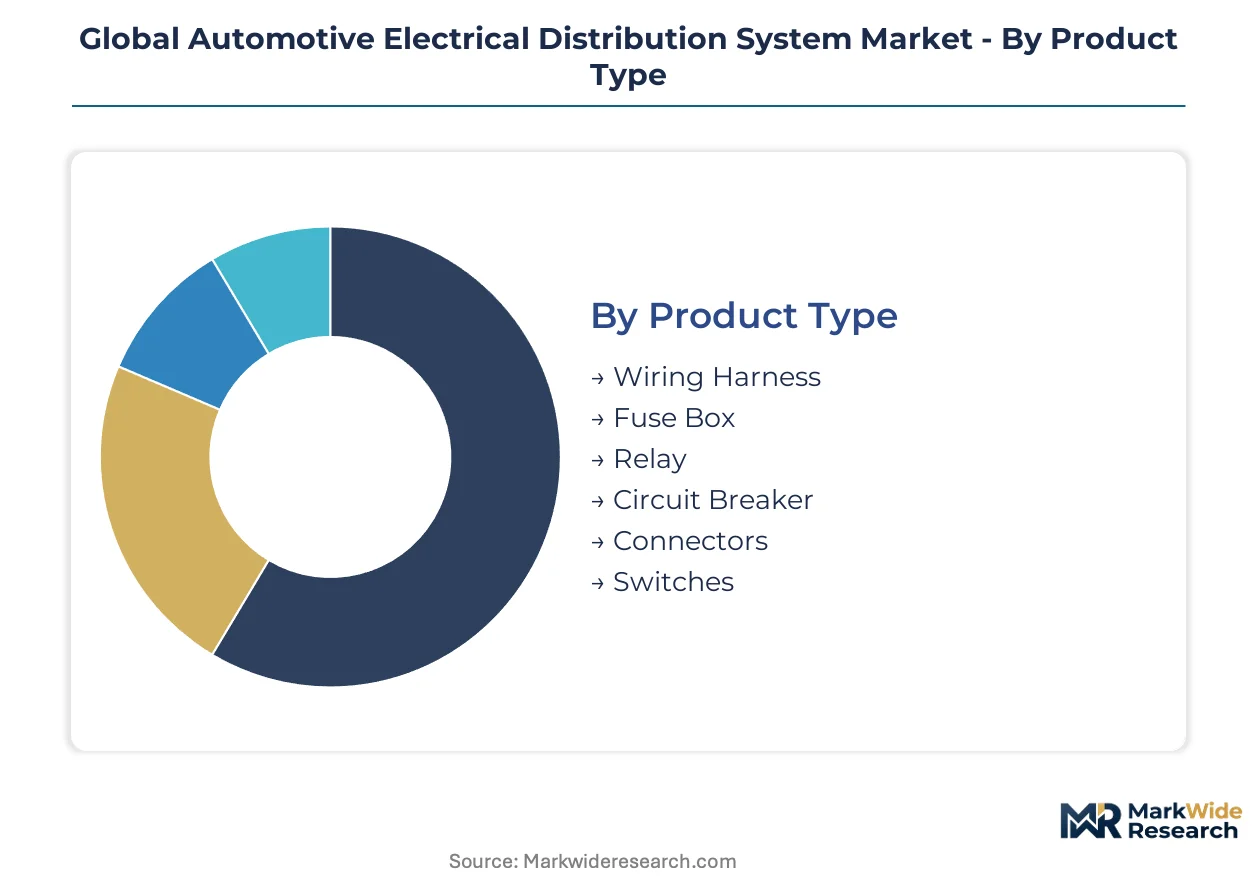
The global automotive electrical distribution system market is categorized to reflect the diverse components, technologies, and applications driving its evolution. Understanding these segments clarifies the varying demands placed on power and data management within modern vehicles. This segmentation highlights areas of significant investment and technological advancement across the industry.
Product Type:
The product type segmentation reveals the broad use-case spectrum for electrical distribution components, from fundamental power transmission to intricate data routing.
- Wiring Harness:Wiring harnesses form the foundational backbone, bundling numerous wires and cables to transmit power and signals throughout the vehicle. Demand concentrates in Electric Vehicles, where complex high-voltage requirements necessitate specialized, robust harness designs.
- Connectors:Connectors provide detachable junctions for electrical circuits, ensuring reliable power and data flow between vehicle modules. Their demand is intensifying in China and Europe, driven by the proliferation of advanced driver-assistance systems and high-voltage EV architectures.
- Fuse Box:Fuse boxes centralize circuit protection, housing fuses that prevent overcurrent damage to vehicle electrical systems.
- Relay:Relays act as electrical switches, allowing a low-power signal to control a higher-power circuit, essential for various vehicle functions.
- Circuit Breaker:Circuit breakers offer resettable protection against overcurrents, providing a durable alternative to single-use fuses in critical applications.
- Switches:Switches enable manual or automated control of electrical functions, ranging from simple cabin lights to complex system toggles.
Established volume favors Wiring Harnesses; emerging adoption favors Connectors, particularly for high-voltage applications.
Technology:
Technology segmentation reflects the maturity and sophistication of electrical distribution approaches, from basic power delivery to intelligent, software-defined systems.
- Intelligent Power Distribution:Intelligent power distribution systems use software and smart components to dynamically manage power flow, optimizing efficiency and enabling zonal architectures. Adoption is accelerating in premium electric vehicles across North America and Europe, driven by demand for advanced energy management.
- Active Electrical Distribution:Active electrical distribution employs electronic switches and controllers for real-time power routing and load balancing, enhancing reliability and flexibility. This technology finds increasing use in advanced driver-assistance systems within European and Asian vehicle platforms, supporting critical safety functions.
- Passive Electrical Distribution:Passive electrical distribution relies on conventional wiring, fuses, and relays, representing the traditional approach to power delivery.
- Smart Wiring:Smart wiring integrates sensors and communication capabilities directly into the wire, enabling data collection and localized control.
- Signal Transmission:Signal transmission encompasses the dedicated pathways and components for data communication between electronic control units.
Traditional vehicle platforms primarily utilize Passive Electrical Distribution, while Intelligent Power Distribution exhibits the steepest expansion trajectory due to electrification.
Application:
The application segmentation illustrates how different vehicle types dictate specific requirements for electrical distribution system complexity and power handling.
- Electric Vehicles:Electric Vehicles demand robust high-voltage electrical distribution systems, including specialized wiring, connectors, and DC-DC converters for battery management. Demand for these components is surging in China and Germany, reflecting strong government support for new energy vehicles.
- Passenger Vehicles:Passenger Vehicles represent the largest volume application, requiring a broad range of electrical distribution components for comfort, safety, and infotainment systems. The segment's scale in the United States and Japan drives continuous innovation in cost-effective and integrated solutions.
- Commercial Vehicles:Commercial Vehicles require durable electrical systems capable of supporting heavy-duty operations and specialized equipment.
- Hybrid Vehicles:Hybrid Vehicles integrate both internal combustion engines and electric powertrains, necessitating dual-voltage electrical architectures.
- Autonomous Vehicles:Autonomous Vehicles require highly redundant and complex electrical networks to power numerous sensors and critical decision-making ECUs.
Passenger Vehicles currently account for the largest share of electrical distribution system deployment, though Electric Vehicles are gaining share fastest.
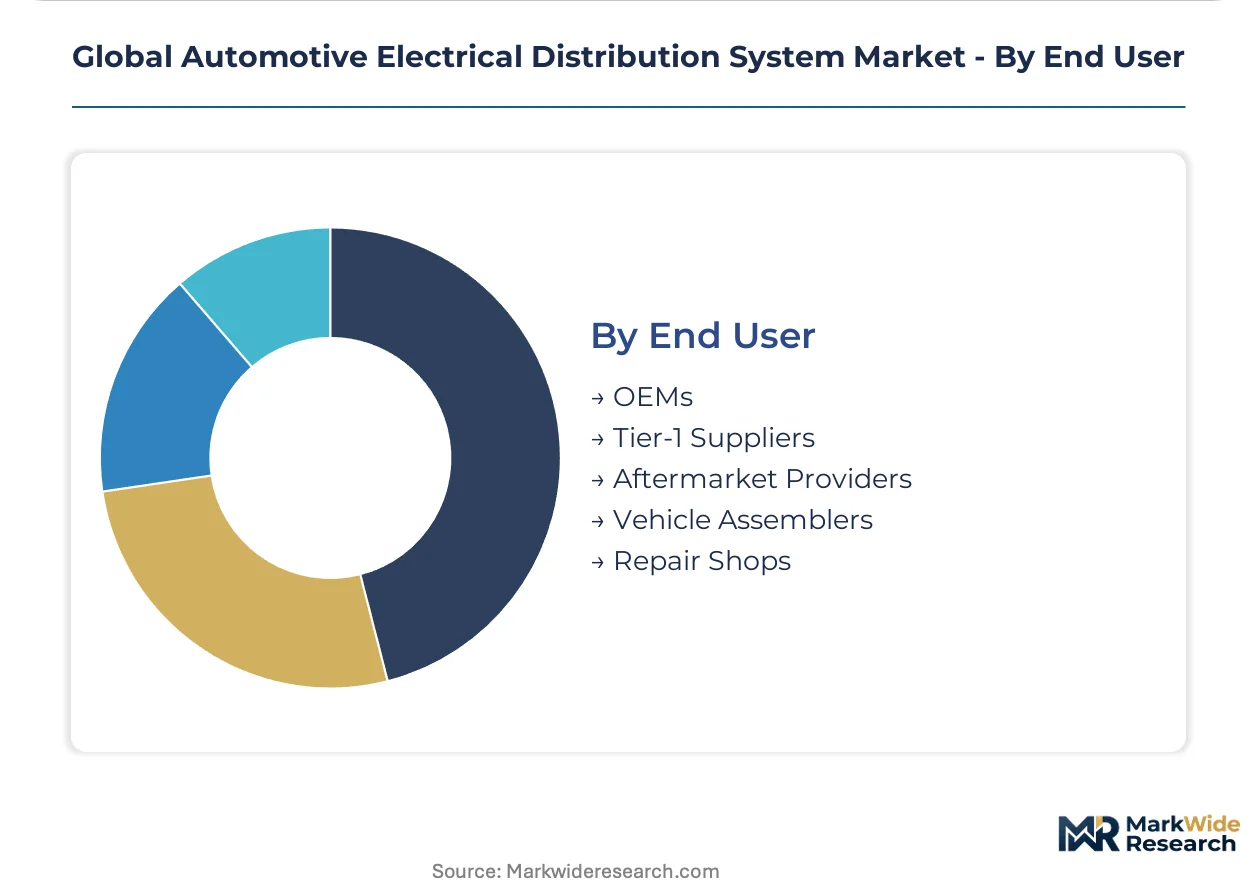
End User:
End-user segmentation highlights the varying points of supply concentration and integration within the automotive value chain for electrical distribution systems.
- OEMs:Original Equipment Manufacturers are the primary consumers, integrating electrical distribution systems directly into new vehicle designs during assembly. Automakers in North America and Europe increasingly engage in co-development partnerships with Tier-1 suppliers for complex EV platforms.
- Tier-1 Suppliers:Tier-1 Suppliers design and manufacture complete electrical distribution systems or major sub-assemblies, serving OEMs with integrated solutions. Companies like Yazaki Corporation and Aptiv PLC leverage their expertise to supply global vehicle production lines.
- Aftermarket Providers:Aftermarket providers supply replacement parts and upgrade components for electrical distribution systems to repair shops and consumers.
- Vehicle Assemblers:Vehicle Assemblers integrate pre-fabricated electrical distribution systems into the final vehicle structure on the production line.
- Repair Shops:Repair Shops diagnose and fix electrical system malfunctions, utilizing replacement components from various suppliers.
OEMs drive the initial demand for new electrical distribution system designs, while Aftermarket Providers cater to ongoing maintenance and repair needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's expanding network of automotive assembly plants underwrites North America's growing role in the global automotive electrical distribution system market. This supply chain reconfiguration is driven by nearshoring initiatives and the increasing complexity of vehicle electrical architectures. Key countries globally are intensifying their focus on advanced electrical systems.
China
China's robust electric vehicle manufacturing capacity drives substantial demand for high-voltage electrical distribution systems. MIIT regulations actively promote the adoption of New Energy Vehicles, directly influencing component specifications. The Yangtze River Delta region, including Shanghai, serves as a major hub for advanced EV production and component integration.
Germany
German automakers' transition to premium electric vehicles and sophisticated ADAS architectures creates strong demand for intelligent power distribution. The EU Green Deal and CSRD compel manufacturers to prioritize sustainable materials and transparent supply chains. Bavaria, with its concentration of automotive OEMs and Tier-1 suppliers, remains a core innovation center.
United States
United States passenger vehicle production, coupled with increasing EV adoption, generates significant demand for integrated electrical systems. US EPA emissions targets and NHTSA safety regulations necessitate advanced power management and redundant systems. The Detroit automotive cluster continues to drive innovation in electrical distribution network design for next-generation vehicles.
Japan
Japanese vehicle manufacturers emphasize highly integrated electrical distribution systems for both hybrid and conventional passenger vehicles. METI initiatives support research and development into advanced automotive electronics and materials. Aichi Prefecture, surrounding Nagoya, remains a cornerstone for automotive production and component supplier ecosystems.
Mexico
Mexico's expanding automotive assembly capacity, particularly for North American markets, is driving demand for electrical harnesses and connectors. The USMCA trade agreement influences local content requirements for electrical components supplied to OEMs. The Northern Border States, including Monterrey, are seeing increased investment in manufacturing facilities for these systems.
Global Automotive Electrical Distribution System Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical elements for electrical distribution systems. The market exhibits a tiered structure, with a few large Tier-1 suppliers dominating integrated system solutions. Several specialized component manufacturers focus on niche high-voltage or smart wiring technologies. Strategic partnerships between OEMs and Tier-1s are a dominant competitive move, alongside portfolio diversification into advanced power electronics.
Within the Tier-1 supplier archetype, Lear Corporation exemplifies deep integration with vehicle platforms through its extensive product portfolio. Yazaki Corporation, with its global manufacturing footprint, anchors the high-volume wiring harness segment, providing foundational electrical networks. Aptiv PLC, a publicly traded company, represents specialization in high-voltage and active safety system architectures, catering to the growing complexity of modern vehicles and their software-defined requirements. These firms continuously adapt their offerings to meet evolving demands for electrification and advanced driver assistance systems.
| Leading Market Players |
|---|
| Lear Corporation |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Aptiv PLC |
| Draexlmaier Group |
| Furukawa Electric |
| Eaton Corporation |
| Leoni AG |
| Littelfuse |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's expanding EV production capacity directly influences downstream pricing power for specialized high-voltage electrical distribution systems. This concentration of manufacturing capability creates distinct cost advantages for local suppliers serving the automotive industry.
Pricing Analysis
EU Green Deal regulations dictate the pricing tier structure for certain electrical components, especially those with sustainable material requirements. The dominant pricing model remains transactional, with contracts often negotiated for specific vehicle platforms. Price differentiation is driven by the customization level required for advanced E/E architectures and the high-voltage certification of components. Pricing pressure stems from material cost volatility, particularly for copper and specialty polymers. OEMs for standard passenger vehicles demonstrate the most price sensitivity, while premium EV manufacturers show less for highly specialized, integrated systems.
Supply Chain Analysis
USMCA trade agreement regulations, influencing local content, shape the supply chain for automotive electrical distribution systems. Supply concentration is evident in China for high-voltage components and in Mexico for wiring harnesses. The industry draws from raw material dependencies on copper for conductors and specialized polymers for insulation. Supply chain concentration with a limited number of specialized suppliers for high-voltage connectors creates a structural risk. Distribution primarily runs directly from Tier-1 suppliers to OEMs and vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift toward software-defined zonal architectures, creating specialized niches for advanced electrical components.
For Market Incumbents: Insulate existing market share by accelerating investment in high-voltage engineering talent and standardizing new component designs for zonal architectures. This counters the threat from specialized new entrants and mitigates margin pressure from commoditization in legacy systems. Deepen co-development partnerships with OEMs for complex EV platforms to ensure early integration.
For New Entrants and Emerging Players: Underpenetration in intelligent power distribution modules for commercial vehicles presents a significant opportunity. Target the development of smart fuses and software-controlled circuit breakers for heavy-duty EV applications in North America. A go-to-market strategy should focus on offering integrated, modular solutions that simplify installation and enhance diagnostic capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a technology consolidation play because the market demands integrated, software-enabled electrical distribution systems for modern vehicles. Target specialized component manufacturers with expertise in high-voltage connectors, smart power electronics, or zonal control units. The signal to watch is the widespread adoption rate of zonal E/E architectures by major global OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Standardizing electrical architectures reduces development costs and enhances component interchangeability across vehicle models. |
| Software-Defined Vehicle Investment | Investing in software for power management enables dynamic load balancing and advanced diagnostic functions in EVs. |
| Geographic Manufacturing Footprint | Expanding production facilities in key automotive hubs like Mexico supports regional supply chain resilience and OEM integration. |
| Technology Licensing | Licensing advanced high-voltage connector or smart fuse technologies accelerates market entry and expands product portfolios. |
| Vertical Integration into Power Electronics | Controlling the production of critical power electronic components secures supply and enhances system performance for OEMs. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings and quantitative estimates. Primary data sources include conversations with OEM platform engineers, Tier-1 R&D directors, electrical system architects, and regulatory specialists. Secondary sources encompass industry association reports, government publications on vehicle electrification, company financial filings, and technical journals focusing on automotive electronics. This approach ensures robust bottom-up and top-down triangulation.
The calibration approach involves iterative modeling, where initial market size and growth figures are refined against macroeconomic indicators and industry-specific drivers. Segmentation dimensions modeled include product type, technology, application, end-user, and regional production capacity. Compound annual growth rates are derived from historical trends, projected market shifts, and expert consensus. Key forecast inputs include global electric vehicle production forecasts and evolving regulatory mandates for vehicle electrification.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology disruptors or vertically integrated OEMs would shift outcomes. The analysis reflects assumptions regarding technological adoption curves and supply chain stability. Material shifts in global EV adoption rates or unforeseen regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
On-Board Fuse Box Market