
 Japan Next Generation Vehicle Market | 2026-2036
Japan Next Generation Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Next Generation Vehicle Market Intelligence
Premium efficiency certification tiers is rotating the competitive landscape toward vehicles with superior energy density and extended range metrics. Toyota Motor Corporation anchors its position through captive control over solid-state battery R&D pipelines. Denso Corporation specializes in thermal management systems that extend electric drivetrain longevity under Japanese climate conditions. Honda Motor Co., Ltd. navigates the transition by leveraging its hybrid heritage into plug-in architectures for domestic fleet buyers.
Japan Next Generation Vehicles encompass electrified, hydrogen-powered, and autonomous mobility platforms engineered to exceed 15% thermal efficiency in hybrid configurations or achieve 800-volt architectures in full-electric variants, serving industrial decarbonization mandates and urban congestion reduction. Battery Technology segments dominate value capture as lithium-ion chemistries shift toward silicon-anode and solid-state formats. Hydrogen Fuel Cells represent the fastest-growing technology dimension, concentrated in commercial bus and heavy-duty logistics applications where refueling speed outweighs infrastructure density constraints.
METI enforces vehicle efficiency standards through its Top Runner program while the Ministry of Land, Infrastructure, Transport and Tourism certifies autonomous driving levels under revised Road Transport Vehicle Act frameworks. PMDA-aligned safety protocols for software-defined vehicles are reshaping type-approval timelines and supplier qualification requirements. Stakeholders must monitor hydrogen station economics and grid-interconnection standards as these determine whether fuel cell or battery-electric platforms achieve scale in Japan's mountainous and island prefectures.
Market Dynamics
METI's Green Growth Strategy is compressing powertrain transition timelines, forcing fleet operators to abandon conventional hybrid architectures before residual value depreciation curves stabilize.
Growth Catalysts
- Carbon Neutrality Mandates:METI's revised targets under the Green Growth Strategy mandate powertrain diversification beyond conventional hybrids, creating regulatory pull for electrified commercial platforms.
- Urban Logistics Electrification:Fleet operators in the Kanto corridor connecting Tokyo, Yokohama, and Chiba are accelerating procurement of battery-electric and hydrogen fuel cell commercial vehicles.
- Solid-State Battery Maturation:Silicon-anode and solid-state lithium-ion chemistries are extending range metrics beyond 600 kilometers, satisfying long-haul freight requirements previously reserved for diesel.
Market Restraints
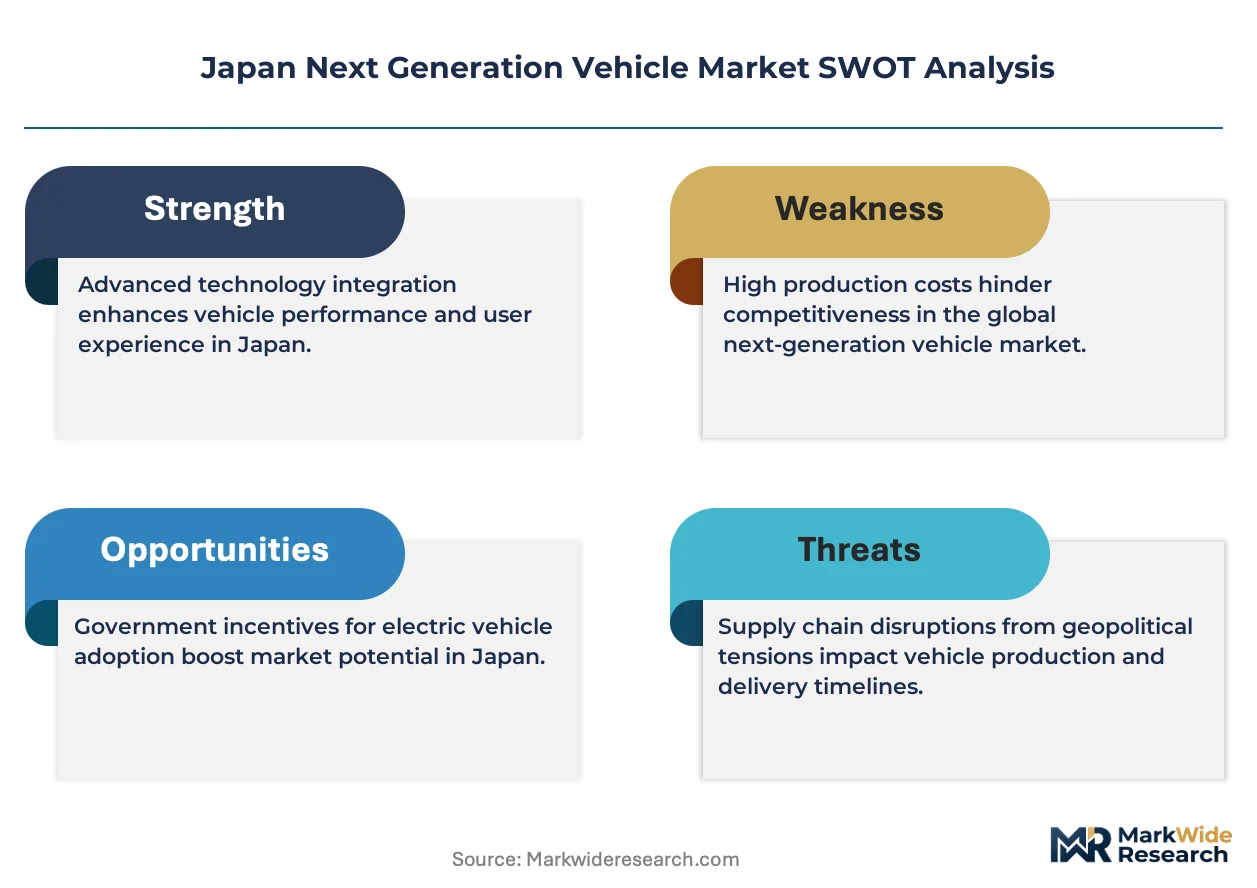
- Charging Infrastructure Asymmetry:Hydrogen station economics remain unfavorable outside the Kanto corridor, limiting fuel cell vehicle deployment to island and mountainous prefectures.
- Critical Mineral Concentration:Lithium and cobalt processing capacity concentrates in external supply chains, exposing Japanese battery manufacturers to input cost volatility and geopolitical friction.
- Grid Interconnection Standards:Regional electric utilities maintain inconsistent fast-charging protocols, fragmenting vehicle-to-grid integration capabilities across prefectural boundaries.
Strategic Opportunities
- Autonomous Mobility Certification:The Ministry of Land, Infrastructure, Transport and Tourism's revised Road Transport Vehicle Act frameworks are accelerating Level 4 autonomous vehicle type-approval timelines.
- Commercial Bus Electrification:Hydrogen fuel cell platforms are capturing share in municipal bus fleets where refueling speed outweighs infrastructure density constraints.
- Thermal Management Specialization:Climate-specific drivetrain longevity solutions for Japan's humidity and temperature variations represent uncaptured white space in component supply.
Industry Challenges
- Software-Defined Vehicle Talent Scarcity:PMDA-aligned safety protocols require embedded systems engineers with dual competency in automotive functional safety and cybersecurity, a skill combination currently underrepresented in domestic labor markets.
- Dual Certification Burden:Manufacturers must simultaneously satisfy METI efficiency standards through the Top Runner program and PMDA software validation timelines, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Next Generation Vehicle Market |
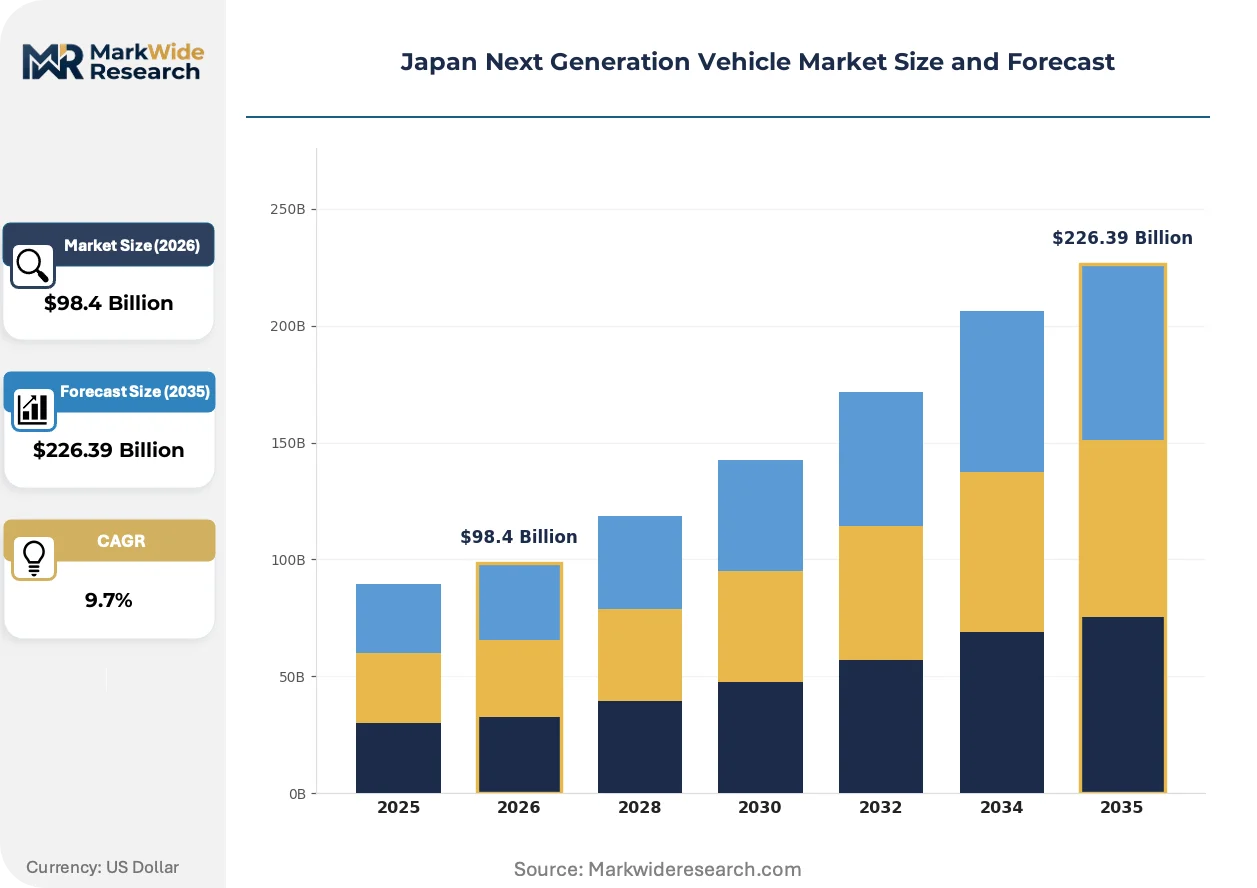
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $226.39 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Vehicles, Hybrid Vehicles, Fuel Cell Vehicles, Autonomous Vehicles Technology: Battery Technology, Hydrogen Fuel Cells, Connected Vehicle Tech, Advanced Driver Assistance Systems End User: Commercial Fleets, Private Consumers, Ride-Sharing Services, Public Transportation Charging Infrastructure: Fast Charging Stations, Home Charging Solutions, Wireless Charging Pads, Battery Swap Stations |
| Companies Covered | Suzuki Motor Corporation, Mazda Motor Corporation, Toyota Motor Corporation, Sony Group Corporation, Denso Corporation, Honda Motor Co., Ltd., Mitsubishi Motors Corporation, GS Yuasa Corporation, Nissan Motor Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Next Generation Vehicle Market Strategic Shifts & Innovations
Solid-state battery commercialization and autonomous driving certification frameworks are restructuring competitive advantage around energy density metrics and software validation capabilities rather than manufacturing scale alone.
Solid-state battery technology is fragmenting the competitive landscape by enabling 800-volt architectures with superior thermal stability. Commercial fleet operators in the Kanto corridor are piloting these platforms for refrigerated logistics where energy density directly determines payload capacity. The technology is fragmenting incumbent supply relationships as cell manufacturers bypass traditional tiered supplier hierarchies.
METI's Top Runner program enforces vehicle efficiency standards through mandatory fleet-average benchmarks that ratchet upward biennially. Manufacturers must redesign powertrain thermal management systems to maintain compliance margins. Heavy-duty logistics segments face the steepest redesign cycles as diesel displacement timelines compress.
Fleet procurement is consolidating around total-cost-of-ownership metrics that incorporate residual value risk from technology obsolescence. Leasing intermediaries are displacing direct manufacturer relationships for urban delivery operators. This behavioral shift concentrates most visibly in Tokyo's last-mile logistics networks where vehicle utilization rates exceed 18 hours daily.
Japan Next Generation Vehicle Market Segmentation
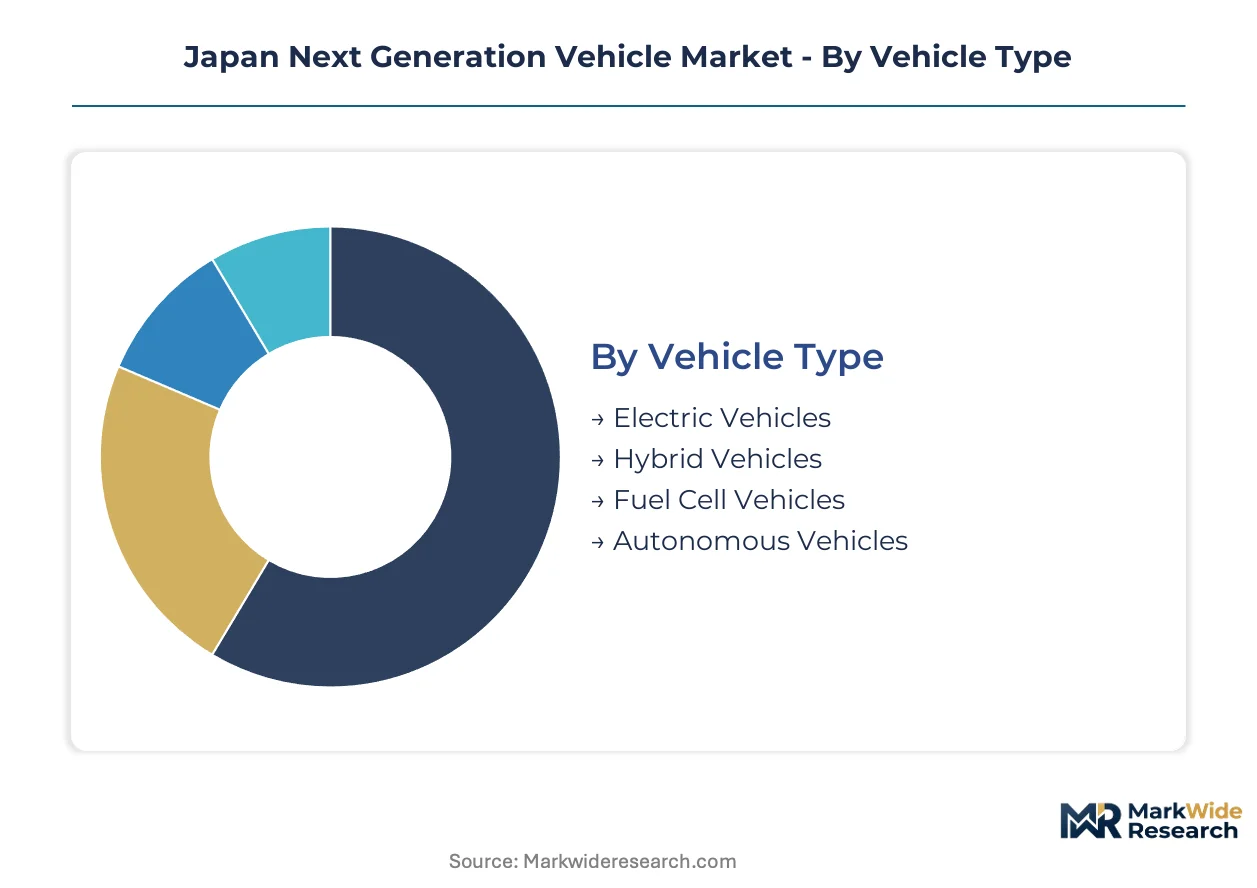
Segmentation reveals how Japan's next generation vehicle market fragments across powertrain technologies, infrastructure dependencies, and customer procurement patterns. Each dimension carries distinct regulatory footprints and supply chain configurations that determine competitive positioning.
Vehicle Type:
Domestic demand concentrates in electrified platforms serving METI decarbonization mandates, while export-oriented production emphasizes hybrid architectures for markets with weaker charging infrastructure.
- Electric Vehicles:Battery-electric platforms with 800-volt architectures and silicon-anode cells are penetrating commercial logistics fleets in Tokyo, Yokohama, and Chiba where charging density supports intensive utilization schedules. METI efficiency benchmarks and residual value guarantees from leasing intermediaries are compressing payback periods for fleet operators.
- Hybrid Vehicles:Conventional and plug-in hybrid configurations retain dominance in private consumer segments and rural prefectures where grid interconnection remains inconsistent. Toyota's captive solid-state battery pipelines and Honda's plug-in hybrid heritage anchor domestic manufacturing capacity.
- Fuel Cell Vehicles:Hydrogen platforms serve heavy-duty logistics and island prefectures where refueling speed outweighs infrastructure density constraints.
- Autonomous Vehicles:Level 4 certification under MLIT frameworks targets ride-sharing and fixed-route public transportation applications.
Hybrid Vehicles hold the largest share; momentum sits with Electric Vehicles.
Technology:
Technology segmentation tracks value capture from energy storage innovations through software-defined vehicle architectures, with cost tiers separating premium efficiency certifications from baseline compliance offerings.
- Battery Technology:Lithium-ion chemistries shifting toward silicon-anode and solid-state formats dominate component value. Thermal management systems from Denso extend drivetrain longevity under Japanese humidity conditions.
- Hydrogen Fuel Cells:Proton exchange membrane stacks and high-pressure storage systems are climbing the fastest in municipal bus and heavy-duty freight segments where refueling infrastructure receives direct METI subsidy allocation.
- Connected Vehicle Tech:V2X communication modules and over-the-air update capabilities satisfy PMDA software validation requirements.
- Advanced Driver Assistance Systems:Sensor fusion platforms bridge current L2 deployment toward MLIT-certified L4 autonomy.
Battery Technology captures the deepest value; Hydrogen Fuel Cells are expanding most quickly.
End User:
Customer type determines procurement volume concentration and technology risk tolerance, with commercial operators accepting earlier technology generations than private consumers.
- Commercial Fleets:Urban logistics operators in the Kanto corridor are consolidating procurement around total-cost-of-ownership metrics that incorporate technology obsolescence risk. Vehicle utilization rates exceeding 18 hours daily justify premium efficiency certifications.
- Private Consumers:Residential buyers in metropolitan prefectures favor plug-in hybrids pending solid-state battery commercialization and charging infrastructure maturation.
- Ride-Sharing Services:Platform operators pilot autonomous vehicle deployments under MLIT Level 4 frameworks.
- Public Transportation:Municipal bus operators prioritize hydrogen fuel cell platforms for route flexibility.
Commercial Fleets drive procurement volume; Ride-Sharing Services show the steepest technology adoption trajectory.
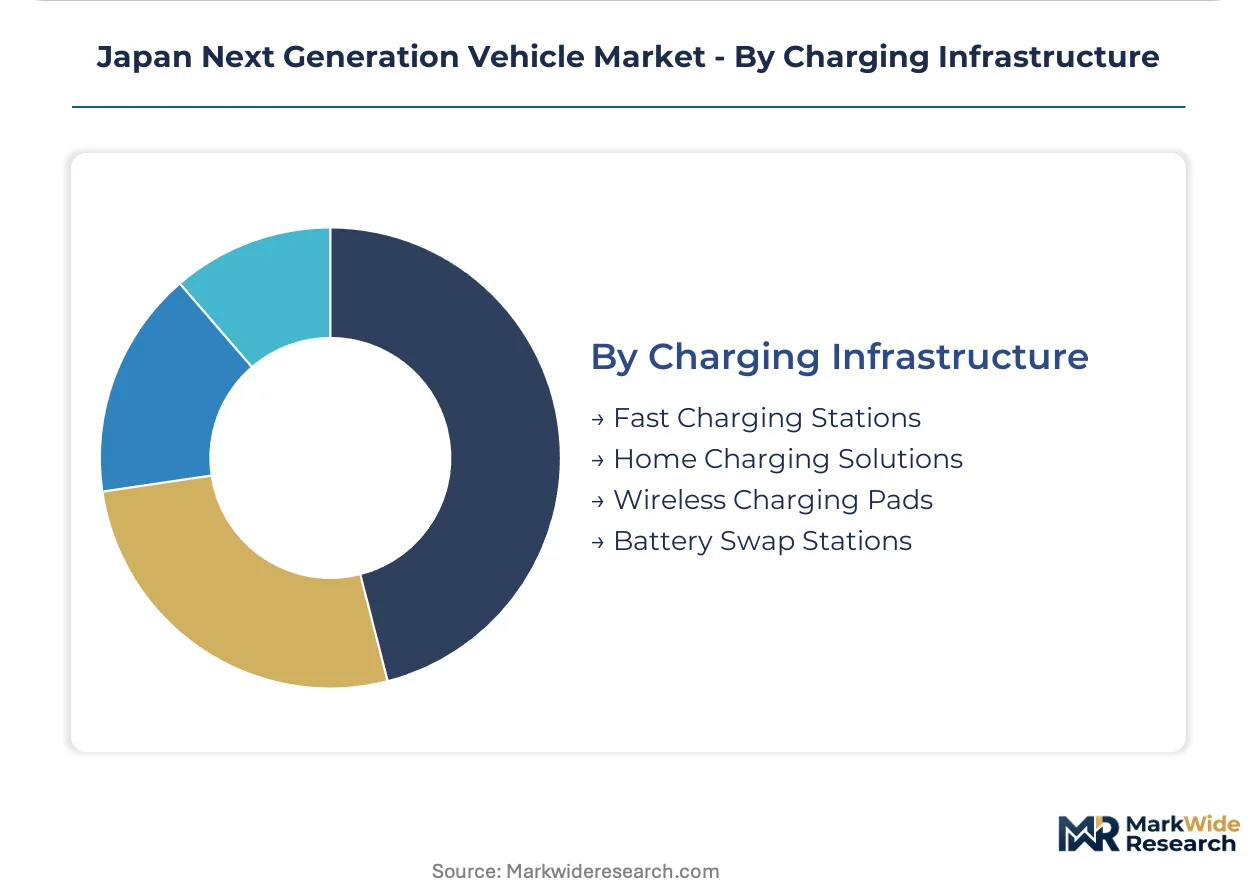
Charging Infrastructure:
Infrastructure segmentation reflects METI's uneven spatial investment patterns, with deployment density determining which powertrain technologies achieve scale in specific prefectures.
- Fast Charging Stations:800-volt DC infrastructure concentrates in Tokyo, Yokohama, and Chiba commercial corridors where fleet electrification timelines are most compressed.
- Home Charging Solutions:Residential AC installations dominate private consumer adoption in metropolitan prefectures with reliable grid interconnection.
- Wireless Charging Pads:Inductive systems target premium residential and commercial parking applications.
- Battery Swap Stations:Automated exchange infrastructure pilots serve taxi and delivery fleets with standardized battery form factors.
Fast Charging Stations command the largest deployment; Battery Swap Stations are gaining share fastest in commercial fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's next generation vehicle market maintains a trade surplus in hybrid powertrain exports while importing lithium and cobalt for battery manufacturing. Domestic demand concentrates in metropolitan corridors where charging density supports fleet electrification timelines.
Kanto
Tokyo, Yokohama, and Chiba form Japan's densest electric vehicle corridor with over 18-hour daily utilization rates for commercial fleets. METI directs subsidy allocation toward fast-charging infrastructure along this axis. Fleet operators here are consolidating procurement around total-cost-of-ownership metrics that incorporate technology obsolescence risk.
Kansai
Osaka and Kyoto prefectures exhibit stronger plug-in hybrid adoption among private consumers awaiting solid-state battery commercialization. The Ministry of Land, Infrastructure, Transport and Tourism certifies autonomous vehicle pilots in this region under revised Road Transport Vehicle Act frameworks. Manufacturing clusters here specialize in connected vehicle modules and thermal management components.
Chubu
Nagoya anchors Toyota's captive solid-state battery R&D pipeline and hybrid powertrain export production. Regional suppliers extend electric drivetrain longevity solutions calibrated for Japanese humidity conditions. Heavy-duty logistics operators in this corridor face compressed redesign cycles under METI's biennial Top Runner efficiency benchmarks.
Kyushu
Fukuoka and surrounding prefectures pilot hydrogen fuel cell deployment for municipal bus fleets where refueling speed outweighs infrastructure density constraints. METI subsidy programs target island prefectures with unfavorable hydrogen station economics. Local governments here prioritize route flexibility over battery-electric alternatives for public transportation.
Hokkaido
Cold-climate battery performance limitations slow full-electric adoption in northern prefectures. Grid interconnection standards from regional electric utilities fragment vehicle-to-grid integration capabilities. Fleet operators here retain conventional hybrid architectures longer than national timelines prescribe.
Japan Next Generation Vehicle Market Key Industry Players
Listed automotive conglomerates compete with private component specialists across powertrain technology development and thermal management systems. The vendor base organizes into three tiers: integrated OEMs with captive battery pipelines, tier-1 subsystem suppliers with climate-specific IP, and emerging mobility platform operators. Dominant competitive moves include backward integration into solid-state cell manufacturing and strategic partnerships for autonomous driving certification.
Within the integrated OEM tier, Toyota Motor Corporation and Honda Motor Co., Ltd. exemplify divergent electrification strategies. Among tier-1 specialists, Denso Corporation occupies a position emphasizing thermal management systems for Japanese climate conditions. These three entities represent the core competitive anchors around which supplier relationships and technology licensing networks reorganize.
| Leading Market Players |
|---|
| Suzuki Motor Corporation |
| Mazda Motor Corporation |
| Toyota Motor Corporation |
| Sony Group Corporation |
| Denso Corporation |
| Honda Motor Co., Ltd. |
| Mitsubishi Motors Corporation |
| GS Yuasa Corporation |
| Nissan Motor Co., Ltd. |
| Others |
Cost & Logistics Intelligence
METI's Top Runner certification tiers gate both supplier qualification and price differentiation simultaneously, compressing margins for manufacturers who miss efficiency benchmarks while rewarding captive battery pipelines with premium positioning. Fleet procurement in the Kanto corridor now filters vendors through dual compliance filters that reshape cost structures across the value chain.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure where volume scale and certification grade determine tier placement. Price differentiation stems from solid-state battery content and METI efficiency tier achievement, with premium tiers commanding significant separation from baseline compliance offerings. Cost compression in standard-tier drivetrains is intensifying because silicon-anode cell shortages favor qualified suppliers. Commercial fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while rural private consumers remain most responsive to upfront acquisition cost.
Supply Chain Analysis
Port congestion along the Shanghai-Yokohama trade lane elevates inbound logistics costs for lithium carbonate and cobalt sulfate shipments destined for Japanese cell plants. Geographic supply concentration draws from Australia, Chile, and Indonesia for lithium and nickel feedstocks. Raw material dependencies center on cathode active materials, separator films, and thermal management fluids. Single-source vulnerability persists in solid-state electrolyte precursor supply. Distribution runs through captive OEM channels and tier-1 subsystem suppliers with direct fleet relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's next generation vehicle market sits at a platform-economics inflection where V2X interoperability standards and hydrogen refueling network density will determine which powertrain ecosystems capture scale. The shift from manufacturing-scale competition to software-validation and energy-density metrics rewrites competitive rules.
For Market Incumbents: Shield hybrid powertrain margins by accelerating backward integration into solid-state cell manufacturing before residual value guarantees expire. Lock in fleet channel control through leasing intermediary partnerships that neutralize technology obsolescence risk for Kanto corridor operators. METI's biennial efficiency benchmark ratchets threaten incumbents who delay thermal management redesign cycles. For New Entrants and Emerging Players: Anchor in municipal bus hydrogen fuel cell deployments across Kyushu island prefectures where refueling speed requirements and METI subsidy allocation create penetrable white space. Target thermal management specialization for Japan's humidity conditions as an uncapped component supply niche. Pursue certification partnerships with MLIT for Level 4 autonomous pilots in Kansai urban corridors. For Investors and Strategic Acquirers: MLIT's revised Road Transport Vehicle Act frameworks reshape the acquisition landscape toward software-defined vehicle capabilities and embedded systems engineering talent. Long-term viability favors targets with dual competency in automotive functional safety and PMDA-aligned cybersecurity protocols. Watch hydrogen station economics in island prefectures as the inflection signal determining fuel cell versus battery-electric platform scale.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive silicon-anode cell access secures METI Top Runner compliance margins for fleet operators. |
| Software-Defined Vehicle Investment | PMDA validation capabilities differentiate suppliers as MLIT accelerates Level 4 certification timelines. |
| Charging Infrastructure Partnership | 800-volt DC fast-charging density in Kanto corridors determines commercial fleet electrification pace. |
| Thermal Management Specialization | Climate-specific drivetrain longevity solutions address uncaptured white space in Japanese humidity conditions. |
| Platform Standardization | Common battery form factors enable swap-station economics for taxi and delivery fleet segments. |
Research Approach
Desk research of METI policy filings, MLIT certification databases, and vehicle production registries preceded structured interviews with OEM platform engineers, tier-1 supplier procurement leads, fleet operations managers, and charging infrastructure developers. Secondary validation drew from customs trade data, hydrogen station deployment records, and PMDA software validation timelines. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates across the analysis window.
Variance decomposition across vehicle class, propulsion architecture, and regional production cluster dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth trajectory synthesis rather than single-point extrapolation. Forecast inputs incorporated METI subsidy allocation patterns, solid-state battery commercialization curves, and autonomous vehicle certification pipeline velocity.
Decision-makers should treat outputs as directional under assumptions of continued METI Green Growth Strategy enforcement and stable lithium carbonate supply channel function; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions regarding hydrogen station buildout rates and grid interconnection standard harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market