
 Automotive Ultracapacitor Market | 2026-2036
Automotive Ultracapacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ultracapacitor Market Intelligence
Project financing for gigafactory-scale manufacturing is reconfiguring the competitive landscape for ultracapacitor suppliers. Maxwell Technologies leverages its established intellectual property portfolio to secure partnerships with major automotive OEMs. Skeleton Technologies specializes in high-power density graphene-based ultracapacitors, targeting performance-critical applications. Panasonic Holdings Corporation sustains its market position through extensive manufacturing scale and deep supply chain control.
Automotive ultracapacitors are electrochemical energy storage devices characterized by extremely high power density and long cycle life, often exceeding one million cycles. Their primary function is to capture and release large bursts of energy rapidly, making them ideal for supplementing batteries in high-demand situations. Electric Double-Layer Capacitors (EDLCs) using activated carbon represent the most mature product segment, dominating current deployments. Regenerative braking and start-stop applications are the fastest-growing use cases, pulling demand from both OEMs and Tier-1 Suppliers.
Vehicle emissions standards, including the US EPA's fuel economy targets and Europe's forthcoming Euro 7 regulations, create a direct incentive for energy recovery technologies. China's Ministry of Industry and Information Technology (MIIT) mandates for New Energy Vehicle production establish a significant, policy-driven market. Component selection for automakers will increasingly balance the power density of ultracapacitors against the evolving energy density of lithium-ion batteries.
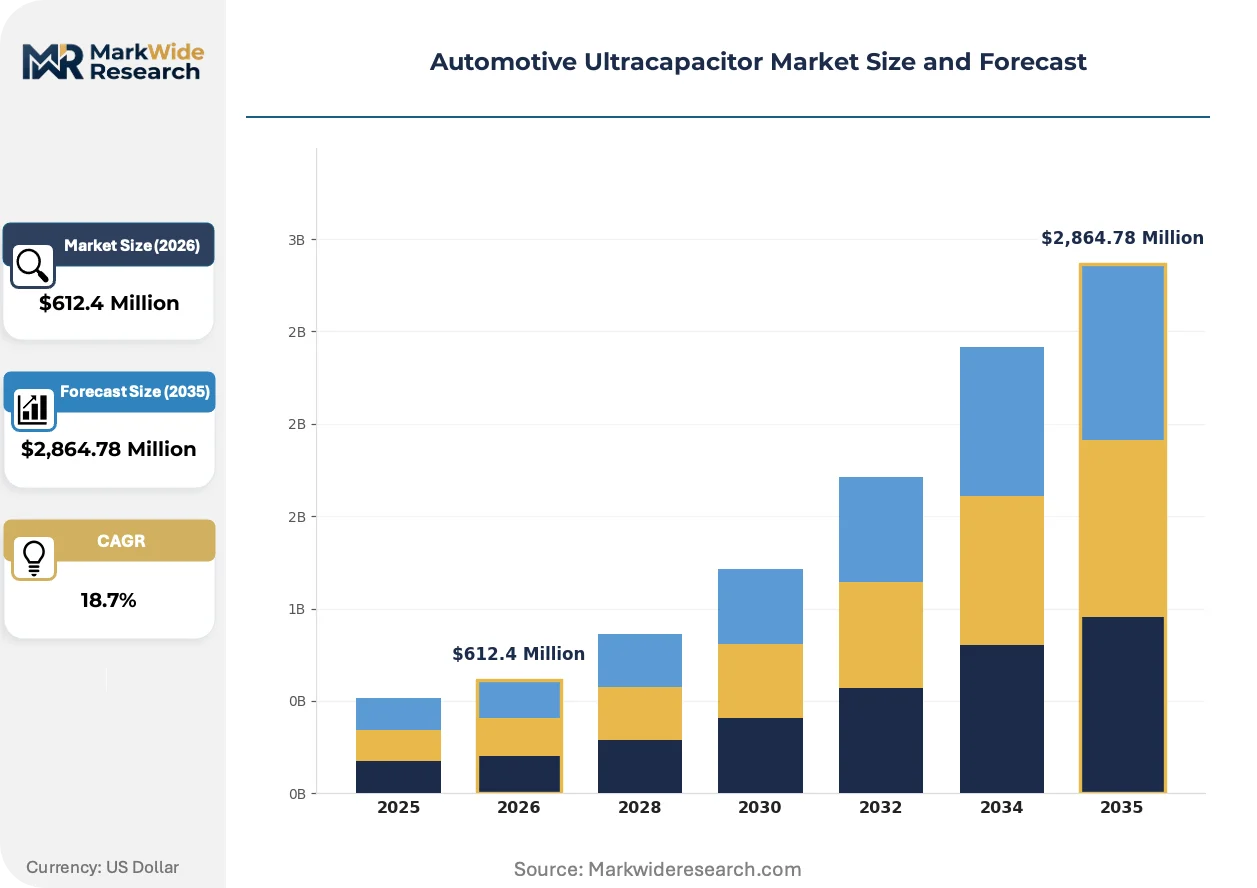
Market Dynamics
The central dynamic shaping the automotive ultracapacitor market is the regulatory mandate for improved vehicle energy efficiency. This pressure from bodies like the EPA and through frameworks such as the EU Green Deal forces automakers to adopt energy recovery systems.
Growth Catalysts
- Regenerative Braking Systems:The adoption of ultracapacitors in regenerative braking for hybrid and electric vehicles is a primary growth engine, enabling efficient capture of kinetic energy that would otherwise be lost as heat.
- China's NEV Mandate:Policies from China's Ministry of Industry and Information Technology (MIIT) that promote New Energy Vehicle (NEV) production create a massive, policy-driven demand center for ultracapacitors and related components.
- Stringent Emissions Standards:Forthcoming regulations like Europe's Euro 7 standards impose strict limits on vehicle emissions, compelling automakers to integrate technologies like ultracapacitors for start-stop systems and power stabilization to meet compliance targets.
Market Restraints
- Energy Density Limitations:Ultracapacitors possess significantly lower energy density compared to lithium-ion batteries, which limits their use as standalone primary energy storage and confines them to high-power, short-duration applications.
- High Initial Cost:The upfront cost of ultracapacitor modules can be higher than that of lead-acid or even some lithium-ion batteries for equivalent voltage, posing a barrier for cost-sensitive vehicle segments.
- Substitution from Batteries:Continuous improvements in the power density and charging speed of lithium-ion and other advanced battery chemistries present a persistent substitution threat, particularly as battery costs decline.
Strategic Opportunities
- Heavy-Duty and Commercial Vehicles:The electrification of buses, trucks, and construction equipment provides a significant opportunity, as these vehicles have frequent start-stop cycles and high-power demands well-suited to ultracapacitor performance.
- Hybrid Energy Storage Systems:Combining ultracapacitors with batteries in a single hybrid pack allows designers to leverage the high power of capacitors and the high energy of batteries, creating optimized solutions for performance and longevity.
- Grid Stabilization in Charging Infrastructure:Ultracapacitors can be deployed within electric vehicle fast-charging stations to buffer the power grid from extreme demand spikes, representing an emerging infrastructure-related application.
Industry Challenges
- Capital-Intensive Manufacturing:Achieving the scale and quality required for automotive-grade ultracapacitor production necessitates substantial capital investment in gigafactory-scale facilities, creating high barriers to entry for new suppliers.
- System Integration Complexity:Integrating ultracapacitors and their control electronics with a vehicle's existing Battery Management System (BMS) and electrical architecture is a complex engineering challenge requiring specialized expertise.
- Lack of Standardization:A lack of industry-wide standards for module form factors, communication protocols, and safety testing protocols complicates design and sourcing for automotive OEMs and Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ultracapacitor Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Capacitors, Electric Double-Layer Capacitors, Pseudocapacitors, Asymmetric Capacitors Component: Activated Carbon, Carbon Nanotubes, Conducting Polymers, Metal Oxides Application: Energy Storage Systems, Regenerative Braking, Start-Stop Applications, Power Buffering End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Nippon Chemi-Con Corporation, TDK Corporation, Panasonic Holdings Corporation, Ioxus, LS Mtron, Maxwell Technologies, KEMET Corporation, Yunasko, Skeleton Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ultracapacitor Market Strategic Shifts & Innovations
Material science advancements in graphene and activated carbons are fundamentally expanding the performance envelope of ultracapacitors. This evolution enables their deployment beyond niche roles into core energy management strategies for next-generation hybrid and electric vehicles.
Advanced control software is a critical innovation for managing energy flow between ultracapacitors, batteries, and vehicle powertrains. Automotive OEMs and Tier-1 suppliers are increasingly adopting these sophisticated algorithms to optimize efficiency and performance in real time. This software-defined approach is digitizing the vehicle's energy storage strategy, enabling dynamic power allocation that extends battery life and improves responsiveness.
The US Environmental Protection Agency's (EPA) fuel economy standards directly incentivize the use of energy recovery technologies. These regulations require automakers to improve their Corporate Average Fuel Economy (CAFE) ratings, making ultracapacitor-based systems an attractive compliance pathway. Consequently, 48V mild-hybrid systems, which depend on ultracapacitors for efficient start-stop and torque assist functions, are seeing wider deployment in the North American market.
Automotive OEMs are evolving their sourcing strategy from buying off-the-shelf components to forming deep co-development partnerships with ultracapacitor manufacturers. This shift replaces transactional procurement with a collaborative process focused on designing application-specific, integrated energy storage solutions. This demand-side behavior is most visible within the European performance EV and global commercial vehicle segments, where custom power delivery profiles are essential.
Automotive Ultracapacitor Market Segmentation
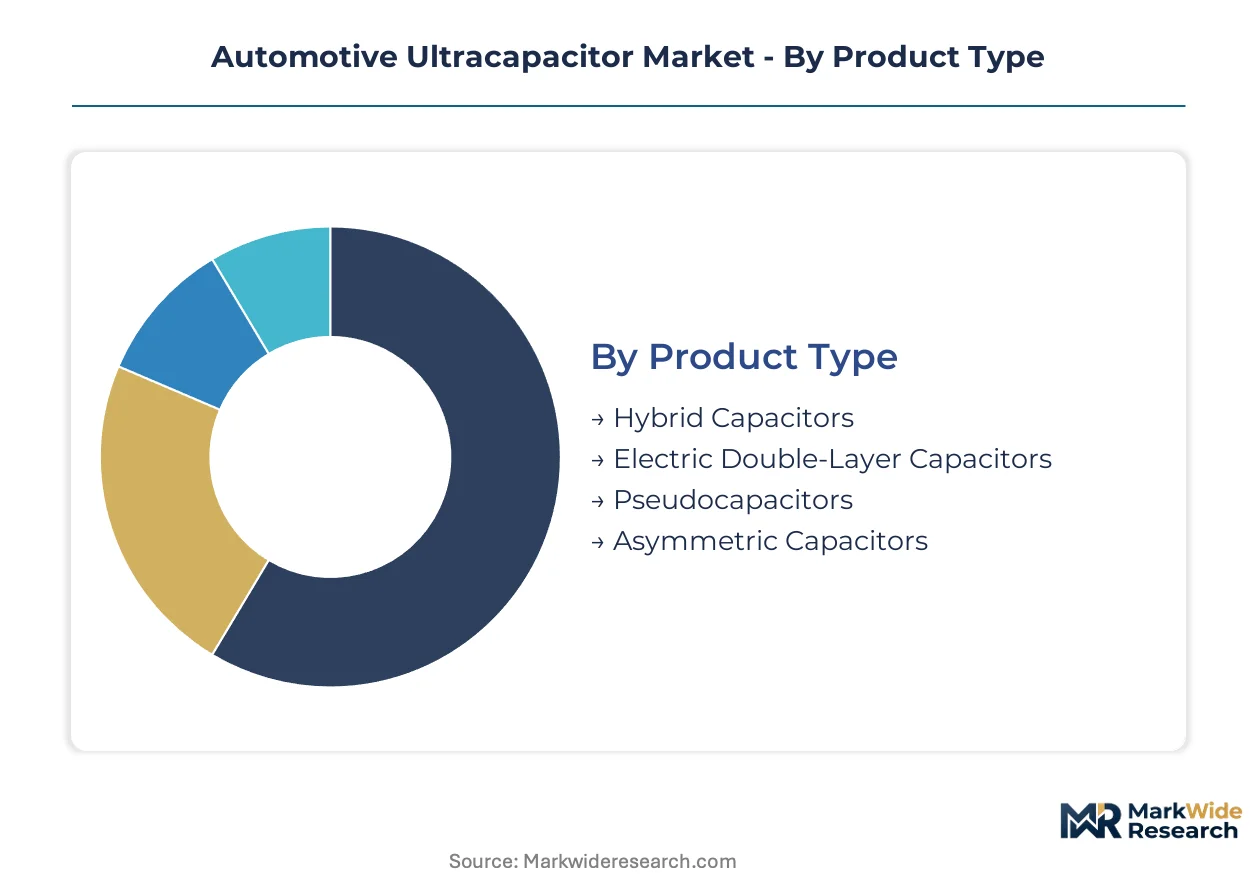
The automotive ultracapacitor market segments reveal distinct technological approaches, key applications, and the primary stakeholders driving demand and integration. Understanding these divisions helps clarify market dynamics, identify high-growth areas, and pinpoint specific technological advancements. This segmentation provides a granular view of how ultracapacitors are being adopted across the diverse automotive ecosystem.
Product Type:
The product type dimension categorizes ultracapacitors by their internal electrochemical design.
- Electric Double-Layer Capacitors (EDLCs):These devices utilize activated carbon electrodes to achieve high surface area for charge separation, providing rapid power delivery and long cycle life. Demand concentrates in hybrid and electric vehicle systems, where EDLCs supplement batteries for high-power bursts.
- Hybrid Capacitors:Combining characteristics of both batteries and conventional ultracapacitors, these devices offer higher energy density than EDLCs while retaining superior power density compared to batteries. Adoption is growing in performance-critical applications requiring a balance of energy and power.
- Pseudocapacitors:These devices store energy through faradaic redox reactions at the electrode surface, offering higher capacitance than EDLCs but typically with lower power density.
- Asymmetric Capacitors:Utilizing different electrode materials, these ultracapacitors are designed to optimize specific performance parameters, often balancing energy and power characteristics for specialized applications.
Electric Double-Layer Capacitors hold installed capacity. Hybrid Capacitors are rotating up the share rankings.
Component:
Material selection for ultracapacitor components directly influences performance metrics.
- Activated Carbon:This material provides a high surface area for ion adsorption, making it the most common and cost-effective electrode material for Electric Double-Layer Capacitors. Demand for activated carbon components is pervasive across mainstream automotive ultracapacitor production.
- Carbon Nanotubes:Known for their exceptional electrical conductivity and mechanical strength, carbon nanotubes enhance electrode performance, enabling higher power density and faster charge/discharge rates. These components are critical for next-generation, high-performance ultracapacitor designs.
- Conducting Polymers:These organic materials offer pseudocapacitive behavior, contributing to higher energy density through redox reactions at the electrode surface.
- Metal Oxides:Transition metal oxides, such as ruthenium oxide, can exhibit high pseudocapacitance, providing significant energy storage capacity in compact form factors.
Activated Carbon components maintain market share. Carbon Nanotubes are expanding most quickly.
Application:
The application segments illustrate the diverse operational roles of ultracapacitors within vehicles.
- Regenerative Braking:Ultracapacitors capture kinetic energy during vehicle deceleration, converting it into electrical energy for storage and later reuse, significantly enhancing fuel efficiency in hybrid and electric vehicles. This application is a primary growth engine for the market, driven by stringent emissions standards.
- Start-Stop Applications:These systems use ultracapacitors to provide rapid power for engine restarts, reducing idle emissions and improving fuel economy in internal combustion and mild-hybrid vehicles. Demand from OEMs for 48V mild-hybrid systems is driving widespread deployment in North America.
- Energy Storage Systems:Ultracapacitors function as auxiliary energy reservoirs, providing rapid power bursts or buffering power fluctuations within a vehicle's electrical system.
- Power Buffering:These ultracapacitor applications stabilize voltage and current, protecting sensitive electronic components from power surges and sags, particularly in high-demand vehicle subsystems.
Regenerative Braking applications drive significant volume. Start-Stop systems are gaining share fastest.
End User:
Customer type segmentation reveals distinct procurement and integration strategies.
- OEMs:Automotive Original Equipment Manufacturers integrate ultracapacitor modules directly into their vehicle platforms, often engaging in co-development partnerships with manufacturers to create application-specific solutions. OEMs demand robust, reliable components that meet stringent automotive qualification standards.
- Tier-1 Suppliers:These suppliers develop and deliver integrated ultracapacitor systems or sub-assemblies to OEMs, often managing the complex system integration and testing processes. Tier-1 suppliers are critical intermediaries, pulling demand from OEMs for advanced energy storage solutions.
- Aftermarket Providers:These entities supply ultracapacitor products for vehicle upgrades, replacements, or specialized modifications outside of original factory installations.
- Vehicle Assemblers:These companies focus on the final assembly of vehicles, integrating components and systems sourced from various suppliers, including ultracapacitor modules.
OEMs command substantial purchasing power. Tier-1 Suppliers follow a steep expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive ultracapacitor market exhibits a complex export-import balance, shaped by regional manufacturing capabilities and distinct policy incentives. This dynamic influences the flow of advanced energy storage components across major automotive hubs. Different continents contribute uniquely to the market's overall supply and demand equilibrium.
China
China's robust New Energy Vehicle (NEV) production drives substantial demand for automotive ultracapacitors. MIIT mandates for NEV production create a massive, policy-driven market. The Yangtze River Delta region, a key NEV manufacturing cluster, integrates ultracapacitors into hybrid and electric powertrains.
United States
United States demand is propelled by widespread 48V mild-hybrid systems and regenerative braking. The US EPA's stringent fuel economy targets directly incentivize energy recovery technologies. Michigan's automotive hub actively deploys ultracapacitor systems for enhanced vehicle efficiency.
Germany
German automotive manufacturers integrate ultracapacitors into performance EVs and commercial vehicles, requiring high power density. Europe's forthcoming Euro 7 regulations compel automakers to employ energy recovery systems for compliance. Bavaria, a central region for automotive innovation, fosters extensive R&D in ultracapacitor applications.
Japan
Japanese automotive OEMs increasingly leverage ultracapacitors for hybrid vehicle efficiency and advanced start-stop systems. METI initiatives support clean energy vehicle technologies, including advanced energy storage. The Nagoya region, a prominent automotive R&D and production center, drives innovation in ultracapacitor integration.
South Korea
South Korea's expanding electric vehicle production and focus on high-power density applications fuel ultracapacitor adoption. Government support for battery and energy storage innovation encourages advanced capacitor technologies. Gyeonggi Province, home to major automotive and electronics companies, serves as a hub for developing next-generation energy solutions.
Automotive Ultracapacitor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical materials and modules. The market exhibits a tiered structure, with specialized material science innovators supplying advanced components to larger module manufacturers. Strategic archetypes include established electronics conglomerates, high-tech startups focused on novel materials, and automotive-centric component suppliers. Dominant competitive moves involve securing long-term strategic partnerships with OEMs and expanding manufacturing capacity to meet future demand.
Within the high-performance segment, Maxwell Technologies exemplifies a firm leveraging established intellectual property to secure OEM partnerships for integrated solutions. Skeleton Technologies, a European specialist, represents an archetype focused on graphene-based ultracapacitors for performance-critical applications, pushing power density limits. Panasonic Holdings Corporation, a Japanese electronics conglomerate, occupies a position anchored by its extensive manufacturing scale and deep supply chain control across diverse automotive applications.
| Leading Market Players |
|---|
| Nippon Chemi-Con Corporation |
| TDK Corporation |
| Panasonic Holdings Corporation |
| Ioxus |
| LS Mtron |
| Maxwell Technologies |
| KEMET Corporation |
| Yunasko |
| Skeleton Technologies |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's expanding ultracapacitor manufacturing capacity directly influences downstream pricing power for automotive energy storage solutions. This concentration of production capabilities shapes cost structures and availability across key automotive markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for automotive ultracapacitors. Price differentiation stems from performance specifications, such as power density and cycle life, and the level of automotive qualification standards achieved. Pricing pressure stems from the continuous advancements in lithium-ion battery technology, which presents a persistent substitution threat. Tier-1 suppliers integrating ultracapacitors into high-volume mild-hybrid systems exhibit the most significant price sensitivity.
Supply Chain Analysis
Established electronics conglomerates and specialized material science firms hold significant manufacturing capacity for automotive ultracapacitors. Geographic supply concentration centers on China, Japan, and South Korea, which are major producers of advanced electronic components. The supply chain draws from critical raw materials including activated carbon and carbon nanotubes. Commodity price volatility for these specialized materials represents a structural risk. Distribution channels primarily run through direct sales to automotive OEMs and Tier-1 suppliers, often involving co-development partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive ultracapacitor market is undergoing a platform-economics inflection, driven by the need for seamless interoperability within hybrid energy storage systems and vehicle electrical architectures.
For Market Incumbents:Pre-empt market share erosion from advanced battery solutions by deepening co-development partnerships with major automotive OEMs and Tier-1 suppliers. Expand manufacturing capacity in strategic regions like Europe and North America to meet localized demand and regulatory requirements. Invest in R&D for next-generation graphene-based materials to maintain a performance edge against emerging entrants. Achieve IATF 16949 certification across all product lines to reinforce automotive-grade reliability.
For New Entrants and Emerging Players:Pursue white-space opportunities in heavy-duty commercial vehicles and grid stabilization for fast-charging infrastructure. The niche segment of performance-critical applications, where high power density is paramount, remains most penetrable. Develop specialized graphene-based ultracapacitors with application-specific integration expertise as a focused go-to-market angle. Target regions with strong policy support for EV infrastructure development, such as parts of the US and EU.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among ultracapacitor manufacturers offering integrated, application-specific solutions to Tier-1 suppliers. The long-term viability of this market is strong, driven by global emissions mandates and ongoing vehicle electrification over the next decade. Identify specialized material science innovators or system integrators with robust intellectual property portfolios as prime acquisition targets. Accelerated adoption of hybrid energy storage systems in mainstream vehicle platforms signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Establishes common interfaces for easier integration into diverse vehicle architectures. |
| Advanced Material R&D | Pushes performance boundaries for power density and cycle life, creating competitive advantages. |
| Manufacturing Capacity Expansion | Ensures supply security and cost efficiencies to meet escalating demand from EV production. |
| Hybrid Energy Storage System Integration | Optimizes vehicle performance by combining ultracapacitors with batteries for balanced power and energy. |
| OEM Co-development Partnerships | Secures long-term supply contracts and tailors solutions to specific automotive application needs. |
Research Approach
A spread of perspectives from automotive OEM procurement leads, Tier-1 system engineers, ultracapacitor material scientists, and EV charging infrastructure developers converged on the working assumptions. Primary interviews were complemented by secondary validation from sources such as EPA fuel economy reports, EU Green Deal policy documents, MIIT NEV production mandates, and corporate financial filings. This dual approach enabled bottom-up analysis of component demand and top-down validation with market sizing.
Demand-supply-balance modeling projects future ultracapacitor market evolution across the analysis window. The analytical framework incorporates segmentation dimensions including product type, component material, application, end-user, and regional production cluster. CAGRs were derived through regression analysis of historical adoption patterns and projected technology roadmaps. Key industry-specific forecast inputs included projected New Energy Vehicle production volumes and regulatory compliance deadlines.
Sensitivities concentrate around geopolitical shifts impacting critical material supply and faster-than-expected battery technology advancements. Forecasts reflect assumptions documented through extensive research and stakeholder engagement. Cross-checking against published automotive industry production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market