
 Global Automotive Electronic Lock Differential Market | 2026-2036
Global Automotive Electronic Lock Differential Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Electronic Lock Differential Market Intelligence
Modular bundling of electronic locking differentials with all-wheel-drive powertrains is repositioning buyer choice toward integrated driveline packages rather than standalone axle upgrades. Dana Incorporated leverages its vertical integration across axle and driveline components to sustain pricing power in OEM negotiations. ZF Friedrichshafen AG anchors its position through manufacturing scale across European and North American assembly plants. Eaton Corporation specializes in electromechanical locking architectures that differentiate its portfolio from hydraulic alternatives.
An automotive electronic lock differential is a torque-vectoring mechanism that uses clutch packs, electric motors, or solenoid actuators to modulate power distribution between wheels, typically operating with response times under 100 milliseconds to prevent traction loss. The device serves primarily to enhance vehicle stability, off-road capability, and cornering performance in variable terrain conditions. Active locking systems occupy the dominant share of product configurations, while electromechanical technology leads adoption due to its compatibility with 48-volt electrical architectures. Sports utility vehicles and light duty trucks represent the fastest-expanding application categories as consumer preferences shift toward higher-ground-clearance platforms.
NHTSA crashworthiness standards, EPA fuel economy regulations, and EU Green Deal mobility targets collectively shape product development trajectories by mandating lighter driveline components and electrification-ready designs. ECE R13 braking stability requirements and China's GB standards for vehicle dynamics further constrain market access for non-compliant suppliers. Stakeholders must monitor how software-defined vehicle architectures reshape the boundary between mechanical differential hardware and centralized drivetrain control.
Market Dynamics
Automotive electronic lock differential development is being fundamentally reshaped by the mandatory integration of 48-volt electrical architectures across premium vehicle platforms, forcing suppliers to redesign actuator and clutch pack specifications for higher voltage tolerance.
Growth Catalysts
- NHTSA Fuel Economy Mandates:Tightened corporate average fuel economy standards are compelling OEMs to adopt lighter electromechanical differentials that reduce driveline mass compared to hydraulic alternatives.
- Electrified Powertrain Proliferation:The expansion of hybrid and battery-electric platforms requires torque-vectoring systems compatible with regenerative braking and multi-motor configurations.
- China:Domestic SUV production in China concentrates sourcing decisions for electronic locking systems, with local assembly plants driving volume demand for integrated AWD packages.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price fluctuations directly impact electric motor actuator costs, compressing margins for electromechanical system suppliers.
- German Supplier Concentration:Critical clutch pack and precision gear manufacturing remains concentrated in Baden-Württemberg and Bavaria, creating geographic supply risk.
- Thermal Management Limitations:Current solenoid actuator designs face heat dissipation constraints under sustained high-torque conditions, limiting deployment in heavy-duty commercial applications.
Strategic Opportunities
- India:Underpenetrated AWD adoption in India's compact SUV segment offers white space for cost-optimized electronic locking differentials as PLI scheme incentives expand local manufacturing.
- Software-Defined Vehicle Convergence:Centralized drivetrain control architectures are converging with electronic differential hardware, enabling over-the-air calibration updates and predictive traction management.
- EU Green Deal Mobility Targets:Carbon border adjustment mechanisms and fleet emission mandates create regulatory tailwinds for lightweight driveline components that improve vehicle efficiency metrics.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of engineers with combined expertise in real-time control algorithms and automotive functional safety (ISO 26262) is delaying product development cycles.
- Legacy CAN Bus Integration:Electronic locking differentials must maintain backward compatibility with existing vehicle network architectures while transitioning to Ethernet-based zonal controllers, adding validation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Electronic Lock Differential Market |
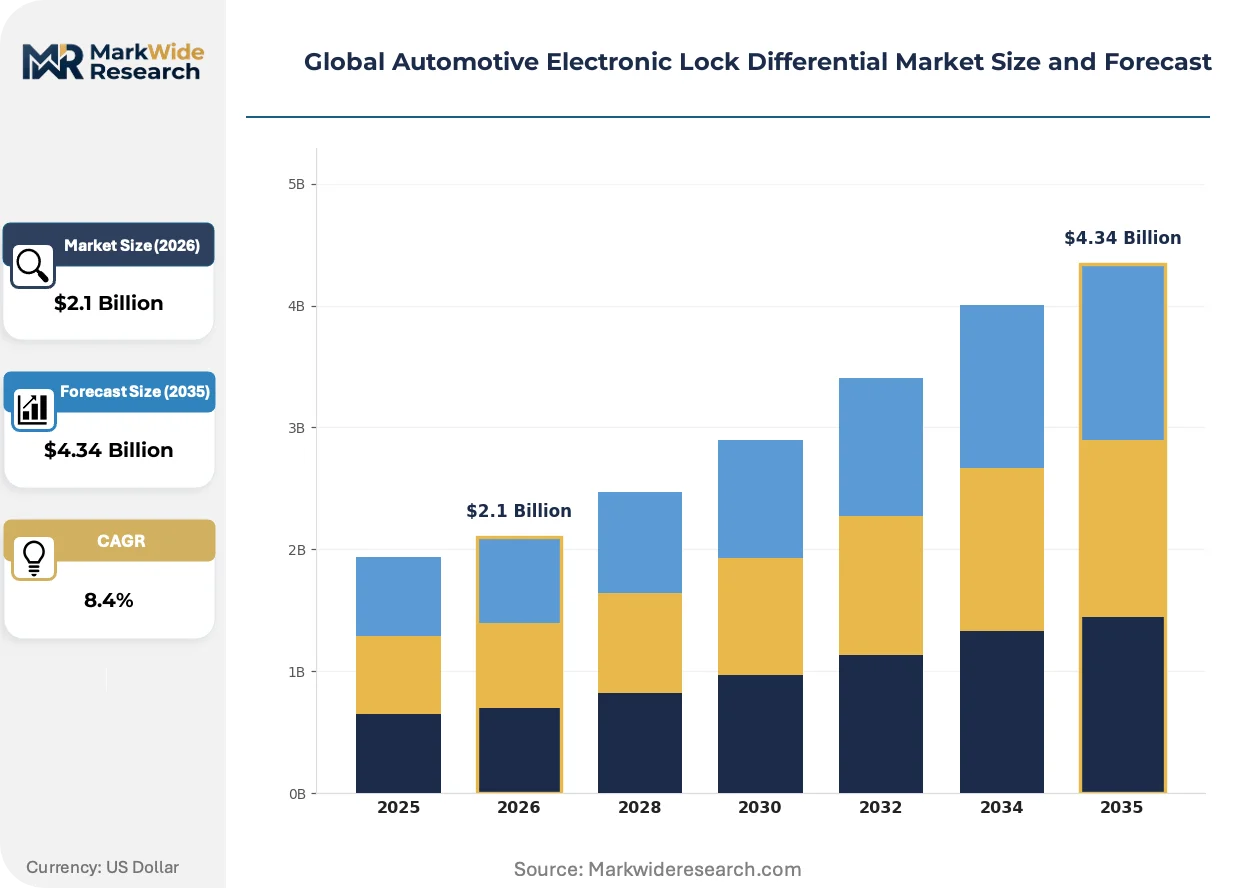
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Locking, Passive Locking, Electronic Control Unit, Electronically Controlled Actuator Technology: Electromechanical, Electrohydraulic, Electrohydrostatic, Electromagnetic Application: Sports Utility Vehicles, Light Duty Trucks, Commercial Vehicles, Off-Road Vehicles, Passenger Cars End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Dana Incorporated, JTEKT Corporation, ZF Friedrichshafen AG, HYUNDAI WIA CORP., American Axle & Manufacturing, Eaton Corporation, BorgWarner Inc., Linamar Corporation, GKN Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Electronic Lock Differential Market Strategic Shifts & Innovations
Three interconnected developments are reshaping how electronic locking differentials are engineered, validated, and procured across the automotive value chain.
Electromechanical actuator technology is converging with 48-volt mild-hybrid architectures to enable faster torque modulation and reduced energy consumption. European luxury OEMs are adopting these integrated systems at accelerated pace for their next-generation SUV platforms. This voltage migration is compressing the competitive window for hydraulic locking alternatives that cannot achieve equivalent response times.
EPA emissions certification protocols now require driveline efficiency testing under standardized load cycles, forcing suppliers to optimize clutch pack engagement algorithms for minimal parasitic loss. The industrial consequence is a shift toward predictive locking strategies that anticipate traction needs rather than reactive slip-based activation. Heavy-duty pickup applications in the United States face the most stringent compliance timelines, with 2027 model year certifications already underway.
Fleet procurement departments are consolidating supplier relationships around full driveline system integrators rather than standalone axle component vendors. Tier 1 suppliers with captive axle, differential, and control module production are displacing multi-vendor assemblies in North American truck platforms. This concentration pattern is most visible in commercial fleet renewals where total cost of ownership calculations favor single-source warranty and service agreements.
Global Automotive Electronic Lock Differential Market Segmentation
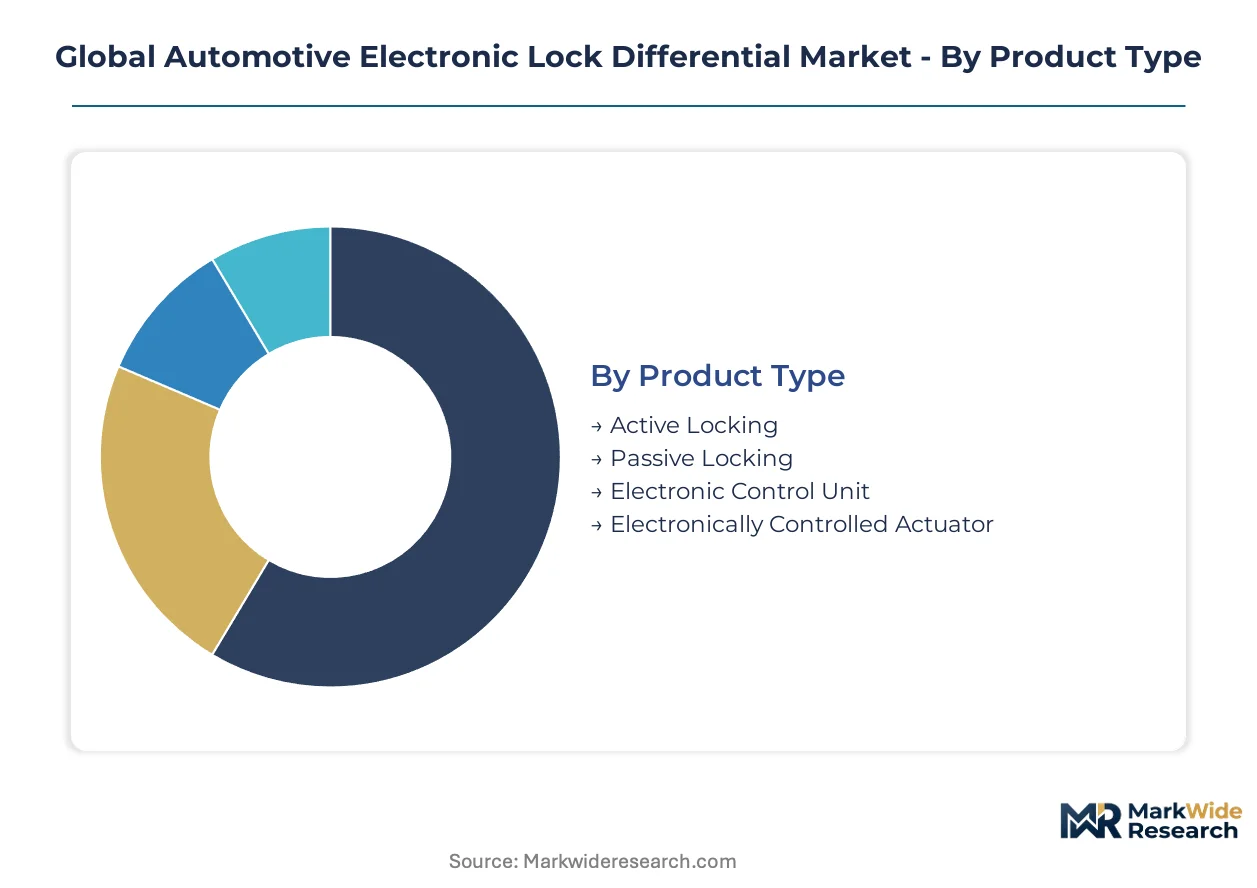
Electronic lock differential configurations vary dramatically in actuator complexity and software content, creating distinct investment profiles across product tiers. OEM procurement strategies increasingly favor bundled architectures that consolidate mechanical hardware with control electronics.
Product Type:
Capital intensity peaks in segments requiring precision clutch pack manufacturing and embedded control firmware development.
- Active Locking:Clutch packs and electric motors enable real-time torque modulation with sub-100 millisecond response times. Sports utility vehicles in China and the United States absorb the majority of active system volume as AWD platforms proliferate. EPA fuel economy mandates favor these lighter electromechanical alternatives over hydraulic predecessors.
- Passive Locking:Pre-set engagement thresholds reduce sensor count and calibration complexity. Light duty trucks in North American fleets specify passive architectures for cost-sensitive trim levels where predictive traction management is not required.
- Electronic Control Unit:Embedded torque-vectoring algorithms demand ISO 26262 functional safety certification and substantial software validation cycles.
- Electronically Controlled Actuator:Solenoid and motor assemblies require tight tolerance manufacturing to maintain engagement repeatability across thermal cycling.
Active Locking absorbs the bulk of installed capacity; Electronically Controlled Actuator is expanding most quickly as 48-volt architectures proliferate.
Technology:
Electrification readiness separates technologies capable of mild-hybrid integration from legacy hydraulic alternatives facing displacement pressure.
- Electromechanical:Electric motor-driven clutch packs achieve faster engagement with lower parasitic loss than fluid-based systems. European luxury OEMs prioritize electromechanical architectures for next-generation SUV platforms. NHTSA fuel economy mandates accelerate adoption as these systems reduce driveline mass.
- Electrohydraulic:Pump and valve assemblies deliver high torque capacity but suffer thermal management constraints under sustained load. Heavy-duty pickup applications in the United States retain electrohydraulic specifications where maximum locking force outweighs efficiency priorities.
- Electrohydrostatic:Closed-loop fluid circuits enable precise pressure control with reduced pump cycling.
- Electromagnetic:Magnetic particle and eddy current designs serve niche applications requiring frictionless modulation.
Electromechanical dominates current OEM sourcing; Electromagnetic is climbing the fastest as research programs advance solid-state torque transfer concepts.
Application:
Ground clearance and all-weather capability requirements determine which vehicle platforms justify differential hardware premiums.
- Sports Utility Vehicles:Higher ride heights and AWD penetration rates make SUVs the primary volume outlet for electronic locking systems. Domestic production in China concentrates sourcing decisions for integrated driveline packages. Consumer preferences for elevated seating positions sustain platform expansion across price tiers.
- Light Duty Trucks:Fleet procurement departments specify electronic locking for work-truck configurations requiring off-site traction. North American commercial renewals favor full driveline system integrators over standalone axle vendors.
- Commercial Vehicles:Durability requirements and total cost of ownership calculations delay adoption in long-haul segments.
- Off-Road Vehicles:Extreme duty cycles demand reinforced clutch pack materials and enhanced thermal dissipation.
- Passenger Cars:Front-wheel-drive dominance and packaging constraints limit penetration in compact and mid-size segments.
Sports Utility Vehicles command the largest share of current installations; Light Duty Trucks are gaining share fastest as fleet electrification timelines accelerate.
End User:
Integration depth and warranty liability exposure vary sharply across the supply chain tier.
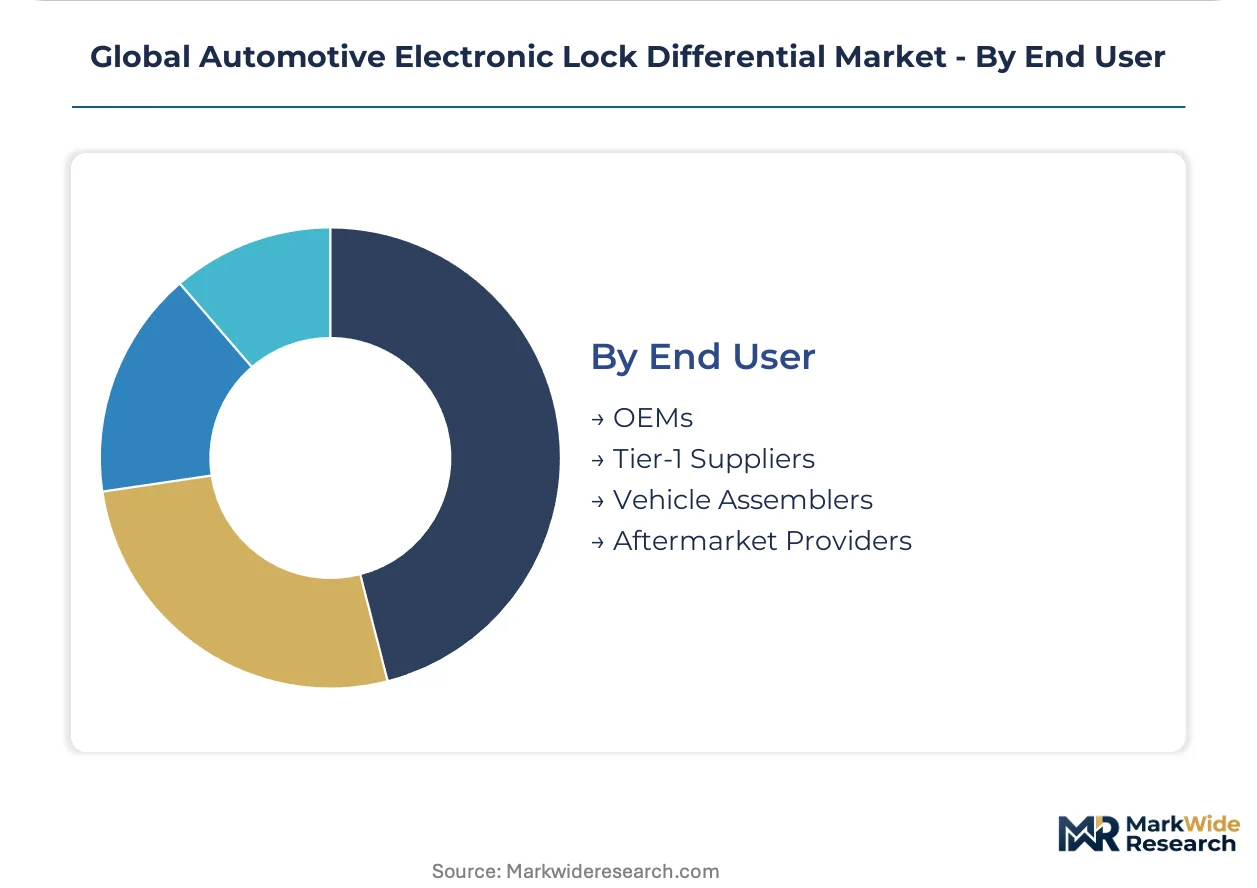
- OEMs:Brand-owning manufacturers specify differential performance targets and calibration parameters for proprietary vehicle platforms. German and US-based OEMs concentrate strategic sourcing decisions for premium AWD systems.
- Tier-1 Suppliers:Full driveline integrators with captive axle and control module production are displacing multi-vendor assemblies. ZF Friedrichshafen and Dana leverage manufacturing scale across European and North American plants.
- Vehicle Assemblers:Contract manufacturers rely on Tier-1 subsystem deliveries with limited design authority.
- Aftermarket Providers:Retrofit kits face compatibility validation challenges across fragmented vehicle architectures.
Tier-1 Suppliers capture the majority of value-added production; Aftermarket Providers are expanding most quickly as vehicle aging populations sustain replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of electronic locking differential hardware while the United States and Germany concentrate OEM specification authority. Domestic SUV assembly in China absorbs substantial component volume. German and US-based automakers drive technology roadmaps through platform-level integration decisions.
United States
Heavy-duty pickup platforms and premium SUV segments anchor demand for electronic locking differentials across Detroit Three lineups. NHTSA fuel economy mandates compress timelines for lightweight electromechanical alternatives to replace hydraulic legacy systems. Manufacturing clusters in Michigan and Ohio concentrate axle assembly operations serving North American truck platforms.
Germany
Luxury OEMs headquartered in Stuttgart and Munich specify next-generation torque-vectoring architectures for performance SUV derivatives. EU Green Deal mobility targets and fleet emission mandates favor driveline components that reduce parasitic loss. Baden-Württemberg hosts precision gear and clutch pack manufacturing that supplies Tier-1 integrators across Europe.
China
Domestic SUV production by state-owned and private automakers drives volume demand for cost-optimized electronic locking systems. GB standards for vehicle dynamics and the country's dual carbon goals shape supplier qualification requirements. Yangtze River Delta assembly plants concentrate sourcing decisions for integrated AWD packages targeting domestic consumers.
Japan
Keiretsu-affiliated suppliers serve hybrid platform programs requiring torque-vectoring compatibility with regenerative braking. METI industrial policy supports electrification-ready driveline component development through targeted R&D incentives. Kanto and Kansai manufacturing belts maintain precision actuator production for domestic and export-bound vehicle platforms.
India
Compact SUV segments show rising AWD penetration as consumers prioritize all-weather capability in emerging markets. PLI scheme incentives expand local manufacturing capacity for automotive driveline components. Tamil Nadu and Maharashtra assembly corridors attract Tier-1 investment for integrated axle and differential production.
Global Automotive Electronic Lock Differential Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the electronic locking differential value chain. The supplier base organizes into three tiers: full driveline system integrators with captive axle production, standalone differential component specialists, and control module electronics vendors. Strategic differentiation hinges on backward integration into precision gear manufacturing and software-defined calibration capabilities. Competitive moves center on manufacturing scale expansion and strategic partnerships with 48-volt electrical architecture suppliers.
Within the full-system integrator tier, Dana Incorporated and ZF Friedrichshafen AG occupy positions defined by manufacturing footprint breadth across multiple continents. Eaton Corporation exemplifies the electromechanical specialization archetype. These three anchors demonstrate how supplier positioning stratifies between bundled driveline packages and standalone component sales to OEM procurement departments.
| Leading Market Players |
|---|
| Dana Incorporated |
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| HYUNDAI WIA CORP. |
| American Axle & Manufacturing |
| Eaton Corporation |
| BorgWarner Inc. |
| Linamar Corporation |
| GKN Automotive |
| Others |
Cost & Logistics Intelligence
Captive in-house production of precision clutch packs and control modules anchors both supply security and pricing power for full driveline integrators serving OEM procurement departments. This backward integration pattern insulates Tier-1 suppliers from raw material volatility while compressing margins for standalone component vendors competing on spot-market terms.
Pricing Analysis
Cost-down pressure on electromechanical actuator tiers accelerates because OEMs mandate 48-volt compatibility without commensurate price premiums. Three-tier pricing structure across premium, standard, and economy levels separates full-system integrators from module suppliers and aftermarket retrofit providers. Price differentiation traces to ISO 26262 certification grade and captive manufacturing scale. Fleet procurement departments exhibit highest price sensitivity; luxury OEM platform engineering teams prioritize performance metrics over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated AWD packages, bypassing traditional distribution layers. Manufacturing concentrates in Germany, China, and the United States for precision gear and clutch pack production. Rare earth magnet supply for electric motor actuators draws from concentrated mining jurisdictions, creating single-source vulnerability for neodymium and dysprosium feedstock. Distribution runs through Tier-1 system integrators with captive axle assembly rather than fragmented multi-vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive electronic lock differential sector sits in a technology-transition phase as electromechanical architectures displace electrohydraulic legacy systems across premium SUV platforms.
For Market Incumbents: Deepen backward integration into precision gear manufacturing to defend margin position against rare earth cost volatility and emerging pure-play actuator specialists. Secure long-term offtake agreements with 48-volt electrical architecture suppliers to lock in component compatibility roadmaps. Expand manufacturing footprint in Yangtze River Delta assembly corridors to capture China domestic SUV volume growth. For New Entrants and Emerging Players: The mid-tier price-point gap between premium European electromechanical systems and economy passive locking alternatives offers entry space for cost-optimized active locking architectures. Target India's compact SUV segment where AWD penetration remains underdeveloped and PLI scheme incentives reduce capital barriers. Pursue joint development agreements with domestic Chinese automakers seeking import substitution for integrated driveline packages. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified automotive conglomerates seeking full driveline integration capabilities. Long-term viability favors suppliers with software-defined vehicle calibration expertise and captive manufacturing across multiple regional production clusters. Monitor NHTSA fuel economy mandate compliance timelines as inflection indicator for electromechanical adoption acceleration versus hydraulic system retention.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around 48-volt architectures reduces validation burden for Tier-1 suppliers. |
| Battery Supply Agreement | Mild-hybrid driveline integration requires coordinated cell procurement for torque-vectoring motor power. |
| Software-Defined Vehicle Investment | Predictive traction algorithms demand over-the-air calibration capabilities separate from hardware sales. |
| Geographic Manufacturing Footprint | Regional assembly plants in Michigan, Baden-Württemberg, and Shanghai reduce logistics exposure. |
| Charging Infrastructure Partnership | Electric vehicle platform convergence requires differential compatibility with regenerative braking protocols. |
Research Approach
Vehicle production databases, IHS Markit registration data, and SEC filings from publicly traded driveline suppliers formed the secondary backbone of this analysis. Primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across installed base evolution and content-per-vehicle trajectories informed the analytical framework over the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from slope analysis of normalized adoption curves against regulatory compliance timelines and technology substitution rates.
Inputs from OEM platform engineering disclosures and Tier-1 supplier capacity announcements were available through the study window; gaps in proprietary calibration algorithm development timelines introduce uncertainty bands around software-content value projections. Forecasts reflect documented assumptions regarding electrification penetration and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market