
 India Automotive Camera Market | 2026-2036
India Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Camera Market Foresight
Fleet operators and commercial vehicle aggregators are redrawing procurement priorities for automotive camera systems in India. Robert Bosch GmbH leverages its Pune technical center to localize ADAS camera calibration for Indian road conditions. Motherson anchors supply contracts with domestic OEMs through its integrated electronics and vision component manufacturing. Continental AG competes on thermal management expertise for cameras operating in India's extreme ambient temperature ranges.
An automotive camera is an electro-optical sensor assembly comprising a CMOS image sensor, molded glass or plastic aspheric lens, and digital signal processor, engineered to capture real-time visual data for vehicle surround-view imaging, obstacle detection, and automated braking activation. ADAS cameras and 360-degree camera systems lead volume absorption as Indian OEMs integrate lane departure warning and collision avoidance features into mid-range passenger vehicles. Machine vision technology differentiates supplier portfolios, while aftermarket providers occupy a fragmented but expanding channel serving vehicle retrofit demand outside factory warranty ecosystems.
The Ministry of Road Transport and Highways mandates AIS-153 compliance for rear-view visibility systems, while the Automotive Research Association of India certifies camera performance under CMVR technical standards. BIS mark requirements for electronic subcomponents add a domestic conformity layer that filters import-dependent suppliers. Stakeholders must monitor how the proposed Bharat NCAP expansion into active safety scoring reshapes OEM camera specification tiers and tier-1 supplier qualification criteria.
Market Dynamics
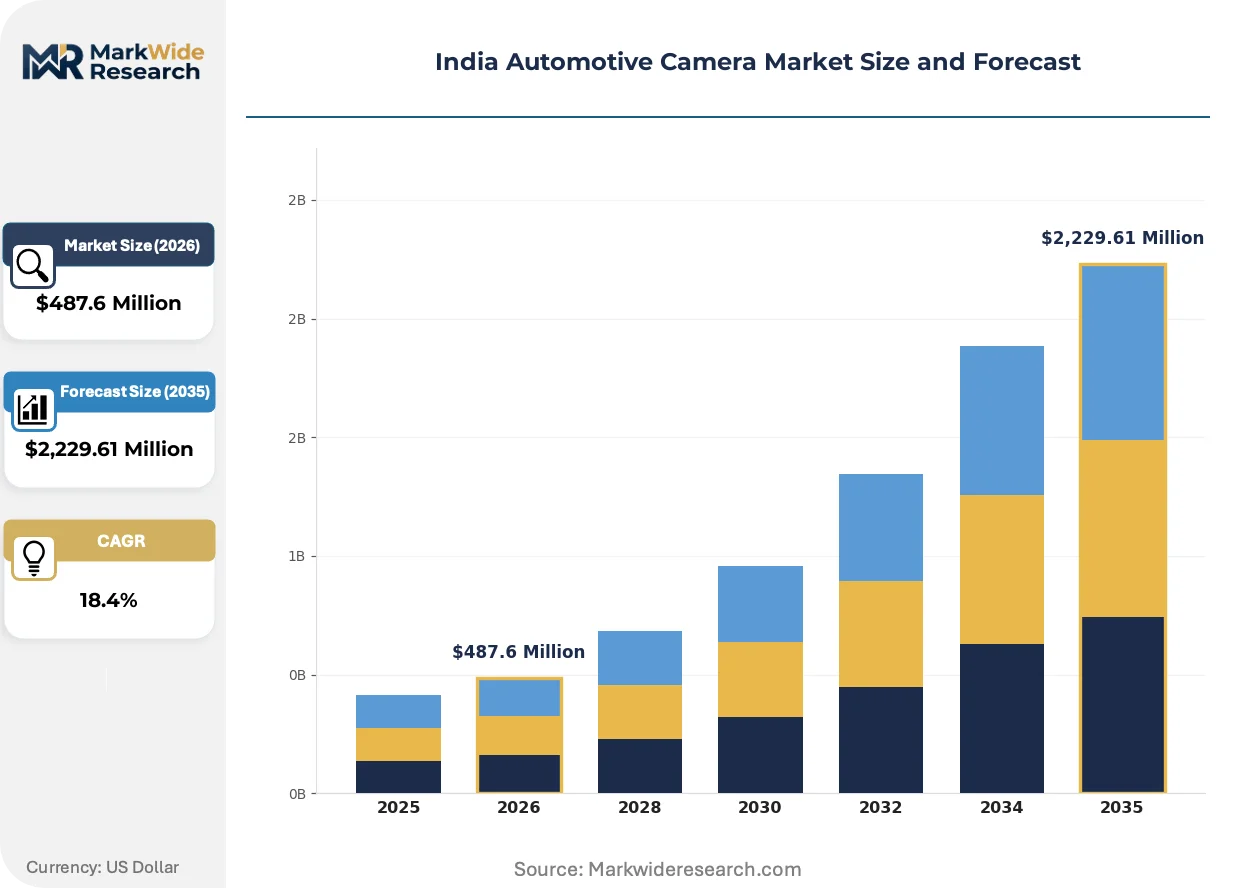
Mandatory rear-view camera regulations under AIS-153 and the proposed Bharat NCAP active safety scoring are compressing OEM specification timelines and forcing tier-1 suppliers to accelerate local calibration capabilities.
Growth Catalysts
- Fleet operator ADAS procurement:Commercial vehicle aggregators deploying highway logistics fleets are mandating forward-facing cameras for collision avoidance, creating sustained volume demand independent of passenger vehicle cycles.
- Bharat NCAP expansion:The proposed active safety scoring protocol will elevate camera-based features from optional equipment to baseline compliance requirements across mass-market vehicle segments.
- Tamil Nadu manufacturing concentration:Chennai-Sriperumbudur's integrated electronics corridor enables just-in-time camera module assembly for OEMs operating within 150-kilometer supply radii.
Market Restraints
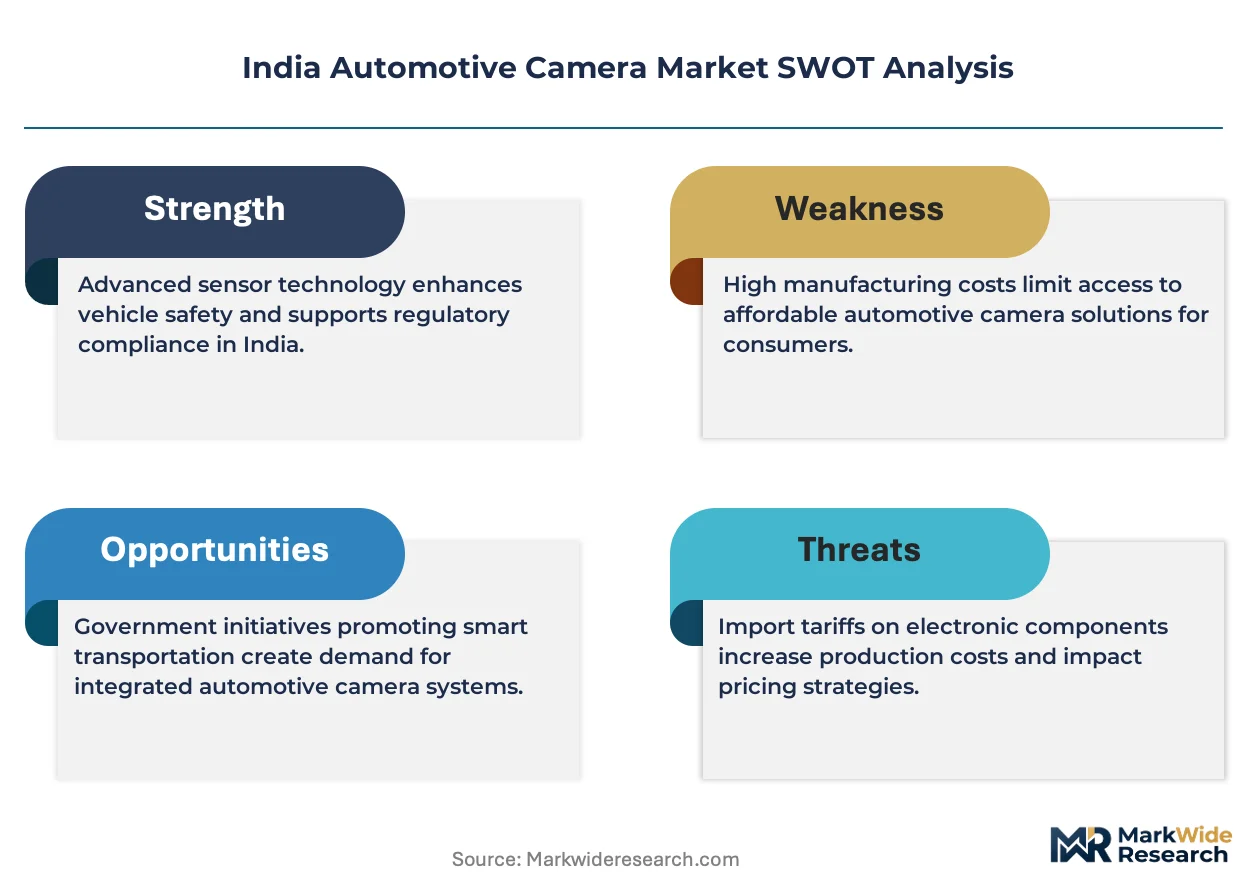
- CMOS sensor import dependency:Domestic camera assembly relies on semiconductor imports subject to DGFT licensing variability and rupee-dollar exchange volatility.
- BIS certification timelines:Bureau of Indian Standards mark acquisition for electronic subcomponents extends supplier qualification cycles by four to six months versus unmarked import alternatives.
- Glass lens thermal limitations:Molded glass optics experience refractive index drift above 50°C ambient, constraining camera reliability in Rajasthan and Gujarat summer operating conditions.
Strategic Opportunities
- Maharashtra automotive corridor localization:Pune-based technical centers can anchor ADAS camera calibration for Indian road geometries, reducing dependence on European validation data.
- Aftermarket retrofit channel:Vehicle owners outside factory warranty ecosystems seek 360-degree camera installations through independent service centers, creating a fragmented but high-margin parallel market.
- PLI scheme electronics manufacturing:Production-linked incentive allocations for semiconductor packaging and camera module assembly are attracting component-level investment previously directed to ASEAN hubs.
Industry Challenges
- Embedded vision software talent scarcity:Machine learning engineers capable of optimizing neural networks for Indian traffic pattern recognition command compensation premiums that strain mid-tier supplier R&D budgets.
- Legacy vehicle electrical architecture integration:Camera systems require CAN bus protocol translation layers to interface with decade-old vehicle platforms prevalent in the commercial vehicle parc.
- ARAI certification queue congestion:Automotive Research Association of India testing capacity for camera performance validation under CMVR technical standards creates six-month backlog risks for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Camera Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear-View Camera, 360-Degree Camera, ADAS Camera, Front Camera Technology: Digital Imaging, Lens Technology, Infrared Sensors, Machine Vision End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assembler Feature: Night Vision, Lane Departure Warning, Collision Avoidance, Object Detection |
| Companies Covered | Valeo SA, Aptiv PLC, Robert Bosch GmbH, Autoliv Inc., Denso Corporation, Continental AG, ZF Friedrichshafen AG, Motherson (Samavardhan Motherson Group), Magna International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Camera Market Shifts & Advancements
Machine vision architectures are diverging between edge-processing cameras with embedded neural accelerators and stripped sensors relying on centralized vehicle compute, reshaping supplier value capture models.
CMOS image sensor resolution tiers are fragmenting competitive positioning in the Indian market. Entry-level 1.3-megapixel sensors serve cost-optimized rear-view visibility systems for mass-market hatchbacks. Mid-tier 2-megapixel variants with HDR capability are penetrating compact SUV lane departure warning applications. Premium 8-megapixel sensors with 120-decibel dynamic range are enabling highway autonomous emergency braking for executive sedans, compressing margin structures at the resolution boundary.
BIS mark requirements for electronic subcomponents are tightening import substitution pathways. The Bureau of Indian Standards mandates domestic conformity assessment for power management integrated circuits and lens actuator drivers, filtering suppliers unable to establish local testing partnerships. Tier-1 integrators are responding by qualifying Indian packaging facilities for previously imported die-level components.
Commercial fleet operators are unbundling camera procurement from vehicle acquisition contracts. Logistics aggregators now specify ADAS hardware separately from OEM supply agreements, enabling multi-brand standardization and aftermarket service continuity. This pattern is most visible in Maharashtra's Mumbai-Pune industrial corridor, where fleet management companies negotiate direct camera supplier contracts with independent installation protocols.
India Automotive Camera Market Segmentation
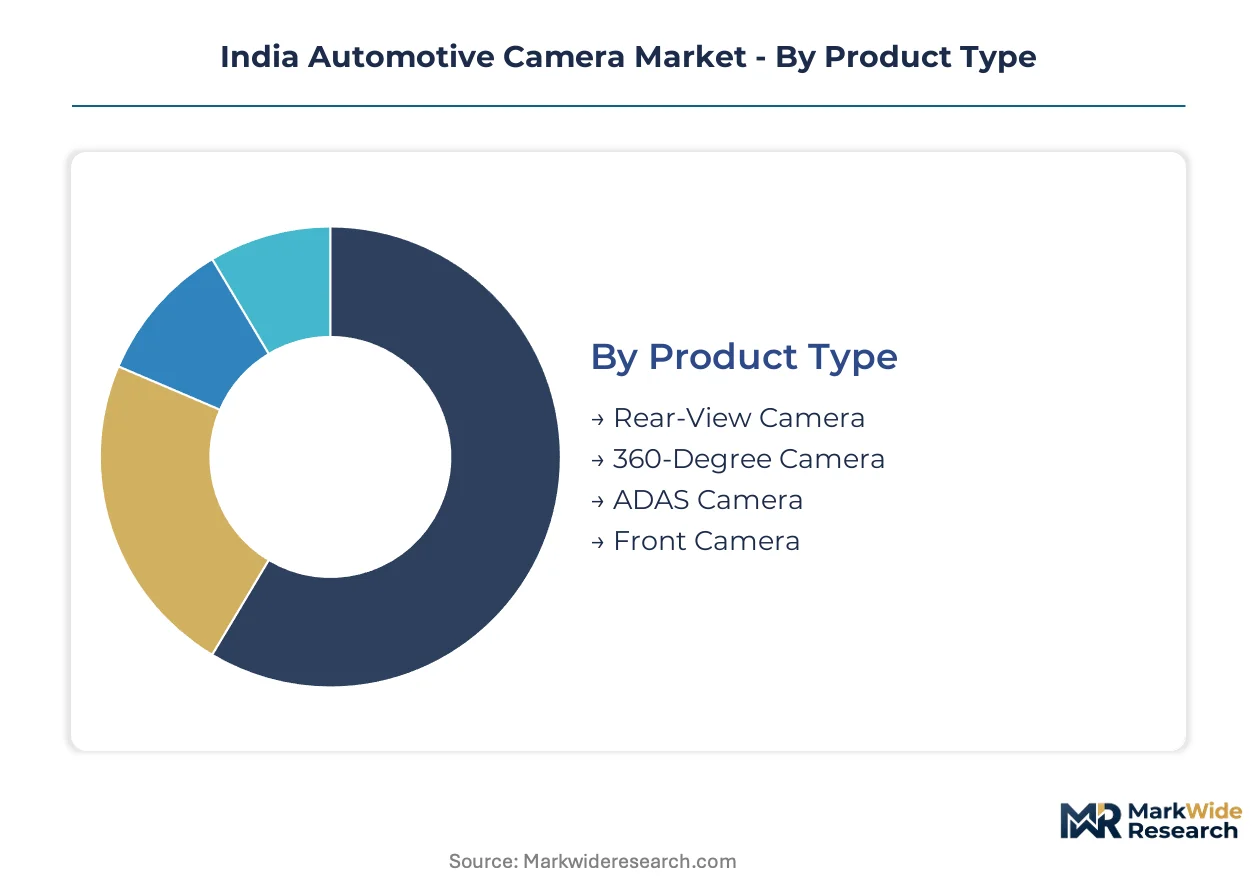
Camera module specification tiers in India diverge sharply between regulatory compliance mandates and discretionary ADAS upgrades. Segment boundaries reflect OEM procurement calendars, BIS certification pathways, and the aftermarket retrofit channel operating outside factory warranty ecosystems.
Product Type:
Margin pools concentrate in ADAS camera systems where embedded vision processing commands premium positioning against commodity rear-view modules.
- Rear-View Camera:CMOS-based visibility systems with 130-degree field-of-view optics serve mandatory AIS-153 compliance for passenger vehicles and commercial fleets. Maharashtra's Pune technical centers calibrate these units for Indian road geometries, though molded glass lens thermal drift above 50°C ambient constrains Rajasthan summer reliability.
- ADAS Camera:Forward-facing stereo configurations with embedded neural accelerators enable lane departure warning and autonomous emergency braking. Tamil Nadu's Chennai-Sriperumbudur electronics corridor anchors just-in-time assembly for OEMs within 150-kilometer supply radii, compressing tier-1 supplier qualification cycles.
- 360-Degree Camera:Multi-sensor surround-view systems synthesize four camera feeds into unified bird's-eye visualization for parking assistance.
- Front Camera:Single-lens units support basic collision warning without full ADAS feature activation.
Rear-View Camera holds installed capacity. ADAS Camera is rotating up the share rankings.
Technology:
Resolution tiers fragment supplier positioning from entry-level 1.3-megapixel sensors through premium 8-megapixel highway braking configurations.
- Machine Vision:Embedded neural network architectures process Indian traffic pattern recognition locally at the camera node, eliminating centralized compute latency. Talent scarcity for ML optimization engineers commands compensation premiums that strain mid-tier supplier R&D budgets in Bengaluru and Hyderabad.
- Digital Imaging:HDR-capable CMOS sensors with 120-decibel dynamic range differentiate executive sedan specifications from mass-market hatchback visibility systems.
- Lens Technology:Molded glass aspheric optics versus plastic alternatives trade thermal stability against cost in Gujarat and Rajasthan operating conditions.
- Infrared Sensors:Low-light enhancement modules extend detection range for night vision feature sets in commercial fleet applications.
Digital Imaging anchors current volume. Machine Vision is climbing the fastest.
End User:
Procurement unbundling by fleet operators is redirecting contract flow from OEM captive supply toward independent tier-1 and aftermarket channels.
- OEMs:Maruti Suzuki, Mahindra & Mahindra, and Tata Motors integrate camera systems at vehicle assembly, specifying BIS-marked subcomponents through qualified tier-1 partnerships. Bharat NCAP active safety scoring proposals are compressing specification timelines across mass-market passenger vehicle segments.
- Aftermarket Providers:Independent service centers in Mumbai-Pune and Delhi-NCR corridors install 360-degree retrofit kits for vehicles outside factory warranty coverage.
- Tier-1 Suppliers:Robert Bosch GmbH, Motherson, and Continental AG qualify directly with OEMs for ADAS camera module supply.
- Vehicle Assembler:Contract manufacturers without full R&D capability source pre-validated camera kits from tier-1 integrators.
OEMs retain volume concentration. Aftermarket Providers are gaining share fastest.
Feature:
Feature bundling decisions reflect Bharat NCAP scoring weightings and fleet operator insurance premium negotiations.
- Collision Avoidance:Forward-facing camera fusion with radar enables autonomous emergency braking, the highest-weighted active safety feature in proposed NCAP protocols. ARAI certification queue congestion creates six-month backlog risks for new product introductions in this category.
- Lane Departure Warning:Edge-detected lane marking recognition requires 2-megapixel minimum resolution for highway reliability.
- Night Vision:Infrared-enhanced low-light detection extends sensor utility beyond visible spectrum limitations.
- Object Detection:Vulnerable road user classification for pedestrian and cyclist recognition in urban traffic conditions.
Collision Avoidance holds specification priority. Lane Departure Warning is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor's western alignment underwrites Maharashtra's procurement dominance, while Chennai's port infrastructure anchors Tamil Nadu's electronics export throughput for camera module assembly.
Maharashtra
Fleet operators along the Mumbai-Pune industrial corridor mandate forward-facing cameras for highway logistics compliance. The state's transport department enforces AIS-153 rear-view visibility standards through RTO inspection protocols. Pune's technical centers calibrate ADAS systems for Indian road geometries, reducing European validation dependency.
Tamil Nadu
OEM assembly plants in Sriperumbudur generate just-in-time demand for camera module supply within 150-kilometer radii. The state's electronics manufacturing policy channels PLI scheme allocations toward semiconductor packaging facilities. Chennai's port infrastructure enables die-level component import for domestic camera assembly.
Gujarat
Commercial vehicle OEMs in Sanand integrate camera systems for Bharat NCAP compliance preparation. The state's industrial development corporation offers capital subsidies for automotive electronics manufacturing. Ahmedabad's testing facilities validate thermal performance specifications for molded glass optics above 50°C ambient.
Karnataka
Bengaluru's machine learning talent pools attract embedded vision software development for traffic pattern recognition. The state's startup policy provides R&D grants for neural network optimization in ADAS applications. Electronics City hosts tier-1 supplier technical centers serving southern OEM corridors.
Haryana
Passenger vehicle OEMs in Manesar specify camera systems for export-compliant safety configurations. The state's automotive hub policy incentivizes component localization through tariff differential protection. Gurgaon's supplier parks enable module assembly proximity to Maruti Suzuki and Honda assembly lines.
India Automotive Camera Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and captive supply arrangements. The supplier base consolidates around three archetypes: diversified automotive electronics conglomerates, pure-play vision system specialists, and integrated component-to-module manufacturers. European and Japanese conglomerates anchor premium ADAS tiers through technical center investments. Domestic private specialists capture aftermarket retrofit volume through service center networks. Competitive moves center on local calibration capability acquisition and BIS certification pathway optimization.
Among diversified conglomerates, Robert Bosch GmbH and Continental AG occupy positions exemplifying European technical center localization strategies. Motherson represents the integrated domestic archetype spanning electronics and vision component manufacturing. These three anchors demonstrate how supplier qualification cycles compress through proximity to Maharashtra and Tamil Nadu OEM assembly clusters.
| Leading Market Players |
|---|
| Valeo SA |
| Aptiv PLC |
| Robert Bosch GmbH |
| Autoliv Inc. |
| Denso Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Motherson (Samavardhan Motherson Group) |
| Magna International Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between fleet operators and tier-1 suppliers lock in both CMOS sensor supply access and price visibility across the Bharat NCAP compliance cycle, insulating procurement from rupee-dollar volatility while compressing margin buffers for uncontracted spot buyers.
Pricing Analysis
Volume-discount tiering structures separate ADAS camera modules from commodity rear-view units by certification grade and resolution specification. Three-tier pricing stratifies across 8-megapixel premium highway braking configurations, 2-megapixel standard lane departure systems, and 1.3-megapixel economy rear-view visibility modules. Cost compression in the economy tier intensifies as domestic assembly scales under PLI scheme allocations, while premium ADAS modules retain pricing power through embedded neural accelerator differentiation. Fleet operators demonstrate lowest price sensitivity due to insurance premium negotiation leverage, whereas independent aftermarket service centers face acute margin pressure from BIS certification overhead.
Supply Chain Analysis
Inventory buffers for CMOS image sensors stretch to twelve-week lead times due to DGFT licensing variability and Taiwan-South Korea semiconductor concentration. Domestic camera assembly draws from die-level imports through Chennai port infrastructure, with molded glass lens supply anchored in China and Japan. Single-source vulnerability in neural accelerator chipsets creates qualification risk for tier-1 suppliers pursuing Bharat NCAP active safety scoring compliance. Distribution runs through just-in-time module delivery within 150-kilometer radii of Maharashtra and Tamil Nadu OEM assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against ultrasonic sensor fusion substitutes that threaten to displace pure camera-based ADAS architectures in cost-optimized vehicle segments, particularly as OEMs face Bharat NCAP compliance cost ceilings.
For Market Incumbents: Secure BIS certification pathway optimization through local testing partnerships, compressing supplier qualification cycles by four to six months against import-dependent competitors. Deepen backward integration into semiconductor packaging facilities under PLI scheme allocations, reducing CMOS sensor import exposure. Anchor technical center investments in Pune for Indian road geometry calibration, creating switching costs against European validation-dependent rivals. For New Entrants and Emerging Players: Aftermarket retrofit service gaps in Delhi-NCR and Mumbai-Pune corridors offer white-space entry where OEM warranty ecosystems exclude vehicle owners seeking 360-degree camera installations. Target commercial fleet aggregators unbundling camera procurement from vehicle acquisition contracts, enabling multi-brand standardization agreements. Pursue direct supplier contracts with independent installation protocols as the primary go-to-market angle, bypassing OEM captive supply channels. For Investors and Strategic Acquirers: Capital is best deployed toward tier-1 integrators with qualified ARAI certification capacity and established OEM supply relationships across the projection horizon. Acquisition targets should demonstrate embedded vision software capability for Indian traffic pattern recognition, where talent scarcity commands compensation premiums. Monitor ARAI testing queue congestion as the inflection signal—backlog expansion indicates supply-constrained pricing power for certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ARAI Certification Capacity Expansion | Reduces six-month backlog risks for Bharat NCAP active safety scoring compliance. |
| PLI Scheme Semiconductor Packaging Investment | Attracts die-level component assembly previously directed to ASEAN manufacturing hubs. |
| Embedded Vision Software Acquisition | Secures machine learning engineering talent for Indian traffic pattern optimization. |
| Aftermarket Service Network Partnership | Captures high-margin retrofit demand outside OEM warranty ecosystems. |
| Tamil Nadu Corridor Manufacturing Footprint | Enables just-in-time delivery within 150-kilometer radii of Sriperumbudur assembly plants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and ARAI certification officials; and secondary validation through vehicle production databases, DGFT import licensing records, BIS conformity assessment registries, and PLI scheme allocation disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive electronics trade flows.
Across the analysis window, the forecasting framework modeled volume and value outputs by vehicle class, propulsion architecture, camera content per vehicle, and regional production cluster. CAGRs derived from segment-level growth trajectory synthesis, with specific inputs including Bharat NCAP regulatory timeline assumptions and fleet operator ADAS procurement intensity patterns.
Material uncertainties — regulatory delay in Bharat NCAP active safety scoring implementation, rupee exchange volatility affecting CMOS sensor import costs, and ARAI testing capacity expansion timelines — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive Esim Market