
 Automotive Magnetic Sensor Market | 2026-2036
Automotive Magnetic Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Magnetic Sensor Market Analytics
Tier-1 suppliers is reorganizing procurement priorities around magnetic sensors for electrified powertrains and advanced driver-assistance architectures. Infineon Technologies dominates silicon-based Hall Effect integration for traction motor commutation. Allegro MicroSystems anchors its position through proprietary packaging that withstands temperatures above 150°C in engine-bay deployments. NXP Semiconductors competes on programmable sensor platforms that reduce OEM calibration cycles.
Automotive magnetic sensors detect field strength, polarity, or position changes through Hall Effect, magnetoresistive, or inductive principles, converting magnetic flux into voltage signals with resolution thresholds below 1 millitesla for crankshaft and camshaft timing applications. Hall Effect Sensors sustain the largest volume footprint due to cost-scaled CMOS fabrication, while Magnetoresistive Sensors capture expanding share in angle-sensing modules where anisotropic magnetoresistance enables sub-degree precision. Fluxgate Sensors occupy niche territory in steering-column torque sensing where drift stability outweighs unit cost.
NHTSA mandates on anti-lock braking and electronic stability control enforce minimum sensor response times, while the EU Green Deal's vehicle emissions benchmarks push magnetic sensing deeper into thermal-management loops. China's MIIT enforces GB standards for new-energy vehicle motor control that specify magnetic encoder redundancy. Stakeholders must monitor how ISO 26262 functional-safety grades reshape supplier qualification timelines and in-house versus outsourced magnetic-sensor design decisions.
Market Dynamics
Powertrain electrification is forcing magnetic sensor architectures to migrate from discrete Hall Effect modules toward integrated magnetoresistive arrays capable of sub-degree angular resolution in high-RPM traction motors.
Growth Catalysts
- EU Green Deal emissions benchmarks:Thermal-management loops in battery electric vehicles now embed redundant magnetic encoders for coolant pump control, expanding sensor counts per vehicle by 40-60% versus internal combustion platforms.
- China's MIIT GB standards:Mandatory magnetic encoder redundancy for new-energy vehicle motor control creates specification floors that only multi-axis sensor modules can satisfy.
- Silicon carbide inverters:Switching frequencies above 20 kHz demand magnetic current sensors with bandwidth exceeding 500 kHz, pulling magnetoresistive technologies into traction inverter housings previously served by shunt resistors.
Market Restraints
- Neodymium price volatility:Rare-earth magnet cost swings of 30-50% annually compress gross margins for position-sensor assemblies that depend on fixed magnetic bias fields.
- Wafer fabrication concentration:CMOS Hall Effect die production clusters in Taiwan and South Korea, exposing supply continuity to geopolitical friction and foundry allocation constraints.
- ISO 26262 ASIL-D certification timelines:Functional safety qualification cycles of 18-24 months delay revenue recognition for new sensor designs targeting steer-by-wire and brake-by-wire systems.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized magnetic sensor manufacturing for two-wheeler electrification and entry-level four-wheeler motor control remains underpenetrated by multinational suppliers.
- Sensor fusion with inductive position sensing:Hybrid architectures combining magnetoresistive and inductive principles address safety-critical applications requiring hardware diversity without full redundancy cost.
- Direct-to-OEM module supply:Tier-1 supplier consolidation in Germany and Japan creates openings for specialized magnetic sensor houses to bypass traditional distribution and contract directly with powertrain integrators.
Industry Challenges
- Magneto-thermal co-design expertise:Shortage of engineers capable of simulating magnetic field drift across -40°C to 180°C operating windows slows product development cycles.
- Legacy 12V architecture integration:Magnetic sensors optimized for 48V mild-hybrid systems require voltage isolation redesigns to maintain compatibility with incumbent vehicle electrical platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Magnetic Sensor Market |
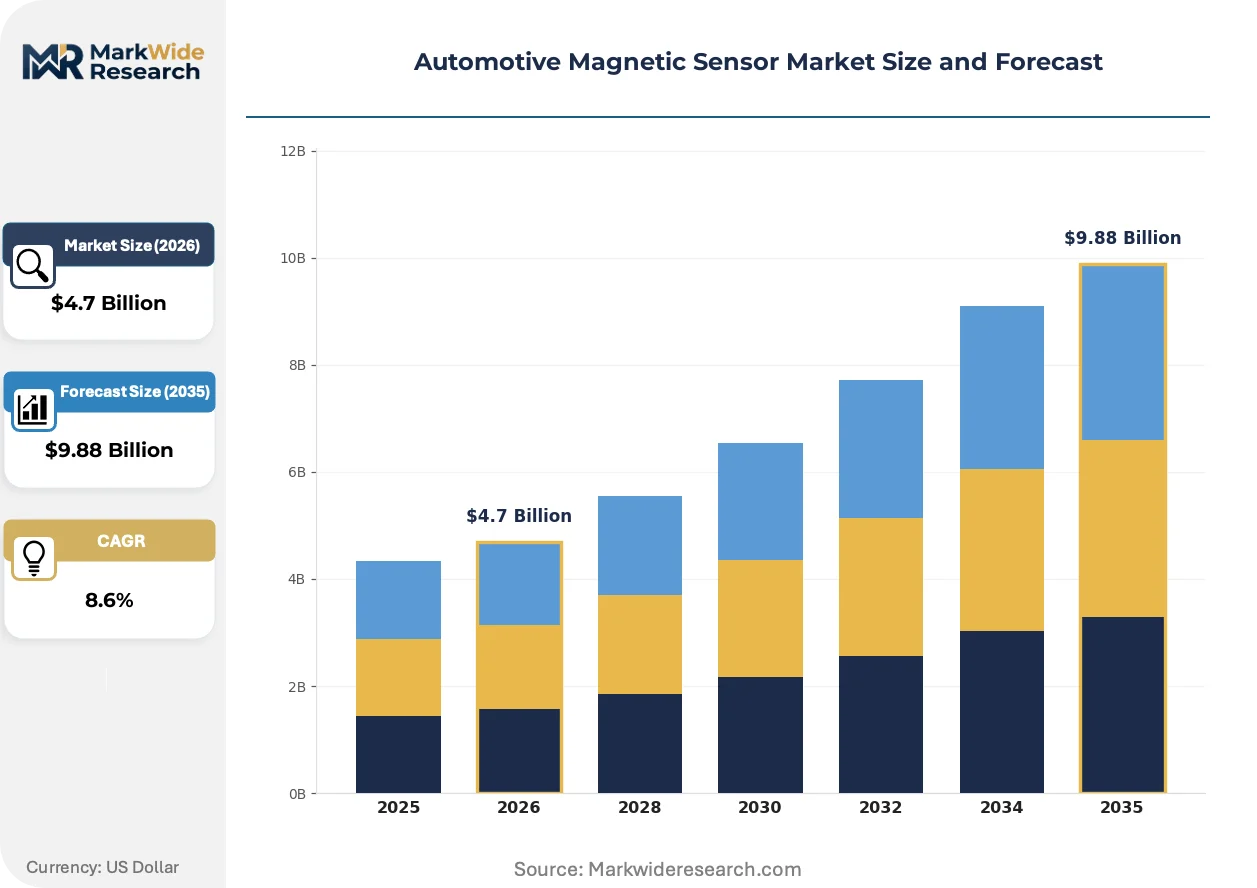
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hall Effect Sensors, Magnetoresistive Sensors, Fluxgate Sensors, Inductive Sensors Application: Position Sensing, Speed Measurement, Anti-lock Braking Systems, Proximity Detection Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Two-wheelers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Automotive Manufacturers |
| Companies Covered | Honeywell International, Infineon Technologies, NXP Semiconductors, Allegro MicroSystems, Texas Instruments, Robert Bosch GmbH, STMicroelectronics, Melexis NV, Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Magnetic Sensor Market Evolving Landscape
Magnetic sensing architectures are bifurcating between cost-optimized Hall Effect dominance in high-volume chassis applications and precision magnetoresistive penetration in electrified powertrains where angular accuracy determines motor efficiency.
TMR (tunnel magnetoresistance) sensors are supplanting AMR (anisotropic magnetoresistance) devices in steering-column torque sensing due to 10x improved sensitivity and inherent temperature stability. Tier-1 chassis suppliers in Germany and Japan have accelerated TMR qualification timelines from 36 to 18 months. This compression is collapsing the addressable market for legacy Hall Effect torque sensors above 5 Nm measurement range.
NHTSA mandates on automatic emergency braking and pedestrian detection are tightening magnetic sensor response-time specifications to sub-100-microsecond thresholds for wheel-speed modules. The regulatory pressure is disqualifying inductive sensor architectures from new platform designs despite their historical cost advantage. Suppliers are responding by migrating Hall Effect signal chains from analog voltage outputs to digital SENT and PSI5 protocols that satisfy deterministic latency requirements.
Powertrain engineering teams are consolidating magnetic sensor procurement under single-source contracts for complete motor position, current, and temperature sensing subsystems. This bundling displaces the historical practice of discrete component sourcing across multiple commodity suppliers. The shift is most pronounced in China's NEV manufacturing corridors, where vertical integration between battery pack and motor control unit suppliers favors sensor houses capable of multi-physics module integration.
Automotive Magnetic Sensor Market Segmentation
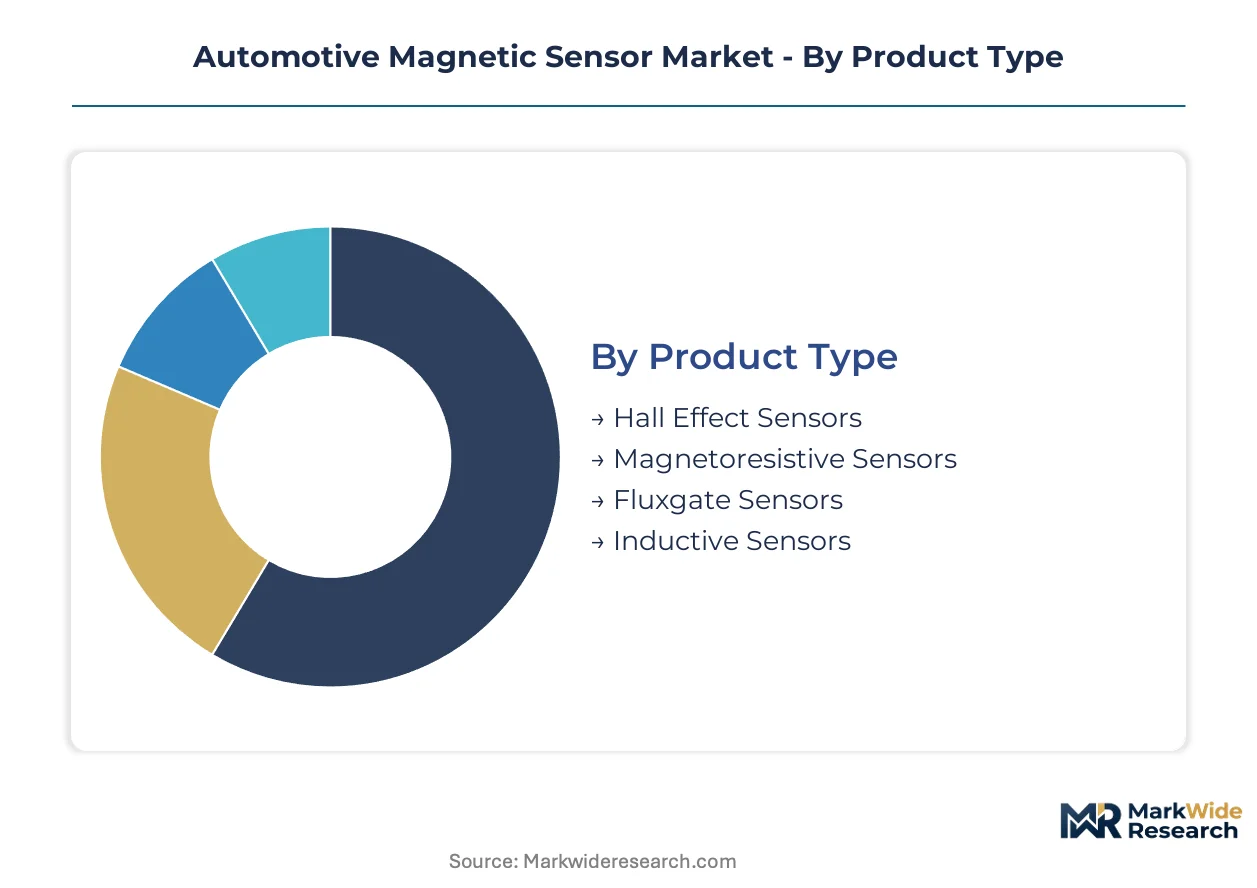
Magnetic sensor architectures fragment across four intersecting dimensions that determine procurement economics and technical qualification pathways. Product type defines the physics of field detection, while application and vehicle type dictate performance thresholds and volume scale.
Product Type:
Highest margins concentrate in magnetoresistive technologies where precision requirements for electrified powertrains justify premium positioning over commodity Hall Effect alternatives.
- Hall Effect Sensors:Silicon-based CMOS fabrication enables sub-millitesla resolution for crankshaft and camshaft timing. Cost-scaled production in Taiwan and South Korea sustains dominance in high-volume chassis applications where response times below 100 microseconds satisfy NHTSA wheel-speed mandates.
- Magnetoresistive Sensors:Anisotropic and tunnel magnetoresistance architectures deliver sub-degree angular precision for traction motor commutation. China's MIIT GB standards for new-energy vehicle motor control are accelerating multi-axis module adoption in Shenzhen and Shanghai manufacturing corridors.
- Fluxgate Sensors:Drift stability across -40°C to 180°C operating windows supports steering-column torque sensing where ISO 26262 ASIL-D grades apply.
- Inductive Sensors:Legacy position detection in transmission systems faces displacement by Hall Effect alternatives as SENT and PSI5 protocol migration accelerates.
The dominant share belongs to Hall Effect Sensors, while Magnetoresistive Sensors is closing the gap fastest.
Application:
Application segmentation tracks functional safety criticality, with position and speed modules commanding qualification premiums over proximity detection.
- Position Sensing:Motor encoder arrays for battery electric vehicle powertrains require redundant magnetic feedback loops. Germany's automotive engineering corridor drives specification tightening for rotor angle accuracy in Munich and Stuttgart development centers.
- Speed Measurement:Wheel-speed modules for anti-lock braking and electronic stability control must satisfy sub-100-microsecond latency thresholds under NHTSA mandates.
- Anti-lock Braking Systems:Sensor fusion architectures combining magnetic and inductive principles address hardware diversity requirements without full redundancy cost.
- Proximity Detection:Door-latch and seat-position sensing operates at lower functional safety grades with reduced calibration overhead.
Position Sensing commands the largest revenue pool, though Speed Measurement exhibits the steepest expansion trajectory from regulatory tightening.
Vehicle Type:
Electrification intensity varies sharply across vehicle categories, with electric vehicles embedding 40-60% more magnetic sensors per platform than internal combustion equivalents.
- Electric Vehicles:Traction motor control, battery thermal management, and onboard charging systems each demand dedicated magnetic sensing subsystems. China's NEV manufacturing hubs in Hefei and Xi'an concentrate procurement volume for multi-physics module integration.
- Passenger Cars:Mild-hybrid 48V architectures create voltage isolation redesign challenges for magnetic sensors maintaining 12V legacy compatibility.
- Commercial Vehicles:Heavy-duty powertrain durability requirements favor magnetoresistive technologies in transmission position sensing.
- Two-wheelers:India's PLI scheme for automotive components is localizing motor control sensor manufacturing for entry-level electrification.
Electric Vehicles holds the dominant position, while Two-wheelers is gaining share fastest from emerging market electrification programs.
End User:
Procurement authority is consolidating under Tier-1 suppliers and direct OEM relationships, compressing aftermarket and discrete component channels.
- Tier-1 Suppliers:Chassis and powertrain integrators in Germany and Japan are bundling magnetic sensor procurement under single-source contracts for complete motor position, current, and temperature subsystems.
- OEMs:Direct contracting with specialized magnetic sensor houses is bypassing traditional distribution in China's vertically integrated NEV supply chains.
- Automotive Manufacturers:In-house versus outsourced magnetic sensor design decisions hinge on ISO 26262 functional-safety grade requirements.
- Aftermarket Providers:Replacement sensor volume concentrates in legacy internal combustion platforms with slower electrification adoption curves.
Tier-1 Suppliers controls the largest procurement volume, though OEM direct engagement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in magnetic sensor procurement for electric vehicle manufacturing. Germany's Rhine-Alpine corridor connects Stuttgart engineering centers to component fabricators across Central Europe. The Port of Los Angeles anchors North American distribution for Hall Effect die shipments from Asian foundries.
China
NEV manufacturing corridors in Hefei and Xi'an concentrate multi-axis magnetic encoder demand for traction motor control. MIIT GB standards mandate redundant sensor architectures that only integrated module suppliers can satisfy. Shenzhen and Shanghai development centers are tightening rotor angle accuracy specifications for domestic EV platforms.
Germany
Munich and Stuttgart automotive engineering clusters drive specification tightening for magnetoresistive position sensing in electrified powertrains. KBA type-approval processes enforce ISO 26262 ASIL-D grades for steer-by-wire magnetic torque modules. The Rhine-Ruhr industrial belt hosts Tier-1 chassis integrators bundling complete sensor subsystems under single-source contracts.
United States
Silicon Valley fabless design houses and Detroit powertrain engineering centers split magnetic sensor innovation between signal processing and automotive qualification. NHTSA mandates on automatic emergency braking enforce sub-100-microsecond response thresholds for wheel-speed modules. Michigan's automotive corridor is consolidating procurement authority under Tier-1 suppliers capable of multi-physics integration.
Japan
Nagoya and Tokyo metropolitan areas anchor magnetoresistive sensor development for hybrid powertrain position detection. METI technology roadmaps prioritize TMR sensor qualification compression timelines. Toyota City and surrounding Aichi prefecture manufacturing clusters are migrating Hall Effect signal chains to digital SENT protocols for deterministic latency compliance.
South Korea
Seoul Capital Area semiconductor foundries supply CMOS Hall Effect die for high-volume chassis applications. Busan-Ulsan automotive component clusters serve Hyundai-Kia motor control unit suppliers with angular encoder modules. Government battery technology initiatives are pulling magnetic current sensors into thermal management loops for domestic NEV platforms.
Automotive Magnetic Sensor Market Competitive Landscape
Concentration sits with diversified semiconductor conglomerates and specialized magnetic sensor houses. Three archetypes dominate: silicon foundry-integrated players leveraging CMOS scale, magnetic sensing specialists with proprietary packaging expertise, and diversified industrial electronics groups cross-selling automotive modules. Competitive moves center on single-source subsystem bundling and direct OEM contracting that bypasses traditional Tier-1 distribution channels.
Among Germany-based diversified technology groups, Infineon Technologies and Robert Bosch GmbH exemplify the foundry-integrated archetype with captive silicon fabrication and automotive qualification depth. Allegro MicroSystems occupies a position within the magnetic sensing specialist tier, its corporate identity signaling dedicated focus on field-detection technologies. These three anchors illustrate how procurement consolidation favors players capable of multi-physics module integration across position, current, and temperature sensing domains.
| Leading Market Players |
|---|
| Honeywell International |
| Infineon Technologies |
| NXP Semiconductors |
| Allegro MicroSystems |
| Texas Instruments |
| Robert Bosch GmbH |
| STMicroelectronics |
| Melexis NV |
| Asahi Kasei |
| Others |
Value Network & Pricing Analysis
ISO 26262 ASIL-D certification gates both supplier qualification and price stratification, forcing magnetic sensor vendors to absorb 18-24 month validation cycles before accessing premium positioning in steer-by-wire and brake-by-wire contracts. This regulatory threshold simultaneously blocks commodity entrants from safety-critical tiers while allowing certified suppliers to command sustained margin premiums over standard-grade alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects ASIL certification grade and volume commitment scale. Premium tiers attach to multi-axis magnetoresistive modules for traction motor control where China's MIIT GB standards mandate redundancy. Cost compression in Hall Effect wheel-speed sensors is intensifying because Taiwan foundry allocation constraints limit die supply elasticity. Aftermarket replacement channels exhibit highest price sensitivity, while OEM direct contracts for integrated powertrain subsystems show lowest.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Rotterdam lane periodically disrupt CMOS Hall Effect die shipments from Asian foundries to European Tier-1 integrators. Taiwan and South Korea anchor wafer fabrication for silicon-based sensors, while Germany and Japan concentrate magnetoresistive packaging expertise. Neodymium permanent magnets for position-sensor bias fields draw from Chinese rare-earth processing clusters. Single-source vulnerability concentrates in 150°C-rated ceramic substrate supply for engine-bay deployments. Distribution runs through direct OEM contracting in China's NEV corridors and bundled subsystem procurement in Germany's Rhine-Ruhr belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification represents a high-growth disruption as silicon carbide inverter adoption above 20 kHz switching frequencies forces magnetoresistive current sensors into traction inverter housings previously served by shunt resistors.
For Market Incumbents: Consolidate procurement relationships through single-source subsystem bundling spanning position, current, and temperature sensing to counter emerging specialized magnetic sensor houses. Deepen backward integration into 150°C-rated ceramic packaging capacity in Germany's Rhine-Alpine corridor to defend margin position against rare-earth magnet cost volatility.
For New Entrants and Emerging Players: Multi-physics module integration services for China's vertically integrated NEV supply chains represent an under-served layer where incumbent semiconductor conglomerates lack agile customization. India's PLI scheme for automotive components offers the most penetrable geography for two-wheeler motor control sensor localization. Pursue direct contracting with Hefei and Xi'an battery pack suppliers bypassing traditional Tier-1 distribution.
For Investors and Strategic Acquirers: EU Green Deal emissions benchmarks reshape the acquisition landscape by accelerating thermal-management sensor demand in battery electric vehicles. Position for 5-10 year viability through magnetoresistive specialists with proven ASIL-D qualification compression capabilities. Monitor TMR sensor qualification timeline compression from 36 to 18 months as the inflection signal for steering-column torque sensing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetoresistive Module Standardization | Reduces OEM calibration cycles for traction motor commutation in Shenzhen manufacturing corridors. |
| Rare-Earth Magnet Supply Agreement | Secures neodymium pricing stability against 30-50% annual volatility for position-sensor assemblies. |
| TMR Sensor Qualification Acceleration | Collapses 36-month timelines to 18 months for steering-column torque sensing in Nagoya clusters. |
| Direct-to-OEM Distribution Bypass | Opens contracting channels with China's vertically integrated NEV powertrain integrators. |
| Multi-Physics Subsystem Bundling | Consolidates procurement authority under single-source contracts for complete motor sensing architectures. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and magnetic sensor R&D leads provided ongoing calibration across primary fieldwork. Secondary validation drew from NHTSA regulatory filings, MIIT GB standard publications, vehicle production databases, and IHS Markit registration data. Bottom-up sensor shipment modeling triangulated against top-down powertrain content-per-vehicle estimates.
Consistency checks against external semiconductor industry benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include sensor physics type, functional safety criticality, vehicle propulsion architecture, content per vehicle tier, and regional production cluster. CAGRs derived from fitted growth curves incorporating silicon carbide inverter penetration rates and NEV adoption trajectories as automotive-specific inputs.
Underlying assumptions cover sustained EU Green Deal enforcement and China's MIIT GB standard continuity, with deviation risk concentrated in rare-earth magnet supply disruptions and Taiwan foundry allocation constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market