
 North America Automotive Lead-Acid Battery Market | 2026-2036
North America Automotive Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Lead-Acid Battery Market Intelligence
Asset-light leasing models for battery recycling infrastructure are reshaping competitive entry in the North America automotive lead-acid battery space. Clarios leverages its closed-loop collection network across the United States and Canada to sustain raw material security. East Penn Manufacturing Company anchors its position through vertically integrated lead smelting and plastic recycling operations in Pennsylvania. EnerSys competes in the commercial vehicle segment with specialized deep-cycle products for fleet electrification programs.
North America automotive lead-acid batteries are electrochemical storage devices employing lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, typically operating at 12 volts with cold cranking amperage ratings between 400 and 1000 A for passenger vehicle starting applications. These units provide burst current for engine cranking, stabilized voltage for onboard electronics, and reserve capacity for accessory loads during alternator failure. Flooded batteries still occupy the largest volume share across OEM and aftermarket channels due to established recycling economics and lower unit costs, though AGM segments are accelerating as original equipment on start-stop vehicles and mild-hybrid architectures. The aftermarket provider channel differentiates through private-label sourcing and regional distribution density rather than manufacturing scale.
The EPA enforces lead emissions limits under the National Emission Standards for Hazardous Air Pollutants, while Transport Canada mandates UN ECE R100 compliance for battery systems in new vehicle homologation. OSHA workplace exposure standards for lead smelting operations shape where new recycling capacity can locate. Stakeholders must monitor how state-level extended producer responsibility frameworks in California and New York evolve collection obligations and recycling rate targets.
Market Dynamics
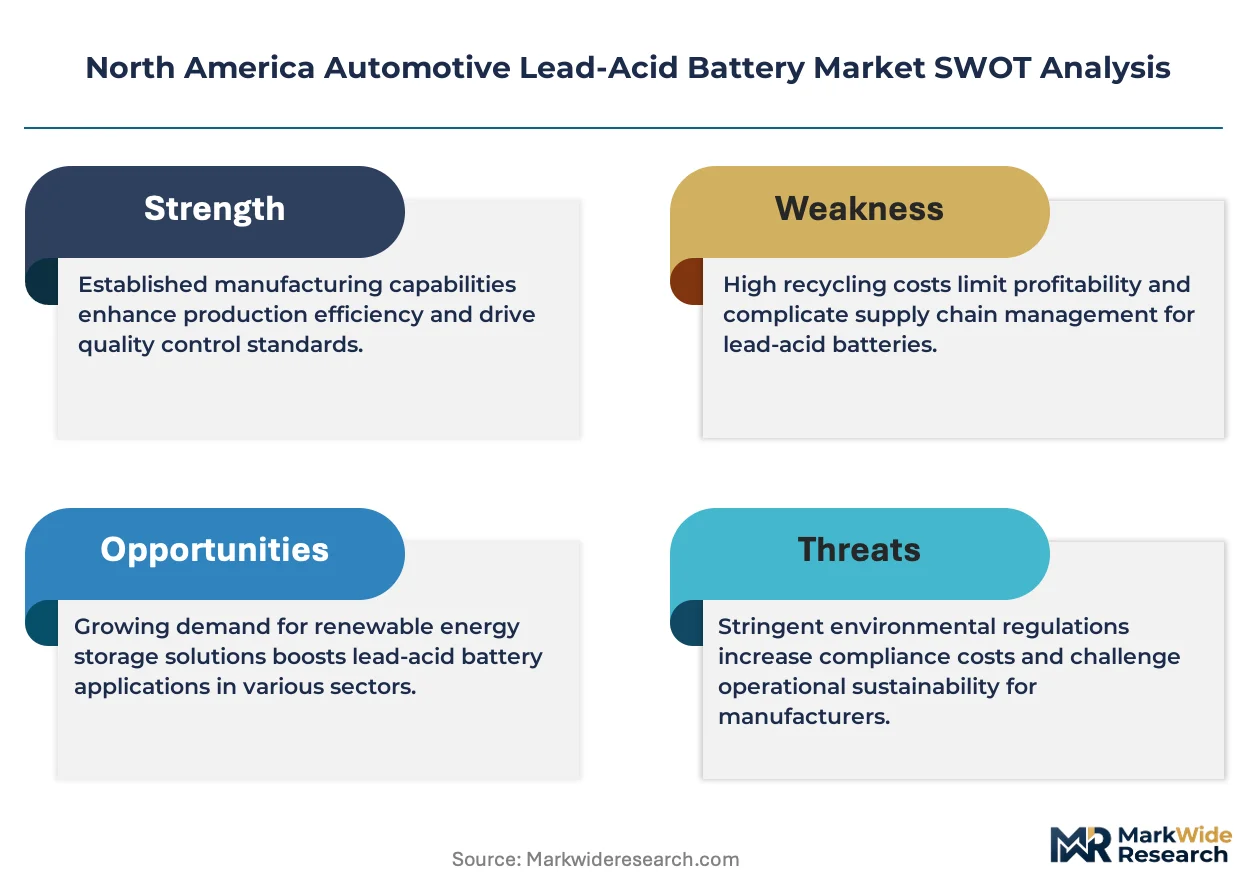
The EPA's tightened National Emission Standards for Hazardous Air Pollutants are compressing manufacturing footprints and forcing capital reallocation toward closed-loop recycling architectures across the United States and Canada.
Growth Catalysts
- Start-stop vehicle electrification:OEMs across Michigan, Ohio, and Indiana are specifying absorbent glass mat batteries for mild-hybrid powertrains, pulling demand from conventional flooded units.
- Extended producer responsibility frameworks:California and New York state-level mandates are tightening collection obligations and recycling rate targets, accelerating infrastructure investment.
- Fleet electrification programs:Mexican commercial vehicle operators are expanding procurement of deep-cycle units for delivery van and last-mile logistics applications.
Market Restraints
- Lead price volatility:Raw material input costs for lead dioxide and sponge lead fluctuate with London Metal Exchange pricing, compressing margin predictability for manufacturers.
- Smelting capacity concentration:Primary lead recycling infrastructure clusters in Pennsylvania and Missouri, creating geographic supply risk for West Coast battery assemblers.
- Lithium-ion substitution:Electric vehicle OEMs are bypassing lead-acid architectures entirely for high-voltage lithium-ion packs in full-electric platforms.
Strategic Opportunities
- Aftermarket private-label channels:Regional distributors in Texas and Florida are building captive sourcing relationships with Mexican maquiladora assemblers to bypass branded premium pricing.
- Closed-loop recycling monetization:The EPA's lead emissions standards create first-mover advantage for operators achieving near-zero discharge certification.
- Commercial vehicle deep-cycle segmentation:Fleet telematics integration is creating demand for smart battery monitoring in long-haul trucking applications.
Industry Challenges
- OSHA lead exposure compliance:Workplace exposure standards for smelting operations restrict greenfield site selection and extend permitting timelines in dense industrial corridors.
- UN ECE R100 homologation:Transport Canada's battery system certification requirements for new vehicle platforms add months to product validation cycles.
- Legacy system integration:Start-stop electronics in vehicles manufactured before 2015 lack voltage stabilization architecture compatible with AGM charging profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Lead-Acid Battery Market |
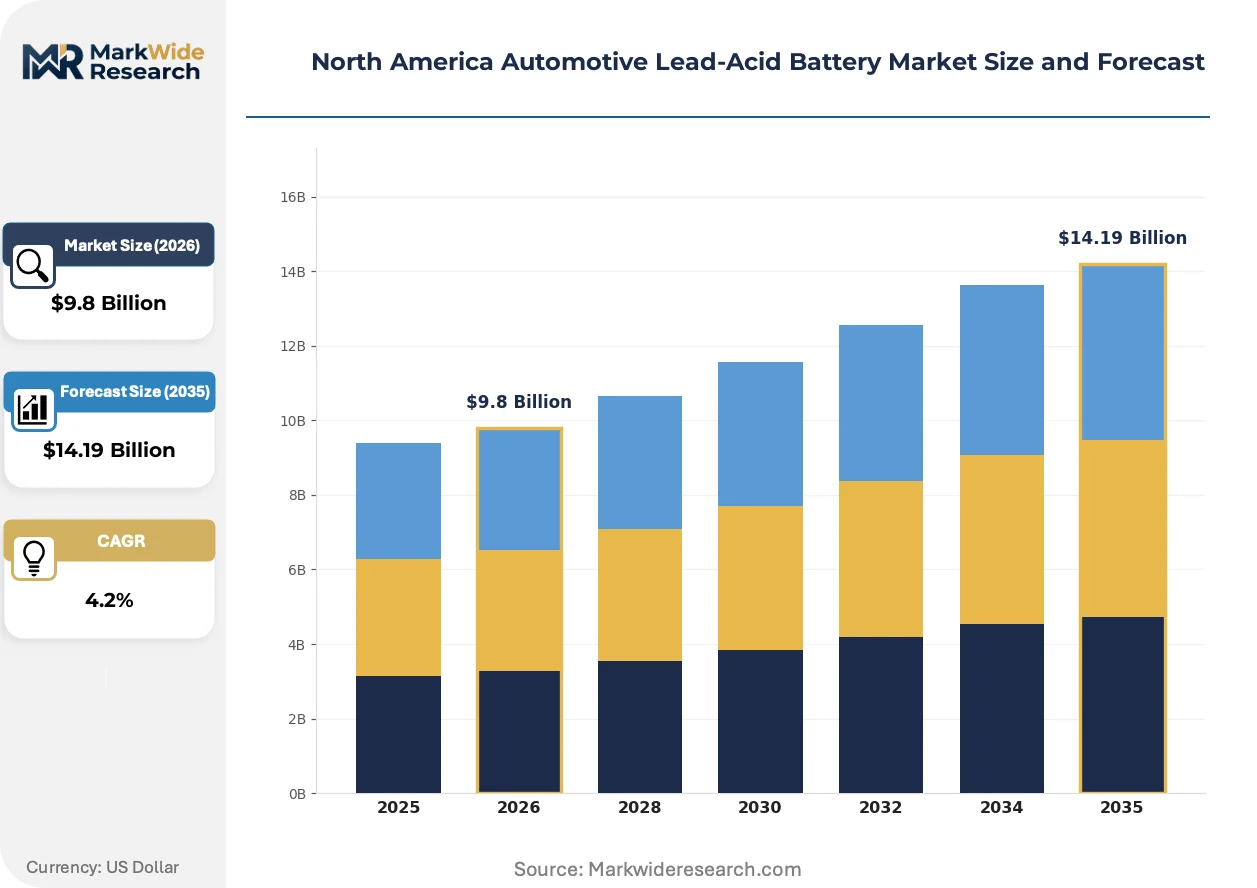
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLA, AGM, Flooded, VRLA End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Application: Starting, Lighting, Ignition, Energy Storage Technology: Conventional, Advanced Lead, Hybrid, Others |
| Companies Covered | Clarios, EnerSys, East Penn Manufacturing Company, C&D Technologies, GS Yuasa Corporation, Exide Technologies, Leoch International Technology, Crown Battery, ATLASBX, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Lead-Acid Battery Market Strategic Shifts & Innovations
Digital twin architectures are virtualizing battery lifecycle management across the value chain, compressing warranty claim resolution and enabling predictive maintenance monetization for fleet operators.
Battery management system software is virtualizing state-of-health monitoring for commercial vehicle fleets, replacing manual conductance testing with cloud-based degradation forecasting. Large fleet operators in the U.S. Midwest automotive corridor are adopting these platforms fastest, driven by total cost of ownership contracting models. The structural consequence is a compression of traditional aftermarket service intervals and a shift toward subscription-based battery lifecycle management.
The EPA's National Emission Standards for Hazardous Air Pollutants enforcement is tightening allowable lead stack emissions from secondary smelters, forcing capital expenditure toward baghouse filtration and acid mist suppression systems. Manufacturers in Pennsylvania and Missouri face the steepest compliance curves due to aging infrastructure bases. Start-stop battery assemblers sourcing recycled lead are prioritizing certified-zero-discharge suppliers to preempt supply chain liability.
Fleet procurement offices are consolidating battery purchasing through national account structures, displacing decentralized regional distributor relationships. Large commercial vehicle operators in Mexico and the U.S. South are centralizing specification authority at headquarters level, demanding volume-tier pricing and unified warranty terms. This concentration is most visible in last-mile delivery electrification programs where total fleet cost visibility trumps local service relationships.
North America Automotive Lead-Acid Battery Market Segmentation
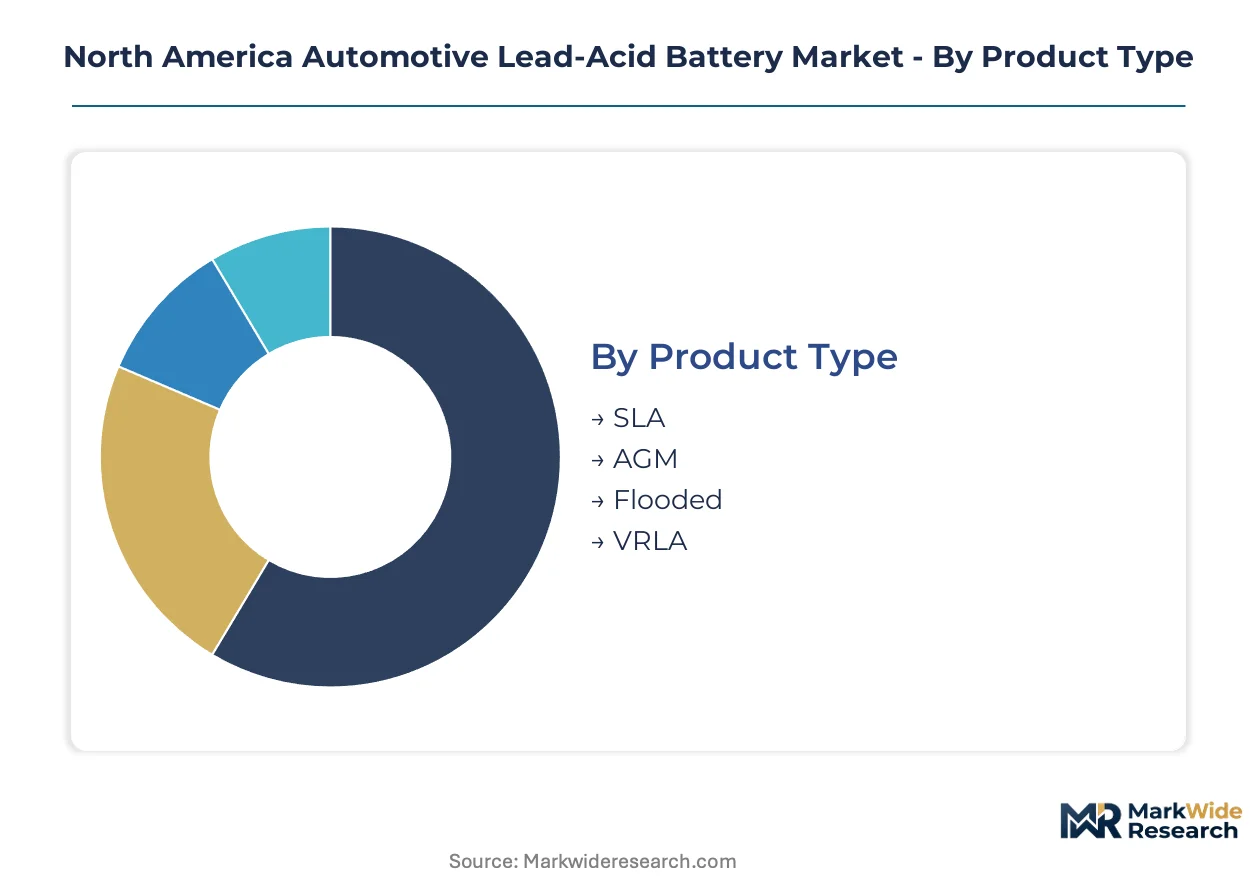
Segmentation in North America automotive lead-acid batteries reveals distinct service intensity profiles across product architectures and procurement channels. OEM-specified units demand minimal aftermarket intervention, while fleet-operated deep-cycle systems require intensive lifecycle management and predictive maintenance contracts.
Product Type:
After-sales-service intensity varies sharply across these architectures, with flooded units demanding periodic electrolyte maintenance and AGM systems requiring specialized charging infrastructure.
- SLA:Sealed lead-acid construction eliminates electrolyte replenishment, reducing field service requirements. Demand concentrates in auxiliary power applications for commercial vehicle sleeper cabs across Texas and Florida interstate corridors, driven by fleet standardization on maintenance-free architectures.
- AGM:Absorbent glass mat separators enable higher compression ratios and vibration resistance. Michigan, Ohio, and Indiana OEMs specify these for start-stop powertrains, pulling procurement away from flooded units as mild-hybrid penetration deepens in the U.S. Midwest automotive corridor.
- Flooded:Conventional vented design with removable caps dominates price-sensitive aftermarket replacement cycles through regional distributors.
- VRLA:Valve-regulated recombinant chemistry suits enclosed engine compartments with limited ventilation access.
By volume, Flooded leads. By growth pace, AGM is expanding most quickly.
End User:
Procurement authority concentrates differently across these channels, with fleet operators consolidating national purchasing power while dealerships retain fragmented local relationships.
- OEMs:Original equipment manufacturers in Michigan, Ohio, and Indiana specify battery architectures during vehicle platform development. Their sourcing decisions lock in supply agreements spanning multiple model years, creating captive demand for certified suppliers meeting UN ECE R100 homologation through Transport Canada.
- Fleet Operators:Mexican commercial vehicle fleets and U.S. long-haul operators are centralizing battery procurement through national account structures. These stakeholders demand integrated telematics and unified warranty terms, displacing decentralized regional distributor relationships in last-mile delivery electrification programs.
- Aftermarket Providers:Regional distributors build private-label sourcing relationships with Mexican maquiladora assemblers to bypass branded premium pricing.
- Dealerships:Franchise service centers handle warranty replacements and consumer walk-in demand with inventory tied to manufacturer authorization requirements.
By transaction volume, Aftermarket Providers dominate. By contract value concentration, Fleet Operators are gaining share fastest.
Application:
Functional segmentation tracks power delivery profiles, with starting applications demanding burst current capacity and energy storage requiring deep-cycle durability.
- Starting:Cold cranking amperage between 400 and 1000 A delivers burst current for passenger vehicle engine ignition. OEM demand clusters in the U.S. Midwest automotive corridor where vehicle assembly plants specify 12-volt architectures compatible with legacy alternator systems.
- Energy Storage:Deep-cycle discharge capability supports commercial vehicle hotel loads and auxiliary power units. Mexican fleet operators expanding delivery van electrification programs drive procurement growth for cycling-resistant plate designs in last-mile logistics applications.
- Lighting:Stabilized voltage supply for headlamp and interior illumination systems during alternator failure.
- Ignition:Sustained current delivery for spark ignition systems in conventional internal combustion powertrains.
By installed base, Starting leads. By expansion trajectory, Energy Storage shows the steepest climb.
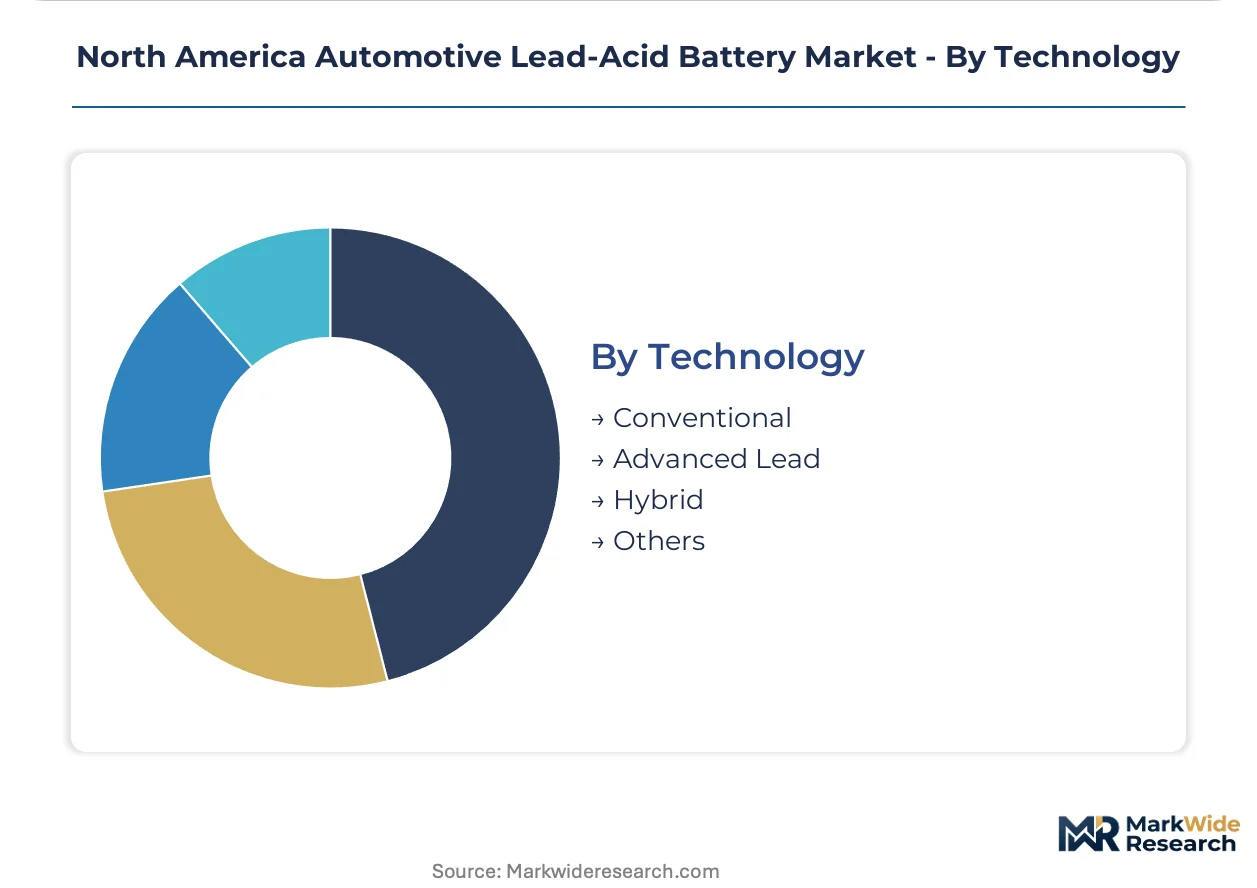
Technology:
Technology tiers reflect manufacturing process sophistication and materials engineering, with advanced lead chemistries commanding specification premiums from emission-sensitive OEMs.
- Conventional:Standard lead dioxide and sponge lead plate construction with sulfuric acid electrolyte dominates aftermarket replacement cycles. Pennsylvania and Missouri smelting infrastructure supplies recycled lead feedstock, though EPA National Emission Standards for Hazardous Air Pollutants compliance costs compress margins for aging facilities.
- Advanced Lead:Enhanced grid alloys and carbon additives improve charge acceptance for start-stop cycling. OEMs across Michigan, Ohio, and Indiana specify these architectures to meet fuel economy regulations, driving specification shifts as mild-hybrid vehicle production scales.
- Hybrid:Dual-chemistry systems combining lead-acid with supercapacitor elements for voltage stabilization.
- Others:Experimental plate compositions and electrolyte formulations in limited commercial deployment.
By production volume, Conventional leads. By specification momentum, Advanced Lead is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions enforcement and state-level producer responsibility mandates are redistributing manufacturing capacity across North American jurisdictions. Battery assemblers and recyclers are relocating to optimize regulatory compliance and feedstock access.
United States
The U.S. Midwest automotive corridor spanning Michigan, Ohio, and Indiana concentrates OEM battery specification authority for start-stop vehicle programs. EPA National Emission Standards for Hazardous Air Pollutants enforcement compels Pennsylvania and Missouri smelters toward baghouse filtration upgrades. Fleet telematics adoption in Texas and Florida interstate corridors accelerates predictive maintenance contracting for commercial vehicle deep-cycle systems.
Canada
Transport Canada mandates UN ECE R100 compliance for battery systems in new vehicle homologation, extending product validation cycles for suppliers serving Detroit Three assembly plants. Ontario's manufacturing base supplies sealed lead-acid units for auxiliary power in commercial vehicle sleeper cabs crossing the Ambassador Bridge corridor. Quebec's recycling infrastructure processes lead feedstock from U.S. Northeast collection networks under cross-border environmental protocols.
Mexico
Mexican fleet operators in Mexico City Metro and Nuevo León are expanding procurement of absorbent glass mat units for last-mile delivery van electrification programs. The central government's automotive sector incentives attract maquiladora battery assemblers serving U.S. aftermarket private-label channels. Jalisco and Bajío Region logistics hubs concentrate deep-cycle demand from commercial vehicle operators centralizing national purchasing authority.
North America Automotive Lead-Acid Battery Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated recyclers and specialized deep-cycle manufacturers. Three strategic archetypes dominate: closed-loop recycling operators with smelting assets, start-stop battery specialists serving OEM specification channels, and private-label assemblers leveraging Mexican maquiladora cost structures. Competitive moves center on EPA zero-discharge certification pursuit and fleet telematics integration partnerships.
Within the integrated recycling tier, Clarios and East Penn Manufacturing Company exemplify operators controlling collection-through-smelting value chains. EnerSys occupies a position among deep-cycle specialists targeting commercial vehicle fleet electrification programs. These three entities represent contrasting scale strategies: continental collection network density, single-site vertical integration, and segment-focused product architecture respectively.
| Leading Market Players |
|---|
| Clarios |
| EnerSys |
| East Penn Manufacturing Company |
| C&D Technologies |
| GS Yuasa Corporation |
| Exide Technologies |
| Leoch International Technology |
| Crown Battery |
| ATLASBX |
| Others |
Cost & Logistics Intelligence
EPA National Emission Standards for Hazardous Air Pollutants enforcement compresses both pricing tier spreads and supply chain configuration, forcing capital reallocation toward baghouse filtration upgrades that widen the gap between certified-zero-discharge suppliers and marginal operators facing margin erosion.
Pricing Analysis
EPA zero-discharge certification creates the primary spread between premium and standard tiers, with certified suppliers commanding contract premiums from OEMs in Michigan, Ohio, and Indiana. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales service bundling. Cost compression in economy-tier flooded batteries is intensifying because Mexican maquiladora assemblers bypass branded premium pricing. Fleet operators show least price sensitivity due to total cost of ownership contracting, while independent aftermarket distributors remain most price-sensitive.
Supply Chain Analysis
Export-control restrictions on advanced battery management system software limit cross-border technology flows to Mexican maquiladora operations. Primary lead recycling infrastructure concentrates in Pennsylvania and Missouri, with secondary assembly clustering in Michigan, Ohio, and Indiana. The supply chain draws from recycled lead feedstock, sulfuric acid electrolyte, and specialized separator materials. Single-source vulnerability runs through Pennsylvania smelting capacity for West Coast battery assemblers. Distribution runs through national account structures consolidating fleet procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as fleet electrification programs splinter procurement authority between OEM specification channels, national fleet accounts, and regional aftermarket distributors.
For Market Incumbents: Build regulatory compliance moats through EPA zero-discharge certification investment. Secure captive supply through backward integration into Pennsylvania or Missouri smelting assets. Defend against lithium-ion substitution threat by embedding smart battery monitoring into deep-cycle product architectures. For New Entrants and Emerging Players: Mexican last-mile delivery van electrification programs represent the most penetrable entry point for AGM specialists lacking OEM certification. Texas and Florida interstate corridors offer secondary opportunity for telematics-integrated deep-cycle systems. Go-to-market through fleet telematics platform partnerships bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated recyclers with EPA certification. Long-term viability hinges on closed-loop collection network density and smelting asset control. Acquisition focus should target certified-zero-discharge operators in Pennsylvania and Missouri. Monitor California and New York extended producer responsibility framework implementation as inflection indicator for collection obligation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Certification | EPA zero-discharge certification secures OEM supply agreements and preempts liability exposure. |
| Fleet Telematics Integration | Smart battery monitoring platforms enable predictive maintenance subscription revenue from Midwest long-haul operators. |
| Maquiladora Cost Positioning | Mexican assembly operations bypass branded premium pricing in Texas and Florida aftermarket channels. |
| Vertical Smelting Integration | Captive lead recycling insulates margin from London Metal Exchange price volatility. |
| AGM Specification Migration | Start-stop vehicle programs in Michigan, Ohio, and Indiana pull procurement from flooded units. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA enforcement actions, Transport Canada homologation filings, and vehicle production databases. Primary interviews engaged Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, fleet operations managers, and lead smelting facility operators. Secondary sources included UN ECE R100 certification records, state-level extended producer responsibility regulatory filings, and customs trade data on lead scrap flows. Bottom-up segment sizing triangulates against top-down production volume estimates.
Forecast inputs span start-stop vehicle penetration rates, fleet electrification program scaling, and smelting capacity compliance timelines across the analysis window. Segmentation dimensions modeled include product architecture, end-user procurement channel, application power profile, and technology tier. CAGRs derive from regression against historical production correlations with vehicle assembly volumes and battery replacement cycle frequencies. Industry-specific inputs incorporate EPA emissions enforcement trajectory and Transport Canada validation cycle durations.
Practitioners should monitor EPA National Emission Standards for Hazardous Air Pollutants enforcement intensity and California extended producer responsibility implementation for early signals. Forecasts reflect assumptions on mild-hybrid vehicle production scaling and fleet telematics adoption curves. Material shifts in lithium-ion cost parity or federal battery recycling mandate timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market