
 Car Bulb Market | 2026-2036
Car Bulb Market Size, Share, and Industry Trends Forecast 2026-2036
Car Bulb Market Outlook
China is reshaping automotive lighting supply chains through expanded LED chip foundry capacity and downstream module assembly. Koito Manufacturing Co., Ltd. leverages vertical integration across lens design, LED packaging, and headlamp assembly to sustain pricing power in OEM channels. Osram GmbH anchors European aftermarket demand through its established distribution network and brand recognition among independent repair shops. HELLA GmbH & Co. KGaA competes on adaptive front-lighting systems that integrate sensor inputs for beam shaping.
Car bulbs are electromechanical devices that convert electrical energy into visible light through filament incandescence, gas discharge, or solid-state electroluminescence, with LED variants achieving luminous efficacy above 100 lumens per watt and operating lifespans exceeding 30,000 hours. Their primary commercial purpose is to provide regulated illumination for vehicle visibility, signaling, and safety compliance under varying road conditions. LED product type segments command margin premiums over halogen alternatives due to energy efficiency mandates and thermal management requirements, while headlight applications absorb the largest share of OEM engineering resources. Passenger car vehicle type segments generate volume scale, though SUV specifications increasingly demand higher-output fog light and auxiliary lighting configurations.
EPA fuel economy standards indirectly drive LED adoption by reducing electrical load on alternators, while NHTSA Federal Motor Vehicle Safety Standard 108 defines photometric performance minimums for headlamps and tail lights. China's GB standards for automotive lighting establish domestic testing protocols that influence export certification costs for foreign suppliers. Stakeholders must monitor divergence between regional electromagnetic compatibility requirements and thermal cycling test protocols when allocating R&D budgets across geographic markets.
Market Dynamics
LED retrofit demand is compressing halogen replacement cycles as vehicle owners prioritize energy efficiency and extended service intervals over upfront cost savings, fundamentally restructuring aftermarket inventory planning across distributor networks.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 108:Tightening photometric minimums for headlamp output are forcing premature halogen replacements, expanding addressable demand for certified LED alternatives in the US aftermarket.
- EPA fuel economy standards:Reduced electrical load mandates are accelerating OEM specification of low-draw LED headlamps across passenger car and SUV platforms.
- LED chip foundry capacity expansion:Chinese substrate manufacturing clusters are driving module cost reductions that enable price-competitive retrofit kits for independent repair channels.
Market Restraints
- Epoxy resin and rare-earth phosphor volatility:LED packaging materials face input cost swings that compress assembler margins and destabilize long-term supply agreements.
- Single-source thermal substrate concentration:High-performance ceramic PCB supply clusters in East Asian manufacturing hubs, creating geographic vulnerability for European module producers.
- Halogen legacy compatibility requirements:NHTSA and ECE regulations mandate backward-compatible beam patterns that constrain optical design freedom for LED retrofit developers.
Strategic Opportunities
- Adaptive front-lighting system integration:Sensor-fused beam shaping that responds to oncoming traffic and road curvature represents unpenetrated white space in mid-market SUV segments.
- Independent repair shop certification programs:Brand-authorized installer networks in Germany and France capture premium pricing through warranty-backed LED retrofit services.
- Vehicle-to-everything lighting protocols:Convergence of V2X communication standards with exterior illumination creates entry points for suppliers capable of embedded software development.
Industry Challenges
- Thermal management engineering scarcity:LED headlamp design requires rare cross-functional expertise combining optical simulation, materials science, and computational fluid dynamics.
- Homologation timeline compression:Divergent GB standards, ECE regulations, and NHTSA testing protocols force redundant certification cycles that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Bulb Market |
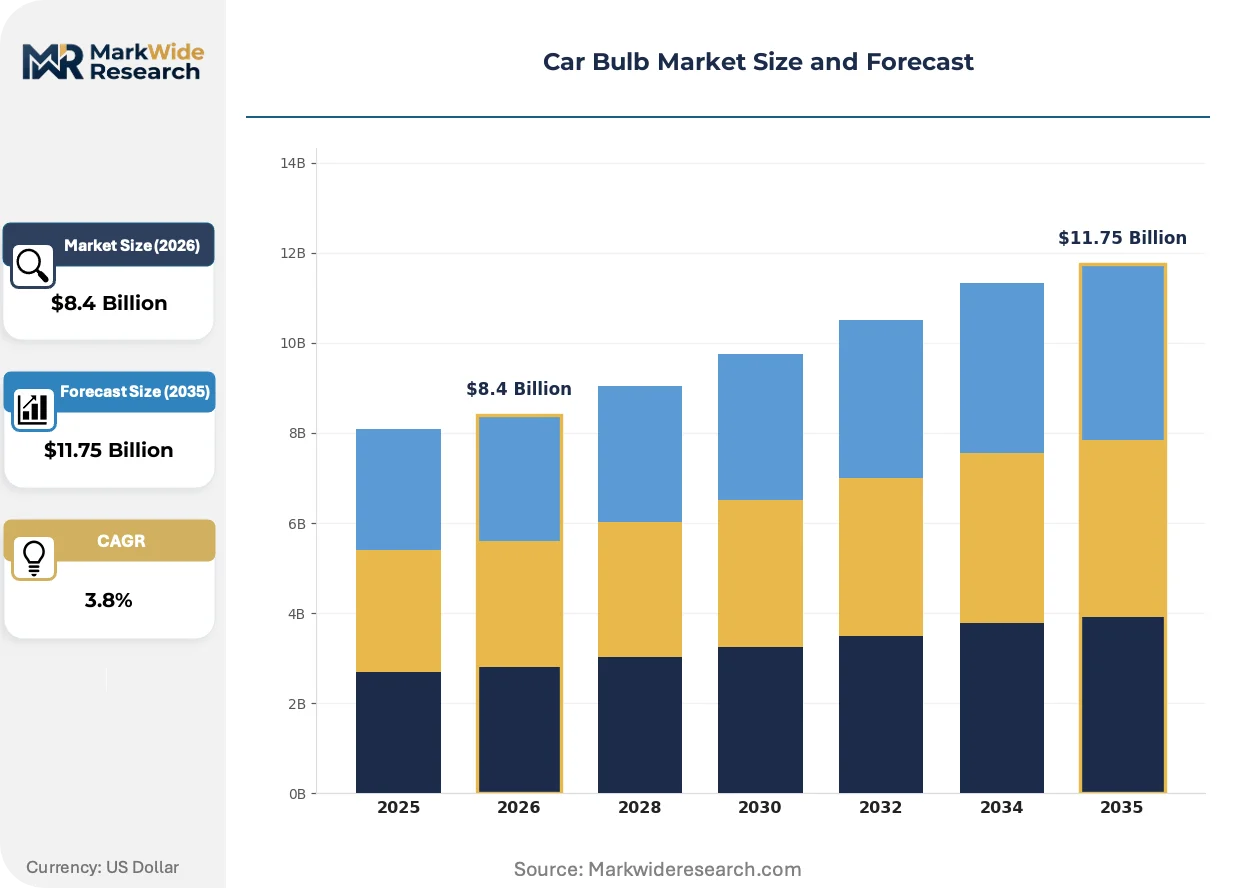
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, LED, Xenon, Incandescent Application: Headlights, Fog Lights, Tail Lights, Indicator Lights Vehicle Type: Passenger Cars, SUVs, Trucks, Motorcycles Power Rating: 12V, 24V, 55W, 100W |
| Companies Covered | Philips (Signify N.V.), Valeo S.A., Osram GmbH, General Electric Company, Magneti Marelli S.p.A., Koito Manufacturing Co., Ltd., Stanley Electric Co., Ltd., Hyundai Mobis Co., Ltd., HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Bulb Market Strategic Shifts
Automotive lighting is undergoing functional transformation from passive illumination hardware to software-defined visibility systems, with control logic and thermal architecture now determining competitive differentiation more than filament or phosphor chemistry.
Matrix LED arrays with individually addressable pixels are digitizing beam pattern control in real time. Premium SUV and passenger car OEMs in Germany and Japan are specifying these systems for 40% of new headlamp programs. This capability is digitizing the traditional supplier-OEM relationship, shifting engineering contracts toward software licensing models and recurring calibration revenue streams.
EU F-Gas Regulation phase-down schedules are accelerating xenon discharge lamp obsolescence across European vehicle fleets. The industrial consequence is forced conversion of service bay inventories and training curricula toward solid-state alternatives. Aftermarket distributors in France and Italy are responding by liquidating HID stock at distressed margins while negotiating exclusive LED supply agreements with module assemblers.
Fleet procurement departments are consolidating lighting spend through national service contracts with integrated parts-and-labor pricing. Independent repair shops in the US Midwest are losing share to authorized dealer networks that bundle LED upgrades with scheduled maintenance. This concentration is most visible in commercial vehicle segments where total-cost-of-ownership calculations favor extended-warranty LED retrofits over repeated halogen replacement cycles.
Car Bulb Market Segmentation
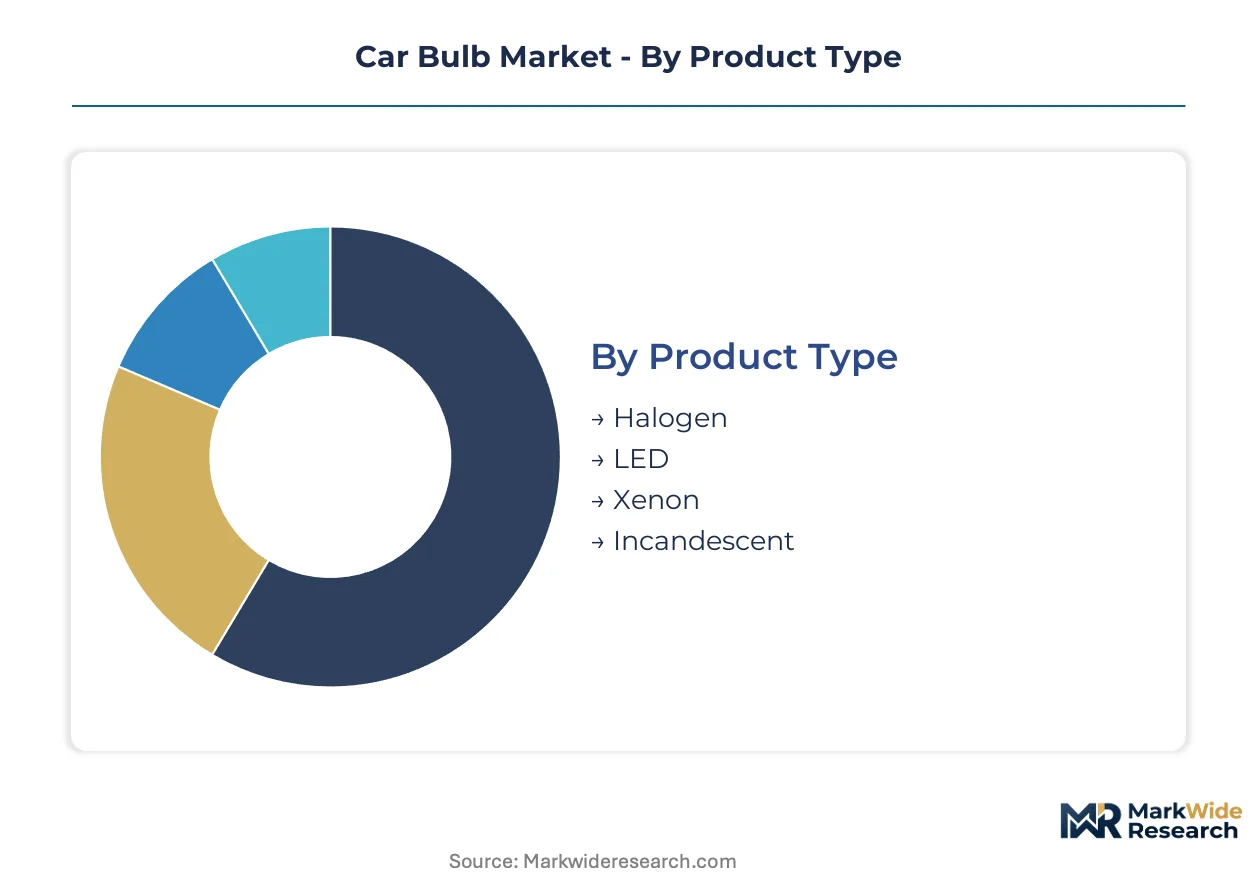
Car bulb segmentation reveals how technology transitions and vehicle electrification reshape procurement priorities across OEM and aftermarket channels. Distinct performance requirements across lighting functions create divergent margin structures that suppliers must navigate.
Product Type:
Technology maturity and energy efficiency mandates split this dimension into four distinct cost-performance tiers with divergent replacement cycles.
- Halogen:Tungsten filament enclosed in halogen gas achieves color temperatures near 3200K with luminous efficacy below 25 lumens per watt. Demand concentrates in emerging economy aftermarket channels where upfront cost sensitivity dominates purchasing decisions and NHTSA backward-compatibility requirements sustain legacy fitment.
- LED:Solid-state electroluminescence through III-V semiconductor junctions delivers efficacy above 100 lumens per watt and operational lifespans exceeding 30,000 hours. German OEM specifications for premium passenger cars absorb the highest-margin chip-on-board modules with active thermal management.
- Xenon:High-intensity discharge through xenon gas arc produces 3000+ lumen output with 35W draw. EU F-Gas Regulation phase-down schedules are forcing fleet conversion timelines toward solid-state alternatives.
- Incandescent:Vacuum-sealed tungsten filament technology survives only in vintage vehicle restoration and specific indicator applications where regulatory grandfathering permits continued use.
Halogen commands the established base. The steepest expansion runs through LED.
Application:
Functional safety classification and beam pattern complexity create four distinct engineering investment profiles across exterior lighting positions.
- Headlights:Forward illumination systems must satisfy NHTSA Federal Motor Vehicle Safety Standard 108 photometric minimums and ECE Regulation 112 beam pattern requirements. Adaptive matrix arrays with individually addressable pixels are digitizing German OEM engineering contracts toward software licensing models.
- Fog Lights:Low-mounted wide-beam units operating below 1000 lumens face less stringent homologation but must survive thermal cycling from road spray and debris impact. SUV specifications in the US Midwest increasingly demand higher-output auxiliary configurations for rural driving conditions.
- Tail Lights:Rear visibility functions prioritize instant-on characteristics and red color point stability under voltage fluctuation. Chinese GB standards for automotive lighting establish distinct testing protocols that influence export certification costs.
- Indicator Lights:Amber signaling functions require directional intensity compliance with SAE J588 and ECE Regulation 6, with LED retrofit demand compressing incandescent replacement cycles in European aftermarket channels.
Headlights absorb the dominant engineering resources. Indicator retrofits are climbing the fastest as safety compliance tightens.
Vehicle Type:
Platform volume scale and specification intensity divide demand across four chassis categories with divergent procurement consolidation patterns.
- Passenger Cars:High-volume sedan and hatchback platforms generate module scale economies but face margin compression from fleet procurement consolidation through national service contracts.
- SUVs:Elevated ride heights and off-road positioning demand higher-output fog light and auxiliary lighting configurations with premium thermal management specifications.
- Trucks:Commercial vehicle duty cycles favor extended-warranty LED retrofits over repeated halogen replacement cycles in total-cost-of-ownership calculations.
- Motorcycles:Compact form factors and vibration exposure create specialized packaging requirements with limited supplier competition.
Passenger cars anchor volume scale. SUVs are gaining share fastest through specification intensity.
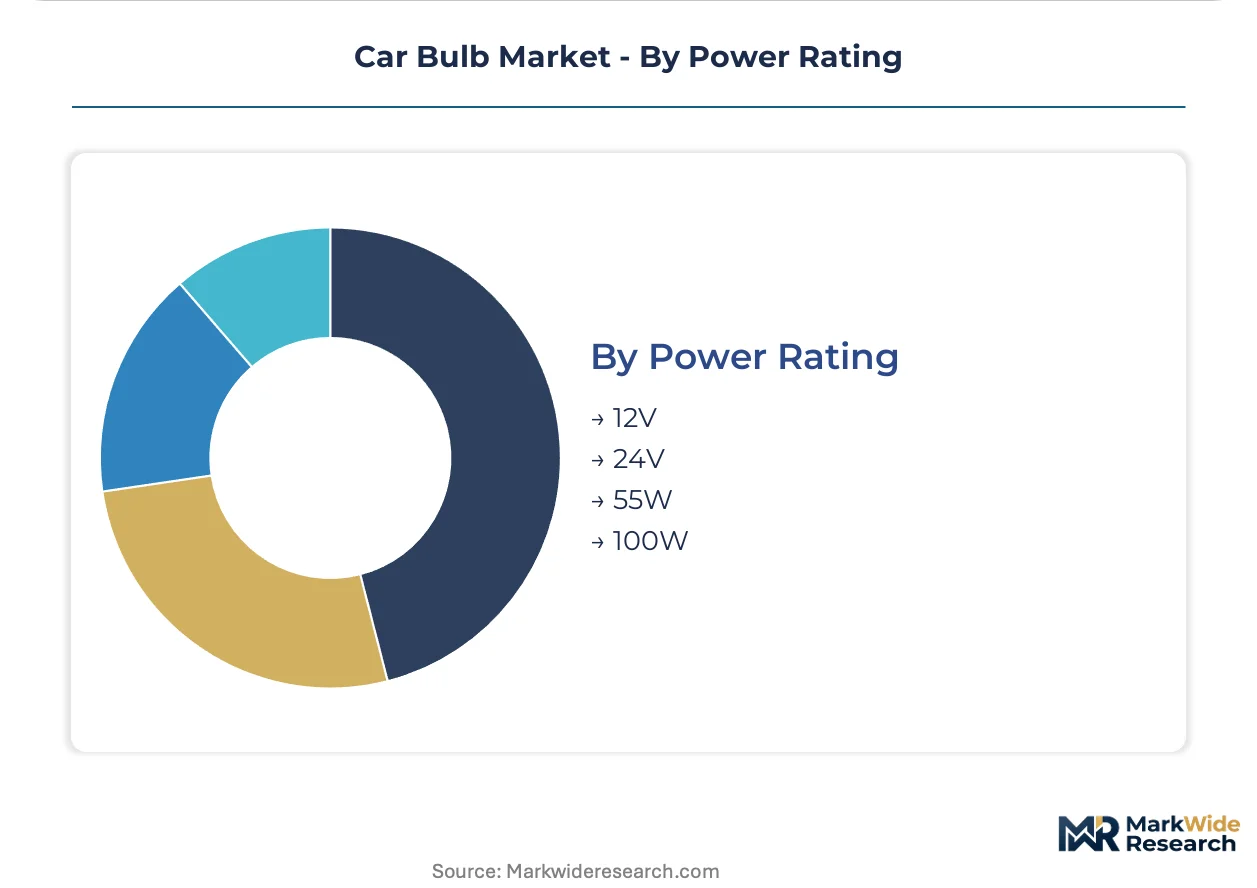
Power Rating:
Electrical system architecture and thermal load capacity segment this dimension across voltage classes and wattage tiers.
- 12V:Dominant passenger car electrical architecture supports halogen and LED modules up to 55W equivalent with standard alternator capacity.
- 24V:Commercial vehicle and heavy truck electrical systems enable higher-output discharge lamps with dedicated wiring harness requirements.
- 55W:Standard halogen headlamp rating faces displacement by 35W LED equivalents delivering comparable luminous flux at reduced electrical draw.
- 100W:High-output auxiliary and off-road specifications concentrated in SUV and truck segments with upgraded alternator and battery configurations.
12V systems command the established base. 55W LED equivalents show the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA Federal Motor Vehicle Safety Standard 108 anchors the United States as the regulatory benchmark for automotive lighting performance, with compliance requirements cascading into export markets and retrofit certification protocols worldwide.
United States
Aftermarket distributors in the US Midwest are expanding LED retrofit inventories as vehicle owners prioritize extended service intervals. NHTSA headlamp standards tighten photometric minimums annually, forcing premature halogen replacements. Detroit-area module assemblers are consolidating supply agreements with Chinese substrate manufacturers to secure cost-competitive chip-on-board components.
Germany
Premium passenger car and SUV OEMs in Bavaria specify advanced matrix LED arrays with individually addressable pixels for adaptive beam shaping. KBA type-approval requirements enforce ECE Regulation 112 compliance that exceeds baseline photometric standards. Stuttgart and Munich engineering clusters are shifting supplier contracts toward software licensing models with recurring calibration revenue streams.
China
LED chip foundry capacity expansion in the Yangtze River Delta is driving module cost reductions for export certification. GB standards for automotive lighting establish domestic testing protocols that influence foreign supplier homologation timelines. Shenzhen and Shanghai assembly hubs are capturing downstream value through integrated lens design and thermal management packaging.
Japan
METI energy efficiency mandates accelerate OEM specification of low-draw LED headlamp platforms across passenger car segments. JIS standards for automotive lighting align with ECE frameworks while maintaining distinct electromagnetic compatibility protocols. Nagoya and Tokyo manufacturing clusters specialize in ceramic PCB substrates for high-performance thermal cycling applications.
France
EU F-Gas Regulation phase-down schedules are forcing fleet conversion timelines from xenon discharge lamps toward solid-state alternatives. ANSM/CNIL data governance frameworks influence connected lighting system development for vehicle-to-everything protocols. Lyon and Paris aftermarket distributors are liquidating HID inventories at distressed margins while negotiating exclusive LED supply agreements.
Car Bulb Market Competitive Environment
Vertically integrated lighting specialists and modular component suppliers split the market between proprietary thermal architectures and distributed assembly networks. Consolidation pressure concentrates around three strategic archetypes: captive OEM suppliers with in-house lens-to-chip production, independent module assemblers sourcing from open-market substrate vendors, and aftermarket brand licensors leveraging established distribution footprints. Dominant competitive moves include backward integration into LED packaging to capture margin from rare-earth phosphor volatility, and geographic expansion through brand-authorized installer networks in European premium retrofit channels.
Among Japanese manufacturers with captive supply structures, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. occupy positions exemplifying the vertically integrated archetype, while Osram GmbH anchors the European aftermarket brand licensing tier through distribution density in independent repair channels. These three entities represent distinct competitive vectors: in-house thermal substrate control, optical simulation specialization, and established brand recognition among service bay procurement managers.
| Leading Market Players |
|---|
| Philips (Signify N.V.) |
| Valeo S.A. |
| Osram GmbH |
| General Electric Company |
| Magneti Marelli S.p.A. |
| Koito Manufacturing Co., Ltd. |
| Stanley Electric Co., Ltd. |
| Hyundai Mobis Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese LED chip foundries is compressing module assembler margins while simultaneously enabling aggressive pricing postures in export markets. This utilization dynamic forces European and Japanese producers to differentiate through thermal substrate specialization or surrender volume share to cost-competitive Yangtze River Delta suppliers.
Pricing Analysis
Price spreads between German OEM specification-grade LED modules and generic aftermarket retrofit kits exceed threefold, with premium-mid-economy pricing differentiation anchored in KBA type-approval certification and active thermal management inclusion. Cost compression in the halogen replacement tier intensifies because Chinese substrate manufacturers are flooding independent repair channels with uncertified chip-on-board alternatives. Fleet procurement departments exhibit lowest price sensitivity due to total-cost-of-ownership calculations favoring extended-warranty LED retrofits, while independent repair shops in emerging economy markets remain most sensitive to upfront unit cost.
Supply Chain Analysis
Epoxy resin and rare-earth phosphor feedstock markets hinge on Chinese separation facility output and Japanese ceramic powder processing, creating dual-source dependency for high-performance LED packaging. High-brightness chip fabrication concentrates in China, Taiwan, and South Korea, with substrate manufacturing clusters in the Yangtze River Delta capturing downstream module assembly value. Single-source vulnerability in ceramic PCB supply from East Asian hubs exposes European assemblers to logistics disruption. Distribution runs through brand-authorized installer networks in Germany and France for premium retrofit channels, while mass-market aftermarket flows through consolidated distributor warehouses in the US Midwest.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Car bulb demand sits in early-cycle expansion as LED retrofit penetration in passenger car and SUV aftermarket channels accelerates faster than OEM replacement rates. NHTSA photometric standard tightening and EPA electrical load mandates provide structural tailwinds for solid-state conversion regardless of new vehicle sales cyclicality.
For Market Incumbents: Build captive thermal substrate supply as the defensive moat against rare-earth phosphor volatility and Chinese module cost compression. Secure exclusive supply agreements with Yangtze River Delta foundries to lock in wafer allocation before capacity absorption tightens. Invest in KBA and NHTSA certification infrastructure to maintain premium pricing power as uncertified alternatives flood independent repair channels. For New Entrants and Emerging Players: Establish a beachhead in adaptive front-lighting system integration for mid-market SUV segments where sensor-fused beam shaping remains underpenetrated. Target US Midwest fleet procurement departments with extended-warranty LED retrofit packages priced against total-cost-of-ownership calculations. Pursue software licensing models with recurring calibration revenue rather than per-unit hardware margins. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among module assemblers with brand-authorized installer networks and OEM software licensing contracts. Long-term viability over the projection horizon favors vertically integrated specialists with in-house lens-to-chip production and established KBA type-approval track records. Watch LED chip foundry utilization rates as the inflection signal for margin compression versus expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Packaging | Captures margin from rare-earth phosphor volatility and secures thermal substrate supply. |
| Brand-Authorized Installer Network Expansion | Locks in premium pricing through warranty-backed retrofit services in German and French markets. |
| Adaptive Front-Lighting System Development | Opens white space in mid-market SUV segments with sensor-fused beam shaping capabilities. |
| Software Licensing Model Transition | Shifts revenue from one-time hardware sales to recurring calibration and control logic licensing. |
| Chinese Foundry Supply Agreement Consolidation | Secures cost-competitive chip-on-board components before capacity absorption tightens allocation. |
Study Parameters
Operator-level perspectives from OEM platform engineers, aftermarket distributor procurement managers, Tier 1 supplier thermal design leads, and independent repair shop owners anchored the qualitative base. Primary interview insights combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standard 108 compliance databases, KBA type-approval registries, vehicle production databases, and customs trade records. Bottom-up module shipment estimates triangulated against top-down vehicle parc calculations across the analysis window.
Scenario-bracketing around LED chip foundry utilization rates, rare-earth phosphor price bands, and NHTSA enforcement intensity produced high-low trajectory bounds. Segmentation modeling incorporated product type, application function, vehicle class, power rating architecture, and regional regulatory cluster dimensions. CAGRs derived from fitted adoption curves calibrated to historical technology transition patterns in automotive lighting.
Stress conditions across epoxy resin price volatility, ceramic PCB supply disruption, and NHTSA photometric standard acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement timelines. Cross-checking against IHS Markit vehicle registration data and aftermarket parts movement indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
TPMS Battery Market