
 Automotive Scroll E-Compressor Market | 2026-2036
Automotive Scroll E-Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Scroll E-Compressor Market Analysis
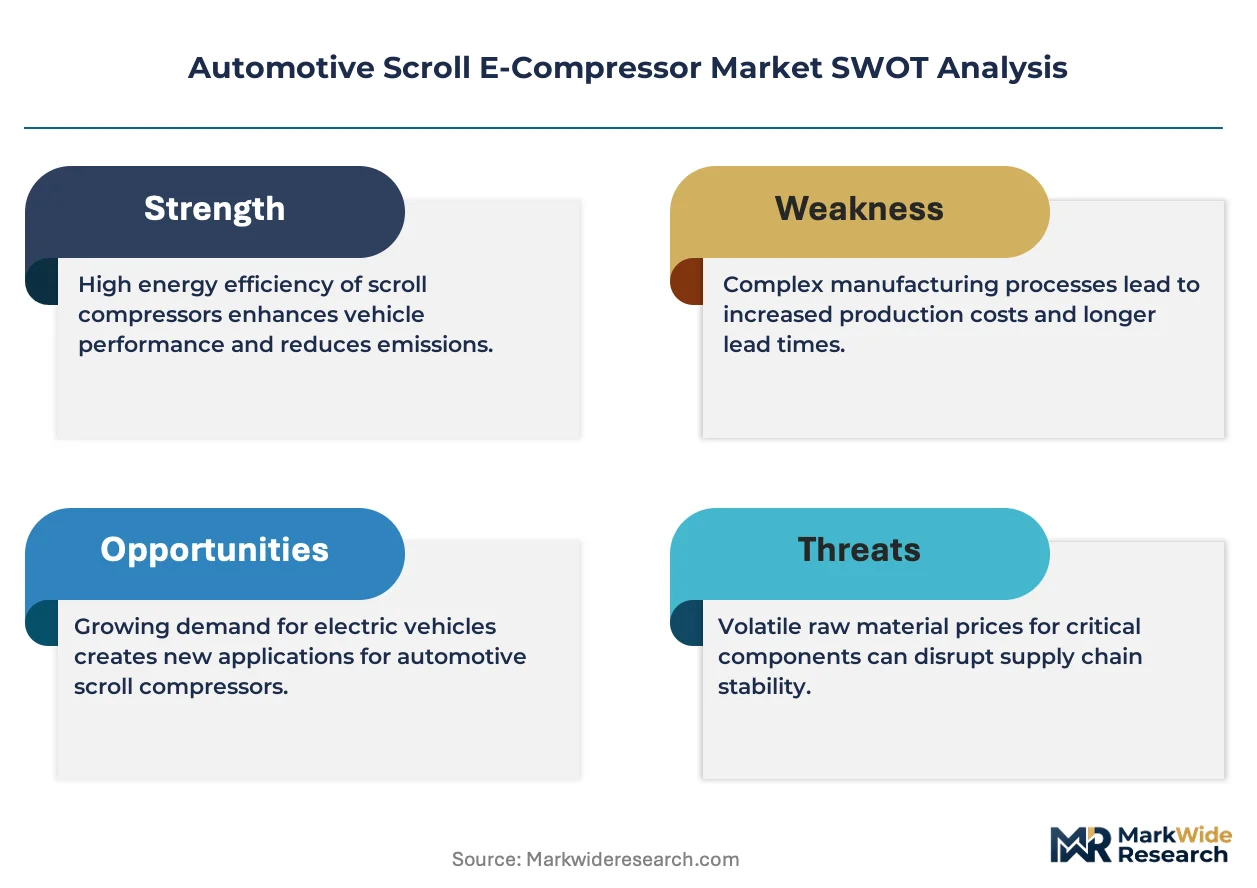
The OEM-direct procurement channel is fragmenting as electric vehicle platforms diversify thermal architectures. DENSO Corporation leverages its integrated motor-inverter designs to anchor premium EV contracts across multiple continents. Sanden Corporation sustains competitiveness through dedicated scroll compressor R&D facilities in Japan and Thailand. BorgWarner Inc. differentiates by extending its power electronics expertise into integrated e-compressor modules for hybrid drivetrains.
An automotive scroll e-compressor is a hermetically sealed positive-displacement device driven by a high-speed electric motor, typically operating at rotational speeds exceeding 6,000 rpm to deliver refrigerant compression without belt-driven mechanical linkages. Its primary commercial purpose is to enable variable-capacity climate control and battery thermal regulation in electrified vehicles where engine-dependent compressors cannot function. The passenger vehicles segment leads absolute volume due to mass-market EV penetration, while the variable displacement product category captures disproportionate margin pools from luxury and performance-oriented platforms. Multi-stage configurations represent the fastest-growing technical subset as 800-volt architectures demand higher pressure ratios for efficient heat pump operation.
The EPA enforces refrigerant leakage thresholds under Section 608 of the Clean Air Act, compelling compressor redesigns toward lower-global-warming-potential working fluids. The EU F-Gas Regulation mandates progressive HFC phase-down, directly shaping product certification requirements for scroll e-compressors sold in member states. China's MIIT imposes dual carbon goals that accelerate domestic OEM adoption of electrically driven thermal systems. Stakeholders must monitor how regulatory convergence on refrigerant chemistry interacts with voltage platform standardization to determine which technical specifications will dominate procurement criteria.
Market Dynamics
The 800-volt electrical architecture migration is compressing development cycles for scroll e-compressor suppliers, forcing simultaneous redesigns of motor windings, inverter topologies, and refrigerant seals to handle higher pressure ratios and switching frequencies.
Growth Catalysts
- Battery thermal management intensity:EV platforms above 100 kWh capacity require dedicated cooling loops for fast-charging protocols, expanding addressable unit volumes per vehicle platform.
- EU F-Gas Regulation phase-down:The mandated HFC reduction schedule is disqualifying conventional compressor technologies from type-approval certification in member states.
- China MIIT dual carbon enforcement:Domestic OEM procurement mandates for electrically driven thermal systems are accelerating supplier localization requirements.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent magnet motors create margin unpredictability for high-speed designs.
- Japanese supplier concentration:Precision scroll wrap manufacturing equipment and specialized machining IP remain captive to a narrow base of equipment vendors in Osaka and Nagoya industrial clusters.
- Refrigerant chemistry lock-in:The EPA's SNAP program restrictions on high-GWP working fluids limit retrofit flexibility for platforms already tooled for specific thermal cycles.
Strategic Opportunities
- India PLI scheme qualification:Automotive component manufacturing incentives under the Production Linked Incentive scheme create cost-competitive export capacity for Southeast Asian EV supply chains.
- Heat pump convergence:Integration of cabin heating and battery conditioning into unified refrigerant architectures doubles compressor duty cycles per vehicle.
- Direct-to-platform procurement:EV-native OEMs are bypassing traditional Tier-1 thermal system integrators, opening supplier relationships with compressor specialists.
Industry Challenges
- High-voltage safety certification latency:IEC 60664 insulation coordination testing for 800-volt-rated compressors extends validation timelines by 8-14 months versus 400-volt predecessors.
- Scroll wrap tribology expertise scarcity:The specialized knowledge base for coating technologies that prevent aluminum-to-steel galling at 10,000+ rpm rotational speeds concentrates within a limited population of Japanese and German engineering specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Scroll E-Compressor Market |
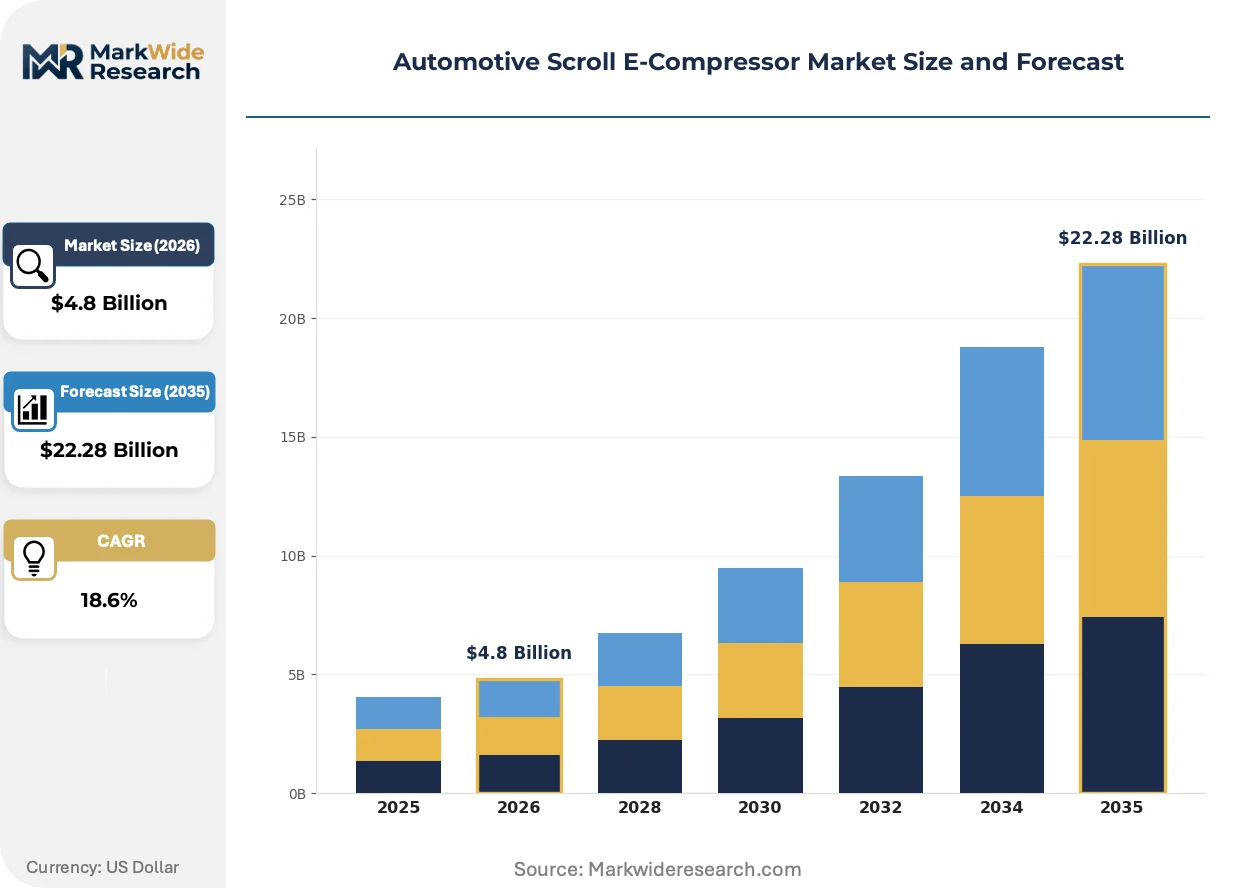
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Fixed Displacement, Variable Displacement Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Technology: Mechanical, Electronic, Pneumatic, Hydraulic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Continental AG, Sanden Corporation, DENSO Corporation, BorgWarner Inc., Toyota Industries Corporation, Hanon Systems, Valeo, Mitsubishi Electric Corporation, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Scroll E-Compressor Market Emerging Trajectories
Refrigerant system virtualization is collapsing the boundary between hardware and thermal management software, enabling predictive compressor operation that anticipates battery load rather than reacting to temperature thresholds.
Integrated inverter-compressor modules are virtualizing the traditional separation between power electronics and mechanical compression. EV platform engineers at premium German and Korean OEMs are specifying these combined units for 2026 model year architectures. This consolidation is virtualizing the procurement category, eliminating separate vendor qualification processes for motor drives and refrigerant hardware.
The EPA's tightened refrigerant leakage thresholds under Section 608 of the Clean Air Act are forcing hermetic seal redesigns and new validation protocols. Compressor housings must now demonstrate sub-15 gram annual leakage rates under accelerated thermal cycling. The passenger vehicle segment bears the heaviest compliance burden, with suppliers redesigning shaft seals and electrical penetrations to meet the 2027 enforcement deadline.
Platform-specific thermal contracts are fragmenting traditional procurement relationships. EV-native manufacturers in China and Scandinavia are negotiating directly with compressor specialists, bypassing established HVAC system integrators. This disintermediation concentrates most visibly in battery-electric truck programs, where thermal load profiles diverge sharply from passenger car norms and reward specialized engineering engagement.
Automotive Scroll E-Compressor Market Segmentation
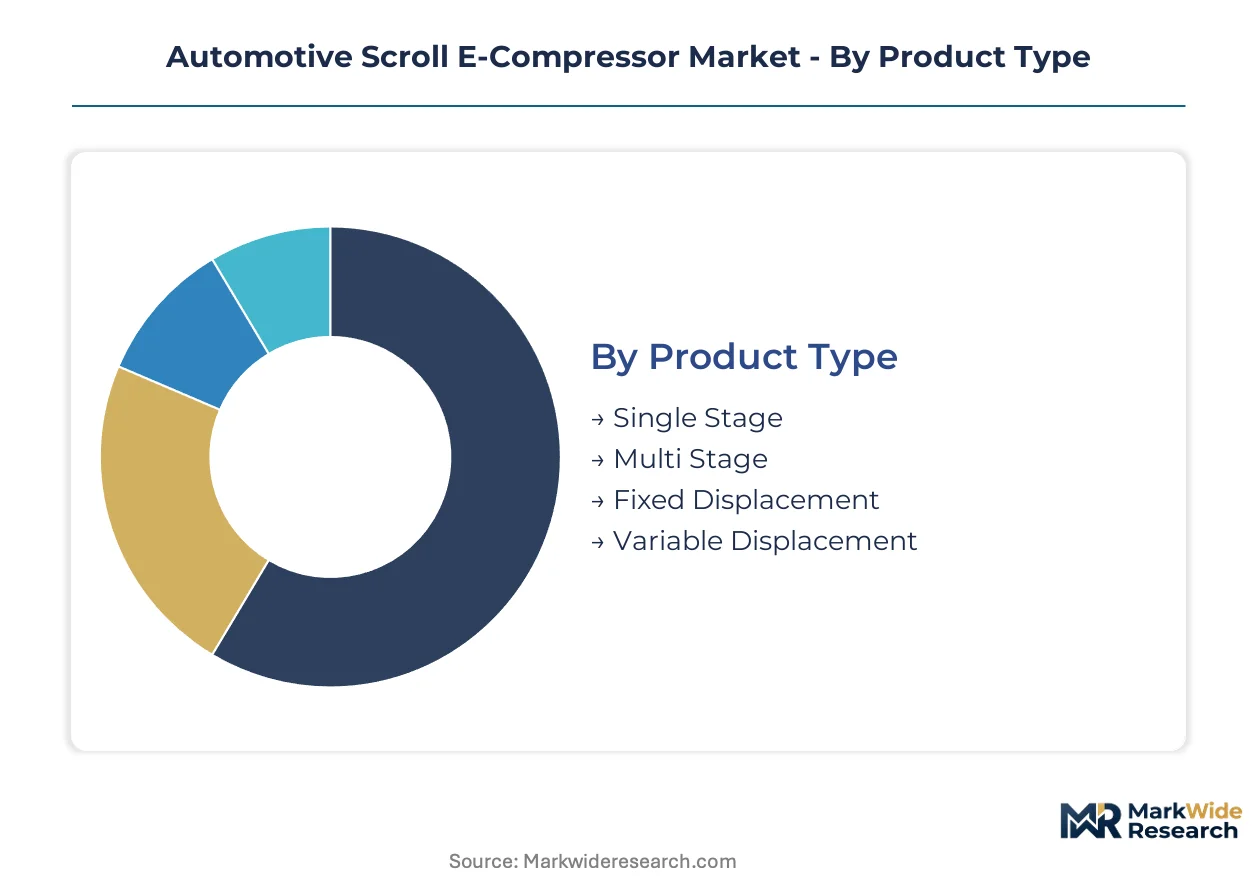
Automotive scroll e-compressor procurement diverges sharply across voltage platforms and thermal architectures. Segment boundaries are hardening as 800-volt battery systems and heat pump integration reshape technical specifications and supplier qualification criteria.
Product Type:
Mature displacement technologies dominate current installed base while multi-stage configurations capture the steepest growth trajectories in premium platforms.
- Variable Displacement:These units modulate refrigerant flow through orbiting scroll geometry adjustment rather than binary on-off cycling. Luxury EV platforms specify variable displacement units for cabin comfort precision, though the control algorithms add firmware validation burden.
- Multi Stage:Cascaded compression chambers deliver pressure ratios exceeding 10:1 for heat pump operation in sub-zero climates. German and Korean OEMs specify multi-stage units for 800-volt architectures where single-stage efficiency collapses.
- Single Stage:Standard scroll geometry serves cost-optimized 400-volt platforms with moderate climate control demands.
- Fixed Displacement:Binary operation suits entry-level EVs with simplified thermal management and minimal heating loads.
Variable displacement handles the majority of throughput; multi-stage is the fastest mover on share.
Application:
Vehicle electrification intensity determines compressor duty cycles and procurement specifications across passenger and commercial duty profiles.
- Electric Vehicles:Battery thermal management demands continuous compressor operation during DC fast-charging events, with refrigerant loops dedicated to cell cooling. Chinese OEMs specify dual-compressor architectures for 100+ kWh packs.
- Passenger Vehicles:Mass-market EV penetration concentrates unit volumes in compact and mid-size platforms where cost-per-watt of cooling capacity drives sourcing decisions.
- Commercial Vehicles:Electric bus and truck programs require scroll compressors rated for 15,000+ hour service life with field-serviceable motor-inverter modules.
- Hybrid Vehicles:Dual thermal architectures—engine-driven cooling plus electric compressor—create packaging constraints that favor compact integrated designs.
Passenger vehicles absorb the highest absolute unit volumes; commercial vehicles are expanding most quickly as electrification reaches heavy-duty segments.
Technology:
Actuation mechanisms separate legacy belt-driven systems from electrically integrated thermal management architectures.
- Electronic:High-speed permanent magnet motors with silicon carbide inverters enable rotational speeds above 10,000 rpm for power density optimization. EPA refrigerant leakage thresholds favor hermetic electronic designs over shaft-sealed alternatives.
- Mechanical:Belt-driven compressors persist in mild-hybrid architectures where engine-dependent accessory drives remain cost-competitive.
- Pneumatic:Compressed air actuation serves specialized industrial vehicle applications with onboard air systems.
- Hydraulic:Fluid power transmission appears in heavy-equipment conversions where hydraulic infrastructure pre-exists.
Electronic actuation commands the dominant revenue share; pneumatic applications are climbing the fastest in niche commercial retrofits.
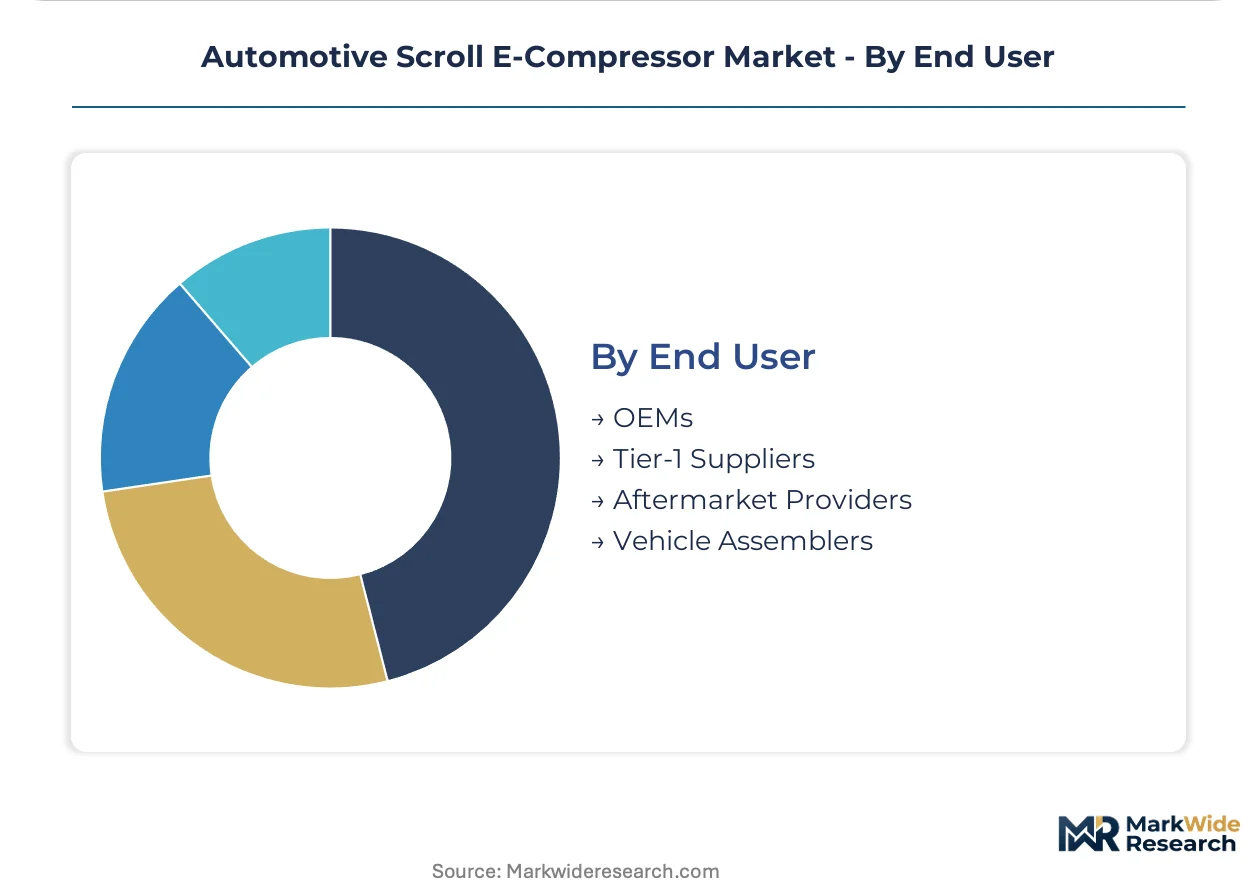
End User:
Procurement channel structure is fragmenting as EV-native manufacturers bypass traditional thermal system integrators.
- OEMs:Direct platform engineering engagement allows specification of compressor-inverter integrated modules rather than discrete component sourcing. DENSO and BorgWarner anchor premium contracts through this channel.
- Tier-1 Suppliers:Established HVAC system integrators face disintermediation pressure as OEMs specify scroll compressors separately from refrigerant line sets and heat exchangers.
- Aftermarket Providers:Service replacement demand concentrates in collision repair and compressor failure scenarios, with remanufactured units gaining traction in cost-sensitive segments.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure compressors through OEM-directed sourcing agreements with limited supplier autonomy.
OEM direct procurement handles the majority of throughput; aftermarket providers are gaining share fastest as early EV fleets age into replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port underwrites China's dominance in automotive scroll e-compressor logistics, handling precision-manufactured thermal components for export to European and North American EV assembly plants.
China
Domestic EV production scales above 8 million units annually, creating captive demand for high-speed compressor architectures. MIIT dual carbon enforcement mandates electrically driven thermal systems in new energy vehicle platforms. The Yangtze River Delta industrial corridor hosts concentrated motor-inverter manufacturing capacity serving BYD and NIO supply chains.
Germany
Premium OEM 800-volt platform launches require multi-stage compression for heat pump efficiency in sub-zero climates. EU F-Gas Regulation phase-down disqualifies conventional compressor technologies from type-approval certification. The Stuttgart industrial cluster anchors precision scroll wrap machining expertise for continental supply networks.
United States
Domestic battery cell manufacturing expansion at Michigan and Tennessee gigafactories pulls thermal component sourcing regionalization. EPA Section 608 refrigerant leakage thresholds force hermetic seal redesigns for sub-15 gram annual leakage compliance. The Detroit-Windsor cross-border automotive corridor concentrates HVAC system integration capacity.
Japan
Precision scroll manufacturing equipment and specialized machining IP remain concentrated in Osaka and Nagoya industrial clusters. METI technology roadmaps prioritize rare-earth magnet substitution in high-speed motor designs. Toyota City anchors integrated thermal system development for hybrid and battery-electric platforms.
South Korea
Hyundai-Kia 800-volt E-GMP platform proliferation drives specification of integrated compressor-inverter modules. KBA-aligned certification requirements for high-voltage safety shape product validation protocols. The Gwangju metropolitan area hosts expanding production capacity for export-oriented EV thermal components.
Automotive Scroll E-Compressor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical concentration. The vendor base organizes around three strategic archetypes: diversified automotive suppliers with thermal portfolio breadth, dedicated compressor specialists with scroll-specific IP, and power electronics firms extending into electromechanical integration. Dominant competitive moves include backward integration into rare-earth magnet supply chains and geographic expansion through joint ventures in Chinese industrial zones.
Among diversified automotive suppliers, DENSO Corporation, Continental AG, and BorgWarner Inc. exemplify distinct strategic positioning. DENSO occupies a position as an integrated motor-inverter design anchor across multiple continents. Continental AG represents the European tier-one archetype with thermal system breadth spanning cabin climate and battery conditioning. BorgWarner sits within the power electronics extension category, translating inverter expertise into electromechanical compressor modules for hybrid drivetrain applications.
| Leading Market Players |
|---|
| Continental AG |
| Sanden Corporation |
| DENSO Corporation |
| BorgWarner Inc. |
| Toyota Industries Corporation |
| Hanon Systems |
| Valeo |
| Mitsubishi Electric Corporation |
| MAHLE GmbH |
| Others |
Supply Flow & Price Mechanics
Rare-earth magnet concentration in Chinese refining and Japanese magnet fabrication concentrates margin capture upstream, forcing compressor assemblers to absorb neodymium price volatility or push cost escalation downstream to OEM thermal system procurement teams.
Pricing Analysis
Volume-discount tiering structures separate multi-million-unit OEM contracts from mid-tier regional assembler agreements and aftermarket single-unit replacement sales. Pricing stratifies across premium integrated motor-inverter modules, standard discrete compressor units, and economy fixed-displacement alternatives, with differentiation driven by voltage platform certification and thermal cycle validation depth. Cost compression in the economy tier is intensifying because Chinese domestic suppliers are scaling 400-volt production for local EV platforms. Fleet procurement teams at commercial vehicle operators exhibit the highest price sensitivity, while German premium OEM platform engineers prioritize performance specifications over unit cost.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare-earth mining complexes and Malaysian separation facilities, with precision magnet fabrication concentrated in Japanese industrial corridors around Osaka and Nagoya. Scroll wrap machining equipment, silicon carbide inverter substrates, and hermetic seal aluminum alloys constitute critical component dependencies. Single-source vulnerability concentrates in Japanese-owned precision grinding equipment for orbiting scroll geometry, where alternative vendors lack the tribology expertise for 10,000 rpm aluminum-to-steel interfaces. Distribution runs through OEM-directed supplier parks adjacent to EV assembly plants in the Yangtze River Delta, Stuttgart industrial cluster, and Michigan battery corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward EV-native OEMs as direct compressor procurement fragments traditional Tier-1 thermal system integrator relationships, consolidating specification authority with platform engineering teams in China and Scandinavia.
For Market Incumbents: Harden rare-earth magnet supply security through backward integration into magnet recycling or long-term offtake agreements with Chinese separation facilities, while accelerating silicon carbide inverter qualification to defend against power electronics specialists encroaching on compressor-inverter integration. The priority lever sits with scroll wrap coating IP retention as Japanese engineering talent scarcity intensifies. For New Entrants and Emerging Players: Pursue aftermarket remanufacturing capacity for early EV fleet compressor replacements, where technical service documentation gaps create white-space for specialized rebuild operations. India's PLI scheme qualification offers the most penetrable geographic entry point for cost-competitive export manufacturing serving Southeast Asian EV supply chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 800-volt multi-stage compressor development programs, favoring acquisition targets with existing high-voltage safety certification infrastructure over greenfield engineering investments. Monitor IEC 60664 insulation coordination test completion timelines as the signal to watch for product-readiness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Security | Long-term offtake agreements with Chinese separation facilities lock in feedstock cost predictability for high-speed motor production. |
| Silicon Carbide Inverter Integration | Consolidated compressor-inverter modules eliminate separate vendor qualification processes at premium German and Korean OEMs. |
| Scroll Wrap Coating IP Development | Proprietary aluminum-to-steel tribology solutions prevent galling failures at rotational speeds exceeding 10,000 rpm. |
| 800-Volt Safety Certification Acceleration | Early IEC 60664 validation completion secures platform engineering engagement before competitor product readiness. |
| India Manufacturing Footprint Establishment | PLI scheme qualification creates cost-competitive export capacity for Southeast Asian EV thermal component demand. |
Methodological Framework
A standing panel of OEM platform thermal engineers, Tier-1 HVAC system procurement directors, rare-earth magnet supply specialists, and aftermarket service operations managers provided ongoing calibration against secondary validation from EPA refrigerant regulation filings, EU F-Gas phase-down schedules, MIIT new energy vehicle production databases, and automotive customs trade records. Bottom-up unit volume estimates triangulated against top-down OEM platform thermal system content analysis.
Scenario-bracketing framed optimistic, baseline, and constrained demand trajectories across the projection horizon, with segmentation modeling spanning voltage platform architecture, displacement technology category, vehicle propulsion type, and regional production cluster. CAGRs derived from slope-intercept analysis of annual unit shipment curves, incorporating battery pack capacity scaling curves and fast-charging protocol penetration assumptions as automotive-specific forecast inputs.
Sensitivities concentrate around rare-earth magnet price volatility, 800-volt platform adoption acceleration, and EPA refrigerant leakage threshold enforcement timing. Cross-checking against IHS Markit vehicle production forecasts and regional EV registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
X-By-Wire Systems Market