
 High Voltage DC Relay for Vehicle Market | 2026-2036
High Voltage DC Relay for Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage DC Relay for Vehicle Market Insights
The direct-to-OEM supply channel is fragmenting as battery pack makers and powertrain integrators build captive relay qualification programs. Panasonic Industry leverages its ceramic sealing expertise to anchor high-voltage contracts with Japanese OEMs. TE Connectivity sustains broad geographic coverage through vertically integrated contact material production. Mitsubishi Electric dominates Asia-Pacific demand with JIS-certified relays rated above 800V DC.
A high voltage DC relay for vehicle is an electromechanical or solid-state switching device engineered to interrupt direct current circuits above 60V DC in electric vehicle power distribution systems, typically rated for 400V to 1000V DC with arc-quenching ceramic chambers and hermetically sealed contact assemblies. It performs critical functions including battery disconnect, pre-charge sequencing, and fast-charge port isolation across onboard and charging infrastructure applications. The electromechanical technology segment retains the largest installed base due to proven rupture capacity and cost structure, though semiconductor-based architectures are capturing design wins in 800V+ platforms where switching speed and cycle life outweigh unit cost. Contact-type products occupy the core volume tier, while relay modules integrating pre-charge resistors and current sensors are consolidating margin pools at system-level pricing.
China's MIIT enforces GB/T standards for high-voltage connector and relay safety in new energy vehicles, compelling design verification above 1500V impulse withstand. The EU AI Act and F-Gas Regulation are converging with ECE R100 to restrict fluorinated gas use in arc suppression while mandating functional safety documentation. Japan's METI coordinates PMDA-adjacent automotive component reliability frameworks that shape export eligibility for relay suppliers targeting domestic OEM supply chains. Stakeholders must monitor how regional safety certifications diverge as voltage platforms split between 400V volume production and 800V premium architectures.
Market Dynamics
The voltage platform split between 400V volume architectures and 800V premium systems is forcing relay suppliers to dual-qualify contact assemblies and ceramic sealing processes for divergent rupture capacity requirements.
Growth Catalysts
- China's dual carbon goals:NEV mandates compress supplier qualification timelines and accelerate procurement volume from domestic battery pack integrators co-located in the Yangtze River Delta cluster.
- GB/T safety standards:MIIT-enforced high-voltage connector and relay verification above 1500V impulse withstand raises technical barriers that favor qualified incumbent suppliers.
- Solid-state contact technology:Semiconductor-based architectures capture design wins in 800V+ platforms where switching speed and cycle life requirements outweigh electromechanical unit cost advantages.
Market Restraints
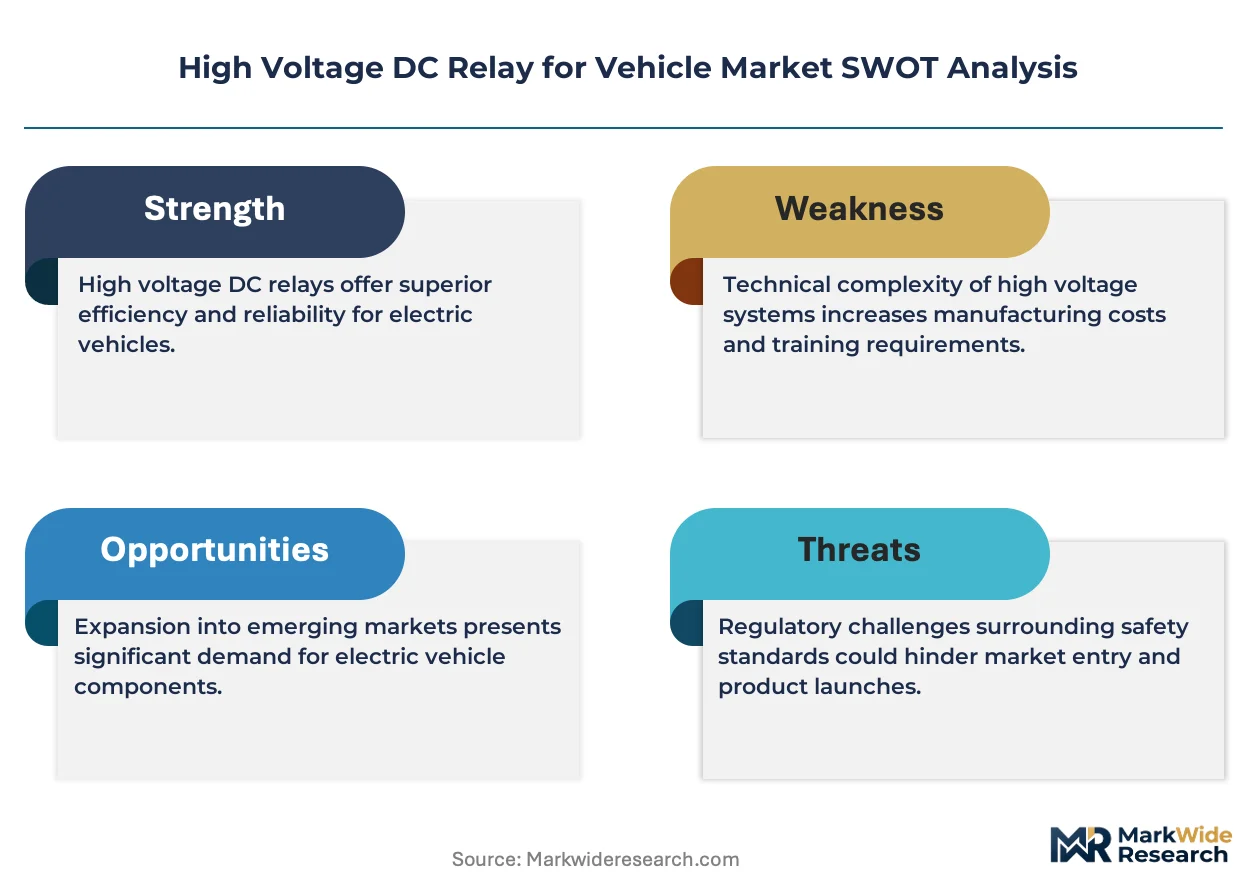
- Silver-copper alloy input volatility:Contact material cost exposure constrains margin flexibility for relay manufacturers without backward integration into precious metal supply.
- Yangtze River Delta concentration:Tier-1 system integrator and relay manufacturer co-location creates geographic supply risk from regional logistics disruptions or energy rationing.
- Fluorinated gas restrictions:EU F-Gas Regulation and ECE R100 convergence limit arc suppression chemistry options, forcing ceramic chamber redesigns.
Strategic Opportunities
- India PLI scheme for auto components:Localized manufacturing incentives attract relay qualification programs targeting domestic NEV assembly and export eligibility.
- Relay module integration:Pre-charge resistors and current sensors consolidated into system-level products capture margin pools beyond discrete component pricing.
- Fast-charge infrastructure buildout:Charging station OEMs require high-cycle-life relays for DC port isolation, opening a channel parallel to vehicle onboard applications.
Industry Challenges
- Functional safety documentation:EU AI Act convergence with automotive standards demands ISO 26262 traceability that extends qualification timelines for new relay architectures.
- 800V platform qualification backlog:Dual certification requirements for 400V and 800V systems strain testing capacity and engineering resources at specialized high-voltage laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage DC Relay for Vehicle Market |
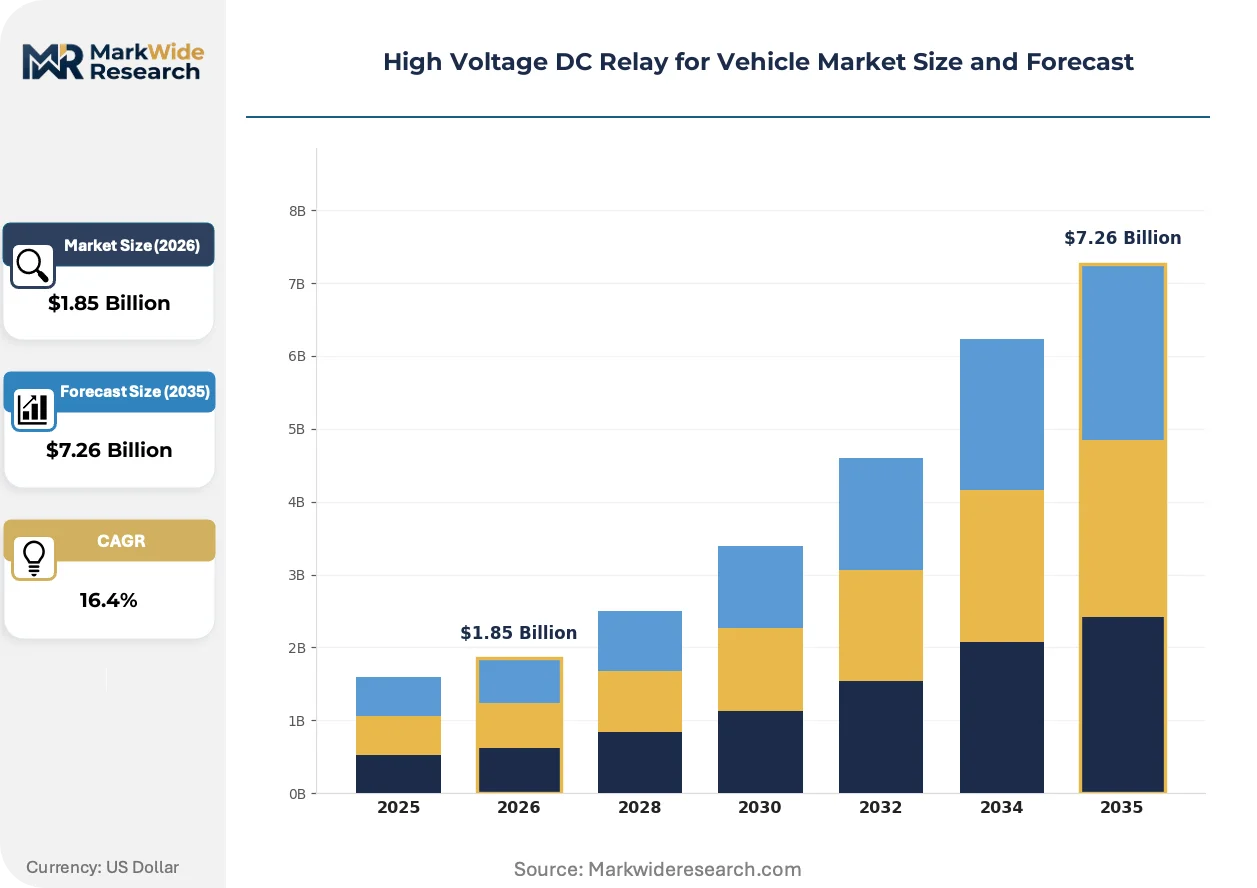
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact, Hybrid, Solid State, Relay Module Technology: Electromechanical, Semiconductor, Optical, Magnetic End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Installation: Onboard, Remote, Centralized, Modular |
| Companies Covered | TE Connectivity, Panasonic Industry, Fujitsu Components, ABB, Sensata Technologies, Mitsubishi Electric, Eaton, Omron Corporation, Littelfuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage DC Relay for Vehicle Market Trends and Innovations
Voltage platform diversification and regulatory chemistry restrictions are compressing relay design cycles while opening modular system-level revenue streams beyond discrete switching components.
Ceramic sealing technology is migrating from traditional electromechanical relay cores to hybrid contact assemblies that withstand 1000V+ DC rupture events. Battery pack makers adopting 800V architectures specify these hermetically sealed designs to meet GB/T impulse withstand requirements. The technology is migrating from Japanese OEM supply chains into Chinese NEV platforms as JIS-certified suppliers expand qualification programs.
EU F-Gas Regulation alignment with ECE R100 restricts sulfur hexafluoride and other fluorinated gases historically used in arc suppression chambers. Relay manufacturers must reformulate quenching media toward vacuum or ceramic-based alternatives without compromising switching speed. European powertrain integrators face compressed redesign timelines as 2025 compliance deadlines approach for new vehicle type approvals.
Direct-to-OEM supply relationships fragment as battery pack makers and powertrain integrators build captive relay qualification programs with dedicated engineering teams. Tier-1 system integrators displace traditional distribution channels by specifying relay modules rather than discrete components. This channel shift concentrates most visibly in China's Yangtze River Delta automotive cluster where pack assembly and relay manufacturing co-locate.
High Voltage DC Relay for Vehicle Market Segmentation
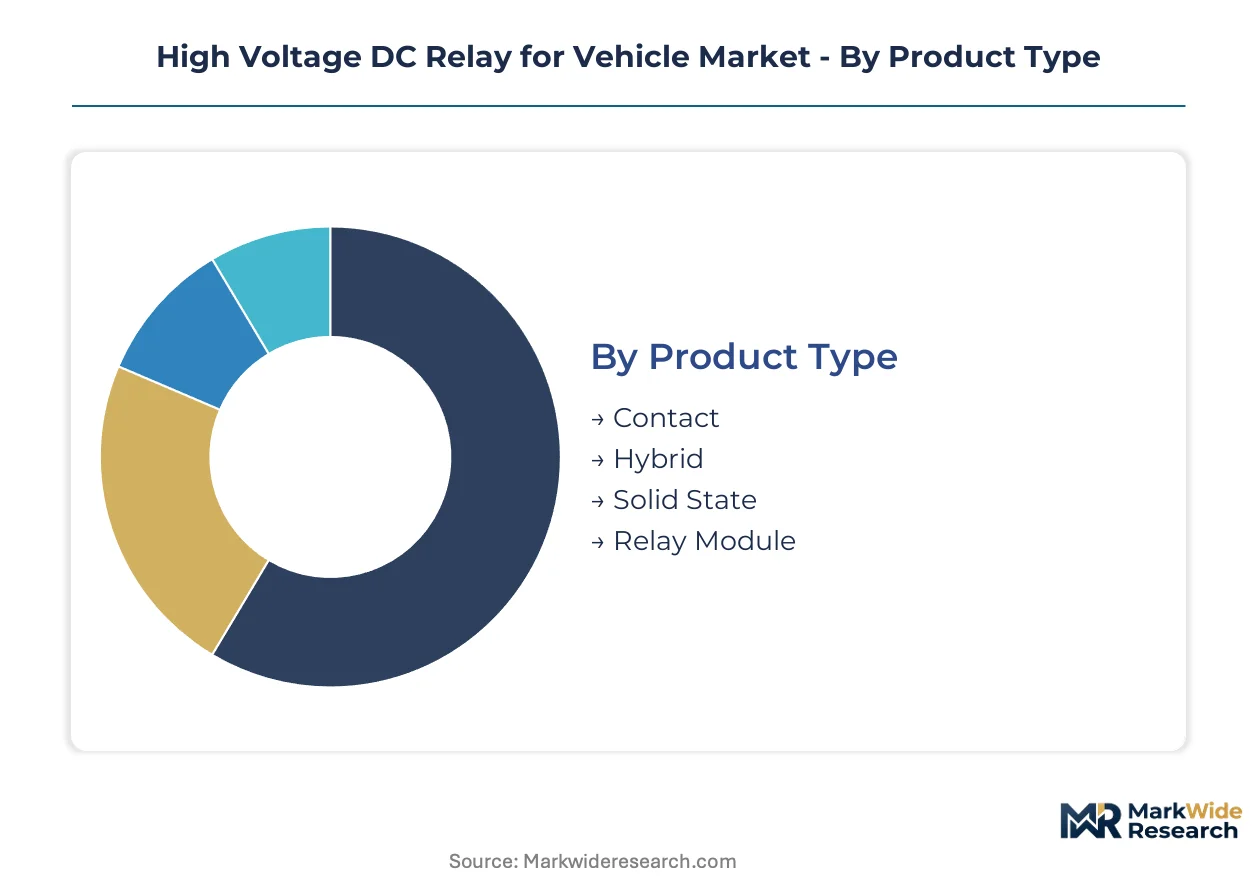
Voltage platform diversification and supply chain reconfiguration are fragmenting procurement patterns across relay categories. Segment boundaries are blurring as battery pack integrators specify system-level modules rather than discrete components.
Product Type:
Cycle times vary sharply—contact products refresh annually with vehicle model years while solid-state architectures face 3-4 year qualification horizons.
- Contact:Electromechanical switching assemblies with silver-copper alloy contacts and ceramic arc chambers dominate procurement volume. Yangtze River Delta battery pack integrators source these for 400V volume platforms where rupture capacity and cost structure outweigh switching speed requirements.
- Hybrid:Designs combine electromechanical contacts with semiconductor auxiliary paths to optimize switching dynamics. Chinese NEV platforms adopting 800V architectures specify these for pre-charge sequencing where GB/T impulse withstand testing above 1500V is mandatory.
- Solid State:Silicon carbide and IGBT-based switching eliminates mechanical wear for high-cycle applications.
- Relay Module:Integrated assemblies consolidating pre-charge resistors, current sensors, and control logic.
Contact products anchor the volume base while relay modules gain share at the steepest rate.
Technology:
Cost tiers separate mature electromechanical production from capital-intensive semiconductor fabrication.
- Electromechanical:Proven rupture capacity above 1000V DC with hermetically sealed ceramic chambers. Japanese OEM supply chains favor JIS-certified variants from established suppliers for domestic hybrid and battery electric platforms.
- Semiconductor:Silicon carbide MOSFET and IGBT architectures deliver sub-millisecond switching for 800V+ fast-charge port isolation. European powertrain integrators specify these where EU F-Gas Regulation restricts traditional arc suppression chemistry.
- Optical:Isolated gate drivers using fiber optic or LED-phototransistor coupling.
- Magnetic:Reed relay and Hall-effect switching for low-current signal paths.
Electromechanical technology captures the dominant revenue share while semiconductor architectures expand most quickly in premium voltage tiers.
End User:
Customer type determines specification authority and contract duration.
- OEMs:Direct vehicle manufacturer procurement for powertrain and battery disconnect applications. China's MIIT NEV mandates compress qualification timelines for domestic OEMs co-located with tier-1 integrators.
- Aftermarket Providers:Replacement relay sourcing for service and repair networks. European independent distributors stock GB/T and ECE R100-certified variants for cross-border vehicle fleets.
- Fleet Operators:Bulk procurement for commercial vehicle electrification programs.
- Dealerships:Localized inventory for warranty service and collision repair.
OEMs anchor the volume base while fleet operators gain share at the steepest rate.
Installation:
Application geometry dictates thermal management and packaging constraints.
- Onboard:Battery pack and powertrain-integrated switching for vehicle propulsion systems. Chinese tier-1 integrators in the Yangtze River Delta cluster specify these for co-located assembly with relay manufacturers.
- Remote:Distributed switching for charging infrastructure and energy storage systems. Fast-charge station OEMs require high-cycle-life variants for DC port isolation in 800V+ installations.
- Centralized:Single-point distribution architecture for compact vehicle platforms.
- Modular:Swappable relay cartridges for serviceability and upgrade paths.
Onboard installation anchors the volume base while remote installation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's Yangtze River Delta automotive cluster while European powertrain integrators absorb compliance cost premiums from EU F-Gas Regulation alignment with ECE R100.
China
NEV procurement from BYD, CATL, and NIO compresses supplier qualification timelines under MIIT GB/T standards mandating 1500V impulse withstand verification. The dual carbon goals accelerate domestic battery pack integration. Yangtze River Delta co-location of tier-1 system integrators and relay manufacturers concentrates technical specification authority in Shanghai-Suzhou corridor assembly plants.
Japan
Domestic OEM supply chains for Toyota, Honda, and Nissan hybrid platforms sustain demand for JIS-certified relays rated above 800V DC. METI coordinates PMDA-adjacent automotive component reliability frameworks that shape export eligibility requirements. Kanto region manufacturing clusters around Tokyo and Yokohama anchor ceramic sealing expertise for hermetic contact assemblies.
Germany
BMW, Mercedes-Benz, and Volkswagen 800V premium architectures drive semiconductor-based relay procurement where switching speed outweighs electromechanical cost structures. ECE R100 convergence with EU F-Gas Regulation restricts sulfur hexafluoride arc suppression chemistry. Bavaria and Baden-Württemberg automotive engineering centers specify vacuum chamber alternatives for 2025 type approval deadlines.
United States
Tesla, Rivian, and Lucid Motors battery electric platforms fragment direct-to-OEM supply channels toward captive relay qualification programs. NHTSA safety frameworks and EPA emissions standards shape high-voltage component documentation requirements. Michigan and California engineering centers co-locate with tier-1 powertrain integrators specifying relay modules over discrete components.
South Korea
Hyundai-Kia and Samsung SDI electrification programs source electromechanical relays for 400V volume platforms alongside solid-state evaluation for 800V Genesis premium architectures. MFDS automotive component standards intersect with export qualification protocols. Seoul Capital Area and Busan-Ulsan manufacturing belts concentrate battery pack assembly with relay manufacturer technical partnerships.
High Voltage DC Relay for Vehicle Market Competitive Landscape
Component specialists and diversified electrical engineering conglomerates split the market across technology tiers. Supplier concentration remains moderate with electromechanical incumbents defending installed base positions against semiconductor architecture entrants. Three archetypes dominate: Japanese ceramic sealing specialists, European diversified industrial conglomerates, and Asian contact material integrators. Competitive moves center on backward integration into precious metal supply and geographic co-location with battery pack assembly clusters.
Within the Japanese specialist tier, Panasonic Industry and Mitsubishi Electric exemplify ceramic sealing and JIS certification anchoring strategies. TE Connectivity represents diversified conglomerate positioning with vertically integrated contact material production spanning multiple voltage platforms. These three companies occupy positions that mirror the tripartite supply chain structure: qualification-heavy OEM direct channels, tier-1 system integrator specifications, and fast-charge infrastructure parallel demand.
| Leading Market Players |
|---|
| TE Connectivity |
| Panasonic Industry |
| Fujitsu Components |
| ABB |
| Sensata Technologies |
| Mitsubishi Electric |
| Eaton |
| Omron Corporation |
| Littelfuse |
| Others |
Pricing and Supply Chain Analysis
Silver-copper alloy contact material sourcing from Japanese and Chinese smelters anchors cost structures while margin pools concentrate with relay module integrators serving Yangtze River Delta battery pack assemblers. The upstream precious metal concentration forces electromechanical suppliers to absorb commodity volatility or pursue captive refining investments.
Pricing Analysis
Configured-to-order pricing for 800V hybrid and solid-state architectures commands premiums against standard contact-product catalogs. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified hermetic designs from GB/T-compliant volume tiers and aftermarket replacement units. Price differentiation hinges on impulse withstand certification grade and ceramic sealing process complexity. Cost compression in 400V electromechanical tiers is intensifying because Yangtze River Delta pack integrators consolidate procurement volumes. Fleet operators exhibit the highest price sensitivity, while German OEMs specifying 800V semiconductor architectures demonstrate the lowest.
Supply Chain Analysis
Silver-copper alloy feedstock draws from Japanese precious metal refiners and Chinese state-owned smelters, with ceramic substrate supply anchored in German and Japanese industrial ceramics clusters. Raw material dependencies center on silver bullion, high-purity copper, and alumina ceramic powders. Single-source vulnerability concentrates in hermetic sealing equipment where Japanese specialists dominate precision furnace supply. Distribution runs through tier-1 system integrator direct channels that displace traditional component distributors in the Yangtze River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery pack maker consolidation into tier-1 system integrators has shifted specification authority away from traditional OEM procurement offices, fragmenting incumbent relay supplier relationships.
For Market Incumbents: Insulate JIS-certified installed base positions through ceramic sealing process patents while accelerating 800V qualification capacity at Yangtze River Delta technical centers. Semiconductor architecture entrants threaten electromechanical share in premium voltage tiers; backward integration into silver-copper alloy supply hedges margin compression from precious metal volatility. For New Entrants and Emerging Players: Establish a beachhead in fast-charge infrastructure remote installation applications where cycle life specifications favor solid-state switching and incumbent qualification backlogs create procurement gaps. India's PLI scheme for auto components offers the most penetrable geography for greenfield relay manufacturing with export eligibility to ASEAN markets. Target charging station OEMs through direct engineering partnerships bypassing vehicle-tier qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward ceramic sealing specialists with JIS certification and existing Yangtze River Delta customer relationships, as these assets compound defensibility across voltage platform transitions. Long-term viability in this market rests on qualification density rather than unit cost position. The signal to watch is MIIT GB/T standard revision timing, which could reset compliance thresholds and advantage pre-qualified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Sealing Capacity Expansion | Japanese specialists scale hermetic furnace operations to meet Chinese NEV 800V qualification demand. |
| Silver-Copper Alloy Backward Integration | Relay manufacturers acquire precious metal refining capabilities to stabilize contact material cost exposure. |
| Relay Module System Integration | Tier-1 integrators consolidate pre-charge resistors and current sensors to capture margin pools above discrete component pricing. |
| Fast-Charge Infrastructure Partnership | Charging station OEMs source high-cycle-life relays for DC port isolation in parallel to vehicle onboard channels. |
| Dual Voltage Platform Qualification | Suppliers invest in 400V and 800V testing capacity to serve divergent rupture capacity requirements simultaneously. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-1 system integrator procurement directors, OEM platform engineers, and fast-charge infrastructure OEM technical leads; and secondary validation against MIIT GB/T standard filings, ECE R100 type approval databases, vehicle production registries, and customs trade records. Bottom-up segment sizing triangulated against top-down voltage platform adoption curves across the analysis window.
Forecast inputs considered electromechanical versus semiconductor technology substitution rates, regional NEV mandate enforcement trajectories, and ceramic sealing capacity expansion timelines. Segmentation dimensions modeled include product type, voltage platform tier, installation geometry, and end-user procurement authority. CAGRs were derived from installed base growth and content-per-vehicle assumptions across the projection horizon, with silver-copper alloy price scenarios and F-Gas Regulation compliance deadlines as sensitivity variables.
Stress conditions across precious metal price volatility, Yangtze River Delta logistics disruption, and 800V platform adoption acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about GB/T standard stability and tier-1 integrator consolidation trajectories. Cross-checking against IHS Markit vehicle production forecasts and MIIT NEV penetration targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market