
 Automotive Temperature and Humidity Sensors Market | 2026-2036
Automotive Temperature and Humidity Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Temperature and Humidity Sensors Market Analysis
The performance gap between premium and commodity automotive temperature and humidity sensors is broadening as OEMs demand sub-0.5°C accuracy for battery thermal management while entry-level vehicles accept wider tolerances. Robert Bosch leverages its MEMS fabrication depth to anchor high-precision digital output lines for European luxury platforms. Sensata Technologies competes through captive semiconductor packaging that sustains cost discipline across mid-volume programs. Texas Instruments specializes in integrated signal-conditioning ICs that differentiate its offerings from discrete-component rivals.
Automotive temperature and humidity sensors are transducer-based devices that convert thermal energy and water vapor concentration into electrical signals, typically operating across -40°C to 150°C with humidity ranges of 0% to 100% RH for underhood and cabin applications. Capacitive humidity elements dominate premium installations where drift resistance and long-term stability matter, while resistive temperature detectors retain share in cost-optimized engine monitoring due to simpler conditioning circuitry. Digital sensor outputs are displacing analog interfaces in climate control modules as OEMs consolidate LIN and CAN bus architectures. MEMS-based temperature sensors represent the fastest-growing technology segment, driven by miniaturization demands in HVAC systems where packaging volume constraints intensify.
NHTSA thermal runaway protocols and EPA fuel-efficiency benchmarks are tightening cabin climate precision requirements in the United States, while ECHA REACH restrictions on certain polymer substrates are reshaping material selection for European sensor housings. China's MIIT dual carbon goals and GB standards for new energy vehicle safety are accelerating domestic certification requirements for battery-adjacent thermal monitoring. Stakeholders must monitor how regional compliance divergence affects platform standardization strategies and supplier qualification timelines.
Market Dynamics
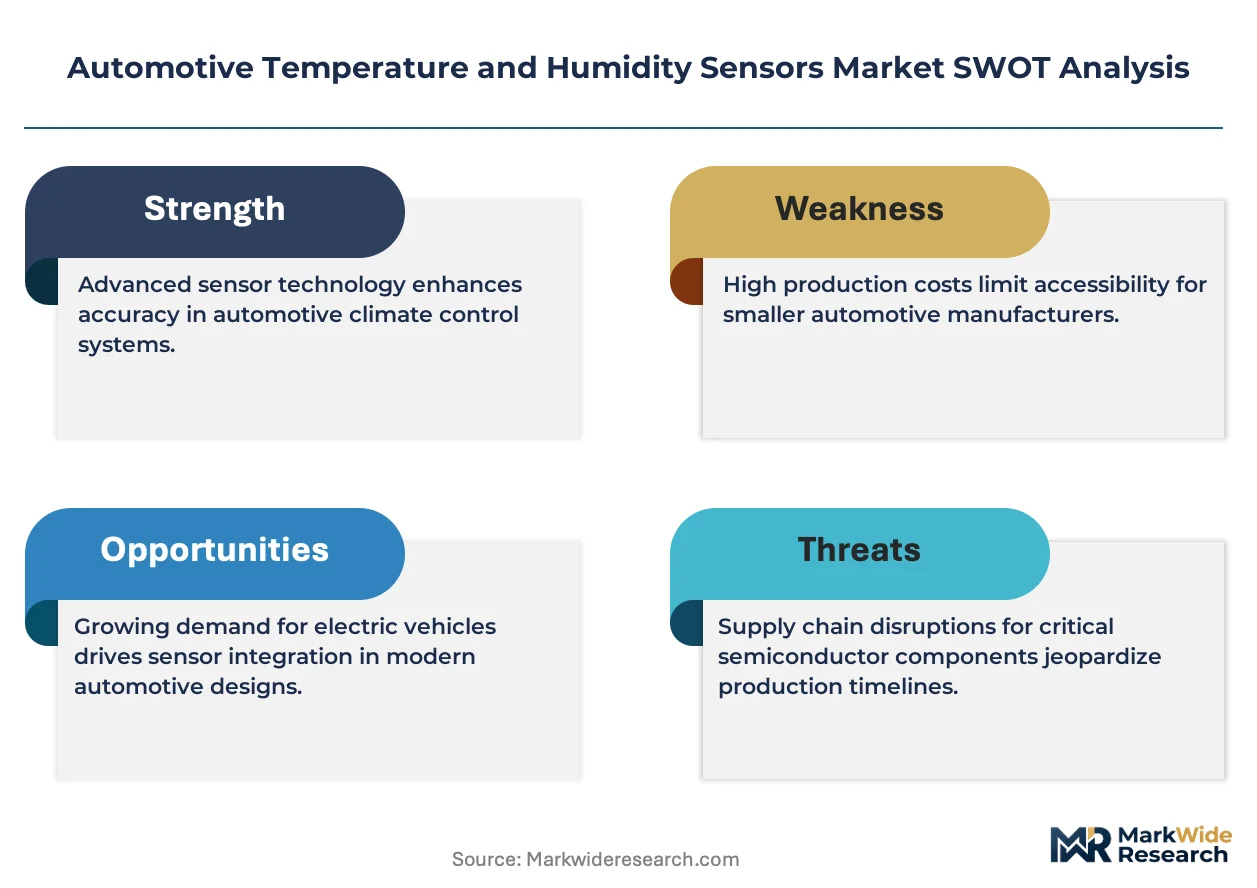
Electric vehicle battery thermal management systems are forcing a sensor accuracy arms race as OEMs mandate sub-0.5°C precision for cell monitoring, compressing tolerance bands that commodity suppliers cannot meet. This precision divide is restructuring supplier tiers and procurement patterns across automotive platforms.
Growth Catalysts
- NHTSA Thermal Runaway Protocols:Mandated battery temperature monitoring density is expanding sensor counts per pack. US OEMs now specify multi-point thermal arrays for cylindrical and prismatic cell configurations.
- Capacitive Humidity Sensing:Drift-resistant polymer films are displacing resistive elements in premium cabin climate modules. European luxury platforms specify these for 15-year service life guarantees.
- China MIIT Dual Carbon Goals:Domestic NEV safety standards are accelerating certification requirements for battery-adjacent thermal monitoring. Local suppliers are scaling MEMS fabrication to capture this procurement volume.
Market Restraints
- MEMS Foundry Concentration:Taiwan and South Korea dominate 200mm MEMS wafer supply. Automotive qualification cycles create 18-24 month lock-in with limited second-source options.
- Palladium Electrode Costs:Resistive temperature detector assemblies face input volatility from precious metal markets. Cost-optimized engine monitoring segments absorb margin compression.
- ECHA REACH Polymer Restrictions:Certain housing substrates face phase-out timelines. European suppliers must reformulate encapsulants without compromising IP67 sealing integrity.
Strategic Opportunities
- India NEV Adoption Curve:Domestic battery assembly plants are greenfield installations without legacy analog sensor infrastructure. Digital LIN-bus architectures allow direct specification of multi-function environmental sensors.
- Vehicle-to-Grid Integration:Bidirectional charging requires cabin preconditioning coordination with grid signals. Humidity-aware thermal management optimizes HVAC energy draw during peak shaving events.
- EU F-Gas Regulation Phase-Down:Refrigerant transition to CO2 and HFO blends demands tighter superheat control. Precision temperature-humidity sensor pairs enable next-generation heat pump calibration.
Industry Challenges
- Automotive SPICE Compliance:Software-enabled digital sensors require ASIL-rated embedded code development. Supplier engineering teams face talent scarcity in functional safety certification.
- Legacy Analog Module Integration:Climate control ECUs with 10-15 year platform life resist digital bus migration. Dual-interface sensor SKUs inflate BOM complexity for tiered vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Temperature and Humidity Sensors Market |
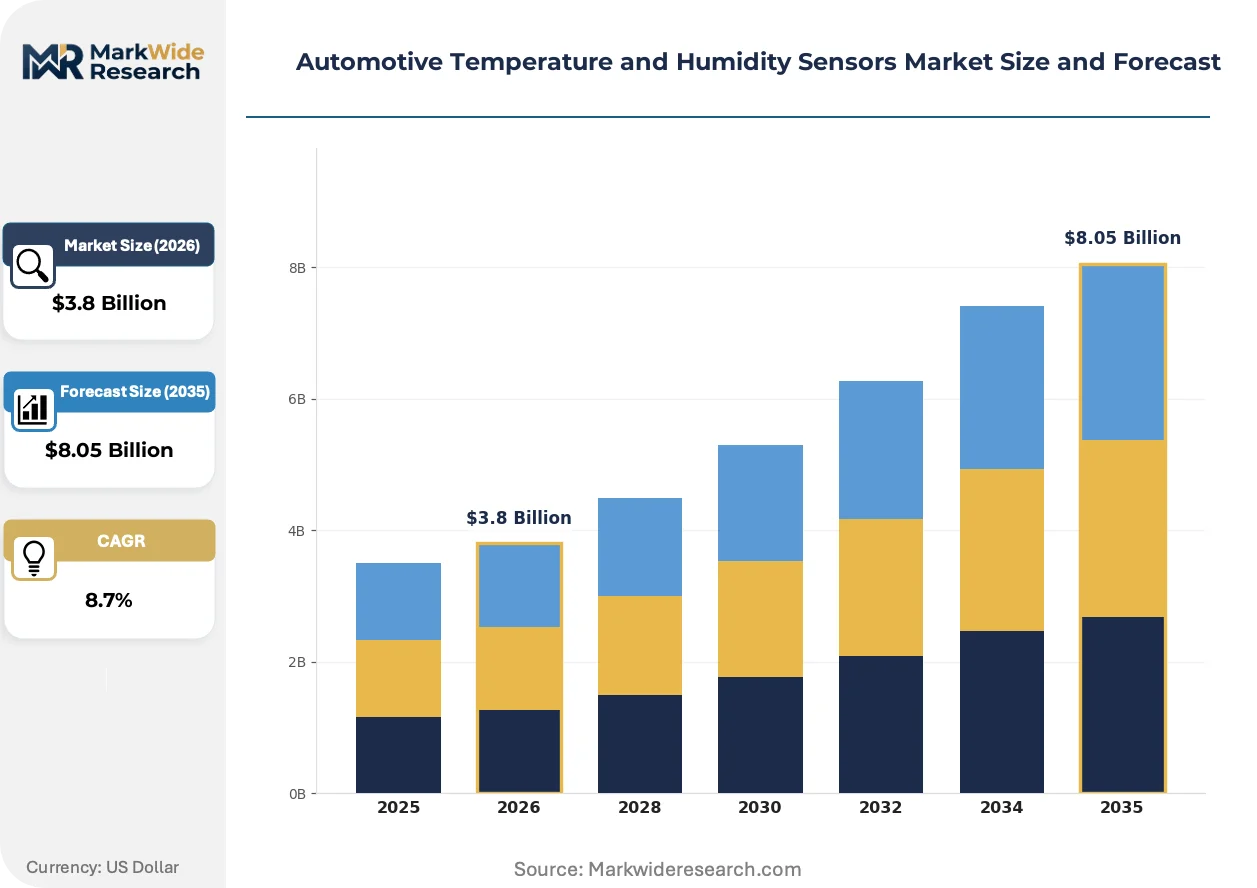
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Resistive Sensors, Digital Sensors, Analog Sensors Application: Climate Control, Cabin Comfort, Engine Monitoring, HVAC Systems End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Wireless, Wired, MEMS, Analog |
| Companies Covered | TDK, Sensata Technologies, Robert Bosch, Continental AG, NXP Semiconductors, Texas Instruments, TE Connectivity, Sensirion, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Temperature and Humidity Sensors Market Emerging Trajectories
Sensor fusion architectures are collapsing discrete temperature and humidity functions into single-package environmental nodes. This integration wave is compressing module counts while elevating software complexity in climate control domains.
MEMS-based multi-sensor arrays are decentralizing thermal mapping across battery packs and HVAC ducts. Tier 1 suppliers specify these for zonal climate control in premium electric SUVs. Distributed intelligence is reducing wiring harness weight and enabling over-the-air calibration updates.
Europe's F-Gas Regulation and impending Euro 7 emissions standards are tightening cabin climate precision requirements. OEMs must demonstrate real-time refrigerant charge optimization through continuous humidity-aware superheat measurement. German luxury platforms are first-movers in specifying predictive HVAC algorithms that anticipate fogging risk.
Fleet operators and mobility-as-a-service providers are consolidating sensor procurement through long-term platform agreements. Direct OEM-supplier contracts are displacing tiered distribution for high-volume electric vehicle programs. This concentration is most visible in China where domestic battery manufacturers specify sensor standards across multiple OEM customers.
Automotive Temperature and Humidity Sensors Market Segmentation
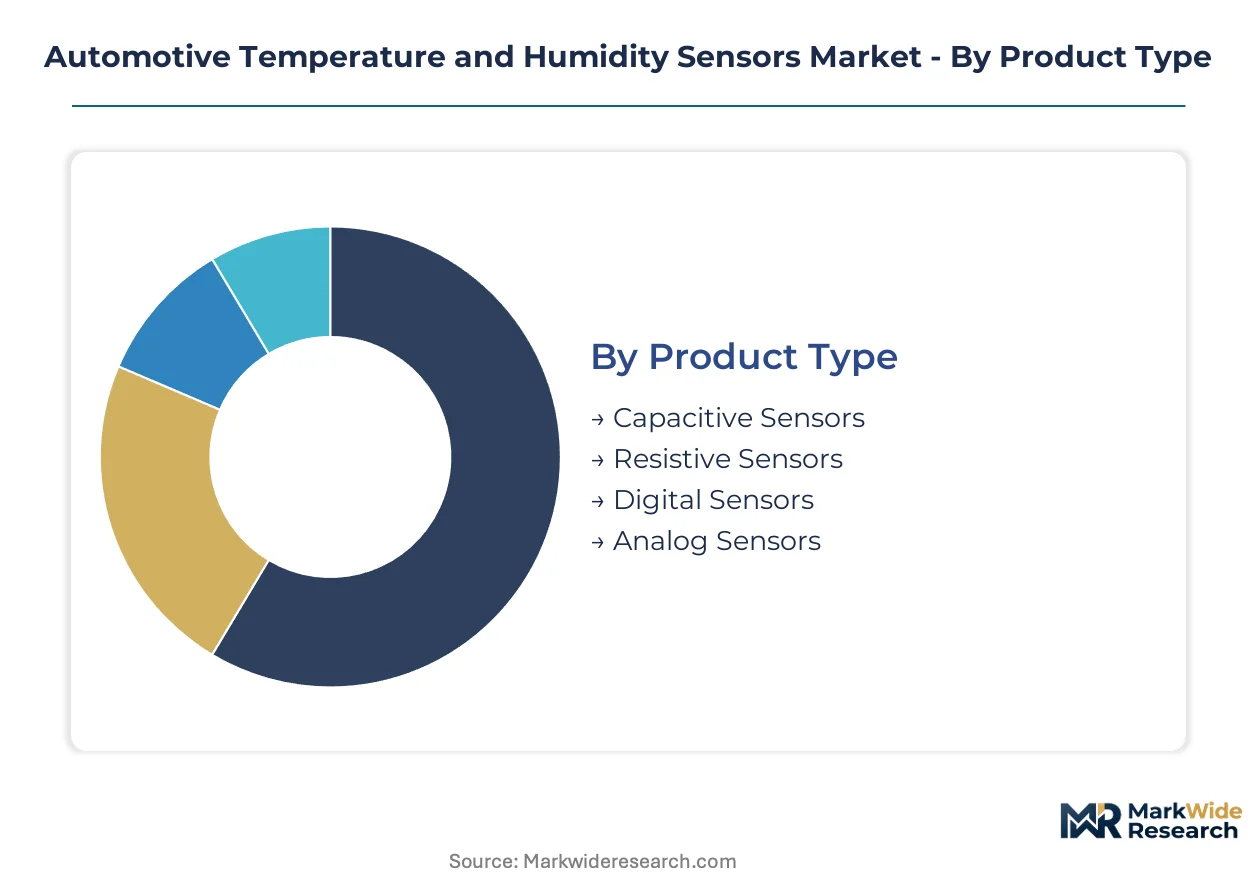
Sensor architecture choices in automotive temperature and humidity monitoring determine qualification timelines, foundry partnerships, and software integration burdens. Procurement patterns diver sharply across precision tiers and thermal management applications.
Product Type:
Supply concentration for precision-grade sensing elements favors capacitive and digital architectures, while commodity engine monitoring sustains resistive and analog volumes.
- Capacitive Sensors:Polymer dielectric films measure humidity through capacitance variation, achieving drift resistance critical for 15-year cabin climate guarantees. German luxury platforms specify these for battery-adjacent thermal monitoring where sub-0.5°C accuracy is mandatory.
- Digital Sensors:LIN and CAN bus outputs consolidate wiring harness architecture while enabling over-the-air calibration updates. China's NEV safety standards are accelerating domestic MEMS foundry investment to capture this procurement volume.
- Resistive Sensors:Platinum or palladium thin-film elements dominate cost-optimized engine monitoring where simpler conditioning circuitry offsets precision trade-offs.
- Analog Sensors:Voltage-output devices persist in legacy climate control modules with 10-15 year platform life resisting digital migration.
Today's leader: Capacitive Sensors. Tomorrow's challenger: Digital Sensors.
Application:
Application-driven procurement splits between precision-critical battery thermal management and volume-scale cabin comfort systems.
- Climate Control:Multi-zone HVAC algorithms demand humidity-aware superheat measurement for refrigerant charge optimization under Europe's F-Gas Regulation. German OEMs specify predictive fogging prevention for premium electric SUVs.
- Engine Monitoring:Resistive temperature detectors track coolant and oil thermal states with wider tolerance bands acceptable to entry-level vehicle programs.
- HVAC Systems:MEMS-based miniaturization addresses packaging volume constraints in duct-mounted sensor nodes.
- Cabin Comfort:Occupant-facing humidity sensing enables automatic defogging and air quality management.
Climate Control commands current procurement spend. Battery-adjacent thermal monitoring within Climate Control applications climbs the fastest.
End User:
Customer-type concentration is shifting from tiered distribution toward direct OEM-supplier contracting for high-volume electric vehicle programs.
- OEMs:Direct platform agreements consolidate multi-year sensor procurement for battery thermal management standardization.
- Tier-1 Suppliers:Climate control module integrators specify sensor fusion architectures collapsing discrete functions into single-package environmental nodes.
- Vehicle Assemblers:Greenfield NEV plants in India specify digital LIN-bus architectures without legacy analog infrastructure.
- Aftermarket Providers:Replacement sensor volumes track vehicle parc age distribution and warranty expiration curves.
OEMs dominate contract value. Tier-1 Suppliers capture expanding specification influence.
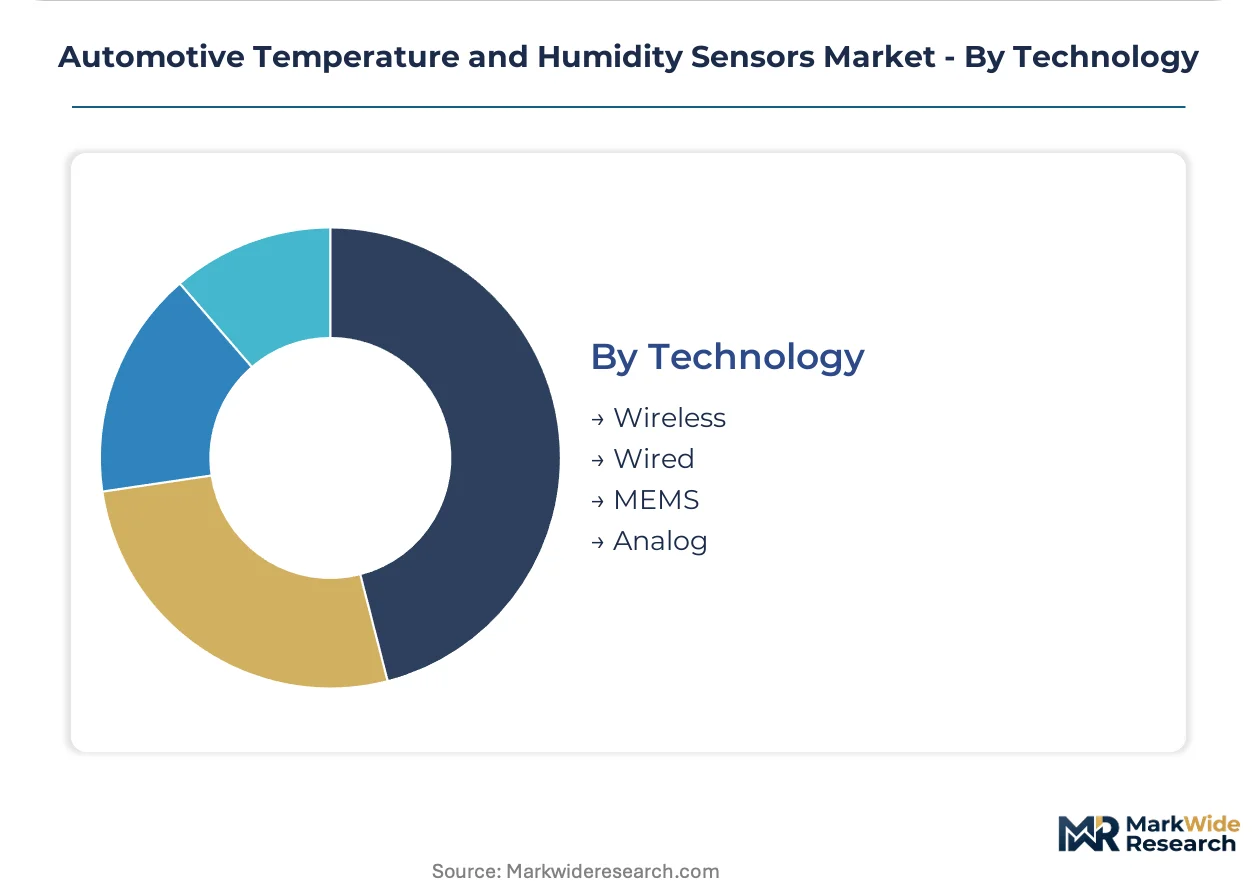
Technology:
Technology selection determines semiconductor packaging complexity and functional safety certification requirements.
- MEMS:Micromachined thermal elements enable multi-sensor arrays for zonal climate control and distributed battery pack mapping.
- Wired:LIN and CAN physical layers remain dominant for deterministic latency in safety-critical thermal monitoring.
- Wireless:Eliminates harness weight in seat-integrated or steering wheel-mounted comfort sensing.
- Analog:Persists where legacy ECU architectures resist digital bus migration.
MEMS anchors technology investment. Wireless gains traction for non-critical comfort applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Detroit, and Shanghai anchor sensor procurement decisions for battery thermal management and cabin climate systems across major automotive production zones.
United States
NHTSA thermal runaway protocols mandate multi-point battery monitoring arrays for cylindrical and prismatic cell configurations. EPA fuel-efficiency benchmarks tighten cabin climate precision requirements for light-duty vehicles. Detroit-area OEM engineering centers specify digital LIN-bus architectures for next-generation electric truck platforms.
Germany
Luxury electric SUV programs drive demand for sub-0.5°C accuracy in zonal climate control modules. ECHA REACH restrictions on polymer substrates force reformulation of sensor encapsulants without compromising IP67 sealing integrity. Stuttgart and Munich engineering clusters coordinate F-Gas Regulation compliance across heat pump calibration systems.
China
Domestic NEV battery assembly plants scale MEMS fabrication capacity to capture procurement volume from MIIT dual carbon goals. GB standards for new energy vehicle safety accelerate certification timelines for battery-adjacent thermal monitoring. Shanghai and Shenzhen foundry investments reduce dependence on Taiwan 200mm wafer supply.
Japan
Automotive OEMs integrate humidity-aware superheat measurement for next-generation CO2 heat pump systems. METI industrial policy supports domestic semiconductor packaging for climate control module suppliers. Nagoya-area tier-1 clusters specify predictive fogging prevention algorithms for premium electric vehicle exports.
India
Greenfield NEV battery plants bypass legacy analog sensor infrastructure through direct digital architecture specification. Domestic assembly operations for cylindrical cell configurations create demand for multi-point thermal arrays. Tamil Nadu and Gujarat manufacturing corridors attract sensor module integrators serving export markets.
Automotive Temperature and Humidity Sensors Market Vendor Landscape
Top-tier vendors anchor precision-grade sensing for battery thermal management, while commodity suppliers serve cost-optimized engine monitoring segments. The vendor base stratifies across three tiers: integrated semiconductor manufacturers with captive MEMS fabrication, specialized sensor houses with automotive qualification depth, and diversified component suppliers leveraging climate control module relationships. Two dominant competitive moves are reshaping positioning: foundry partnerships to secure 200mm MEMS wafer allocation, and sensor fusion architectures that collapse discrete functions into single-package environmental nodes.
Among European-based diversified suppliers, Robert Bosch and Continental AG occupy positions spanning premium-tier digital output lines through integrated module supply. Sensata Technologies exemplifies the specialized sensor house archetype with captive semiconductor packaging discipline. Texas Instruments represents the semiconductor-centric approach through integrated signal-conditioning IC differentiation. These three anchors illustrate how technology depth, automotive qualification timelines, and foundry access stratify competitive positioning across precision tiers.
| Leading Market Players |
|---|
| TDK |
| Sensata Technologies |
| Robert Bosch |
| Continental AG |
| NXP Semiconductors |
| Texas Instruments |
| TE Connectivity |
| Sensirion |
| STMicroelectronics |
| Others |
Supply Flow & Price Mechanics
Captive MEMS fabrication anchors both supply security and pricing power for precision-grade sensor suppliers serving battery thermal management contracts. Robert Bosch and Sensata Technologies leverage in-house semiconductor packaging to defend margin structures against commodity competitors dependent on external foundry access.
Pricing Analysis
Discrete component sales dominate low-volume aftermarket channels while bundled module supply captures premium pricing through climate control ECU integration. Three-tier pricing structure across precision-certified, automotive-grade, and industrial-grade levels reflects ASIL certification investment and foundry qualification timelines. Cost compression in resistive temperature detector segments stems from palladium electrode volatility and simpler conditioning circuitry requirements. Entry-level vehicle programs exhibit highest price sensitivity, while luxury electric SUV platforms prioritize sub-0.5°C accuracy over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for 200mm MEMS wafer supply, creating 18-24 month qualification lock-in for automotive programs. Sensor housings draw from polymer substrate suppliers facing ECHA REACH reformulation timelines, while platinum and palladium thin-film elements rest on precious metal market dynamics. Tariff exposure runs through cross-border semiconductor packaging flows between European module integrators and Asian foundry partners. Distribution runs through direct OEM contracting for high-volume electric vehicle platforms, displacing tiered distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive temperature and humidity sensors rests on MEMS miniaturization cost curves and the shift toward digital LIN-bus architectures that command premium pricing over legacy analog outputs.
For Market Incumbents: Cement foundry partnerships with 200mm MEMS wafer allocation to secure capacity for battery thermal management qualification cycles. Lock in multi-year platform agreements with German and Chinese OEMs before commodity suppliers achieve automotive-grade certification. Defend against emerging MEMS specialists by accelerating sensor fusion R&D that collapses discrete temperature and humidity functions into single-package environmental nodes. For New Entrants and Emerging Players: Direct digital sales channels to Indian greenfield NEV plants bypass legacy analog infrastructure requirements and tiered distribution markups. Target vehicle-to-grid integration applications where humidity-aware thermal management algorithms create specification influence without competing on foundry scale. Pursue white-label supply relationships with climate control module integrators seeking second-source options for LIN-bus sensor arrays. For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor houses with captive semiconductor packaging because automotive qualification timelines create durable moats against pure-play MEMS foundries. Focus acquisition screening on targets with ASIL-rated embedded code capabilities and existing OEM platform engineering relationships. Watch for inflection when China's domestic MEMS foundry investments achieve automotive-grade yield rates, potentially reshaping procurement geography.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures 200mm wafer allocation for NHTSA-mandated battery thermal monitoring arrays. |
| Sensor Fusion Architecture Development | Collapses discrete functions into single-package nodes for zonal climate control in premium SUVs. |
| ASIL Functional Safety Certification | Enables software-enabled digital sensor supply to European luxury platforms. |
| Digital LIN-Bus Platform Standardization | Captures procurement from Indian greenfield NEV plants without legacy analog infrastructure. |
| Polymer Encapsulant Reformulation | Maintains IP67 sealing integrity under ECHA REACH substrate restrictions. |
Methodological Framework
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, MEMS foundry operations managers, and climate control module integrators grounded qualitative insights in operational reality. Secondary validation drew from NHTSA regulatory filings, ECHA REACH substance restriction updates, MIIT dual carbon policy documents, and vehicle production databases. Bottom-up sensor unit estimates triangulated against top-down climate control module shipment data.
Segment-level projections across capacitive, digital, resistive, and analog architectures combined with application splits in battery thermal management, climate control, and engine monitoring. Propulsion architecture differentiation between battery electric, plug-in hybrid, and internal combustion platforms shaped content-per-vehicle assumptions throughout the modeling period. CAGRs derived from slope analysis of historical qualification timelines and announced OEM platform transitions.
The model assumes a particular technology adoption path; alternative pathways for wireless sensor networks in non-critical comfort applications would alter the outlook. Forecasts reflect assumptions about MEMS foundry yield progression, REACH compliance timelines, and NEV penetration curves that remain subject to revision. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Stepper Motors Market