
 Automotive Battery Market | 2026-2036
Automotive Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Market Analysis
Modular battery pack architectures with cell-to-chassis integration is repositioning how OEMs evaluate supplier partnerships. CATL leverages its vertical integration into cathode materials to sustain cost leadership across European EV programs. Panasonic anchors its competitiveness through high-nickel cylindrical cell specialization for premium passenger vehicles. Samsung SDI differentiates via prismatic solid-state development pipelines targeting next-generation platforms.
An automotive battery is an electrochemical storage device delivering direct-current power for vehicle propulsion, lighting, and auxiliary systems, typically operating at nominal voltages from 12V in conventional lead-acid starter units to 800V in high-performance lithium-ion traction packs. The device stores and releases energy through reversible redox reactions, with energy density, cycle life, and thermal stability serving as critical performance parameters governing vehicle range and safety. Lithium-ion chemistry occupies the dominant revenue position due to its gravimetric energy advantage, while solid-state configurations represent the fastest-growing technology segment as manufacturers resolve ceramic electrolyte manufacturing scalability. Passenger vehicles command the largest end-user volume pool, though electric buses concentrate margin-rich high-capacity procurement contracts with longer contract durations and stricter performance guarantees.
The US NHTSA and EPA coordinate crash-safety testing with emissions compliance timelines that effectively mandate zero-emission powertrains in key state markets. China's MIIT enforces GB/T standards for cell format, thermal runaway propagation resistance, and recycling traceability that shape export qualification requirements. The EU Battery Regulation establishes carbon footprint disclosure and recycled content minimums that will restructure supply chain sourcing decisions. Stakeholders must monitor how divergent regional compliance timelines for solid-state qualification and recycling infrastructure scale will fragment procurement strategies across manufacturing footprints.
Market Dynamics
Cell-to-chassis integration is compressing pack assembly tiers and forcing OEMs to renegotiate supplier relationships around direct cell sourcing rather than module procurement. This structural shift eliminates intermediate manufacturing layers while concentrating thermal management and structural engineering expertise at the vehicle platform level.
Growth Catalysts
- EU Battery Regulation carbon mandates:Recycled content minimums and carbon footprint disclosure requirements are redirecting cathode material sourcing toward European refining capacity and qualified scrap suppliers.
- Electric bus fleet procurement:Municipal operators in Shenzhen, Santiago, and European transit authorities are signing multi-year high-capacity contracts with performance guarantees extending beyond standard passenger vehicle warranties.
- 800V architecture proliferation:High-voltage traction systems reduce charging duration and copper mass, accelerating adoption across premium passenger vehicle platforms and enabling downsized thermal management hardware.
Market Restraints
- Lithium carbonate price volatility:Concentrated South American brine and Australian spodumene supply exposes cell manufacturers to input cost swings that compress margin visibility on long-term OEM contracts.
- Single-source cathode precursor dependence:China's dominance in refined cobalt, nickel sulfate, and lithium hydroxide processing creates geographic concentration risk for European and North American cell assembly operations.
- Solid-state ceramic electrolyte manufacturing yields:Current sintering and thin-film deposition processes suffer from defect rates and throughput limitations that delay commercial scale-up beyond pilot lines.
Strategic Opportunities
- India automotive electrification:PLI scheme incentives for cell and module manufacturing are attracting cathode active material investments to serve domestic two-wheeler and compact passenger vehicle demand.
- Second-life stationary storage:Retired EV packs with residual capacity are redirecting toward grid balancing and commercial peak-shaving applications through refurbished battery system integrators.
- V2G bidirectional charging infrastructure:Aggregated vehicle battery capacity is enabling frequency regulation services and demand response revenue streams for fleet operators with managed charging software.
Industry Challenges
- Thermal runaway propagation testing:China's GB/T and UN 38.3 certification timelines for cell-level abuse tolerance and system-level containment are extending product qualification cycles by six to twelve months.
- Electrolyte additive formulation IP:Patent thickets around high-voltage stabilizers and solid-electrolyte interphase enhancers are forcing licensing negotiations or work-around R&D investments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Market |
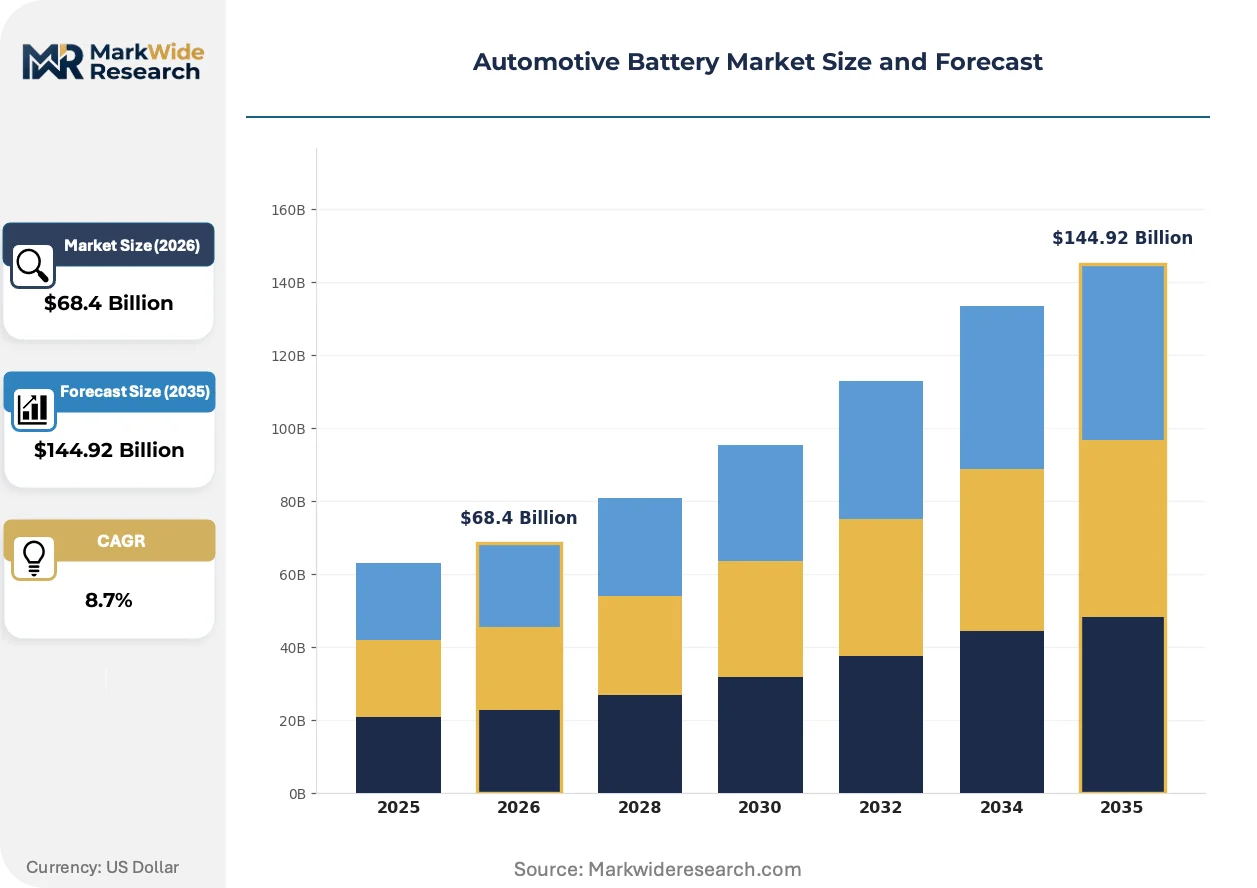
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Solid-State End User: Passenger Vehicles, Commercial Vehicles, E-Bikes, Electric Buses Technology: Start-Stop, Regenerative Braking, Fast Charging, Wireless Charging Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | SK On, Samsung SDI, CATL, Gotion High-Tech, EVE Energy, BYD, Panasonic, Sunwoda, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Market Emerging Trajectories
Electrochemical storage architectures are fragmenting across chemistry, form factor, and integration depth as OEMs pursue divergent paths to cost parity and performance differentiation. This diversification is compressing standardization timelines while elevating the strategic value of cell engineering partnerships.
Sodium-ion chemistry is decentralizing the mid-range energy density segment previously dominated by lithium iron phosphate. Chinese cell manufacturers are scaling prismatic sodium-ion production for urban delivery vehicles and entry-level passenger cars where gravimetric energy constraints are less severe. This chemistry is decentralizing cathode supply chains by eliminating lithium and cobalt dependence while enabling regional precursor sourcing.
China's MIIT enforcement of GB/T thermal runaway propagation standards is mandating multi-layer cell barriers and venting architectures that add mass and cost to pack designs. Cell manufacturers serving export markets must maintain parallel product configurations to satisfy divergent UN 38.3, UL 2580, and GB certification regimes. European OEMs are responding by consolidating cell sourcing around suppliers with qualified multi-standard testing capabilities.
Fleet operators are consolidating procurement decisions at the group purchasing organization level rather than through individual vehicle OEM channels. This buyer concentration is compressing contract negotiation cycles and elevating total-cost-of-ownership analytics over upfront pack pricing. The shift is most visible in German commercial vehicle leasing and Nordic electric bus tendering markets where lifecycle performance guarantees now dominate supplier selection criteria.
Automotive Battery Market Segmentation
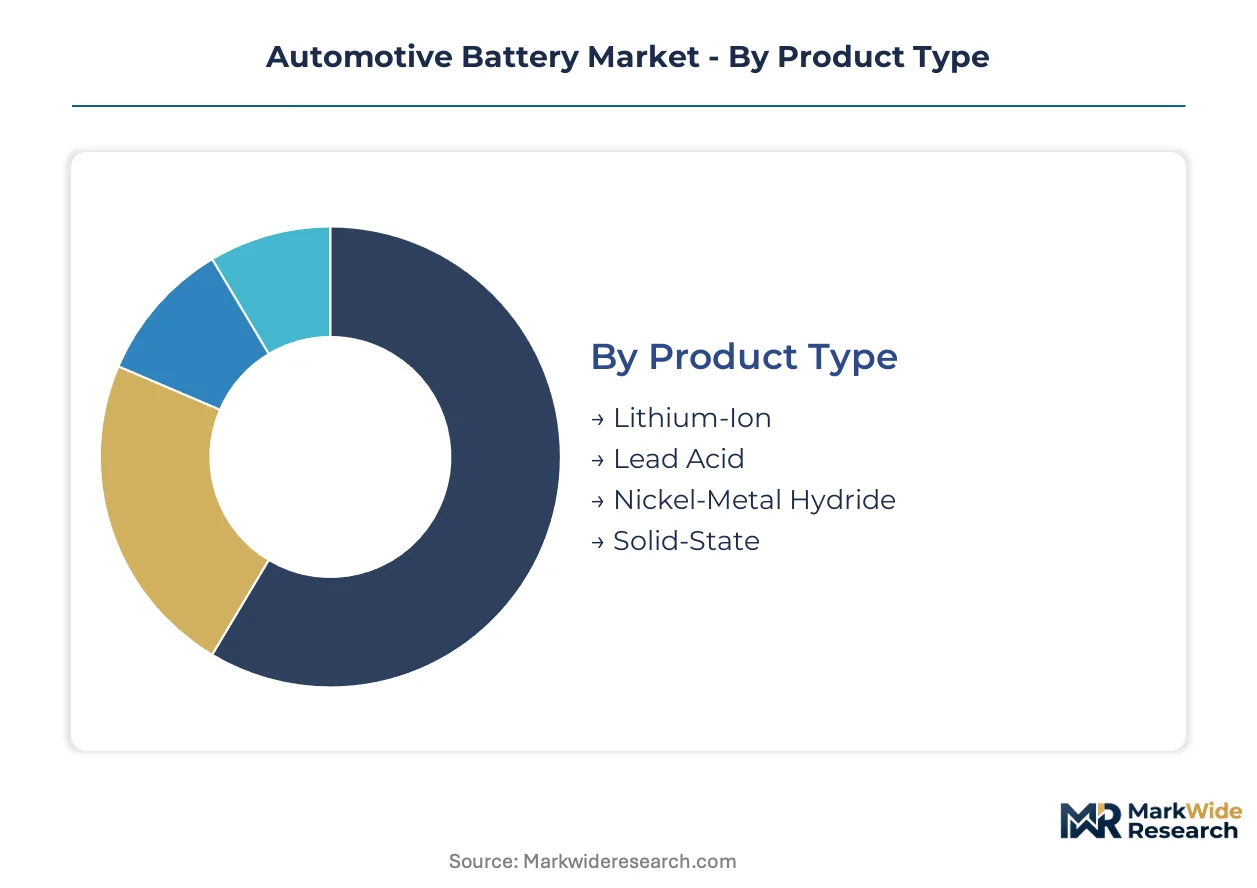
Automotive battery procurement strategies diverge sharply across chemistry, application, and integration depth. OEMs now segment supplier relationships by voltage architecture and thermal management requirements rather than simple capacity tiers. This restructuring concentrates contract negotiation leverage around cell engineering capabilities and certification breadth.
Product Type:
Upgrade cycles for traction systems are compressing as OEMs migrate from conventional chemistries toward higher-density configurations, forcing parallel qualification tracks and dual-source strategies.
- Lithium-Ion:Reversible intercalation chemistry dominates current production with nickel-cobalt-manganese and lithium iron phosphate variants serving distinct thermal and cost profiles. Demand concentrates in Stuttgart and Wolfsburg manufacturing corridors where German OEMs specify 800V high-nickel packs for premium platforms; carbon footprint disclosure under EU Battery Regulation is redirecting cathode sourcing toward qualified European refiners.
- Solid-State:Ceramic or sulfide electrolyte configurations eliminate flammable liquid components while enabling lithium-metal anodes with gravimetric energy advantages. Pilot production lines in Japan and South Korea are scaling thin-film deposition and sintering processes; manufacturing yield limitations and defect rates currently constrain throughput beyond demonstration volumes.
- Lead Acid:Mature flooded and absorbed glass mat designs retain cost advantages for 12V auxiliary and starter functions in conventional powertrains.
- Nickel-Metal Hydride:Toyota hybrid platforms continue procurement of prismatic NiMH packs where proven cycle stability outweighs lithium-ion energy density requirements.
Volume placements concentrate in lithium-ion; the faster expansion belongs to solid-state.
End User:
Customer procurement patterns fragment across fleet scale and contract duration, with municipal operators extracting performance guarantees unavailable to individual retail buyers.
- Passenger Vehicles:Individual ownership and retail leasing channels drive the largest unit volumes with pack sizes ranging from 40kWh urban commuter configurations to 120kWh luxury platforms. European premium OEMs are consolidating cell sourcing around suppliers with multi-standard certification capabilities; cell-to-chassis integration is eliminating module-tier suppliers from direct contracts.
- Electric Buses:Municipal fleet operators in Shenzhen and Santiago are signing multi-year procurement agreements with capacity warranties extending 8-12 years and residual value guarantees. These contracts concentrate margin-rich high-capacity volumes; lifecycle total-cost-of-ownership analytics now dominate supplier selection over upfront pack pricing.
- Commercial Vehicles:Regional delivery and long-haul trucking applications are adopting 800V architectures to enable megawatt charging corridor compatibility.
- E-Bikes:Compact 36V and 48V lithium-ion packs serve micromobility demand with simplified thermal management and standardized form factors.
Passenger vehicles anchor unit volumes; electric buses command superior contract terms and longer duration commitments.
Technology:
System-level feature adoption tracks voltage architecture proliferation and charging infrastructure density, with premium platforms bundling multiple technologies.
- Fast Charging:High-current capability requires silicon-carbide power electronics and enhanced electrolyte formulations to mitigate lithium plating at elevated C-rates. Deployment concentrates in 800V premium passenger platforms where 350kW station availability is expanding across German autobahn corridors; thermal management complexity adds mass and cost to pack designs.
- Regenerative Braking:Bidirectional power electronics capture deceleration energy with efficiency advantages proportional to drive cycle stop frequency. Urban delivery vehicles and electric buses in Shenzhen extract maximum value from brake energy recovery; integrated motor-generator units are displacing friction brake maintenance intervals.
- Start-Stop:Conventional 12V lead-acid and lithium-ion auxiliary systems enable engine shutdown at idle for marginal fuel consumption reduction.
- Wireless Charging:Inductive pad configurations eliminate connector wear for fleet depot applications with standardized parking alignment.
Fast charging infrastructure is penetrating fastest; regenerative braking delivers proven operational savings in high-stop-frequency duty cycles.
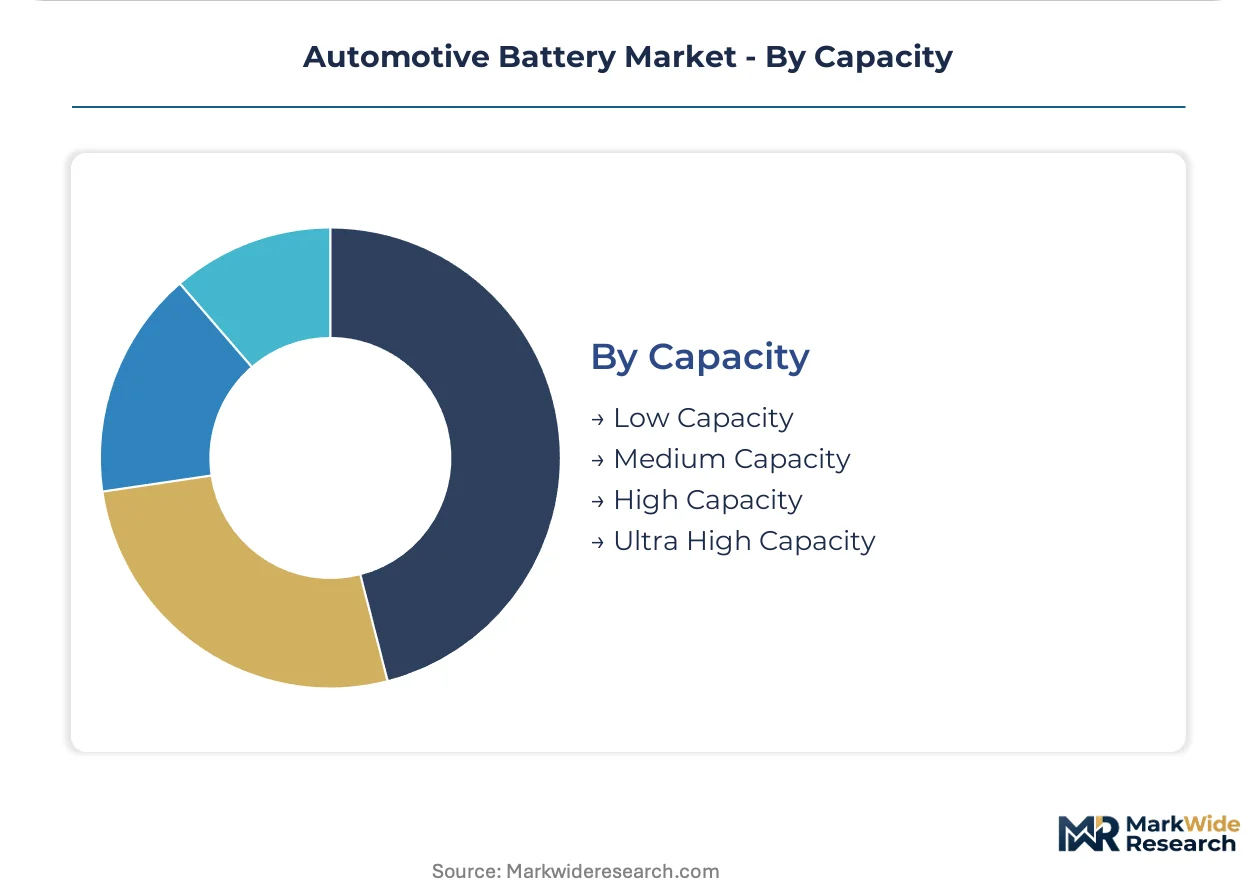
Capacity:
Pack sizing strategies balance range anxiety mitigation against cell cost and mass penalties, with divergence between urban and intercity use cases.
- High Capacity:80-120kWh configurations serve premium passenger platforms and intercity commercial routes where charging station spacing exceeds urban density. German OEMs specify these packs for Stuttgart-produced luxury sedans; EU Battery Regulation recycled content minimums are restructuring cathode precursor sourcing decisions.
- Ultra High Capacity:150kWh-plus systems enable electric bus route completion without midday charging and support long-haul trucking corridor economics. Shenzhen municipal operators specify these configurations for 24-hour transit coverage; cell suppliers must extend cycle life warranties to match 12-year fleet replacement timelines.
- Medium Capacity:40-80kWh packs dominate compact passenger vehicle segments where daily commute distances limit range requirements.
- Low Capacity:Sub-40kWh systems persist in entry-level urban vehicles and E-bike applications with overnight charging availability.
High capacity packs dominate current revenue; ultra high capacity systems are climbing fastest as electric bus fleets expand procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of automotive cells while Germany and the United States concentrate consumption in premium vehicle platforms. This production-consumption divide shapes trade flows and supplier qualification requirements across regulatory jurisdictions.
China
Shenzhen electric bus fleets and passenger vehicle OEMs drive domestic absorption of high-nickel and lithium iron phosphate chemistries. MIIT enforces GB/T thermal runaway propagation standards that extend export qualification timelines for cell manufacturers. The Yangtze River Delta and Pearl River Delta clusters anchor cathode precursor refining and cell assembly capacity serving both domestic and European OEM programs.
Germany
Stuttgart and Wolfsburg manufacturing corridors specify 800V high-capacity packs for premium passenger platforms and commercial vehicle electrification. EU Battery Regulation carbon footprint disclosure mandates redirect cathode sourcing toward qualified European refiners and scrap suppliers. Bavaria and Baden-Württemberg concentrate cell gigafactory investments and automotive R&D partnerships with Asian suppliers.
United States
California zero-emission vehicle mandates and Texas energy storage demand pull high-capacity lithium-ion configurations across passenger and grid-scale applications. NHTSA coordinates crash-safety testing with EPA emissions compliance timelines that effectively mandate electrification in coastal state markets. The Midwest automotive belt and Southwest battery corridor attract cathode active material investments under IRA production incentives.
South Korea
Domestic OEMs and export programs to European premium brands sustain demand for high-nickel cylindrical and prismatic cell formats. METI-aligned industrial policy supports solid-state electrolyte pilot lines and next-generation platform development. The Seoul Capital Area and Busan-Ulsan industrial complex concentrate cell engineering talent and testing infrastructure for multi-standard certification.
India
Two-wheeler electrification and compact passenger vehicle demand drive procurement of mid-range capacity packs with simplified thermal management. PLI scheme incentives for cell and module manufacturing attract cathode precursor investments to serve domestic OEM programs. Gujarat and Tamil Nadu anchor initial gigafactory deployments and component supplier clustering under state-level industrial corridor designations.
Automotive Battery Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across cathode chemistry, cell format, and integration depth. The vendor base organizes into three tiers: Asian cell manufacturers with captive material supply, European system integrators with OEM co-development contracts, and regional assemblers serving aftermarket and specialty vehicle demand. Consolidation pressure operates through direct cell sourcing mandates from OEMs and multi-standard certification requirements that favor scale. Strategic moves concentrate on backward integration into cathode precursors and geographic co-location with vehicle assembly footprints.
Within the scale-driven tier, CATL and LG Energy Solution occupy positions defined by vertical control over refining and cell engineering. BYD anchors the diversified conglomerate archetype through captive vehicle demand and in-house pack integration. Samsung SDI exemplifies the premium-specialist positioning through prismatic format development and solid-state pilot investments. These three companies represent distinct strategic paths: cost leadership through upstream integration, demand security through automotive affiliation, and technology differentiation through format specialization.
| Leading Market Players |
|---|
| SK On |
| Samsung SDI |
| CATL |
| Gotion High-Tech |
| EVE Energy |
| BYD |
| Panasonic |
| Sunwoda |
| LG Energy Solution |
| Others |
Supply Flow & Price Mechanics
Cell-to-chassis integration is compressing pack assembly tiers and forcing direct cell procurement contracts that simultaneously concentrate buyer leverage and eliminate module-tier margin pools. This structural shift repositions pricing power toward OEMs with platform engineering capabilities while exposing suppliers to raw material volatility without intermediate value capture buffers.
Pricing Analysis
Cost-down pressure on high-nickel cylindrical cells accelerates because South American lithium carbonate spot volatility compresses margin visibility on long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates CATL's vertically integrated cost position from Samsung SDI's prismatic premium and regional assemblers serving aftermarket demand. Price differentiation hinges on certification breadth and cathode chemistry grade. Fleet operators in Shenzhen exhibit lowest price sensitivity due to lifecycle total-cost-of-ownship analytics, while Indian two-wheeler OEMs anchor the economy tier with acute cost pressure.
Supply Chain Analysis
Dual-sourcing mandates from German OEMs now require qualified suppliers to maintain parallel GB/T, UN 38.3, and UL 2580 certification capabilities, fragmenting procurement decisions across testing infrastructure investments. Geographic concentration centers on China's Yangtze River Delta for cathode refining, South Korea's Seoul Capital Area for high-nickel cell engineering, and Germany's Bavaria corridor for European OEM co-development. Raw material dependencies draw from Australian spodumene, Chilean brine operations, and Indonesian nickel processing. Single-source cathode precursor vulnerability from China's refined cobalt and nickel sulfate dominance creates tariff exposure risk. Distribution runs through direct OEM platform engineering contracts rather than module-tier intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation establishes a cost-of-compliance moat where carbon footprint disclosure and recycled content minimums favor incumbents with qualified European refining partnerships and scrap supplier networks.
For Market Incumbents: Deepen backward integration into cathode active material production to defend margin position against sodium-ion chemistry entrants targeting mid-range energy density segments. Secure multi-standard certification capabilities across GB/T, UN 38.3, and UL 2580 regimes to maintain access to German OEM direct cell sourcing programs. Capacity addition in Poland or Hungary aligns with EU Battery Regulation carbon mandates while reducing logistics exposure. For New Entrants and Emerging Players: Launch via second-life stationary storage refurbishment partnerships to bypass cell manufacturing capital intensity and thermal runaway propagation testing timelines. Target India's PLI scheme corridors in Gujarat and Tamil Nadu where domestic two-wheeler electrification creates penetrable demand with simplified thermal management requirements. Pursue licensing agreements for electrolyte additive IP rather than work-around R&D investments. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state electrolyte specialists given manufacturing yield breakthroughs as the inflection catalyst. Long-term viability across the analysis window favors prismatic format developers with OEM co-development contracts over cylindrical commodity producers. Monitor ceramic sintering throughput improvements at pilot lines as the signal to watch for commercial scale-up timing. Deviation in solid-state defect rates would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Chassis Integration | Eliminates module-tier suppliers while concentrating thermal management expertise at OEM platform level. |
| Multi-Standard Certification Investment | GB/T, UN 38.3, and UL 2580 qualification enables access to German premium OEM direct sourcing. |
| Cathode Precursor Backward Integration | Captive nickel sulfate and lithium hydroxide processing defends margins against South American spot volatility. |
| Solid-State Pilot Line Scale-Up | Ceramic electrolyte sintering yield improvements determine next-generation platform qualification timelines. |
| Second-Life Storage Partnership | Retired EV pack refurbishment redirects residual capacity toward grid balancing revenue streams. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, cathode material refining executives, and fleet operator purchasing managers underwrites the qualitative findings. Primary interviews with cell manufacturing R&D heads and thermal management system integrators combined with secondary validation from MIIT GB standard filings, EU Battery Regulation implementation guidance, and vehicle production databases establish demand-side triangulation. Bottom-up cell shipment tracking and top-down OEM electrification commitment analysis cross-validate volume estimates.
Rate-of-change decomposition across chemistry transitions, voltage architecture proliferation, and integration depth shifts structures the forecast framework. Segmentation dimensions span propulsion architecture, vehicle class, content per vehicle, and regional production cluster throughout the forecast period. CAGRs derive from installed base turnover modeling and replacement cycle analysis. Industry-specific inputs include electric bus fleet tender award timelines and 800V platform rollout schedules from Stuttgart and Wolfsburg manufacturing corridors.
Lithium carbonate price spikes, solid-state manufacturing yield stagnation, and divergent regional compliance timeline acceleration are the dominant revision risks. Forecasts reflect assumptions around cathode chemistry cost curves and thermal runaway testing standard harmonization. Deviation in EU Battery Regulation recycled content enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market