
 Global Automotive Multifunctional Lamp Market | 2026-2036
Global Automotive Multifunctional Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Multifunctional Lamp Market Intelligence
The basis of competition is shifting, creating a divide between high-volume, standardized halogen lamps and advanced, integrated LED systems. This split separates the commodity aftermarket from the OEM premium segment. Valeo SA leverages its system integration capabilities for advanced adaptive lighting solutions. In contrast, Koito Manufacturing Co., Ltd. dominates with its massive production scale across multiple technology tiers.
Automotive multifunctional lamps are integrated lighting modules that consolidate functions like headlamps, turn signals, and daytime running lights into a single housing. These systems often feature complex optics and are electronically controlled by the vehicle’s central computer. LED lamps command the largest share of the product type segment due to their efficiency and design flexibility. Within the technology segment, adaptive lighting systems represent the fastest-growing category, driven by safety enhancements.
Vehicle lighting performance and safety are governed by stringent regulations, including standards set by the US National Highway Traffic Safety Administration (NHTSA) and UNECE regulations referenced for CE marking in Europe. These rules dictate minimum brightness, beam patterns, and color, directly influencing product design. Stakeholders must now decide whether to invest in developing next-generation micro-LED and laser lighting capabilities or optimize existing LED platforms for cost-competitiveness.
Market Dynamics
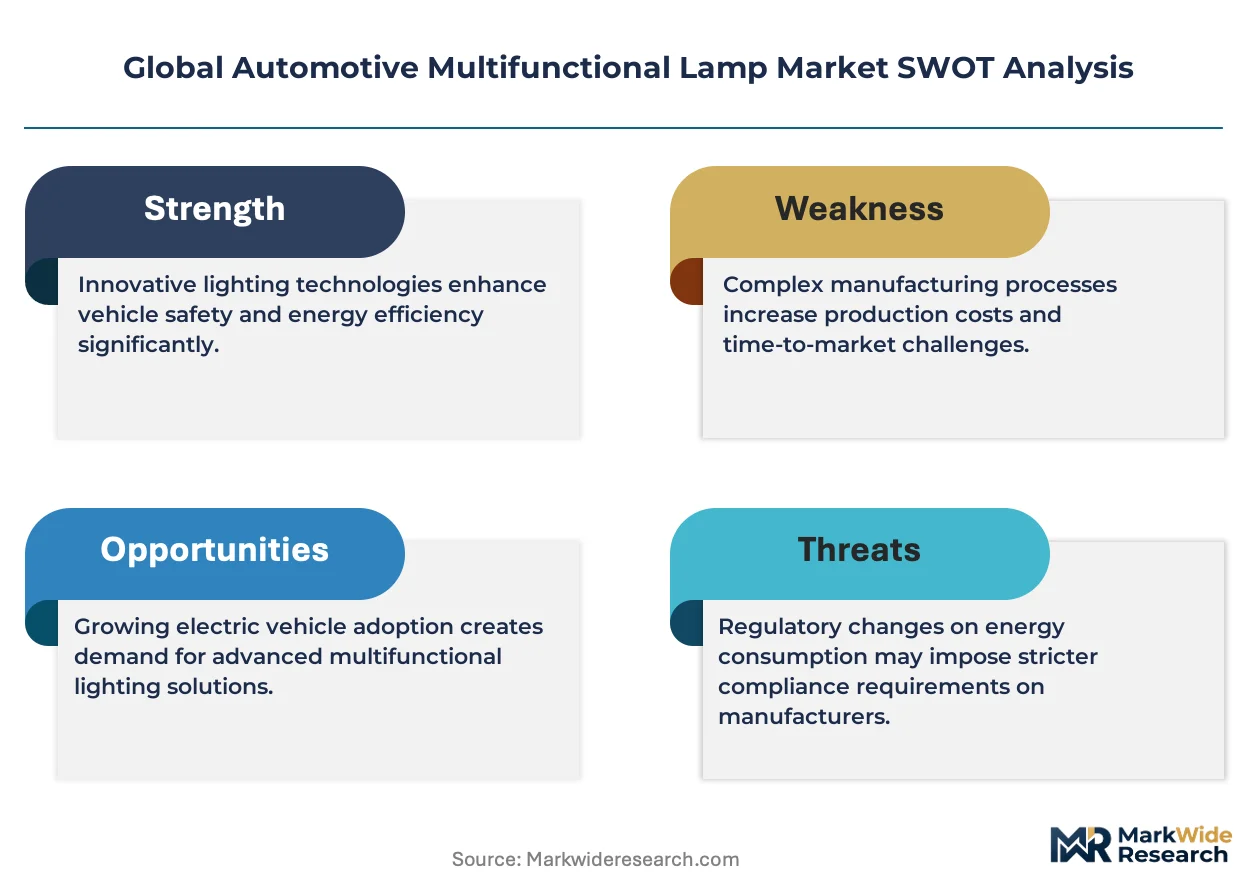
The fundamental market dynamic is the divergence between commoditized halogen replacement parts and sophisticated, electronically controlled LED systems. This split is creating separate value chains for the aftermarket and the premium OEM segment, driven by vehicle electrification and advanced safety requirements.
Growth Catalysts
- EV Platform Adoption:Electric vehicle architectures prioritize energy-efficient components, accelerating the shift to integrated LED multifunctional lamps to conserve battery range and enable unique styling.
- Safety Regulation:Evolving standards from bodies like the US NHTSA and UNECE mandate advanced features like adaptive driving beams, compelling OEMs to adopt more complex lighting systems.
- LED Cost Reduction:Continuous improvements in manufacturing processes and scale have lowered the cost of high-output LED chips, making them viable for mass-market vehicle segments.
Market Restraints
- High System Cost:The significant price premium for adaptive LED and OLED systems over traditional halogen lamps remains a primary barrier to adoption in budget-conscious vehicle models.
- Semiconductor Dependency:Production relies heavily on a concentrated global supply of microcontrollers and LED drivers, creating vulnerability to shortages and price volatility. *Thermal Management: Effectively dissipating heat from high-density LED arrays is a persistent technical challenge that can compromise performance and lifespan if not properly engineered.
Strategic Opportunities
- Micro-LED Integration:The convergence of micro-LED technology with vehicle sensors offers a path to create intelligent lighting surfaces that can project information or warnings onto the road.
- Aftermarket LED Conversion:A substantial opportunity exists in regions like Southeast Asia and Latin America for aftermarket kits to upgrade the vast existing fleet of halogen-equipped vehicles.
- Personalization Features:Developing software-defined lighting enables customizable welcome sequences, animated turn signals, and interior ambient lighting, creating new revenue streams for OEMs.
Industry Challenges
- Software Integration Complexity:Harmonizing the firmware of advanced lamp modules with different vehicle electronic control units (ECUs) creates significant software development and validation hurdles for suppliers.
- Divergent Homologation:Navigating the different and lengthy certification processes required by US FMVSS and European UNECE regulations for new lighting technologies delays product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Multifunctional Lamp Market |
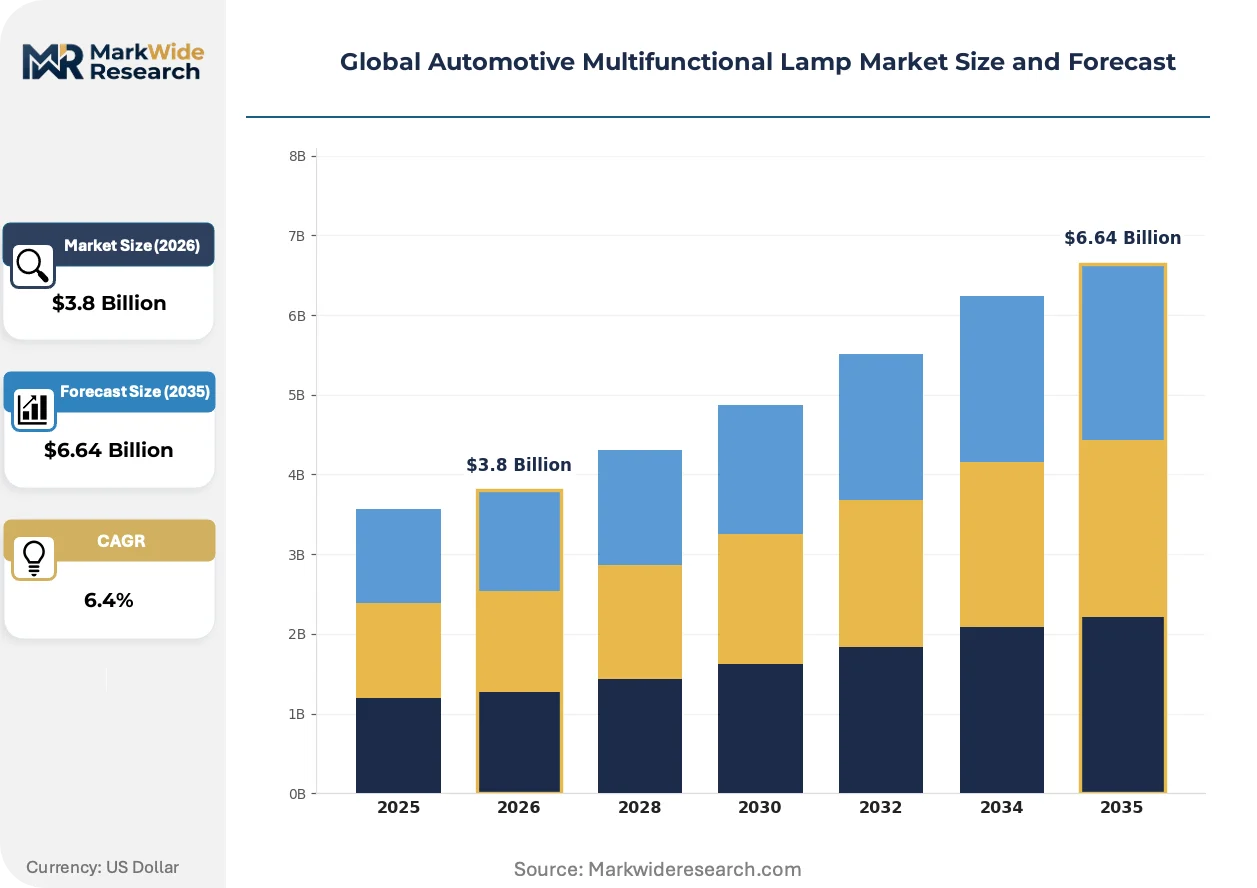
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lamps, Halogen Lamps, Xenon Lamps, OLED Lamps, Incandescent Lamps Technology: Adaptive Lighting, Matrix LED, Laser Lighting, Fiber Optic, Ambient Lighting Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-Road Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Dealerships |
| Companies Covered | Koito Manufacturing Co., Ltd., Valeo SA, HELLA GmbH & Co. KGaA, Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., ams OSRAM, Osram GmbH, Continental AG, Varroc Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Multifunctional Lamp Market Strategic Shifts & Innovations
The evolution of automotive lighting from a passive safety component into an active, intelligent vehicle system is accelerating. This transformation is defined by the deep integration of software, advanced optics, and semiconductor technology into the lamp itself.
Digital micromirror device (DMD) technology, also known as digital light processing, uses millions of microscopic mirrors to project high-resolution, adaptable beam patterns. Premium automotive manufacturers are adopting this for flagship models to enable advanced adaptive driving beam functions. This technology is decentralizing light control from a few mechanical shutters to millions of individual digital pixels, turning the headlamp into a programmable projection device.
Finalization of the US National Highway Traffic Safety Administration's rule permitting adaptive driving beam (ADB) headlights aligns American standards with established UNECE regulations. This policy change removes a major barrier for global automakers. The luxury and premium vehicle segments are most affected, now able to deploy existing global ADB systems in the US market without modification.
OEM purchasing behavior is moving away from sourcing individual components and toward procuring fully integrated and pre-validated lighting system modules from Tier-1 suppliers. This model disrupts smaller, specialized component makers who lack full system capabilities. This shift is most pronounced in the fast-paced electric vehicle sector across China and Europe, where rapid development cycles are paramount.
Global Automotive Multifunctional Lamp Market Segmentation
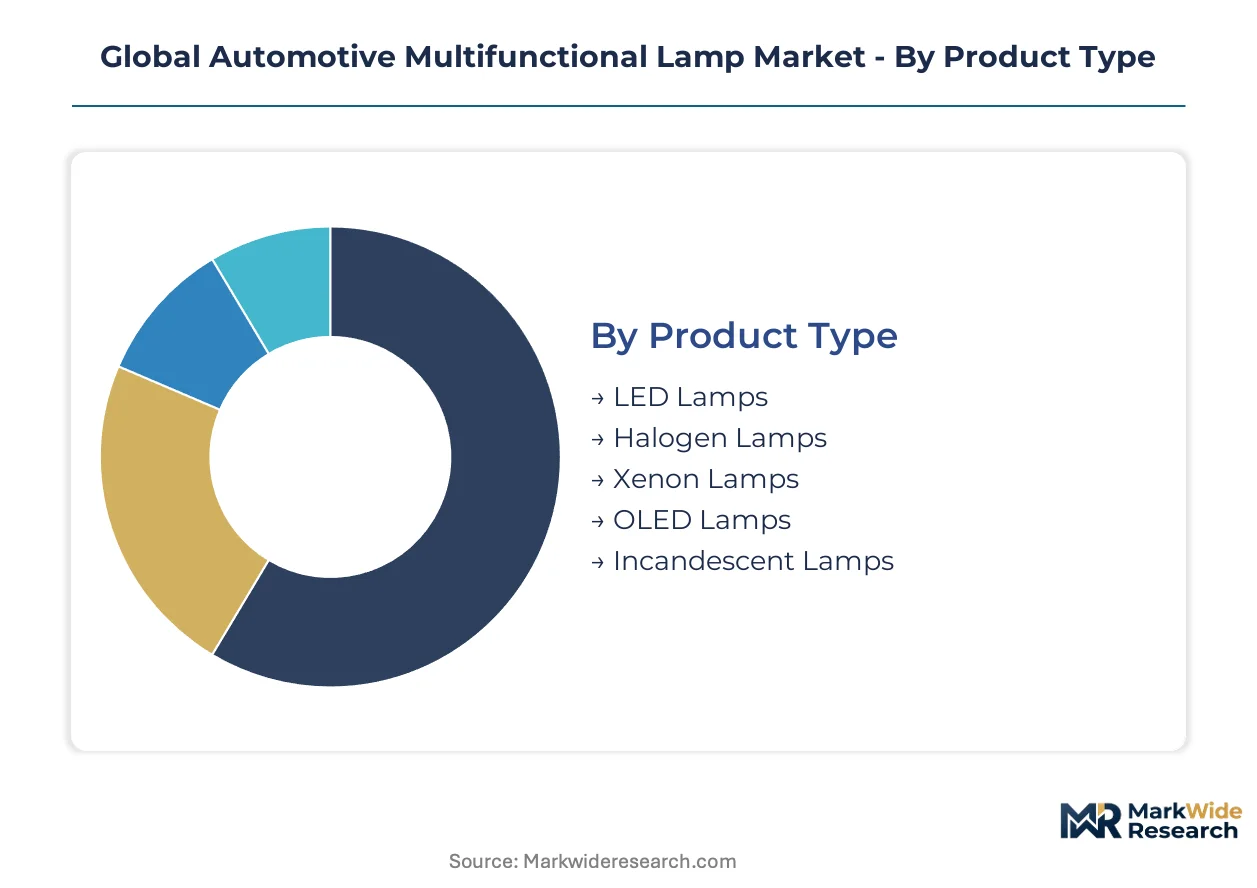
The automotive multifunctional lamp market is intricately segmented, reflecting the diverse technological advancements, application requirements, and end-user demands across the global vehicle landscape. Understanding these distinctions is crucial for stakeholders to identify areas of concentrated demand and emerging opportunities within both new vehicle production and the aftermarket.
Product Type:
The market for multifunctional lamps is defined by distinct upgrade and replacement cycles, influencing product type adoption across vehicle generations and price points.
- LED Lamps:These integrated units utilize light-emitting diodes for superior energy efficiency, extended lifespan, and design flexibility, enabling complex styling and advanced features. Demand concentrates in new passenger vehicles and electric vehicle platforms due to energy conservation and styling advantages.
- OLED Lamps:Organic light-emitting diodes offer ultra-thin form factors, uniform light distribution, and dynamic lighting capabilities for high-end aesthetic and functional integration. Luxury vehicle manufacturers in Europe and Asia are increasingly adopting OLED technology for signature lighting elements.
- Halogen Lamps:Traditional incandescent lamps use a tungsten filament encased in a halogen gas-filled bulb, offering a cost-effective solution with established performance characteristics. Halogen lamps remain prevalent in budget-conscious vehicle models and form the backbone of the global aftermarket for replacement parts.
- Xenon Lamps:High-intensity discharge (HID) lamps produce brighter, whiter light than halogens through an electrical arc between two electrodes in a xenon gas-filled bulb. These lamps are found in mid-range to premium vehicles, offering enhanced nighttime visibility.
- Incandescent Lamps:These basic lighting elements, relying on a heated filament, are largely phased out for primary lighting functions but persist in some low-cost auxiliary applications. Incandescent lamps hold a diminishing share, primarily in older vehicle models.
Volume placements concentrate in Halogen Lamps; the faster expansion belongs to OLED Lamps.
Technology:
Technology segmentation highlights the varying levels of sophistication and integration available in modern automotive lighting systems, driven by safety and aesthetic demands.
- Adaptive Lighting:These intelligent systems automatically adjust beam patterns, intensity, and direction based on driving conditions, vehicle speed, and steering input to optimize illumination and minimize glare for other drivers. Safety regulations in Europe and the US are compelling OEMs to integrate adaptive lighting into premium and mid-range vehicles.
- Laser Lighting:Laser technology offers extremely long-range illumination and highly concentrated light beams, enabling precise light distribution and compact headlamp designs. This cutting-edge technology is currently reserved for ultra-luxury and high-performance vehicles, particularly in Germany.
- Matrix LED:Matrix LED systems utilize individually controllable LEDs to create dynamic, high-resolution light patterns, allowing for precise light distribution and glare-free high beams. This technology is widely adopted in premium passenger vehicles across Europe and China.
- Fiber Optic:Fiber optic cables transmit light from a central source to various points, primarily used for interior ambient lighting and subtle exterior accents. Interior design trends in passenger vehicles increasingly leverage fiber optics for customizable cabin aesthetics.
- Ambient Lighting:This technology provides soft, indirect illumination within the vehicle cabin, enhancing comfort, mood, and perceived luxury. Ambient lighting is a standard feature in many modern passenger vehicles, especially those targeting a premium experience.
Advanced driver assistance systems drive demand for Adaptive Lighting, while Laser Lighting exhibits the steepest expansion trajectory.
Application:
Application segmentation reveals the diverse demands placed on lighting systems across different vehicle platforms and usage scenarios, influencing design and regulatory compliance.
- Passenger Vehicles:This segment includes sedans, SUVs, hatchbacks, and minivans, representing the largest volume application for multifunctional lamps due to widespread consumer ownership. Passenger vehicle lighting emphasizes aesthetics, safety features, and energy efficiency, particularly for electric models.
- Commercial Trucks:Heavy-duty and light-duty commercial vehicles require robust, durable lighting systems capable of withstanding harsh operating conditions and long hours. Regulatory compliance for visibility and signaling is paramount for commercial trucks across North America and Europe.
- Two-Wheelers:Motorcycles, scooters, and mopeds utilize compact and efficient multifunctional lamps, integrating headlamps, turn signals, and tail lights into streamlined designs. Urban mobility trends in Southeast Asia and India drive significant demand for two-wheeler lighting solutions.
- Off-Road Vehicles:These vehicles, including ATVs, UTVs, and specialized construction equipment, demand highly durable and powerful lighting to navigate challenging terrains and low-visibility environments. Ruggedness and extreme weather resistance are key requirements for off-road lighting.
- Specialty Vehicles:This category encompasses emergency vehicles, agricultural machinery, and industrial vehicles, each requiring customized lighting solutions for specific operational tasks and safety protocols. Functionality and regulatory adherence dictate lighting design for specialty vehicles.
Passenger Vehicles represent the largest demand segment, with Off-Road Vehicles gaining share fastest due to specialized requirements.
End User:
End-user segmentation reflects the distinct procurement models and value chain positions within the automotive lighting ecosystem, from initial manufacturing to post-sale service.
- OEMs:Original Equipment Manufacturers integrate multifunctional lamps directly into new vehicles during the assembly process, demanding high-volume supply, stringent quality control, and advanced technological integration. OEMs prioritize seamless integration with vehicle electronics and design aesthetics.
- Aftermarket Providers:These entities supply replacement parts and upgrade kits for vehicles already in operation, catering to repair, maintenance, and personalization needs. Aftermarket demand is driven by vehicle age, accident rates, and consumer desire for performance or aesthetic enhancements.
- Tier-1 Suppliers:These companies design, develop, and manufacture complete lighting modules and systems for OEMs, often acting as system integrators for complex lighting solutions. Tier-1 suppliers play a critical role in bringing advanced lighting technologies to market.
- Vehicle Assemblers:These companies focus on the final assembly of vehicles, sourcing components from various suppliers, including lighting systems. Vehicle assemblers require reliable supply chains and components that meet precise installation specifications.
- Dealerships:Authorized dealerships sell new and used vehicles and provide maintenance and repair services, often sourcing replacement lighting components directly from OEMs or their approved channels. Dealerships serve as a point of contact for consumers requiring lamp replacements or upgrades.
OEMs command the largest share of new vehicle installations, while Aftermarket Providers target the significant installed base for upgrades and repairs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's robust automotive manufacturing base, particularly for electric vehicles, drives significant demand for advanced multifunctional lamps. This concentration of production and innovation positions China as a pivotal market in the global landscape. The shift towards energy-efficient lighting systems for EV platforms is particularly pronounced in this region.
China
Electric vehicle platform adoption significantly increases demand for integrated LED multifunctional lamps in China. Stringent GB standards for vehicle lighting influence product design and performance. The Yangtze River Delta region, including cities like Shanghai and Nanjing, serves as a major hub for advanced automotive lighting production and EV manufacturing.
Germany
Premium automotive manufacturers in Germany prioritize adaptive lighting and cutting-edge laser lighting technologies. UNECE regulations, referenced for CE marking, compel OEMs to integrate sophisticated lighting features. The Stuttgart and Munich automotive clusters are central to the research, development, and production of high-end lighting systems for luxury vehicles.
United States
Evolving safety regulations from the US National Highway Traffic Safety Administration (NHTSA) mandate advanced features like adaptive driving beams. This regulatory environment pushes OEMs towards more complex lighting systems. Detroit remains a key center for traditional automotive manufacturing, while California leads in electric vehicle innovation and associated lighting technologies.
Japan
Japanese automotive manufacturers emphasize large-scale production and robust technology integration for multifunctional lamps. The Ministry of Economy, Trade and Industry (METI) guides industrial standards for automotive components. Nagoya's automotive cluster, home to major OEMs, drives substantial volume demand for both standard and advanced lighting solutions.
India
Growing passenger vehicle sales and a substantial aftermarket for upgrades fuel demand for multifunctional lamps in India. BIS standards ensure product quality and safety for lighting components within the country. Automotive manufacturing hubs in Chennai and Pune are expanding their capabilities for both OEM supply and aftermarket distribution of lighting systems.
Global Automotive Multifunctional Lamp Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the automotive multifunctional lamp market. The industry structure shows a blend of highly integrated global suppliers and specialized technology providers. Strategic archetypes include vertically integrated manufacturing giants, advanced system integrators, and niche component specialists. Competitive moves frequently involve technology licensing and strategic partnerships to expand product portfolios.
Within the vertically integrated manufacturing tier, Japan-based Koito Manufacturing Co., Ltd. occupies a dominant position due to its massive production scale across various technology tiers. French-based Valeo SA exemplifies an advanced system integrator, leveraging its capabilities for sophisticated adaptive lighting solutions. German-based HELLA GmbH & Co. KGaA also sits within the system integrator archetype, offering comprehensive automotive lighting and electronics to global OEMs.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| ams OSRAM |
| Osram GmbH |
| Continental AG |
| Varroc Engineering |
| Others |
Cost & Logistics Intelligence
The bifurcation between commodity halogen lamps and advanced LED systems creates distinct pricing and supply chain structures. This split is driven by differing technology complexities, regulatory compliance requirements, and manufacturing scale across vehicle segments.
Pricing Analysis
Performance-based pricing for advanced adaptive lighting systems reflects their enhanced safety outcomes and design flexibility for vehicle manufacturers. Pricing stratifies across premium, standard, and economy tiers, driven by features like adaptive beam patterns, high-resolution projection, and brand premium. Pricing pressure stems from continuous LED cost reductions in the mid-range segment, impacting traditional lamp profitability. OEMs prioritize integrated system value, while aftermarket buyers remain highly price-sensitive for replacement parts.
Supply Chain Analysis
Domestic content mandates in China and Europe reshape sourcing strategies for automotive lighting components, favoring localized production. Geographic supply concentration centers in East Asia, particularly China, Japan, and South Korea, for critical microcontrollers and LED drivers. Production relies heavily on a concentrated global supply of semiconductor components, introducing significant single-source vulnerability and potential for price volatility. Distribution runs through Tier-1 suppliers who integrate complex modules for OEMs and specialized regional distributors for the aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive multifunctional lamp market is fundamentally a cost-of-compliance story, where stringent UNECE regulations for adaptive driving beams create a significant barrier to entry for non-compliant manufacturers and foster innovation.
For Market Incumbents: Lock in long-term OEM contracts by demonstrating advanced software integration capabilities with diverse vehicle electronic control units and offering comprehensive system validation. Consolidate market share through strategic acquisitions of specialized micro-LED optics firms, mitigating the threat from emerging digital projection technologies. Invest in advanced thermal management solutions to extend product lifespan and reduce warranty claims, enhancing product reliability.
For New Entrants and Emerging Players: Online marketplaces and specialized installer networks offer a viable digital-channel route for new entrants targeting the aftermarket LED conversion segment. Focus on developing cost-effective, high-quality upgrade kits for existing halogen-equipped vehicles in regions like Southeast Asia, addressing unmet demand. A strong go-to-market angle involves emphasizing energy efficiency, enhanced nighttime visibility, and easy installation for consumers.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated Tier-1 suppliers given the accelerating shift to software-defined vehicles and complex lighting modules. Long-term viability hinges on companies that can master both hardware miniaturization and sophisticated software integration, enabling advanced functionalities. The signal to watch is successful commercial deployment of micro-LED projection systems in high-volume vehicle platforms, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-LED Technology Licensing | Secures access to next-generation display and projection capabilities, crucial for intelligent lighting surfaces in premium vehicles. |
| EV Platform Integration Partnership | Establishes preferred supplier status with electric vehicle manufacturers, leveraging energy efficiency and styling flexibility. |
| Regional Aftermarket Distribution Expansion | Captures growth opportunities in emerging markets like India for halogen-to-LED conversion kits, expanding market reach. |
| Software-Defined Lighting IP Development | Builds proprietary firmware for customizable welcome sequences and animated turn signals, creating new revenue streams for OEMs. |
| Advanced Thermal Management R&D | Addresses a persistent technical challenge for high-density LED arrays, improving performance and product longevity for suppliers. |
Research Approach
Independent corroboration across Tier-1 supplier executives, OEM procurement leads, and automotive electronics engineers underwrites the qualitative findings of this study. The analysis integrates insights from primary interviews with secondary validation from vehicle production databases, regulatory filings from NHTSA and UNECE, and technology patent landscapes. This approach ensures robust bottom-up and top-down triangulation of market dynamics.
Historical reference periods anchored the forecast window, establishing a baseline for growth trajectory across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived through a comprehensive assessment of technology adoption curves and evolving regulatory landscapes. Key forecast inputs included EV platform rollout schedules and semiconductor component availability.
Inputs from global automotive production statistics and regulatory updates were available through the study window; gaps in specific regional aftermarket sales data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and economic stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market