
 Automotive UPS (in Vehicle UPS) Market | 2026-2036
Automotive UPS (in Vehicle UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive UPS (in Vehicle UPS) Market Outlook
ISO 26262 functional safety certification is bifurcating the competitive landscape into qualified automotive-grade suppliers and generalist power electronics firms. Siemens AG leverages its embedded software competency to sustain certification breadth across ASIL-rated UPS controllers. Eaton Corporation anchors its position through backward integration into high-reliability magnetics and thermal management subsystems.
An automotive uninterruptible power supply is a dedicated onboard energy storage and conversion subsystem that maintains critical electrical loads during transient or sustained loss of primary vehicle power, typically employing lithium-ion cells with cell-level voltage monitoring and active thermal regulation to deliver ride-through capacity from hundreds of milliseconds to several minutes. The technology dimension shows inverter-based architectures dominating current OEM specifications while battery management system integration represents the fastest-growing engineering investment area as cell chemistries diversify. Controller-based designs occupy the aftermarket channel where retrofit compatibility and plug-and-play installation drive purchasing decisions.
NHTSA crashworthiness and electrical safety standards in the United States, ECE R10 electromagnetic compatibility regulations in Europe, and China's GB/T standards for new energy vehicle electrical subsystems collectively define the compliance perimeter for market access. Product liability exposure under these frameworks pushes Tier-1 suppliers toward modular architectures that simplify traceability and field replacement. Stakeholders must monitor how evolving cybersecurity mandates for vehicle-to-everything communication interfaces reshape UPS subsystem authentication requirements.
Market Dynamics
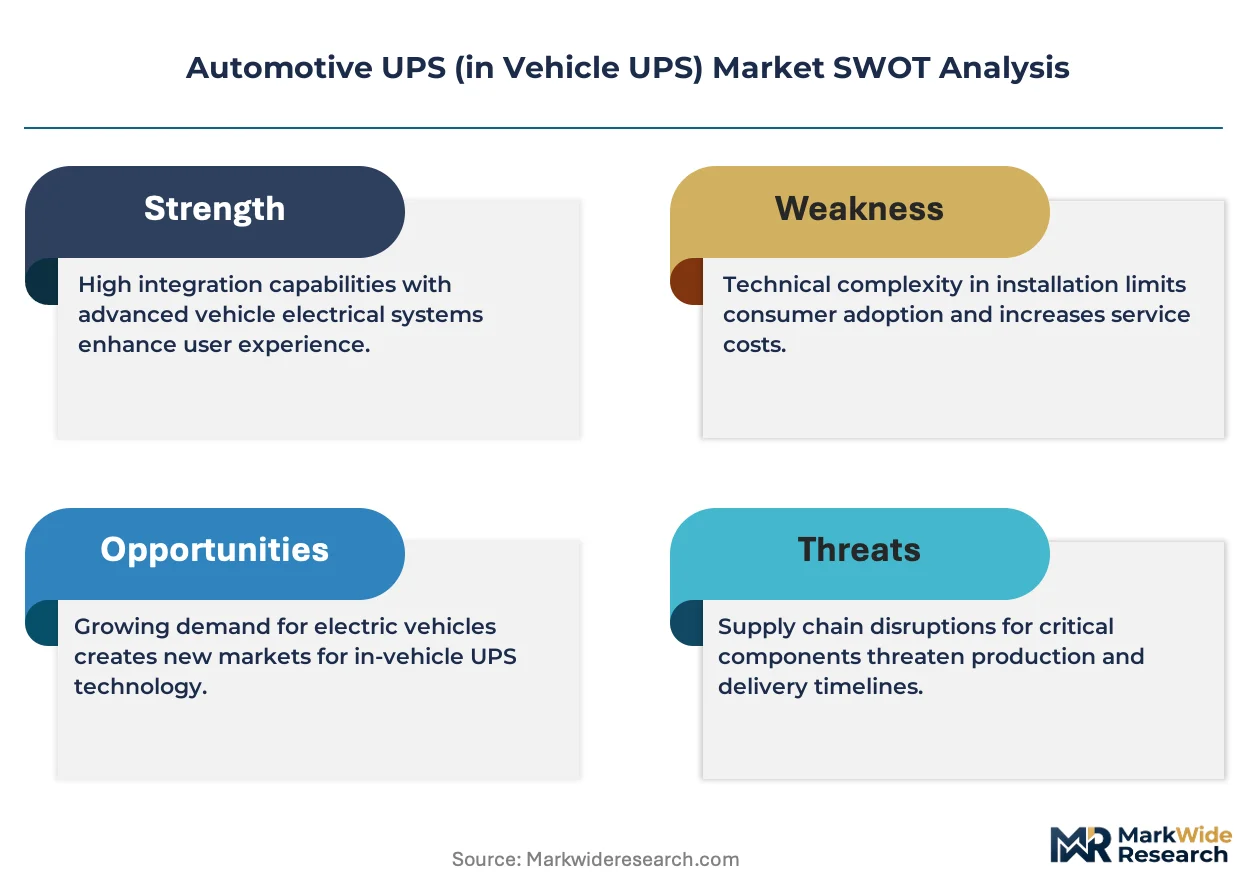
ISO 26262 functional safety certification is compressing supplier margins while concentrating procurement authority among ASIL-qualified Tier-1 integrators who control battery management system architecture decisions.
Growth Catalysts
- NHTSA electrical safety mandates:Crashworthiness standards for emergency communication backup power compel OEM integration of certified lithium-ion UPS subsystems in commercial vehicle platforms.
- ADAS rollout acceleration:Sensor fusion and automated braking systems require millisecond-level power continuity that legacy vehicle electrical architectures cannot guarantee.
- Germany manufacturing concentration:Stuttgart and Munich electronics clusters generate concentrated procurement pull for automotive-grade power conversion modules.
Market Restraints
- Lithium carbonate volatility:Cell chemistry raw material cost swings compress module-level gross margins and deter long-term supply contracts.
- Magnetics supplier concentration:High-reliability ferrite core production concentrates in Japanese and Chinese specialist foundries, creating single-source exposure.
- Thermal runaway containment:Cell-level fault propagation physics impose hard engineering limits on energy density scaling for enclosed vehicle environments.
Strategic Opportunities
- India commercial fleet electrification:BIS certification pathways for auxiliary power subsystems remain underdeveloped relative to latent demand from logistics operators.
- Vehicle-to-grid integration:Bidirectional power flow capability converges with stationary energy storage economics to create dual-use value propositions.
- EU Battery Regulation traceability:Digital product passport mandates create first-mover advantage for suppliers with embedded blockchain-enabled chain-of-custody systems.
Industry Challenges
- Functional safety engineer scarcity:ASIL-D certification competency concentrates among semiconductor and aerospace veterans, forcing cross-industry compensation wars.
- Legacy 12V electrical integration:Dual-voltage architectures complicate harness design and diagnostic protocol standardization across OEM platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive UPS (in Vehicle UPS) Market |
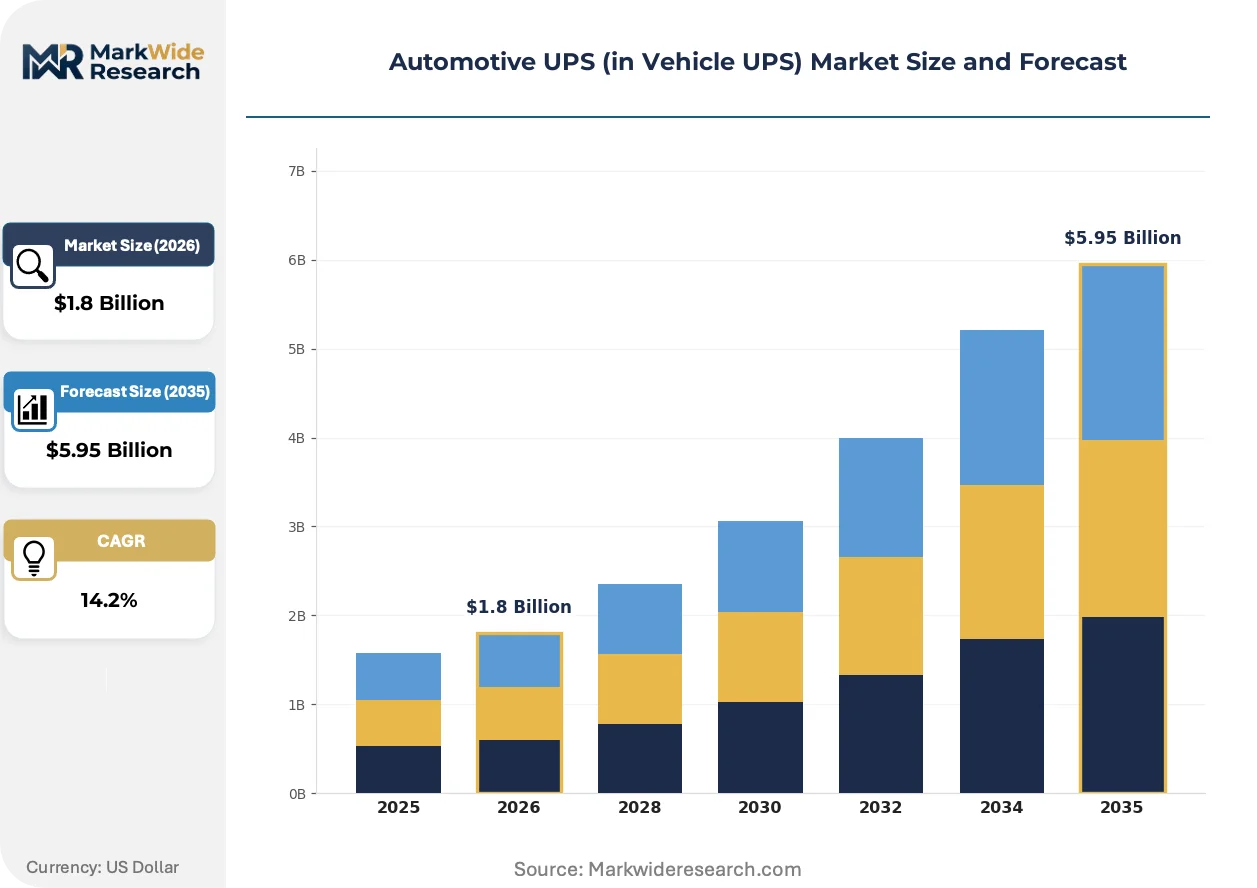
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Supercapacitor Technology: Inverter-Based, Controller-Based, Battery Management System, Modular Design End User: OEMs, Tier-1 Suppliers, Aftermarket Retailers, Fleet Operators Distribution Channel: Online Retail, Direct Sales, Distributors, Automotive Dealers |
| Companies Covered | Siemens AG, Schneider Electric, Eaton Corporation, ABB Ltd, Delta Electronics, General Electric Company, Panasonic Corporation, Fujitsu Limited, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive UPS (in Vehicle UPS) Market Strategic Shifts
Solid-state cell architectures and intelligent battery management algorithms are restructuring competitive advantage around thermal performance and predictive fault detection rather than raw energy density metrics.
Solid-state electrolyte designs are supplanting conventional liquid electrolyte lithium-ion cells in premium vehicle UPS specifications. German and Japanese OEM validation programs have accelerated from laboratory to fleet trial phases within eighteen months. This chemistry transition compresses incumbent cell manufacturer margins while enabling thinner form factors that integrate beneath seat rails and cargo floors.
EU Battery Regulation mandatory carbon footprint disclosure rules reshape supplier qualification criteria for market access. Module assemblers must now document upstream mining, refining, and cell production emissions through audited chain-of-custody systems. Premium commercial vehicle segments in Scandinavia and the Netherlands are responding fastest, inserting climate performance clauses into Tier-1 supply agreements.
Fleet operator direct procurement of UPS subsystems for retrofit installation is fragmenting traditional OEM-Tier-1-Tier-2 hierarchies. Commercial vehicle leasing companies and last-mile delivery operators now specify backup power architectures independently of chassis manufacturers. This channel disintermediation concentrates most visibly in United States Class 3-6 truck segments where telematics uptime guarantees drive specification authority toward fleet engineering departments.
Automotive UPS (in Vehicle UPS) Market Segmentation
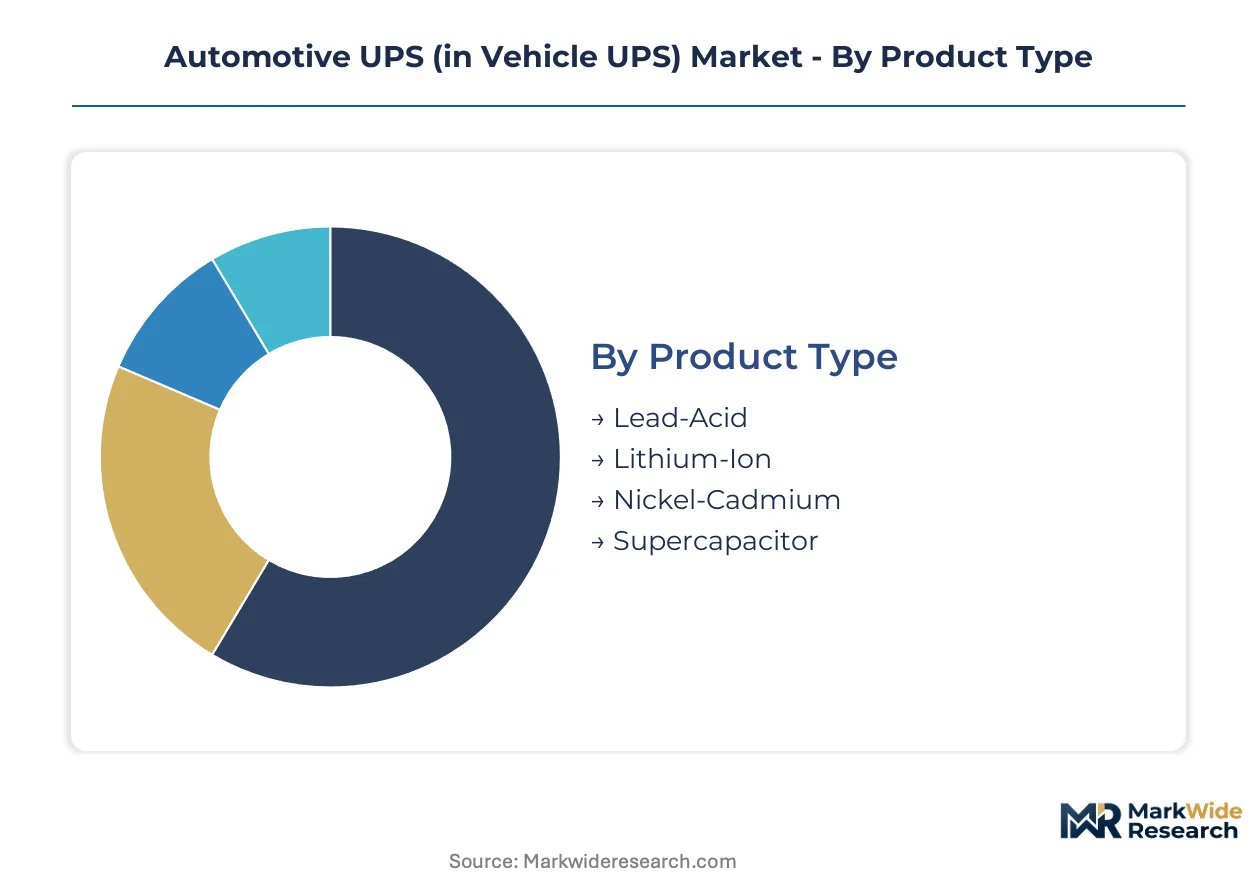
Segmentation in the automotive UPS market reveals how procurement authority and margin capture shift across chemistry choices, architectural approaches, and channel configurations. Each dimension carries distinct implications for certification burden, integration complexity, and pricing power.
Product Type:
Lithium-ion commands the widest margin pools due to energy density premiums and ASIL certification requirements that filter out commodity competitors.
- Lithium-Ion:Employs layered oxide or phosphate cathode chemistries with cell-level voltage monitoring and active thermal regulation. Stuttgart and Munich electronics clusters generate concentrated procurement pull for these modules in premium commercial vehicle platforms requiring extended ride-through capacity.
- Lead-Acid:Absorbed glass mat or gel electrolyte designs dominate cost-sensitive retrofit applications where weight and cycle life tradeoffs are acceptable. Fleet operators across United States Class 3-6 truck segments specify these units for basic telematics backup where millisecond switching is not critical.
- Nickel-Cadmium:Sintered plate construction delivers extreme temperature tolerance for military and arctic commercial applications.
- Supercapacitor:Electrochemical double-layer designs provide sub-second bridging power for automated braking systems.
The dominant share belongs to Lithium-Ion, while Supercapacitor is closing the gap fastest in ADAS-critical applications.
Technology:
Engineering investment concentrates where battery management system integration enables predictive fault detection and chemistry-agnostic platform architectures.
- Inverter-Based:IGBT or SiC power stage topologies convert DC storage to AC or regulated DC outputs with sub-millisecond transfer times. OEM specifications in Germany and Japan increasingly mandate these architectures for sensor fusion and automated driving power continuity.
- Battery Management System:Cell balancing algorithms and thermal runaway prediction software represent the fastest-climbing R&D expenditure category as cell chemistries diversify and ISO 26262 ASIL-D requirements harden.
- Controller-Based:Microprocessor-governed switching logic serves aftermarket retrofit channels where plug-and-play installation and legacy vehicle compatibility drive purchasing decisions.
- Modular Design:Hot-swappable subassembly architectures simplify field replacement and traceability compliance under EU Battery Regulation mandates.
Volume leadership sits with Inverter-Based systems, though Battery Management System is expanding most quickly as software-defined differentiation intensifies.
End User:
Specification authority migration toward fleet engineering departments is fragmenting traditional OEM-Tier-1 hierarchies and compressing channel margins.
- Fleet Operators:Commercial vehicle leasing companies and last-mile delivery operators now specify backup power architectures independently of chassis manufacturers, concentrating procurement pull in United States logistics corridors and European freight hubs.
- OEMs:Integrated vehicle manufacturers embed UPS subsystems at platform design phase, capturing scale economies but accepting full product liability exposure under NHTSA and ECE frameworks.
- Tier-1 Suppliers:System integrators control battery management system architecture decisions and ASIL certification pathways, filtering Tier-2 component access to qualified automotive-grade sources.
- Aftermarket Retailers:Distributors and installation networks serve retrofit demand from operators seeking telematics uptime guarantees without chassis replacement.
Fleet Operators are gaining specification share fastest, while OEMs retain volume leadership through platform integration lock-in.
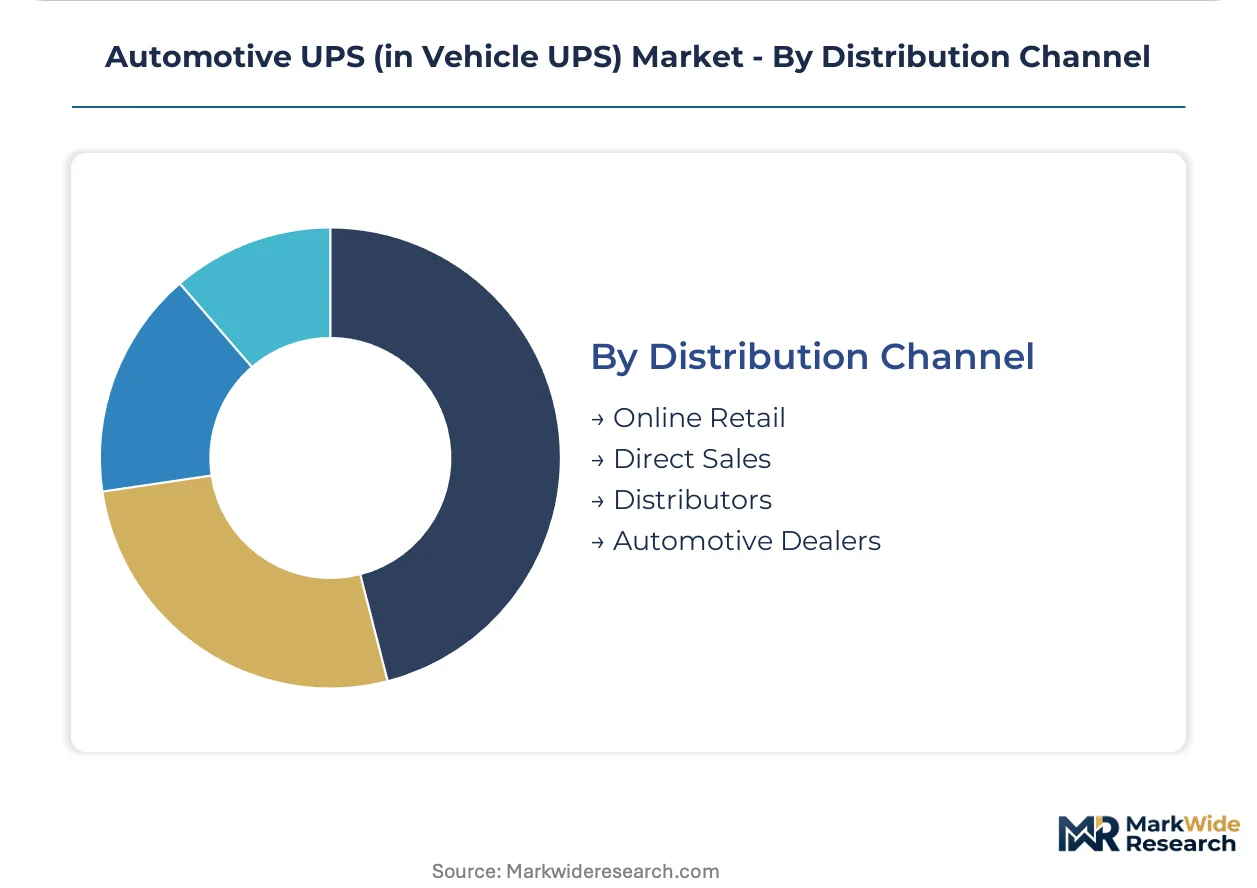
Distribution Channel:
Channel economics diverge sharply between certified direct relationships requiring technical support investment and low-touch digital transactions.
- Direct Sales:Tier-1 suppliers and cell manufacturers maintain captive sales engineering teams for OEM and large fleet accounts, embedding application-specific thermal and magnetic design services.
- Distributors:Specialized industrial electronics wholesalers carry inventory for mid-size fleet operators and regional installation contractors, bridging certification documentation and logistics.
- Automotive Dealers:Franchise and independent service centers access UPS modules through OEM parts networks for warranty-compliant replacement.
- Online Retail:E-commerce platforms serve small fleet operators and individual vehicle owners with standardized controller-based units, trading technical support depth for price transparency.
Direct Sales commands the premium tier, while Online Retail is climbing fastest as procurement digitization penetrates smaller operator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany, Japan, and the United States concentrate procurement authority for automotive-grade UPS modules, driven by telematics uptime requirements and ADAS power continuity mandates.
United States
Class 3-6 commercial truck fleets and last-mile delivery operators specify lithium-ion backup power independently of chassis manufacturers. NHTSA crashworthiness standards compel certified emergency communication power architectures. Detroit and Dallas-Fort Worth logistics corridors generate concentrated demand for retrofit UPS installations.
Germany
Premium commercial vehicle OEMs embed ASIL-D certified UPS subsystems at platform design phase. EU Battery Regulation carbon footprint disclosure rules reshape Tier-1 supplier qualification criteria. Stuttgart and Munich electronics clusters drive procurement pull for high-reliability power conversion modules.
Japan
Automotive electronics manufacturers accelerate solid-state cell validation programs for next-generation UPS specifications. METI industrial policy supports domestic battery supply chain resilience. Nagoya and Tokyo metropolitan manufacturing belts concentrate inverter-based architecture production.
China
New energy vehicle producers integrate GB/T-compliant auxiliary power subsystems for domestic and export platforms. Dual carbon goals accelerate demand for traceable, low-emission cell chemistries. Yangtze River Delta and Pearl River Delta industrial zones dominate module assembly capacity.
India
Commercial fleet electrification creates latent demand for certified backup power architectures in logistics and public transport segments. BIS certification pathways for automotive electrical subsystems remain underdeveloped relative to market need. Maharashtra and Karnataka automotive corridors attract early supplier establishment.
Automotive UPS (in Vehicle UPS) Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with embedded software competency and power electronics heritage. Market structure concentrates procurement authority among ASIL-qualified Tier-1 integrators who control battery management system architecture decisions. Two strategic archetypes dominate: integrated conglomerates leveraging certification breadth, and specialized power conversion firms anchoring position through magnetics and thermal management. Competitive moves center on backward integration into high-reliability component supply and modular platform architectures that simplify field replacement.
Within the integrated conglomerate tier, Siemens AG and Eaton Corporation exemplify archetypes competing on functional safety certification depth and subsystem integration scope. Schneider Electric and ABB Ltd occupy positions bridging industrial power expertise with automotive qualification pathways. Delta Electronics represents the Asia-Pacific manufacturing scale archetype, while Panasonic Corporation anchors the cell chemistry and electronics integration vector. These named entities illustrate how competitive positioning stratifies across certification grade, geographic manufacturing footprint, and vertical integration depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric |
| Eaton Corporation |
| ABB Ltd |
| Delta Electronics |
| General Electric Company |
| Panasonic Corporation |
| Fujitsu Limited |
| Toshiba Corporation |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for ASIL-D certified battery management controllers concentrate procurement leverage among German and Japanese Tier-1 integrators, compressing margins for second-tier module assemblers while amplifying pricing power upstream. This inventory pressure feeds directly into contract structures that index lithium carbonate exposure against Shanghai Futures Exchange benchmarks.
Pricing Analysis
Cost-plus contracts with quarterly lithium carbonate indexation dominate OEM procurement, with price differentiation anchored in ASIL certification grade and thermal management subsystem integration depth. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D qualified architectures from aftermarket controller-based units. Pricing pressure stems from fleet operator direct procurement bypassing traditional OEM-Tier-1 hierarchies. Aftermarket retrofit channels exhibit highest price sensitivity, while embedded platform specifications tolerate premium positioning for functional safety assurance.
Supply Chain Analysis
Ninety-day inventory cycles for high-reliability ferrite cores expose module assemblers to Japanese and Chinese magnetics foundry scheduling. Automotive-grade lithium-ion cell supply concentrates in South Korea, China, and Japan, with upstream cathode active material drawing from Indonesian nickel and Chilean lithium carbonate streams. Single-source vulnerability in sintered ferrite core production creates tariff-agnostic chokepoints. Distribution runs through captive Tier-1 sales engineering teams for OEM accounts, with specialized industrial distributors bridging mid-size fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on battery management system software layer interoperability, where OEMs are decoupling hardware specifications from control algorithm sourcing. This shift restructures competitive moats around embedded software competency rather than magnetics manufacturing scale.
For Market Incumbents: Fortify ASIL-D certification breadth across emerging solid-state cell chemistries to preempt chemistry-agnostic platform architectures from displacing incumbent module designs. Deepen backward integration into high-reliability thermal management subsystems to defend margin position against controller-based aftermarket competitors. Prioritize embedded software lock-in through over-the-air update infrastructure that binds fleet operators to proprietary battery management algorithms.
For New Entrants and Emerging Players: Fleet telematics uptime guarantee services represent the most penetrable service-layer gap, as incumbents under-serve logistics operators seeking outcome-based power continuity contracts rather than hardware procurement. Target United States Class 3-6 truck retrofit channels where specification authority has already migrated from OEMs to fleet engineering departments. Lead with plug-and-play controller-based architectures that bypass ASIL certification timelines while delivering millisecond switching performance for non-safety-critical loads.
For Investors and Strategic Acquirers: Long-term, this sits as a functional safety consolidation play because ISO 26262 competency scarcity concentrates valuation premiums among qualified Tier-1 integrators as cell chemistry diversity multiplies certification burden. Acquisition target archetype: mid-cap power electronics firms with captive magnetics production and nascent automotive qualification pathways. Watch solid-state cell validation program acceleration by German and Japanese OEMs as inflection indicator for chemistry transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Expansion | Functional safety breadth secures OEM platform integration lock-in against controller-based competitors. |
| Solid-State Cell Partnership | Early chemistry transition access enables thinner form factors for under-seat rail integration. |
| Fleet Telematics Service Layer | Outcome-based uptime guarantees capture specification authority migrating from OEM procurement. |
| Magnetics Backward Integration | Captive ferrite core production insulates margin from Japanese and Chinese foundry scheduling volatility. |
| EU Battery Regulation Traceability | Blockchain-enabled chain-of-custody systems create first-mover qualification advantage under digital product passport mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operations managers; and secondary validation against NHTSA regulatory filings, ECE R10 type-approval databases, vehicle production registries, and customs trade records. Bottom-up module shipment estimates triangulated against top-down OEM platform integration forecasts.
Across the projection horizon, analytical frameworks modeled segmentation across cell chemistry, power conversion architecture, end-user specification authority, and regional regulatory cluster. CAGRs derived from installed base growth, content-per-vehicle trajectories, and replacement cycle dynamics. Forecast inputs incorporated ADAS penetration curves, commercial fleet electrification timelines, and solid-state cell validation program milestones.
Underlying assumptions cover lithium carbonate price band stability, ASIL certification timeline continuity, and OEM platform integration lock-in persistence, with deviation risk concentrated in raw material cost volatility and cybersecurity mandate acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market