
 Electric Vehicle Aftermarket Market | 2026-2036
Electric Vehicle Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Aftermarket Market Intelligence
Independent garage networks is tilting toward certified high-voltage service capability as EV powertrain complexity outpaces traditional mechanical skill sets. Bosch Automotive Service Solution Inc. leverages its diagnostic equipment portfolio to anchor workshop retrofit programs across European markets. Continental AG competes through integrated battery management software that extends into aftermarket analytics platforms.
The electric vehicle aftermarket encompasses replacement parts, maintenance services, and upgrade components for battery-electric and plug-in hybrid vehicles, requiring technicians to handle systems operating at 400–800 volts DC with specialized isolation protocols and thermal management specifications. Its primary commercial purpose is sustaining vehicle performance, safety, and residual value outside original manufacturer service channels. Battery packs and charging stations capture concentrated margin pools as electrification deepens, while maintenance services represent the highest-frequency revenue stream for independent operators. Tires constitute a mature replacement category with accelerating SKU proliferation around EV-specific load ratings and low-rolling-resistance compounds.
The EPA enforces emissions compliance frameworks that indirectly validate aftermarket component performance claims, while NHTSA regulates vehicle safety standards affecting crash-relevant replacement parts eligibility. Germany's KBA oversees type-approval processes that determine whether independent repair components qualify for road-legal installation. Stakeholders must monitor how evolving battery passport requirements under EU regulation reshape parts traceability obligations and sourcing economics.
Market Dynamics
The expiration of manufacturer battery warranties across major EV fleets is forcing independent service networks to absorb high-voltage diagnostic and repair capabilities previously monopolized by OEM channels.
Growth Catalysts
- EU Battery Regulation traceability mandates:Parts sourcing documentation requirements create certified supplier tiers that reward early-compliant distributors with preferential channel access across Germany, France, and the Netherlands.
- Fleet electrification in commercial logistics:Last-mile delivery operators in California and Texas are consolidating maintenance spend under multi-year service contracts that bypass dealership networks entirely.
- Lithium-ion cell remanufacturing:Second-life battery processing facilities in South Korea and Japan are establishing reverse logistics partnerships with independent garages for core collection and refurbishment feedstock.
Market Restraints
- High-voltage technician certification scarcity:Training program throughput in Germany's KBA-accredited institutes limits workshop expansion regardless of equipment investment capacity.
- Semiconductor-dependent power electronics:IGBT and SiC module supply concentrates among Taiwanese and German foundries, exposing aftermarket inventory to automotive OEM allocation priority.
- Battery management system firmware lockout:Proprietary encryption protocols on Tesla and Volkswagen Group packs prevent independent state-of-health assessment without manufacturer authorization tools.
Strategic Opportunities
- India's FAME-II subsidy extension:Two-wheeler and three-wheeler electrification creates demand for low-cost battery replacement networks in Maharashtra and Karnataka states.
- Vehicle-to-grid integration services:Bidirectional charging hardware retrofits allow independent operators to capture energy arbitrage revenue streams alongside traditional maintenance.
- Direct-to-consumer diagnostic subscriptions:Mobile applications linking OBD-II data to predictive maintenance recommendations disintermediate traditional service booking channels.
Industry Challenges
- 800V platform safety protocols:Arc flash containment and personal protective equipment standards for Porsche Taycan and Hyundai E-GMP architectures exceed existing workshop infrastructure.
- Cell-level warranty liability:Independent battery rebuilders face unclear fault attribution when thermal runaway incidents occur post-repair.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Aftermarket Market |
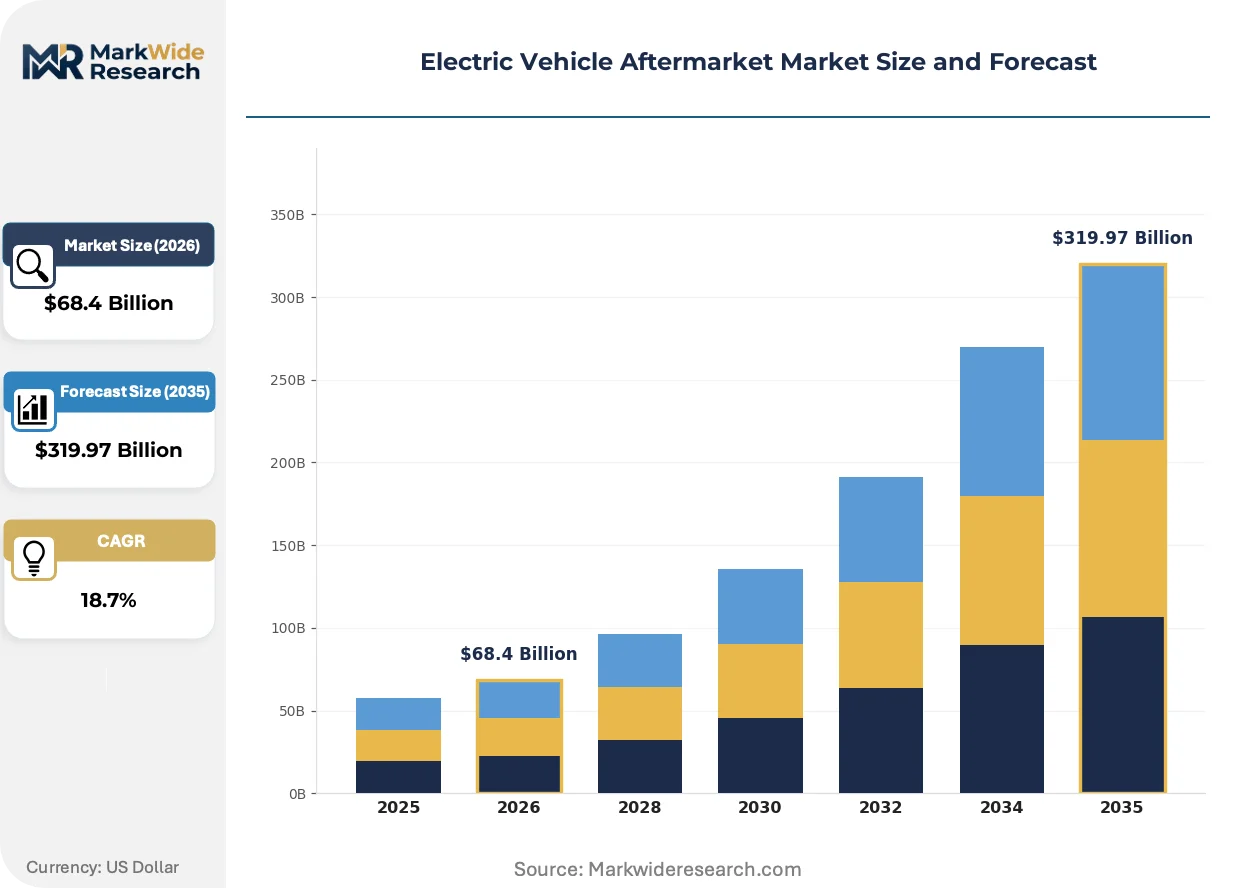
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $319.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accessories, Battery Packs, Charging Stations, Tires Service Type: Maintenance, Repair, Upgrades, Customization Distribution Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Distributors Customer Type: Fleet Operators, Individual Consumers, Dealerships, Aftermarket Suppliers |
| Companies Covered | Bosch Automotive Service Solution Inc., Continental AG, Denso Corporation, ABB Ltd., Schneider Electric SE, 3M, ChargePoint Inc., ZF Friedrichshafen AG, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Aftermarket Market Strategic Shifts & Innovations
Diagnostic automation and predictive analytics are compressing the traditional reactive maintenance model into continuous vehicle health monitoring, with software-defined service intervals displacing fixed-schedule interventions.
Solid-state battery interface standardization is collapsing the proprietary diagnostic tool landscape as cell chemistry uniformity enables universal state-of-health algorithms. Tier-1 suppliers are pre-certifying equipment for 800V architectures before 2026 model year volume ramps. Independent workshop networks in Germany and California are consolidating purchasing through cooperative procurement platforms to access these tools.
EPA emissions compliance verification for aftermarket components now extends to battery pack replacements, requiring independent manufacturers to submit test data under expanded 40 CFR Part 85 protocols. California Air Resources Board staff are prioritizing enforcement against uncertified range-extender installations. Importers in Los Angeles and Houston ports face expanded documentation requirements for remanufactured traction batteries.
Fleet maintenance contracts are unbundling warranty work from preventive service, allowing independent operators to capture scheduled intervals while OEMs retain catastrophic failure liability. Municipal bus operators in Chicago and Dallas are piloting this split-responsibility model. The shift concentrates high-frequency revenue with independents while transferring capital risk to manufacturers.
Electric Vehicle Aftermarket Market Segmentation
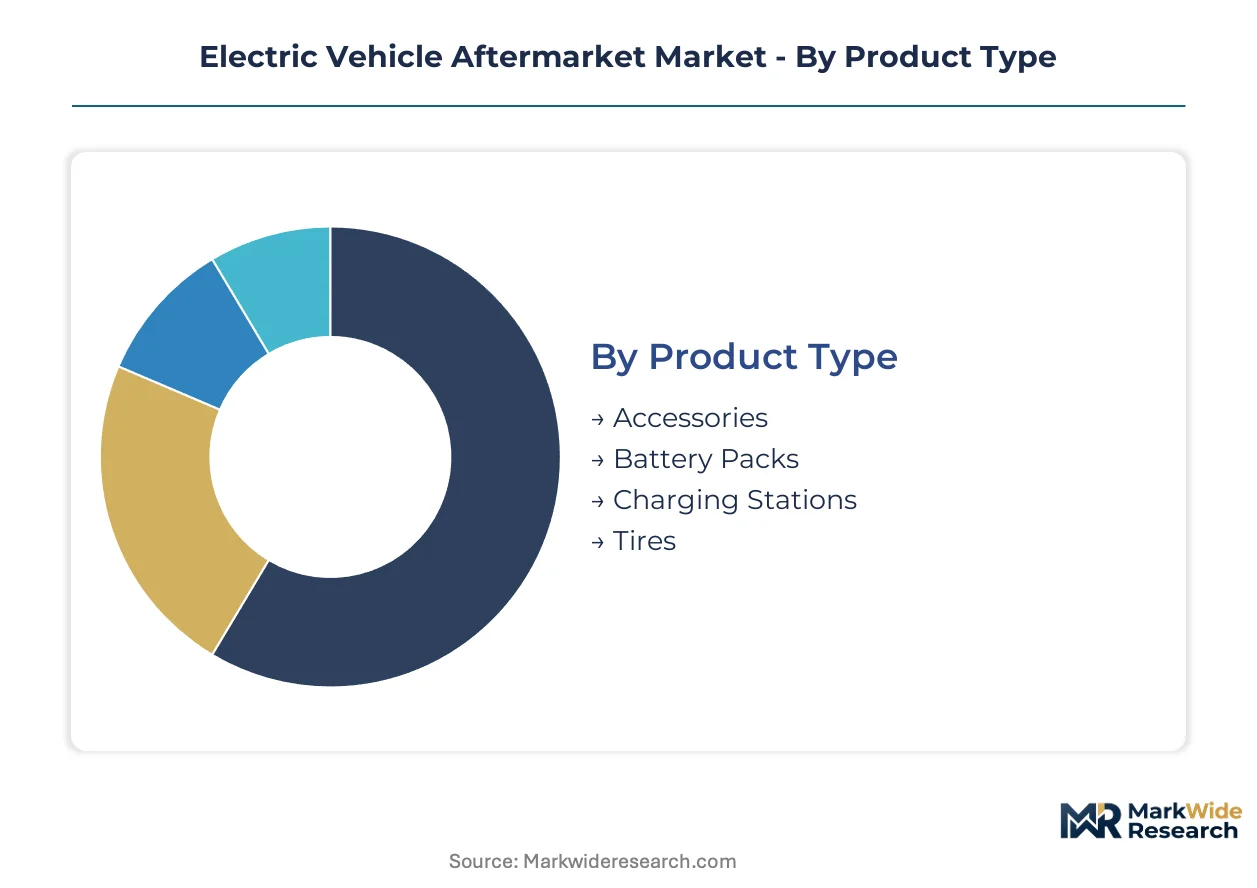
Segmentation in the electric vehicle aftermarket reveals divergent replacement cycles that reshape inventory planning and technician specialization. Battery packs and tires operate on fundamentally different turnover timelines, forcing distributors to balance long-horizon capital commitments against high-frequency consumable restocking.
Product Type:
Replacement velocity varies by an order of magnitude across this category, with consumables turning in months while powertrain components span years.
- Battery Packs:High-voltage lithium-ion assemblies operating at 400–800V DC with integrated thermal management and battery management systems. Demand clusters in Germany where KBA type-approval requirements restrict independent rebuild eligibility, compressing available supply channels.
- Tires:EV-specific compounds engineered for higher load ratings and reduced rolling resistance to preserve range. Fleet operators in California and Texas drive volume through accelerated wear patterns from regenerative braking torque delivery.
- Charging Stations:Level 2 AC and DC fast-charging hardware for residential and commercial installation.
- Accessories:Aerodynamic add-ons, interior upgrades, and connectivity modules.
Battery packs dominate installed base value. Tires are where expansion concentrates.
Service Type:
Margin structure inverts between scheduled interventions and unscheduled failures, with predictive capabilities altering traditional revenue timing.
- Maintenance:Scheduled inspections, software updates, cooling system servicing, and preventive component replacement. Fleet contracts in Chicago and Dallas unbundle this work from warranty coverage, shifting recurring revenue to independent networks.
- Repair:Diagnostic troubleshooting and corrective action for powertrain, thermal, or charging system faults. High-voltage certification scarcity in Germany limits workshop capacity regardless of equipment investment.
- Upgrades:Range-extending battery retrofits, bidirectional charging enablement, and performance software calibration.
- Customization:Aesthetic modifications and feature activation through over-the-air or hardware interventions.
Maintenance commands the highest visit frequency. Upgrades are climbing the fastest as vehicle-to-grid integration matures.
Distribution Channel:
Channel economics diverge sharply between inventory-heavy physical presence and asset-light digital intermediation.
- Distributors:Regional wholesalers maintaining local stock of high-voltage components with certified handling protocols. EU Battery Regulation traceability mandates favor established distributors with documentation infrastructure across Germany, France, and the Netherlands.
- Online Retail:Digital platforms for accessories, tires, and consumer-grade charging equipment. Direct-to-consumer diagnostic subscriptions in California bypass traditional service booking through mobile OBD-II integration.
- Brick-and-Mortar Stores:Physical retail locations with immediate product availability.
- Direct Sales:Manufacturer-controlled channels for proprietary components.
Distributors anchor commercial volume. Online retail is gaining share fastest among individual consumers.
Customer Type:
Procurement scale and technical sophistication create distinct service requirements that fragment vendor strategies.
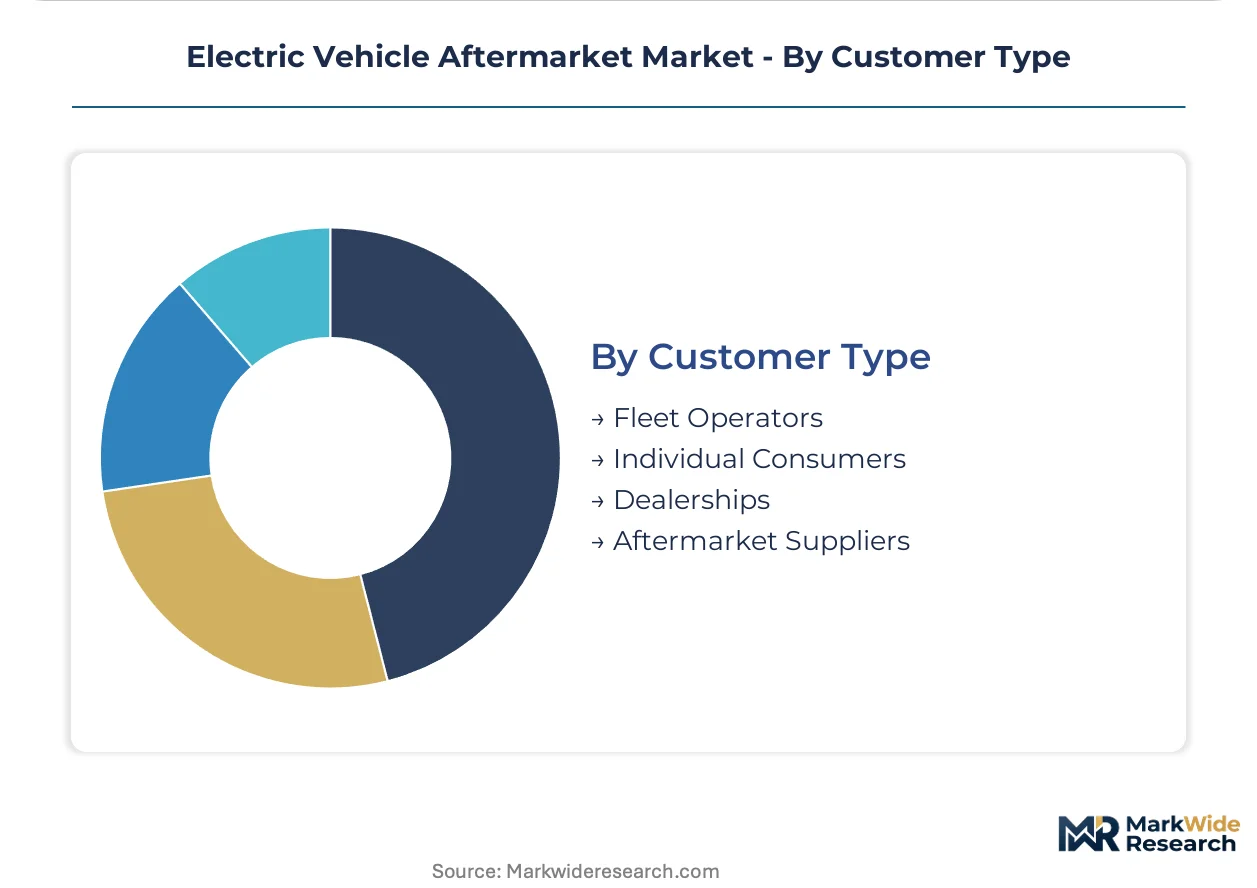
- Fleet Operators:Multi-vehicle commercial and municipal entities consolidating maintenance spend under long-term contracts. Last-mile delivery operators in California and Texas bypass dealership networks entirely through direct independent garage relationships.
- Individual Consumers:Private vehicle owners seeking maintenance, repair, and upgrade services outside OEM channels. Predictive maintenance applications disintermediate traditional booking patterns through continuous health monitoring.
- Dealerships:Authorized service centers retaining warranty work and proprietary diagnostic access.
- Aftermarket Suppliers:Component manufacturers and remanufacturers serving downstream channels.
Fleet operators concentrate contract value. Individual consumers are expanding most quickly as EV ownership broadens beyond early adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for certified high-voltage components while India competes on volume through low-cost battery replacement networks. This asymmetry shapes procurement strategies across independent garage networks and fleet operators.
United States
California and Texas dominate fleet electrification with last-mile delivery operators consolidating maintenance spend under multi-year independent contracts. NHTSA safety standards govern crash-relevant replacement parts eligibility, while EPA emissions compliance extends to battery pack replacements under expanded protocols. Los Angeles and Houston ports face expanded documentation requirements for remanufactured traction batteries.
Germany
KBA type-approval requirements restrict independent battery rebuild eligibility, compressing available supply channels for high-voltage assemblies. The EU Battery Regulation mandates traceability documentation that rewards early-compliant distributors with preferential channel access. Independent garage networks in Bavaria and Baden-Württemberg invest heavily in high-voltage technician certification despite training throughput limits.
China
Domestic EV ownership expansion drives aftermarket demand for replacement battery packs and charging infrastructure. MIIT oversees national standards for battery management systems and power electronics. The Yangtze River Delta and Pearl River Delta industrial clusters concentrate remanufacturing capacity and second-life battery processing facilities.
India
FAME-II subsidy extension accelerates two-wheeler and three-wheeler electrification, creating demand for low-cost battery replacement networks. The country's national automotive regulator enforces safety protocols for high-voltage systems. Maharashtra and Karnataka states anchor emerging independent service networks targeting commercial fleet operators.
South Korea
Advanced battery technology leadership supports second-life cell processing and reverse logistics partnerships. The national industrial regulator under METI direction coordinates standards alignment with export markets. Seoul Capital Area facilities establish core collection networks feeding refurbishment feedstock to regional remanufacturing plants.
Electric Vehicle Aftermarket Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical focus. The market structures around three distinct layers: diagnostic equipment providers anchoring workshop retrofit programs, battery management software developers extending into analytics platforms, and charging infrastructure specialists capturing installation and maintenance revenue. Two dominant competitive moves define current positioning: strategic partnerships between equipment manufacturers and independent garage networks, and portfolio diversification into predictive maintenance software subscriptions.
Within the integrated systems tier, Bosch Automotive Service Solution Inc. and Continental AG exemplify platform breadth, while Denso Corporation occupies a position emphasizing powertrain component specialization. These three entities represent divergent strategic postures: the first two anchor multi-product portfolios spanning diagnostic hardware and software layers, while the third concentrates on thermal and propulsion subsystem expertise. Their collective positioning illustrates how vendor selection criteria increasingly weight certification depth and regulatory compliance infrastructure alongside technical performance.
| Leading Market Players |
|---|
| Bosch Automotive Service Solution Inc. |
| Continental AG |
| Denso Corporation |
| ABB Ltd. |
| Schneider Electric SE |
| 3M |
| ChargePoint Inc. |
| ZF Friedrichshafen AG |
| Delphi Technologies |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's concentration of lithium-ion cell manufacturing capacity feeds directly into aftermarket battery pack pricing power, with independent rebuilders facing cost compression when OEM allocation priority restricts semiconductor module availability to certified distributors.
Pricing Analysis
Configured-to-order battery pack assembly commands substantial premiums over standard remanufactured units, with pricing stratifying across OEM-authorized, KBA-certified independent, and uncertified economy tiers. Certification grade and volume scale drive differentiation, with fleet procurement contracts securing 15-20 point discounts through multi-year commitments. Cost compression in the economy tier is intensifying because Chinese cell imports face expanded documentation requirements at Los Angeles and Houston ports. Fleet operators exhibit the highest price sensitivity, while individual consumers purchasing single replacements accept premium positioning for warranty coverage.
Supply Chain Analysis
Tariff exposure between China and the United States dominates aftermarket component sourcing risk, with IGBT and SiC power electronics drawing from Taiwanese foundries, South Korean battery cell producers, and German automotive tier suppliers. Lithium carbonate, nickel sulfate, and copper foil constitute critical raw material dependencies. Single-source vulnerability concentrates in BMS firmware encryption tools controlled by Tesla and Volkswagen Group. Distribution runs through regional wholesalers with certified high-voltage handling protocols, though cooperative procurement platforms in Germany and California are consolidating purchasing power among independent garage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American last-mile logistics has shifted procurement leverage toward buyers capable of extracting multi-year service commitments, fragmenting traditional OEM channel control.
For Market Incumbents: Insulate certified service relationships by embedding diagnostic equipment through long-term workshop retrofit programs, countering emerging threats from direct-to-consumer predictive maintenance applications. Prioritize backward integration into second-life cell processing to secure refurbishment feedstock and defend margin position against independent rebuilders. For New Entrants and Emerging Players: Establish a beachhead in India's two-wheeler and three-wheeler battery replacement networks, where FAME-II subsidy extension has created white-space demand without entrenched incumbent presence. Target cooperative procurement platforms as the most penetrable channel structure, leveraging volume aggregation to access 800V diagnostic tool certifications ahead of platform standardization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic software subscription providers linking OBD-II data to predictive maintenance recommendations. Long-term viability across the analysis window favors acquisition targets with established EU Battery Regulation traceability infrastructure. Watch vehicle-to-grid integration deployment rates as the signal indicating when bidirectional charging hardware retrofits transition from pilot to scaled revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Certification Investment | KBA-accredited training throughput limits constrain workshop expansion regardless of equipment capital. |
| Second-Life Battery Reverse Logistics Partnership | Seoul Capital Area facilities anchor core collection networks feeding regional remanufacturing plants. |
| Predictive Maintenance Software Subscription Launch | Mobile OBD-II integration disintermediates traditional service booking channels in California markets. |
| Cooperative Procurement Platform Participation | German and California garage networks consolidate purchasing power for 800V diagnostic tool access. |
| EU Battery Regulation Traceability Infrastructure Buildout | Early-compliant distributors secure preferential channel access across Germany, France, and Netherlands. |
Research Approach
Desk research of vehicle production databases, IHS Markit registration data, SEC filings from automotive tier suppliers, and EU regulatory documentation preceded structured interviews with aftermarket distributor operations heads, independent garage network managers, fleet procurement directors, and high-voltage technician training institute administrators. Primary fieldwork combined with secondary validation through customs records and port documentation requirements. Bottom-up segment sizing triangulated against top-down market value estimates.
Forecasts assume stable battery chemistry transition timelines and consistent regulatory enforcement intensity across the projection horizon, with segmentation modeled across propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from installed base evolution and replacement cycle compression. Forecast inputs include fleet electrification contract volumes and independent garage certification expansion rates.
Sensitivities concentrate around BMS firmware encryption policy changes, lithium price volatility, and 800V platform safety protocol standardization timelines. Forecasts reflect documented assumptions regarding technician training throughput and semiconductor allocation priority. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market