
 Global Automotive Onboard Charger Market | 2026-2036
Global Automotive Onboard Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Onboard Charger Market Intelligence
Expertise in power electronics and high-voltage systems engineering is redrawing the competitive map for automotive onboard chargers. This requires a specialized talent pool that is currently a bottleneck for some market entrants. BorgWarner Inc. leverages its extensive powertrain integration experience to secure OEM contracts. STMicroelectronics specializes in the core semiconductor components that enable higher efficiency, while Valeo SE competes through its broad portfolio of electrification systems.
An automotive onboard charger is a system within an electric vehicle that converts AC electricity from an external source into the DC power required to charge the vehicle's battery pack. These units typically operate at power levels ranging from 3.3 kW to 22 kW. The adoption of Silicon Carbide and Gallium Nitride technologies is enabling more compact and efficient designs compared to legacy IGBT modules. Demand from Battery Electric Vehicles applications far outpaces that from hybrids, pushing development towards higher-power, three-phase charger configurations.
Regulatory frameworks directly influence component design and market access. The EU's F-Gas Regulation and US EPA rules indirectly support the EV transition, while specific charging standards like ISO 15118 and China's GB/T standards dictate interoperability protocols. These mandates ensure safety and compatibility across different vehicles and charging infrastructure. The central strategic challenge for suppliers is managing the R&D investment required for next-generation bidirectional chargers.
Market Dynamics
The transition to wide-bandgap semiconductors is the central force defining product development. This technological shift enables the higher power densities and efficiencies required by next-generation battery electric vehicles, altering supplier-OEM relationships and cost structures.
Growth Catalysts
- Government Mandates:China's EV incentives and EU CO2 emission standards force automakers to increase BEV production, directly raising onboard charger volume.
- Wide-Bandgap Semiconductors:Silicon Carbide (SiC) technology enables more compact, efficient chargers, improving vehicle performance and reducing consumer charging times.
- Infrastructure Expansion:A growing network of public AC charging points makes EV ownership more practical, justifying OEM investment in higher-power onboard systems.
Market Restraints
- Component Cost:The material and fabrication costs for Silicon Carbide wafers present a significant hurdle compared to mature IGBT power modules.
- Supply Chain Concentration:Production of automotive-grade SiC substrates is limited to a few suppliers, creating sourcing risks and price volatility for manufacturers.
- Thermal Engineering:Increasing power density in compact charger packages introduces complex thermal management challenges, requiring costly and advanced cooling solutions.
Strategic Opportunities
- Bidirectional Functionality:Developing chargers with vehicle-to-grid (V2G) capability opens revenue streams from grid services and home energy management systems.
- Geographic Expansion:India's PLI scheme and other national electrification policies create significant growth opportunities for suppliers beyond established EV markets.
- System Integration:Combining the onboard charger with the DC-DC converter into one integrated power unit reduces vehicle cost, weight, and complexity.
Industry Challenges
- Talent Scarcity:A shortage of power electronics engineers with expertise in high-voltage automotive systems is a critical bottleneck for new product development.
- Regulatory Fragmentation:Ensuring interoperability across evolving regional standards like ISO 15118 and China's GB/T adds significant R&D and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Onboard Charger Market |
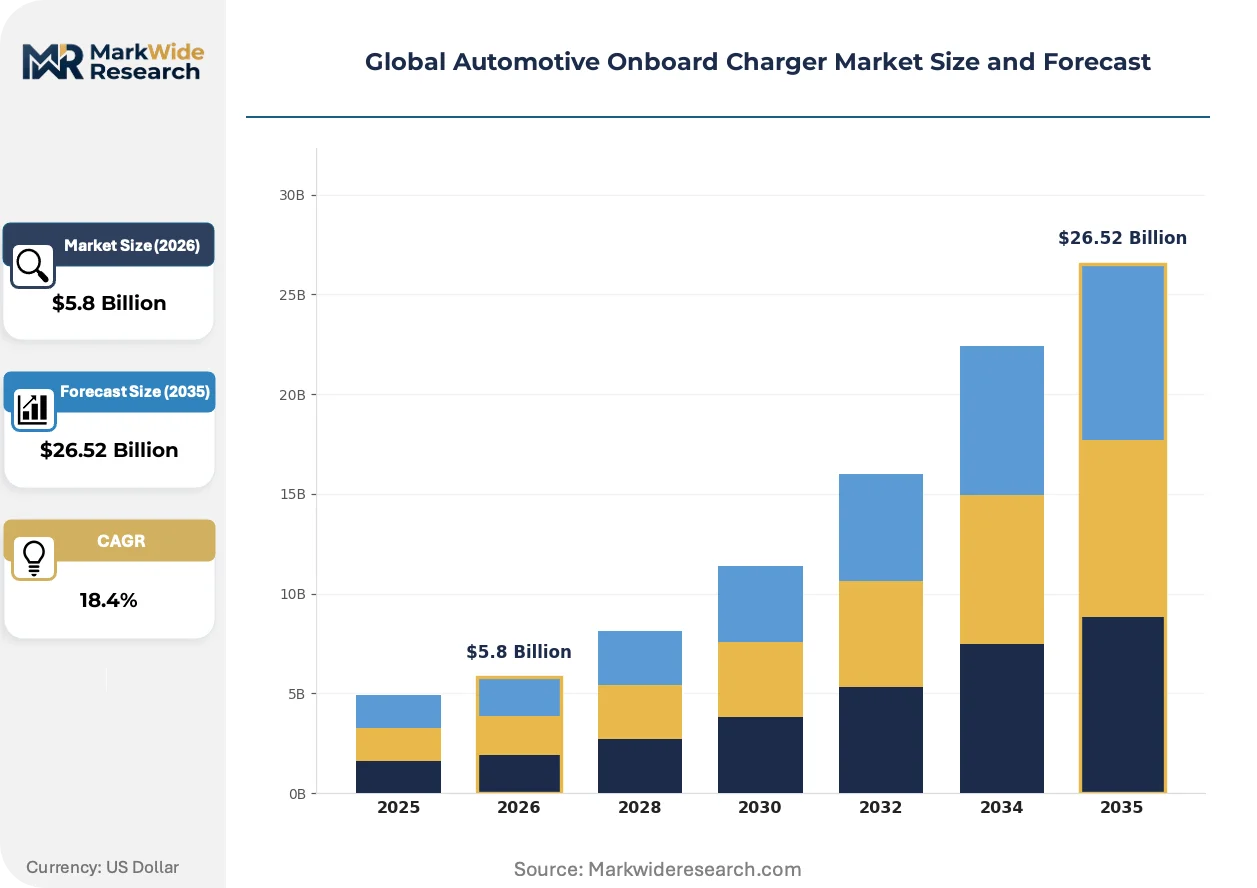
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Bidirectional, High Voltage, Low Voltage Technology: Silicon Carbide, Gallium Nitride, IGBT, MOSFET, Thyristor Application: Battery Electric Vehicles, Hybrid Electric Vehicles, Commercial Vehicles, Light Duty Vehicles, Two Wheelers End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | BorgWarner Inc., Hyundai Mobis Co., Ltd., Delta Electronics, Inc., Valeo SE, Toyota Industries Corporation, Eaton Corporation, STMicroelectronics, LG Electronics, Ficosa International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Onboard Charger Market Strategic Shifts & Innovations
The market's evolution is defined by a push for higher efficiency and greater functional integration. Development focuses on creating smaller, more powerful units that expand the vehicle's role within the broader energy ecosystem.
Wide-bandgap semiconductors like Silicon Carbide (SiC) are key to creating power-dense, efficient onboard chargers. Automakers are adopting SiC-based designs, particularly for chargers rated at 11 kW and higher, to reduce weight and improve vehicle efficiency. This technological shift is fragmenting the traditional automotive power module supply chain, historically dominated by IGBTs.
Communication standards like ISO 15118 are becoming mandatory in key markets. The protocol enables advanced "Plug & Charge" functionality and is a prerequisite for bidirectional power flow like vehicle-to-grid (V2G). Implementation of ISO 15118 in the European Union impacts charger software architecture, demanding significant investment in cybersecurity and interoperability testing.
Consumer expectations for faster home charging are accelerating. This shifts OEM demand from basic single-phase 7.4 kW units towards more powerful three-phase 11 kW and 22 kW onboard chargers. This demand-side shift is particularly visible in European residential markets, where three-phase electrical service is more commonly available to households.
Global Automotive Onboard Charger Market Segmentation
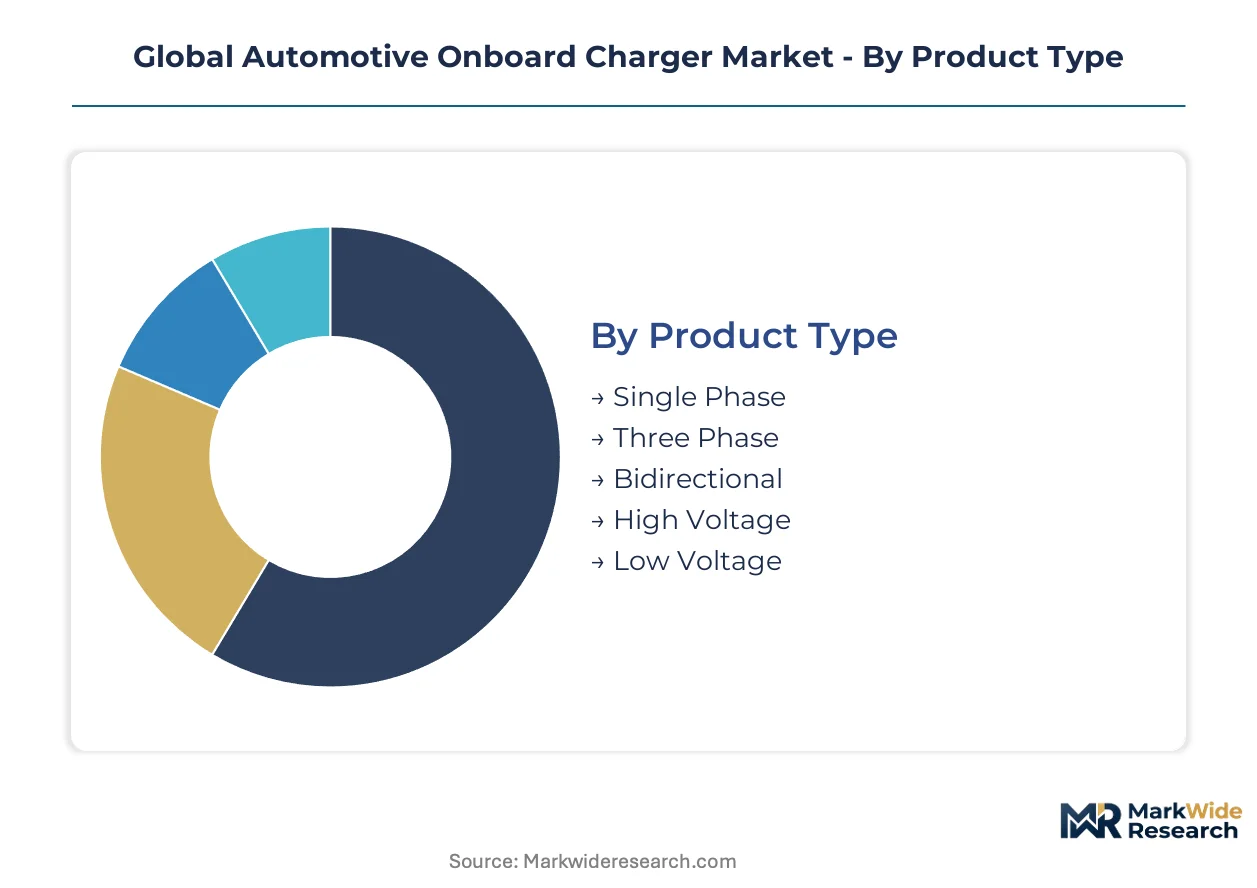
The global automotive onboard charger market is intricately segmented, reflecting diverse technological advancements and evolving vehicle architectures. Understanding these segments is crucial for assessing competitive dynamics and identifying specific growth pockets within the electric vehicle ecosystem.
Product Type:
Segments within product type face varying degrees of substitution pressure from evolving charging infrastructure and vehicle power demands.
- Three Phase:These units typically operate at 11 kW or 22 kW, converting three-phase AC electricity for faster battery charging. Demand for three-phase chargers is particularly strong in European residential markets where compatible electrical grids are common.
- Bidirectional:Bidirectional chargers enable power flow in two directions, supporting vehicle-to-grid (V2G) and vehicle-to-home (V2H) applications. This functionality requires significant R&D investment in advanced power electronics and communication protocols like ISO 15118.
- Single Phase:Single-phase onboard chargers are widely adopted in entry-level EVs, typically offering power levels up to 7.4 kW for home charging.
- High Voltage:High voltage chargers are designed for vehicles with battery packs operating at 800V or higher, enabling faster charging speeds and improved vehicle performance.
- Low Voltage:Low voltage onboard chargers are primarily found in hybrid electric vehicles or for auxiliary systems, operating at lower power levels.
Single Phase anchors the volume base while Bidirectional gains share at the steepest rate.
Technology:
The technology landscape reflects distinct cost tiers, influencing adoption rates and market penetration across vehicle platforms.
- Silicon Carbide:Silicon Carbide (SiC) is a wide-bandgap semiconductor enabling higher power density, increased efficiency, and more compact onboard charger designs. Automakers are adopting SiC-based chargers for premium Battery Electric Vehicles to reduce weight and improve range.
- IGBT:Insulated Gate Bipolar Transistors (IGBTs) represent a mature power semiconductor technology, offering cost-effective solutions for onboard chargers. Legacy IGBT modules are widely used in hybrid electric vehicles, though they present thermal management challenges at higher power levels.
- Gallium Nitride:Gallium Nitride (GaN) is an emerging wide-bandgap semiconductor offering even higher switching frequencies and efficiencies compared to SiC, enabling further miniaturization.
- MOSFET:Metal-Oxide-Semiconductor Field-Effect Transistors (MOSFETs) are used in lower power onboard charger applications, offering good efficiency at moderate voltages.
- Thyristor:Thyristor technology is less common in modern automotive onboard chargers due to slower switching speeds and larger footprints compared to semiconductor alternatives.
Demand for Silicon Carbide technology concentrates in premium BEV segments, while IGBT modules maintain significant presence in cost-sensitive applications.
Application:
Application segments exhibit diverse volume requirements, directly impacting onboard charger power specifications and design complexity.
- Battery Electric Vehicles:BEVs represent the primary growth driver for advanced onboard chargers, demanding higher power levels (11 kW, 22 kW) and integration of wide-bandgap semiconductors. These vehicles require robust charging solutions to minimize charging times and maximize convenience.
- Hybrid Electric Vehicles:HEVs typically utilize lower power onboard chargers, often single-phase units, as their primary propulsion still relies on an internal combustion engine. The focus for HEV chargers remains on cost-effectiveness and reliability rather than extreme power density.
- Commercial Vehicles:Commercial vehicles, including electric buses and trucks, require high-power and robust onboard charging systems to support larger battery capacities and demanding operational cycles.
- Light Duty Vehicles:This segment encompasses passenger cars and light trucks, forming the largest volume base for onboard chargers, ranging from basic single-phase to advanced bidirectional units.
- Two Wheelers:Electric two-wheelers utilize compact, lower-power onboard chargers, often integrated directly into the battery pack or chassis for convenience.
Battery Electric Vehicles represent the market's most dynamic application, contrasting with the mature demand from Hybrid Electric Vehicles.
End User:
End-user segments reveal distinct supply chain concentration patterns, influencing procurement strategies and partnership structures.
- OEMs:Original Equipment Manufacturers integrate onboard chargers directly into their vehicle platforms, often dictating specific design requirements and performance standards. OEMs engage in long-term contracts with specialized suppliers for these critical components.
- Tier-1 Suppliers:Tier-1 suppliers specialize in designing, manufacturing, and supplying complete onboard charger units to OEMs. Companies like BorgWarner Inc. leverage their expertise to secure significant OEM contracts.
- Vehicle Assemblers:Vehicle assemblers focus on the final integration of components into the complete vehicle, relying on OEMs and Tier-1 suppliers for pre-assembled onboard charger modules.
- Aftermarket Providers:Aftermarket providers offer replacement or upgrade onboard charger units, catering to vehicle owners seeking enhanced performance or repair solutions.
OEMs define product specifications, while Tier-1 Suppliers execute the majority of component manufacturing and integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's strong government incentives for electric vehicles differentiate its onboard charger consumption mix. European markets prioritize three-phase charging for faster home solutions. The United States focuses on regulatory alignment and infrastructure development, while other regions see emerging demand.
China
China's robust EV incentives directly stimulate demand for high-power onboard chargers. The country's GB/T standards ensure interoperability across its vast charging infrastructure. The Yangtze River Delta region, including Shanghai, drives significant innovation in EV component manufacturing.
Germany
German consumers expect faster charging solutions, driving demand for 11 kW and 22 kW three-phase units. EU CO2 emission standards compel automakers to increase BEV production, boosting charger volumes. Bavaria, with its automotive industry concentration, fosters advanced power electronics R&D and manufacturing.
United States
Growing electric vehicle sales and expanding public AC charging points increase demand for onboard chargers. US EPA rules indirectly support the EV transition, influencing vehicle electrification strategies. California, a major EV market, sees significant investment in advanced charging technologies and vehicle integration.
South Korea
South Korea's robust domestic EV production drives demand for high-efficiency and compact onboard chargers. National policies promote advanced EV component development and local manufacturing capabilities. The Seoul Capital Area hosts major automotive and electronics companies, advancing integrated power unit designs.
India
India's government electrification push creates significant growth opportunities for onboard charger suppliers. The PLI scheme encourages local manufacturing of advanced automotive components, including chargers. Maharashtra and Gujarat are emerging manufacturing hubs, attracting investment in EV component production.
Global Automotive Onboard Charger Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the automotive onboard charger market. This structure reflects a blend of large, diversified automotive suppliers and niche power electronics experts. Strategic archetypes include full-system integrators, core component providers, and regional manufacturing specialists. Dominant competitive moves involve strategic partnerships with OEMs and continuous R&D investment in wide-bandbandgap semiconductors.
Among the integrated leaders, BorgWarner Inc. exemplifies extensive expertise in powertrain integration, consistently securing significant OEM contracts across various automotive segments. STMicroelectronics, a prominent semiconductor specialist, occupies a critical position by supplying the core wide-bandgap components that enable higher efficiency and more compact charger designs. Valeo SE sits within the tier of broad electrification system providers, offering diverse solutions across various vehicle platforms and supporting the transition to electric mobility. These companies represent distinct strategic approaches, from comprehensive system delivery to specialized component innovation, shaping the competitive dynamics of the global market.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hyundai Mobis Co., Ltd. |
| Delta Electronics, Inc. |
| Valeo SE |
| Toyota Industries Corporation |
| Eaton Corporation |
| STMicroelectronics |
| LG Electronics |
| Ficosa International S.A. |
| Others |
Cost & Logistics Intelligence
Extended lead times for critical wide-bandgap semiconductor components influence the automotive onboard charger supply chain, giving integrated component suppliers significant pricing leverage. This concentration directly impacts the cost structure for next-generation electric vehicle platforms.
Pricing Analysis
Long-term offtake agreements characterize the dominant pricing model between Tier-1 suppliers and OEMs for onboard chargers. Price differentiation stems from Silicon Carbide content and advanced bidirectional functionality. Pricing pressure intensifies for basic 7.4 kW single-phase units due to increased competition and cost-down mandates. Entry-level Battery Electric Vehicles and Hybrid Electric Vehicles exhibit the highest price sensitivity, contrasting with premium BEV segments.
Supply Chain Analysis
China and South Korea anchor the manufacturing of advanced power electronics and integrated onboard charger modules. The supply chain draws from critical raw materials like Silicon Carbide wafers and specialized magnetics. Single-source vulnerability for automotive-grade SiC substrates presents a significant structural risk for manufacturers. Distribution primarily flows direct from Tier-1 suppliers to Original Equipment Manufacturers for vehicle integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a substitution defense play, where incumbents must navigate the rapid deployment of high-power DC fast charging infrastructure. Protecting market share requires continuous innovation in onboard charging technology.
For Market Incumbents:
Fortify R&D investment in advanced wide-bandgap semiconductors like Gallium Nitride to enhance power density and efficiency. Secure long-term supply agreements for critical Silicon Carbide wafers to mitigate sourcing risks. Deepen vertical integration into power module manufacturing to control costs and intellectual property. This counters the threat from specialized power electronics firms and ensures technological leadership for future vehicle platforms.
For New Entrants and Emerging Players:
Integration complexity of bidirectional charging software presents a service-layer gap where incumbents under-serve. Target the commercial vehicle segment or specialized vehicle-to-grid applications with modular, standardized software platforms. Focus on integrated power units combining onboard chargers with DC-DC converters to reduce vehicle complexity. This strategy allows penetration by addressing specific high-value white-space opportunities.
For Investors and Strategic Acquirers:
Long-term, this sits as a technology-driven growth play because electrification trends demand increasingly efficient and compact charging solutions. Acquisition targets should include niche power electronics firms with proven Silicon Carbide or Gallium Nitride expertise. Look for software developers specializing in ISO 15118 communication protocols or V2G energy management. The signal to watch is OEM announcements regarding 800V vehicle architectures or widespread bidirectional charging mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Investment in SiC/GaN R&D | Advances power density and efficiency for next-generation electric vehicle platforms. |
| Strategic partnerships with semiconductor manufacturers | Ensures stable supply and co-development of critical wide-bandgap components. |
| Developing integrated OBC/DC-DC units | Reduces vehicle weight and complexity while optimizing power electronics packaging. |
| Expanding bidirectional charging capabilities | Unlocks new revenue streams from vehicle-to-grid and home energy management. |
| Targeting commercial vehicle applications | Captures high-power, robust charging demand from electric trucks and buses. |
Research Approach
Cross-validation between primary interviews with OEM engineers and secondary data from automotive production databases anchors the qualitative findings. This approach ensures robust insights into market dynamics. Industry stakeholders included OEM platform engineers, Tier-1 procurement leads, power electronics R&D directors, and EV infrastructure planners. Secondary sources comprised vehicle registration data, government EV incentive reports, and semiconductor industry analyses, triangulated with bottom-up market sizing.
Sensitivity analysis quantifies the impact of varying EV adoption rates and regulatory changes across the modeling period. The analytical framework incorporated segmentation dimensions such as product type, technology, application, regional EV policy, and charging power level. Compound Annual Growth Rates were derived from historical trends and projected technological shifts. Key forecast inputs included global EV production forecasts and wide-bandgap semiconductor cost curves.
Underlying assumptions cover stable government incentives and infrastructure buildout, with deviation risk concentrated in rapid shifts in battery technology or global economic downturns. Forecasts reflect these assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
EV Traction Motor Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
High Speed Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
North America Electric Motor Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Car Charger Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Motor Gear Unit Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Smart E-Drive Market