
 Electric Vehicle Shielded HV Cables Market | 2026-2036
Electric Vehicle Shielded HV Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Shielded HV Cables Market Insights
Fleet operators and premium passenger OEMs are reorganizing procurement priorities around electromagnetic compatibility and thermal resilience in high-voltage architectures. Sumitomo Electric Industries leverages its integrated materials science portfolio to dominate shielding performance benchmarks for 800V platforms. Prysmian Group anchors European supply security through localized extrusion and compounding capacity near Stuttgart and Munich. Leoni AG differentiates via modular cable system design that reduces assembly complexity for battery pack integrators.
Electric vehicle shielded HV cables are multi-layer conductor assemblies incorporating aluminum or copper cores, semiconductor layers, XLPE insulation, and metallic braid shielding to contain electromagnetic emissions while managing thermal loads above 150°C in continuous operation. Their primary purpose is to transmit direct current power between battery packs, inverters, and traction motors without interference to adjacent control systems or external receivers. Shielded cables command the largest value share due to mandatory electromagnetic compatibility requirements in battery systems and motor connections, while multi-core configurations represent the fastest-growing product type as manufacturers consolidate wiring harnesses to reduce weight and installation labor. Aluminum conductor variants are gaining material share against copper where OEMs accept modest conductivity trade-offs for mass reduction in long-run power distribution segments.
Europe's ECE R10 regulation and the EU's F-Gas framework are tightening electromagnetic and environmental standards that dictate shielding effectiveness thresholds and material composition in cable insulation systems. China's GB standards and NMPA vehicle certification protocols are converging toward equivalent shielding performance mandates for domestic EV platforms. Japan's METI roadmap for next-generation mobility is accelerating JIS standard revisions that will test shielding durability under extended thermal cycling. Stakeholders must monitor regulatory divergence between electromagnetic compatibility testing protocols to avoid redundant certification costs across export markets.
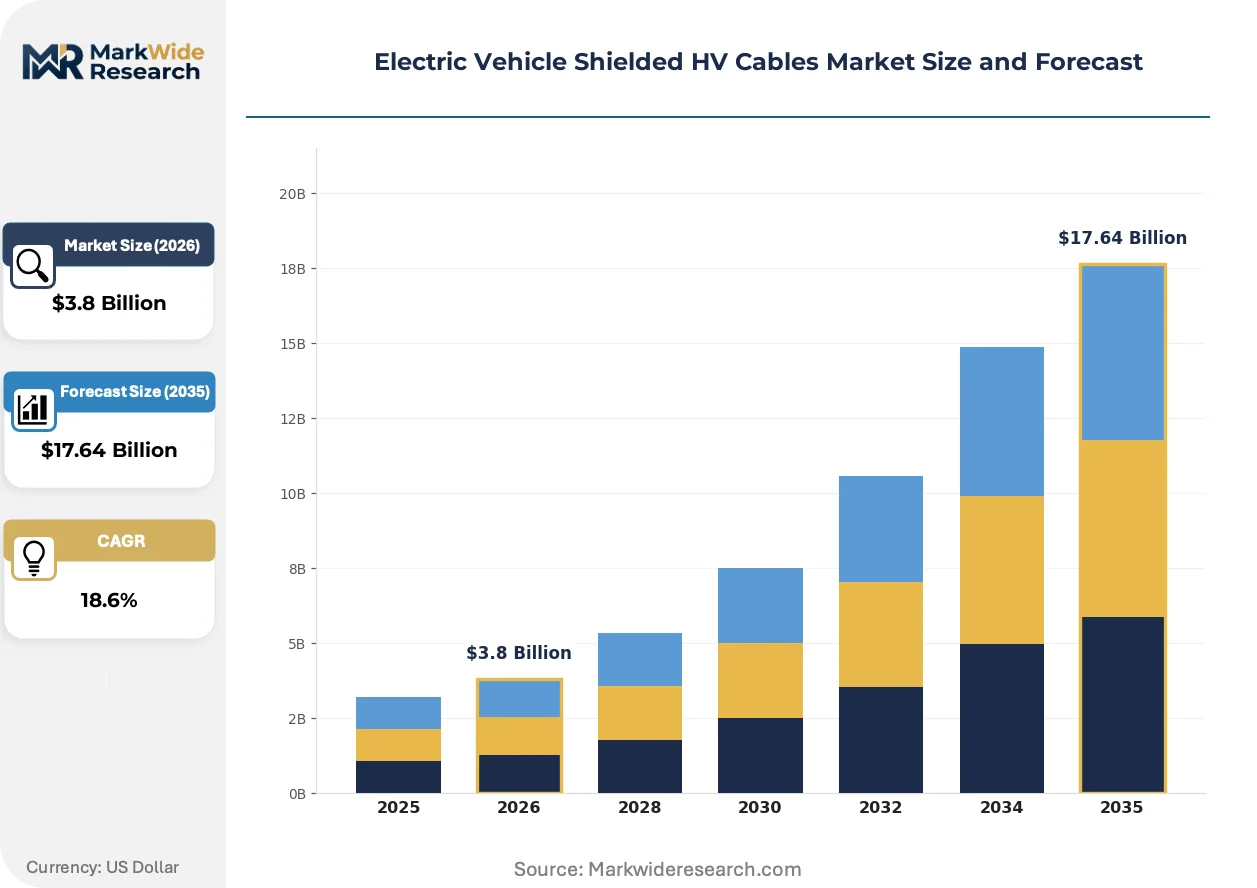
Market Dynamics
Platform voltage escalation from 400V to 800V architectures is compressing shielding performance tolerances and forcing cable suppliers to redesign conductor geometries and braid densities for electromagnetic containment under higher thermal loads.
Growth Catalysts
- ECE R10 electromagnetic compliance:Europe's tightening interference thresholds mandate upgraded shielding across all battery-electric platforms, pulling demand for multi-layer cable assemblies with enhanced metallic braid coverage.
- Aluminum conductor substitution:Mass-sensitive OEMs in long-run distribution segments are accepting conductivity trade-offs to reduce vehicle weight, expanding material options beyond copper cores.
- 800V platform proliferation:Premium passenger EV architectures require thicker insulation walls and semiconductor layers to manage dielectric stress, elevating cable complexity and value per meter.
Market Restraints
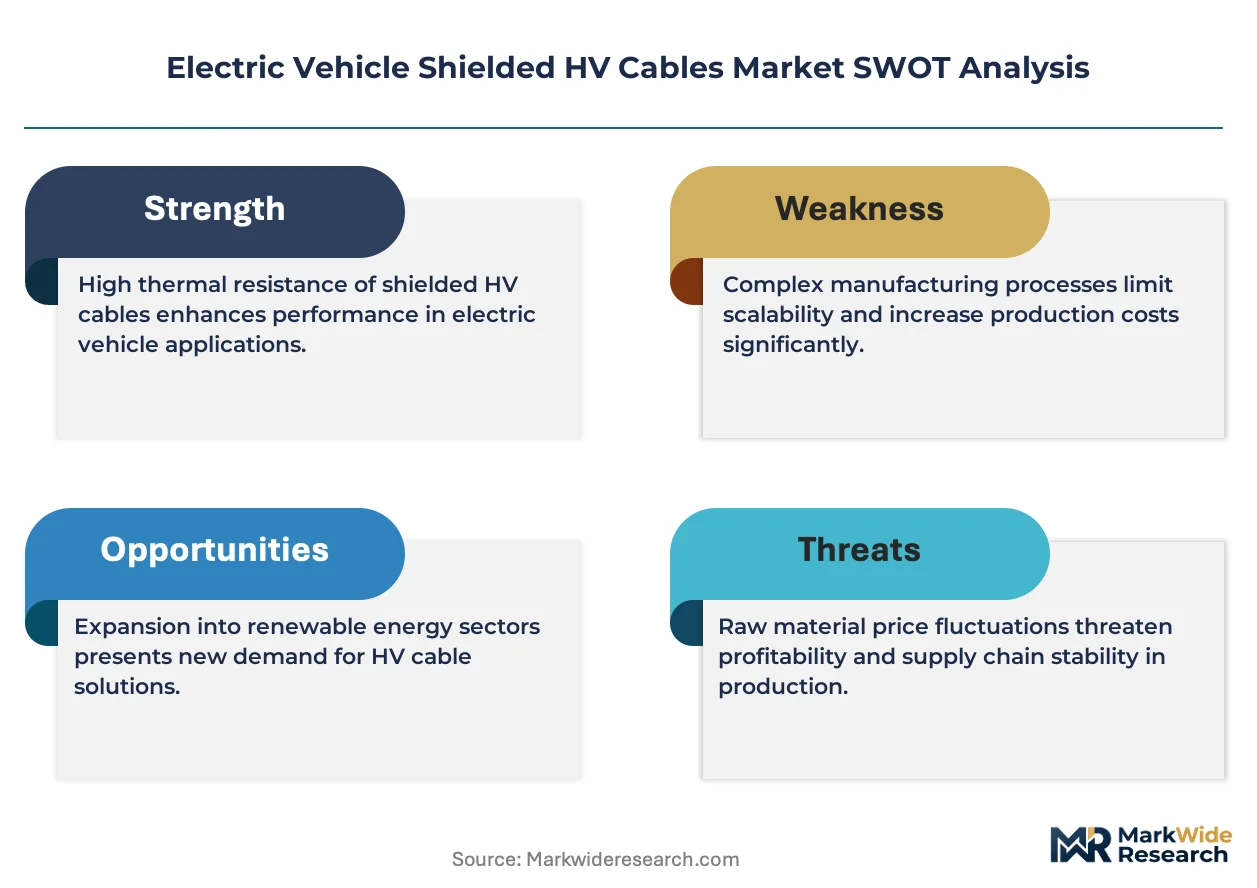
- Copper price volatility:Conductor materials represent the largest cost component in HV cable assemblies, exposing manufacturers to London Metal Exchange fluctuations that compress margin predictability.
- German supply concentration:Extrusion and compounding capacity clusters near Stuttgart and Munich create geographic vulnerability to regional energy cost spikes or logistics disruptions.
- XLPE thermal ceiling:Cross-linked polyethylene insulation faces hard temperature limits around 150°C continuous operation, constraining power density in next-generation motor connections.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing will localize battery pack assembly, creating demand for shielded HV cable supply chains serving domestic OEMs.
- Multi-core harness consolidation:Battery pack integrators are consolidating discrete wiring runs into unified cable systems, opening design contracts for modular assemblies that reduce installation labor.
- China GB standard convergence:NMPA certification protocols are aligning with European electromagnetic benchmarks, enabling cable suppliers to serve both markets with single qualification cycles.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite-element modeling for shielding effectiveness prediction requires specialized physics expertise that outpaces current vocational training pipelines.
- ECE R10 certification timelines:Revised testing protocols for 800V systems extend validation cycles by four to six months, delaying platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Shielded HV Cables Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shielded Cables, Unshielded Cables, Heavy-Duty Cables, Multi-Core Cables Material: Copper, Aluminum, PVC, XLPE Application: Battery Systems, Charging Infrastructure, Motor Connections, Power Distribution End User: Automotive Manufacturers, EV Charging Stations, Fleet Operators, Consumers |
| Companies Covered | Sumitomo Electric Industries Ltd., Prysmian Group, Leoni AG, Aptiv PLC, Yazaki Corporation, Nexans S.A., Huber + Suhner, TE Connectivity Ltd., Furukawa Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Shielded HV Cables Market Trends and Innovations
Material science advances and regulatory harmonization are compressing traditional cable design cycles while fragmenting competitive advantage across electromagnetic simulation capabilities rather than extrusion scale alone.
Semiconductor-layer extrusion technology is fragmenting established supply relationships. Tier-1 battery pack integrators in Germany and Japan are qualifying second-source suppliers for gradient-insulation layers that manage electric field distribution across conductor interfaces. This capability dispersion is fragmenting procurement concentration that previously favored integrated materials houses.
Europe's F-Gas framework is accelerating fluoropolymer phase-out in cable insulation systems. Manufacturers must reformulate jacket materials to maintain chemical resistance without perfluorinated compounds, with Stuttgart-based OEMs piloting bio-based thermoplastic elastomers for under-hood routing. The regulatory pressure is compressing material qualification timelines while elevating testing costs for alternative formulations.
Fleet operators are unbundling cable specification from full harness procurement. Large logistics operators in California and Lower Saxony are issuing direct material specifications to cable manufacturers, bypassing traditional tier-1 wiring harness distributors. This disintermediation is compressing distributor margins while forcing cable suppliers to build direct technical service capabilities for volume accounts.
Electric Vehicle Shielded HV Cables Market Segmentation
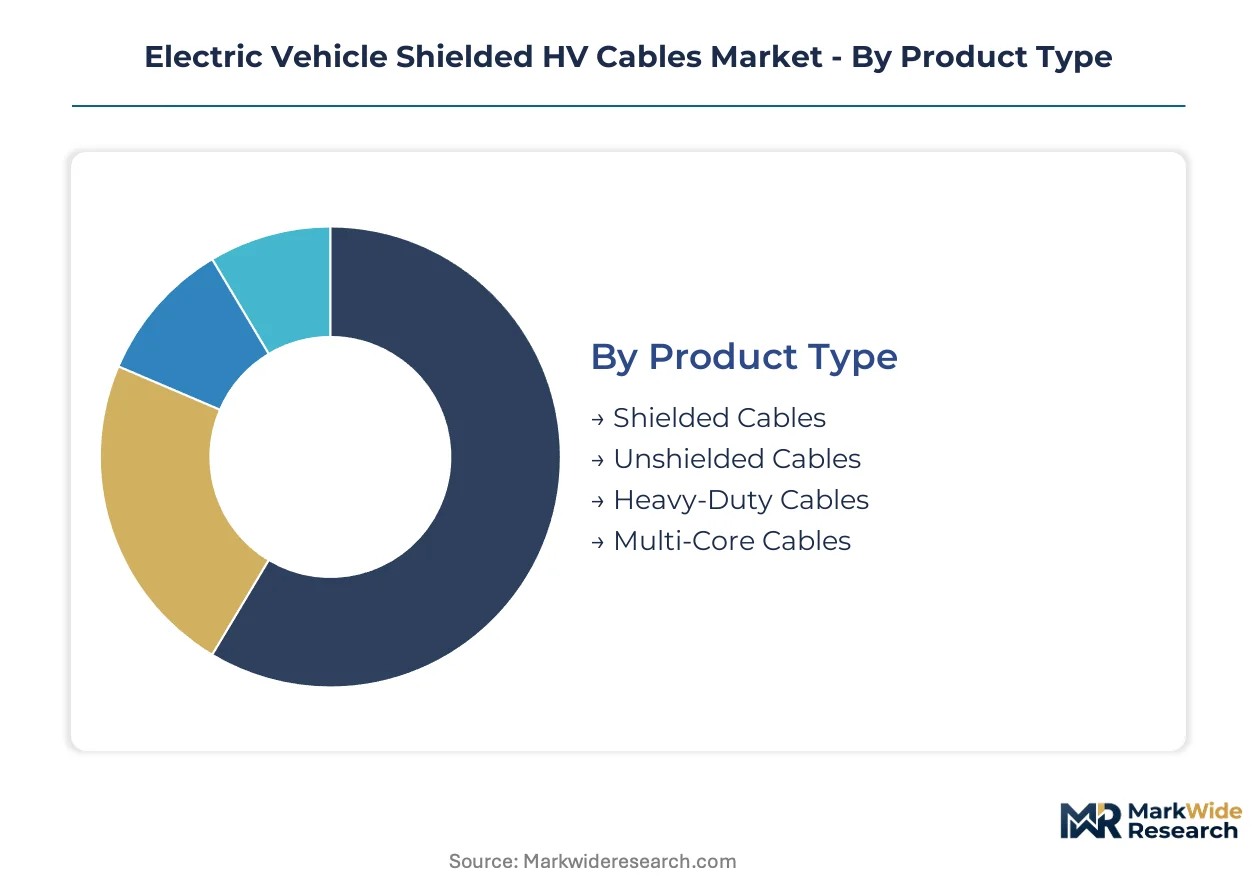
Segmentation in the electric vehicle shielded HV cables market reveals how procurement channels fragment across voltage classes and thermal specifications. Procurement officers route high-complexity shielded assemblies through direct OEM contracts while standard unshielded variants flow via tier-1 harness distributors.
Product Type:
Channel routing diverges sharply by electromagnetic containment requirements, with shielded variants commanding direct technical sales relationships and unshielded cables moving through volume distributors serving cost-sensitive platforms.
- Shielded Cables:Multi-layer assemblies incorporate metallic braid shielding and semiconductor layers to contain electromagnetic emissions under ECE R10 thresholds. German premium OEMs in Stuttgart and Munich mandate these for all battery-to-inverter connections on 800V architectures.
- Multi-Core Cables:Consolidated conductor bundles reduce installation labor and harness weight in battery pack integration. Fleet operators in California and Lower Saxony are specifying these directly to manufacturers, bypassing traditional tier-1 distributors to compress assembly costs.
- Unshielded Cables:Simpler conductor-insulation assemblies serve auxiliary power routing where electromagnetic interference poses minimal risk to vehicle systems.
- Heavy-Duty Cables:Reinforced jacketing and enhanced thermal management suit commercial vehicle power distribution with extended duty cycles.
By volume, shielded cables lead procurement schedules. By growth pace, multi-core configurations are climbing the fastest as pack integrators consolidate wiring architectures.
Material:
Cost tiers stratify sharply around conductor metal selection, with aluminum commanding premium positioning for mass reduction despite conductivity trade-offs while copper retains volume dominance in short-run, high-current segments.
- Copper:Highest conductivity cores dominate motor connections and fast-charging infrastructure where resistive losses directly impact thermal management. London Metal Exchange price volatility compresses margin predictability for manufacturers locked into annual supply contracts.
- XLPE:Cross-linked polyethylene insulation systems manage dielectric stress up to 150°C continuous operation across 400V and 800V platforms. Stuttgart-based OEMs are piloting reformulated grades to maintain performance as F-Gas framework pressures eliminate fluoropolymer alternatives.
- Aluminum:Reduced density conductors serve long-run power distribution where OEMs accept modest efficiency losses for vehicle mass reduction.
- PVC:Lower-cost jacketing materials retain share in auxiliary routing applications with relaxed thermal requirements.
Copper retains the dominant revenue position. Aluminum is gaining share fastest where mass-sensitive platforms extend driving range.
Application:
Application segments map directly to thermal load intensity and regulatory scrutiny, with battery systems commanding highest specification grades and charging infrastructure segments fragmenting across power level tiers.
- Battery Systems:Cell-to-inverter connections require maximum shielding effectiveness and dielectric resilience under sustained thermal cycling. ECE R10 compliance mandates multi-layer assemblies with enhanced metallic braid coverage across all European platforms.
- Charging Infrastructure:Station-to-vehicle connections span 400V to 800V architectures with varying duty cycles. China's GB standards and NMPA certification protocols are converging toward European electromagnetic benchmarks, enabling single qualification cycles for export suppliers.
- Motor Connections:Inverter-to-traction motor routing faces hard thermal ceilings around 150°C that constrain power density in next-generation designs.
- Power Distribution:Consolidated routing across vehicle architectures favors multi-core configurations to reduce installation complexity.
Battery systems absorb the largest cable volumes per vehicle. Charging infrastructure is expanding most quickly as public network deployment accelerates.
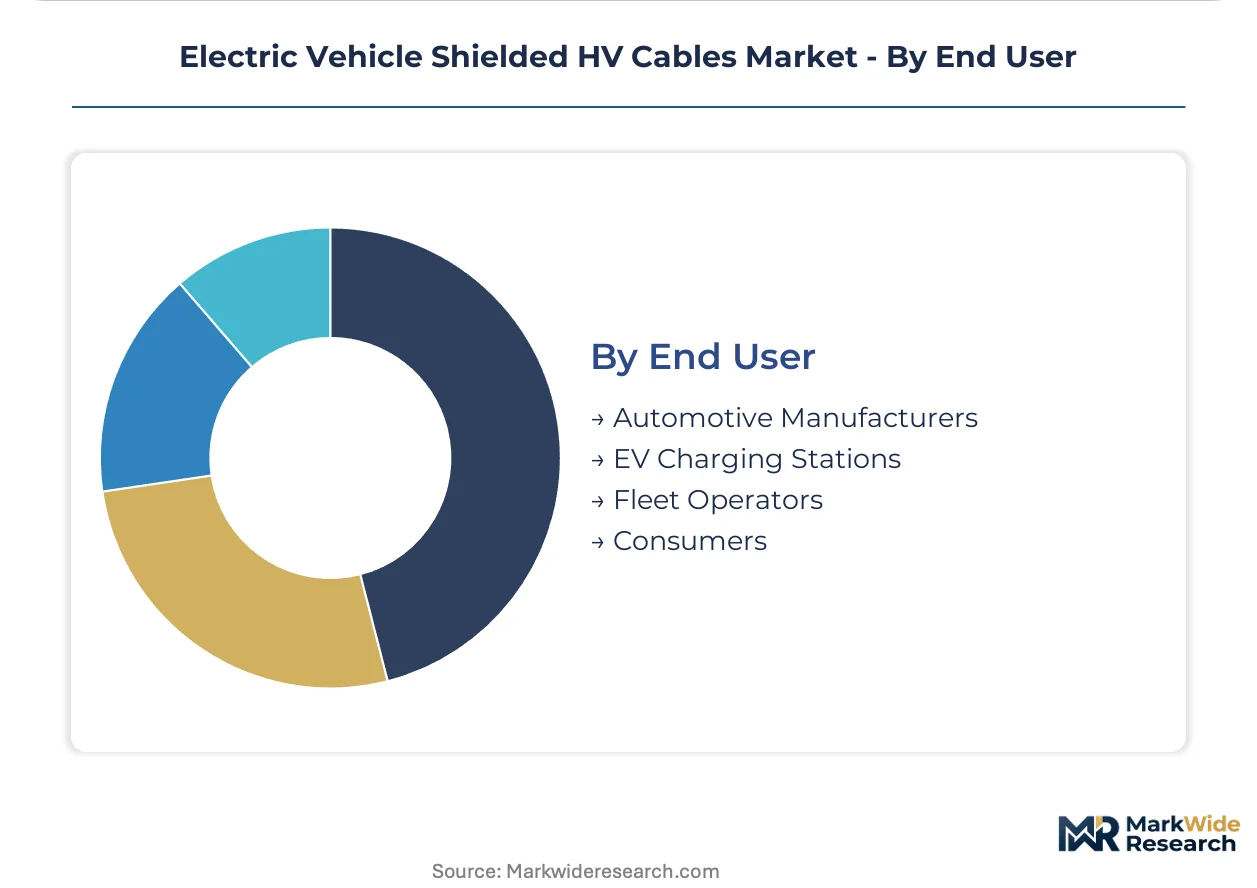
End User:
Customer type determines contract structure, with automotive manufacturers demanding integrated system design services and fleet operators unbundling material specifications from full harness procurement.
- Automotive Manufacturers:Integrated platform developers specify complete cable systems with electromagnetic simulation validation and thermal modeling. German OEMs are localizing supply chains near Stuttgart and Munich extrusion clusters to compress logistics exposure.
- Fleet Operators:Large logistics operators in California and Lower Saxony issue direct material specifications to cable manufacturers, disintermediating tier-1 wiring harness distributors and compressing distributor margins.
- EV Charging Stations:Infrastructure operators procure heavy-duty assemblies rated for continuous outdoor exposure and repeated connection cycles.
- Consumers:Aftermarket replacement demand remains minimal given integrated vehicle architectures and limited serviceability.
Automotive manufacturers dominate procurement value. Fleet operators are restructuring purchasing fastest through direct material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cable extruders dominate European supply security for premium passenger platforms, while Chinese manufacturers scale GB-standard production for domestic OEM electrification roadmaps. Japanese suppliers anchor shielding technology advancement through METI-funded next-generation mobility programs.
Germany
Premium OEM procurement localizes around Stuttgart and Munich extrusion corridors for 800V platform supply security. ECE R10 electromagnetic compliance mandates pull multi-layer shielded assemblies into all battery-electric architectures. Baden-Württemberg compounding clusters are expanding semiconductor-layer capacity to meet tightened interference thresholds.
China
Domestic EV platform proliferation drives HV cable specification at scale across NMPA-certified manufacturers. GB standards convergence with European electromagnetic benchmarks enables single qualification cycles for export-oriented suppliers. Yangtze River Delta battery pack integrators are consolidating multi-core harness procurement to reduce installation labor.
United States
Fleet operators in California issue direct material specifications to cable manufacturers, disintermediating traditional tier-1 wiring harness distributors. NHTSA safety protocols and state-level zero-emission mandates accelerate shielded cable adoption in commercial vehicle electrification. Detroit-area automotive engineering centers are validating 800V cable systems for next-generation truck platforms.
Japan
METI roadmap funding accelerates JIS standard revisions for shielding durability under extended thermal cycling. Domestic OEMs prioritize electromagnetic simulation capabilities in supplier qualification for next-generation mobility architectures. Nagoya-area automotive electronics clusters are integrating cable shielding design into platform development cycles.
India
PLI scheme incentives for advanced chemistry cell manufacturing localize battery pack assembly and create downstream HV cable demand. BIS certification alignment with international electromagnetic standards reduces technical barriers for component imports. Tamil Nadu and Gujarat automotive manufacturing corridors are attracting cable extrusion investments to serve domestic OEM electrification.
Electric Vehicle Shielded HV Cables Market Competitive Landscape
Player mix skews toward integrated materials science houses with captive conductor and insulation compounding capabilities. Market structure concentrates around three to five vertically positioned suppliers controlling premium-tier electromagnetic performance benchmarks. Two dominant competitive moves define positioning: backward integration into semiconductor-layer extrusion technology and geographic co-location near Stuttgart and Munich OEM engineering centers.
Among Japanese and European integrated manufacturers, Sumitomo Electric Industries Ltd., Prysmian Group, and Leoni AG occupy positions spanning materials science through modular system design. Sumitomo exemplifies the integrated materials house archetype with control over conductor metallurgy and shielding braid manufacturing. Prysmian represents European supply security positioning through localized extrusion capacity. Leoni sits within the modular system design tier, reducing assembly complexity for battery pack integrators through consolidated harness architectures.
| Leading Market Players |
|---|
| Sumitomo Electric Industries Ltd. |
| Prysmian Group |
| Leoni AG |
| Aptiv PLC |
| Yazaki Corporation |
| Nexans S.A. |
| Huber + Suhner |
| TE Connectivity Ltd. |
| Furukawa Electric Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Aluminum conductor substitution in long-run distribution segments simultaneously redraws procurement geography toward Yangtze River Delta extrusion clusters and compresses unit economics for copper-dependent manufacturers locked into annual London Metal Exchange contracts. This materials transition fragments established pricing power while rewarding suppliers with captive metallurgy capabilities.
Pricing Analysis
400V-to-800V platform transition pricing gaps separate legacy shielding specifications from next-generation semiconductor-layer assemblies with thickened insulation walls. Three-tier pricing structure across premium electromagnetic performance, standard ECE R10 compliance, and economy auxiliary routing reflects certification grade and braid density differentiation. Cost compression in standard-tier cables intensifies as Chinese GB-standard suppliers achieve single-qualification cycles for European export. Fleet operators in Lower Saxony exhibit lowest price sensitivity due to total-cost-of-ownership framing, while aftermarket distributors face margin erosion from direct OEM procurement.
Supply Chain Analysis
Strait of Malacca transit vulnerability for semiconductor-layer polymer feedstocks concentrates risk in Southeast Asian chemical shipping lanes. Extrusion capacity clusters in Germany, China, and Japan anchor global supply, drawing from copper cathode, XLPE resin, and aluminum billet inputs. Single-source vulnerability in gradient-insulation layer qualification feeds from tier-1 battery pack integrator concentration near Stuttgart and Nagoya. Distribution runs through direct technical sales for shielded assemblies and volume distributors for unshielded auxiliary cables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation in California and Lower Saxony shifts procurement leverage toward direct material specification, fragmenting traditional tier-1 distributor intermediation. This buyer-power concentration rewards cable suppliers with technical service capabilities and modular system design expertise.
For Market Incumbents: Consolidate backward integration into semiconductor-layer extrusion technology to defend against second-source qualification trends fragmenting procurement relationships. Prysmian Group's localized compounding capacity near Munich demonstrates geographic co-location as margin protection against energy cost spikes. Captive shielding braid manufacturing anchors electromagnetic performance benchmarking as Sumitomo Electric Industries leverages integrated materials science.
For New Entrants and Emerging Players: ECE R10 fast-track certification for 800V architectures opens white-space in European premium passenger platforms where validation timelines extend four to six months. India's PLI scheme for advanced chemistry cell manufacturing creates penetrable entry point as domestic battery pack assembly localizes HV cable demand. Target fleet operator direct procurement channels with modular multi-core harness designs that reduce installation labor.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive wiring harness specialists lacking electromagnetic simulation capabilities. Long-term viability hinges on 5-10 year platform voltage escalation trajectories toward unified 800V architectures. Watch JIS standard revision timelines under METI funding as inflection signal for shielding durability testing requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor-Layer Extrusion Capacity Expansion | Baden-Württemberg compounding clusters meet tightened ECE R10 interference thresholds for 800V platforms. |
| Aluminum Conductor Metallurgy Investment | Yangtze River Delta extruders capture mass-reduction specifications from range-sensitive OEMs. |
| Multi-Core Harness System Design | Modular architectures reduce assembly complexity for battery pack integrators consolidating wiring runs. |
| GB Standard Convergence Qualification | Single certification cycles enable Chinese suppliers to serve European electromagnetic benchmarks. |
| Direct Fleet Operator Technical Service | California logistics operators bypass tier-1 distributors with material specifications to cable manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 battery pack procurement managers, electromagnetic simulation specialists, and fleet operator maintenance directors and refined through secondary validation against IHS Markit vehicle production databases, ECE R10 regulatory filings, London Metal Exchange copper price series, and NMPA certification protocol documents. Bottom-up segment sizing triangulated with top-down market envelope checks ensures internal consistency across voltage class, conductor material, and application dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segments. CAGRs derive from fitted growth curves calibrated to platform electrification roadmaps and charging infrastructure deployment schedules. Electromagnetic compliance timeline extensions and aluminum substitution elasticity parameters inform scenario boundaries.
Decision-makers should treat outputs as directional under base assumptions of ECE R10 enforcement continuity and 800V platform proliferation; material deviation would warrant model refresh. Revision becomes warranted when copper price volatility crosses threshold margins or when F-Gas framework fluoropolymer phase-out accelerates alternative insulation qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Wireline Trucks Market