
 Personal Mobility Devices Market | 2026-2036
Personal Mobility Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Mobility Devices Market Intelligence
Rehabilitation facilities is pivoting toward outpatient and home-based care models, expanding procurement of portable electric wheelchairs and smart walkers. Invacare Corporation leverages its North American manufacturing footprint to serve this shift. Ottobock sustains technology leadership in prosthetics-adjacent mobility through advanced materials science. Pride Mobility Products anchors the consumer scooter segment with broad retail distribution.
Personal mobility devices encompass wheeled and ambulatory assistive equipment designed to transport or support individuals with impaired locomotion, typically incorporating aluminum or carbon fiber frames, lithium-ion power systems, and joystick or sensor-based control interfaces for commercial and clinical use. Wheelchairs and scooters command the largest revenue pools, while smart devices represent the fastest-expanding technology tier due to IoT integration and remote monitoring capabilities. Manual devices retain dominance in emerging markets where cost sensitivity shapes procurement, though hybrid systems are gaining traction in rehabilitation facilities seeking flexible equipment utilization.
FDA 510(k) clearance requirements and the EU Medical Device Regulation govern product entry in the two largest addressable markets, with FDA focusing on electrical safety and software validation for powered units while MDR demands enhanced clinical evidence and post-market surveillance. Japan's PMDA adds another compliance layer for companies targeting its aging demographic. Stakeholders must monitor reimbursement code updates and cybersecurity standards for connected devices as regulatory scope expands beyond mechanical safety into data governance.
Market Dynamics
The transition from institutional care to home-based rehabilitation is compressing product lifecycles and demanding portable, connected mobility solutions that integrate with remote monitoring infrastructure.
Growth Catalysts
- MDR Clinical Evidence Requirements:The EU Medical Device Regulation mandates enhanced post-market surveillance, accelerating investment in sensor-equipped wheelchairs that generate real-world performance data.
- Lithium-Ion Battery Chemistry:Energy density improvements in lithium iron phosphate cells are extending powered wheelchair range by 40% while reducing charging cycles, expanding viable use cases.
- Japan's Super-Aged Society:METI subsidies for assistive technology procurement are driving PMDA fast-track approvals for smart mobility devices targeting the 65-plus demographic.
Market Restraints
- Neodymium Magnet Supply Concentration:Rare earth processing dominance by Chinese refiners creates input cost volatility for brushless motor production in powered wheelchairs.
- FDA 510(k) Software Validation:Cybersecurity documentation requirements for connected devices extend clearance timelines by 8-14 months, freezing product launches.
- Manual Wheelchair Substitution:Low-cost aluminum-frame devices from Southeast Asian manufacturers displace electric units in price-sensitive emerging markets.
Strategic Opportunities
- German Rehabilitation Clinic Networks:Outpatient care expansion creates demand for foldable electric wheelchairs that transport in standard vehicle trunks.
- ISO 13485 Certification Convergence:Unified quality management standards enable single manufacturing lines to serve FDA, MDR, and PMDA markets simultaneously.
- Telehealth-Integrated Mobility:Remote diagnostics via embedded IoT sensors open recurring revenue streams through predictive maintenance subscriptions.
Industry Challenges
- Embedded Systems Engineering Talent:Shortage of firmware developers with medical device cybersecurity expertise delays connected product roadmaps.
- Legacy Hospital IT Integration:Proprietary data protocols in existing electronic health record systems block seamless device-to-platform connectivity.
- Biocompatibility Testing Backlogs:ISO 10993 skin-contact material assessments face 6-month queue times at accredited laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Mobility Devices Market |
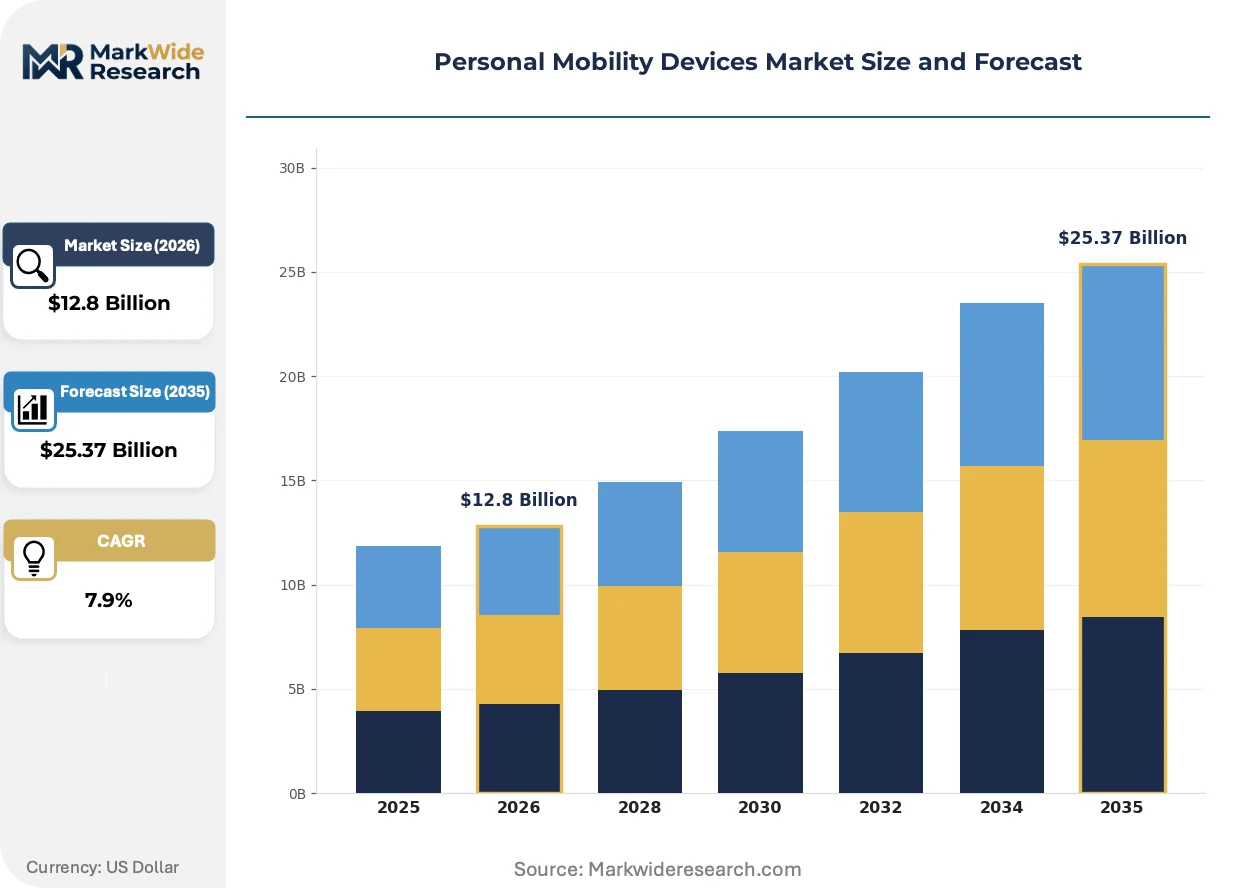
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $25.37 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wheelchairs, Scooters, Walkers, Crutches End User: Individuals with Disabilities, Elderly Citizens, Rehabilitation Facilities, Mobility Clinics Technology: Manual, Electric, Hybrid, Smart Devices Distribution Channel: Retail Stores, Online Marketplaces, Medical Supply Providers, Direct Sales |
| Companies Covered | Invacare Corporation, Ottobock, Drive DeVilbiss Healthcare, Sunrise Medical, Permobil, GF Health Products, Pride Mobility Products, Medline Industries, Arjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Mobility Devices Market Strategic Shifts & Innovations
Software-defined control architectures and sensor fusion are transforming mechanical mobility equipment into data-generating healthcare endpoints. This shift demands new competencies across hardware, firmware, and clinical validation.
Brushless DC motor systems with integrated motor controllers are electrifying wheelchair drivetrain efficiency. Rehabilitation facilities in Germany and the United States are specifying these units for indoor-outdoor hybrid use. The technology is electrifying competitive positioning by compressing the performance gap between mid-tier and premium product lines.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing serialization investments across manufacturing footprints. Component suppliers must now maintain electronic records traceable to individual wheelchair units. Powered mobility categories with software-as-medical-device features face the steepest compliance cost increases.
Hospital procurement departments are consolidating vendor lists around full-service mobility partners capable of equipment, maintenance, and training bundles. Independent durable medical equipment distributors lose share to manufacturer-direct contracts. This concentration is most pronounced in United States integrated delivery networks managing Medicare Advantage populations.
Personal Mobility Devices Market Segmentation
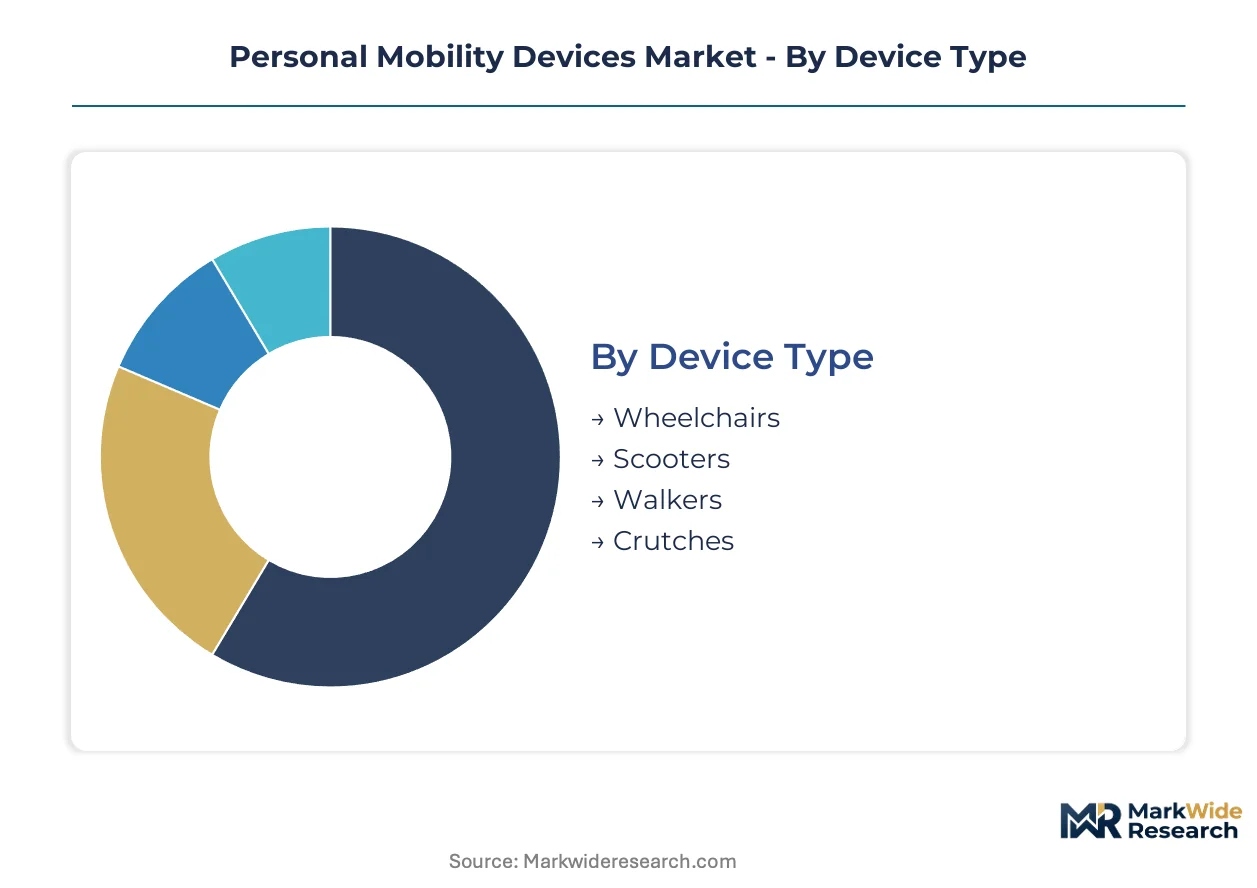
Personal mobility devices span mechanical, electromechanical, and connected systems with divergent certification pathways. Segmentation by device type, technology tier, and distribution channel determines which products face FDA 510(k) software validation, EU MDR clinical evidence requirements, or Japan PMDA fast-track scrutiny.
Device Type:
Wheelchairs and scooters carry the heaviest regulatory burden due to powered variants, while walkers and crutches navigate lighter classification thresholds in most jurisdictions.
- Wheelchairs:Aluminum-frame manual units and lithium-ion powered systems with brushless DC drivetrains. Rehabilitation facilities in Germany and the United States specify foldable electric configurations for outpatient care expansion. FDA electrical safety documentation and MDR post-market surveillance requirements concentrate compliance investment here.
- Scooters:Three-wheel and four-wheel configurations with tiller steering and SLA or lithium battery packs. Consumer procurement through retail channels in the United States drives volume, though Medicare Advantage coding changes reshape reimbursement eligibility. METI subsidies in Japan accelerate PMDA approvals for lightweight transportable models.
- Walkers:Standard folding and rollator designs with hand brakes and seating surfaces. ISO 10993 biocompatibility testing for grip materials creates laboratory queue bottlenecks.
- Crutches:Axillary and forearm designs with carbon fiber or aluminum construction. Lowest certification burden among device types enables rapid Southeast Asian manufacturing entry.
Wheelchairs sit at the top of the volume ranking, with scooters climbing the fastest.
End User:
Procurement authority and reimbursement access shape demand concentration across patient populations and institutional buyers.
- Individuals with Disabilities:Private insurance and vocational rehabilitation funding support premium powered wheelchair acquisition in the United States. Out-of-pocket expenditure dominates in markets lacking national coverage frameworks.
- Elderly Citizens:Japan's super-aged demographic drives METI-subsidized smart device procurement. Home healthcare transition in Germany expands rental and lease models for foldable electric units.
- Rehabilitation Facilities:Integrated delivery networks in the United States consolidate vendor lists around full-service equipment-maintenance-training bundles. Outpatient care pivot demands portable systems with remote monitoring compatibility.
- Mobility Clinics:Specialized seating and positioning assessment centers prescribe custom-configured wheelchairs. ISO 13485 certification requirements filter supplier participation.
Elderly citizens command the largest addressable population base, with rehabilitation facilities expanding procurement fastest.
Technology:
Software-defined architectures and connectivity features trigger cybersecurity documentation requirements that extend clearance timelines.
- Manual:Purely mechanical systems with no electrical components. Southeast Asian aluminum-frame production displaces electric units in price-sensitive emerging markets. Minimal regulatory friction enables rapid geographic expansion.
- Electric:Brushless DC motor systems with joystick or sip-and-puff control interfaces. Lithium iron phosphate chemistry extends range by 40% while reducing charging cycles. FDA 510(k) software validation for connected variants adds 8-14 months to launch timelines.
- Hybrid:Manual-electric convertible systems for flexible rehabilitation facility utilization. German clinic networks specify these for indoor-outdoor patient transitions.
- Smart Devices:IoT-embedded wheelchairs and walkers with sensor fusion and remote diagnostics capability. EU MDR Unique Device Identification mandates force serialization investments. Telehealth integration opens predictive maintenance subscription revenue.
Manual technology retains volume leadership, with smart devices tracing the steepest expansion trajectory.
Distribution Channel:
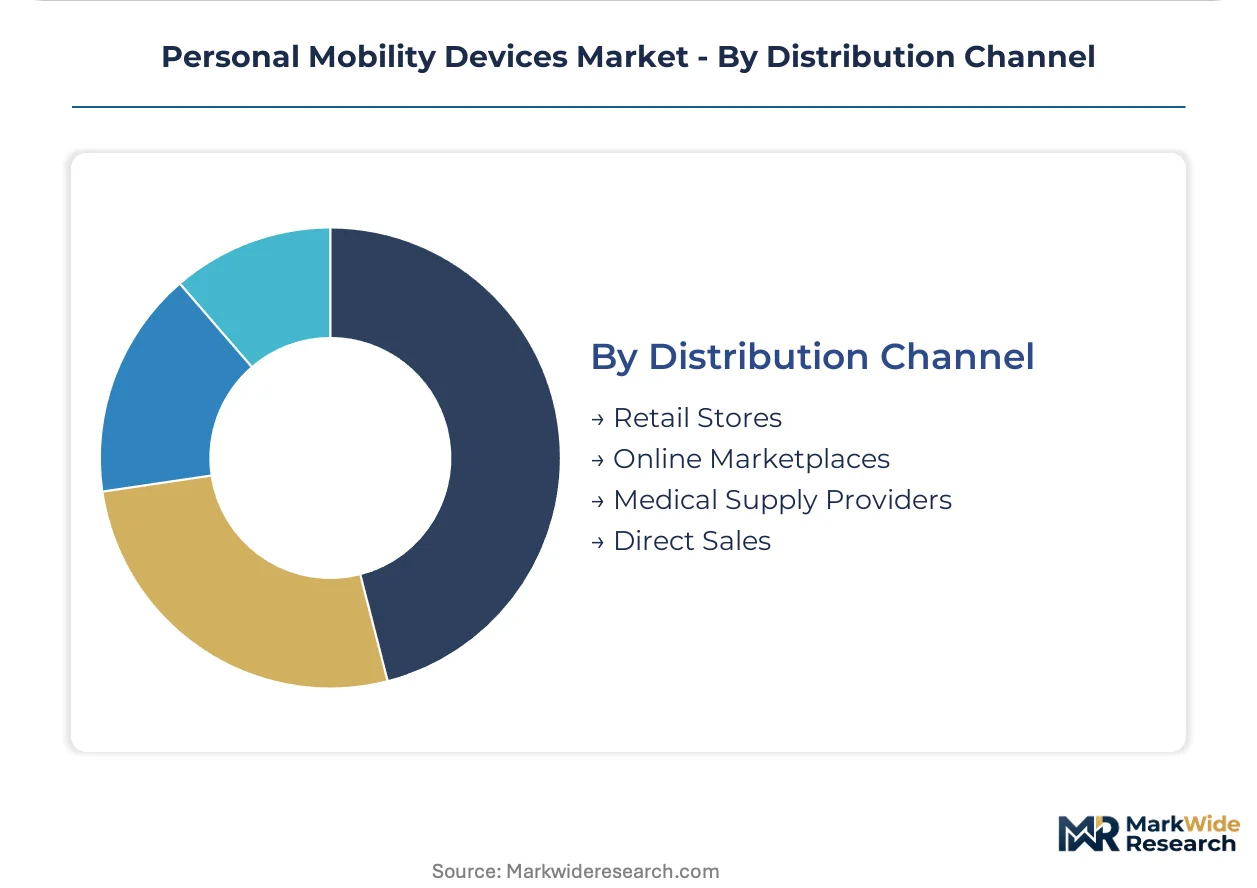
Channel selection determines margin structure, customer service obligations, and exposure to procurement consolidation trends.
- Retail Stores:Consumer scooter and basic walker sales through mass-market and specialty mobility outlets. Pride Mobility Products anchors this channel with broad geographic coverage.
- Online Marketplaces:Direct-to-consumer growth in manual devices and accessories. Cybersecurity standards for connected devices complicate cross-border fulfillment.
- Medical Supply Providers:Independent durable medical equipment distributors face share loss to manufacturer-direct contracts. Hospital procurement consolidation around full-service partners reshapes competitive dynamics.
- Direct Sales:Manufacturer contracts with United States integrated delivery networks and German rehabilitation clinic chains. ISO 13485 certification enables single manufacturing lines to serve FDA, MDR, and PMDA markets simultaneously.
Medical supply providers historically dominated transaction volume, with direct sales gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ohio-based Invacare Corporation anchors North American manufacturing capacity for powered mobility systems serving institutional and home-based care transitions.
United States
Medicare Advantage reimbursement coding and integrated delivery network procurement consolidation drive demand for full-service equipment bundles. FDA 510(k) software validation requirements extend connected device clearance timelines by 8-14 months. Cleveland and Elyria, Ohio, host concentrated manufacturing for electric wheelchairs serving hospital system contracts.
Germany
Outpatient rehabilitation clinic expansion and elderly home healthcare transitions accelerate procurement of foldable electric systems. EU MDR clinical evidence mandates and Unique Device Identification serialization requirements reshape supplier compliance investments. North Rhine-Westphalia rehabilitation networks specify portable units compatible with standard vehicle transport.
Japan
METI subsidies for assistive technology procurement target the super-aged 65-plus demographic with fast-track PMDA approvals. The Ministry of Economy, Trade and Industry drives smart mobility device adoption through direct consumer subsidies. Tokyo and Osaka medical device clusters concentrate distribution infrastructure for lithium-ion powered wheelchairs.
China
Domestic aging population and rehabilitation infrastructure build-out expand addressable demand for cost-optimized manual and electric systems. NMPA medical device registration and dual carbon goals influence battery chemistry selection and manufacturing location decisions. Jiangsu and Zhejiang provinces host aluminum-frame production serving price-sensitive emerging market exports.
United Kingdom
NHS continuing healthcare assessments and community equipment services reshape procurement toward rental and lease models for elderly users. MHRA post-Brexit regulatory alignment with EU MDR standards maintains market access continuity. West Midlands manufacturing retains capacity for manual wheelchair fabrication serving domestic and European distribution.
Personal Mobility Devices Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek embedded systems engineering talent and telehealth platform integration capabilities. The vendor base clusters around three tiers: full-service institutional contractors with ISO 13485 certification, retail-focused consumer scooter specialists, and regional manual device fabricators. Archetypes include integrated delivery network partners, direct-to-consumer distributors, and contract manufacturers for Southeast Asian aluminum-frame production. M&A activity and technology licensing agreements represent the primary competitive vectors as firms address firmware development bottlenecks and cybersecurity documentation requirements.
Among North American full-service providers, Invacare Corporation and Pride Mobility Products exemplify divergent channel strategies, with the former anchoring institutional procurement contracts and the latter occupying retail distribution positions. German prosthetics-adjacent specialist Ottobock represents the technology-intensive archetype, leveraging advanced materials science positioning within rehabilitation facility networks. These three entities illustrate how geographic origin and corporate structure correlate with regulatory pathway selection and end-user segment focus.
| Leading Market Players |
|---|
| Invacare Corporation |
| Ottobock |
| Drive DeVilbiss Healthcare |
| Sunrise Medical |
| Permobil |
| GF Health Products |
| Pride Mobility Products |
| Medline Industries |
| Arjo |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-cleared connected wheelchairs and commodity manual frames manifests in both margin structures and sourcing footprints, with premium tiers commanding bundled service contracts while economy segments compete on aluminum-frame landed cost from Southeast Asian fabricators.
Pricing Analysis
Input-cost pass-through from lithium iron phosphate cells and brushless DC motors compresses margins in mid-tier electric wheelchairs, forcing manufacturers to absorb volatility or renegotiate hospital system contracts. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) software validation and MDR clinical evidence requirements driving differentiation. Cost compression in economy manual devices intensifies because Chinese aluminum extrusion and Vietnamese frame assembly displace electric units in price-sensitive procurement. Rehabilitation facilities and integrated delivery networks show lowest price sensitivity due to bundled maintenance contracts, while individual elderly consumers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks and German rehabilitation clinic chains mandate qualified suppliers for lithium-ion cells across China, South Korea, and Japan, with secondary qualification for rare earth magnet refiners. Brushless motor production draws from neodymium processing concentrated in Chinese refiners, carbon fiber frames from Japanese and German composite specialists, and aluminum extrusions from Jiangsu and Zhejiang provinces. Single-source vulnerability in rare earth magnet supply creates input cost volatility that ripples through powered wheelchair drivetrain economics. Distribution runs through manufacturer-direct contracts with hospital procurement departments, bypassing independent durable medical equipment distributors facing share erosion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
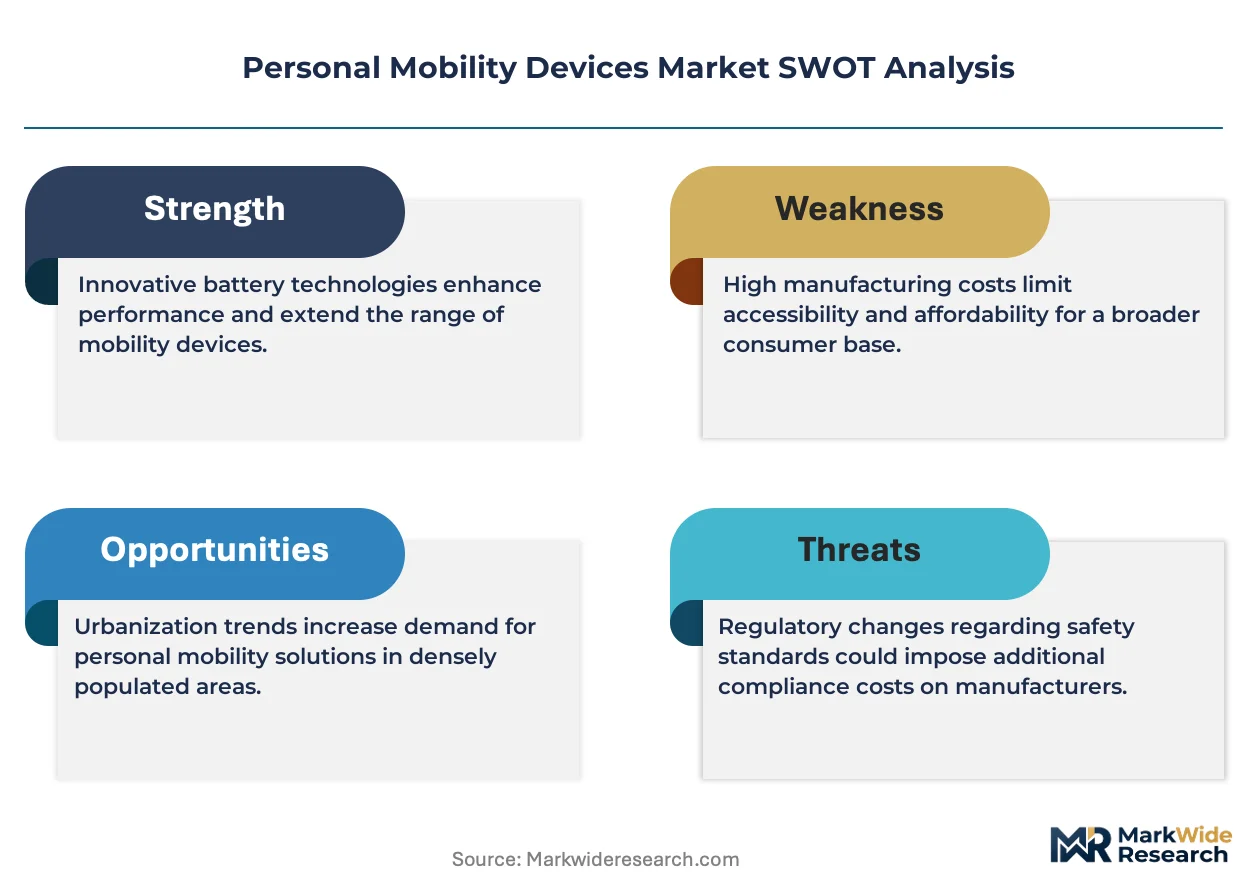
This market reads as a late-cycle quality story, justified by the shift from institutional procurement to home-based care demanding ISO 13485-certified portable systems with embedded IoT diagnostics.
For Market Incumbents: Hedge against margin compression in commodity manual frames by deepening backward integration into lithium iron phosphate cell pack assembly and captive brushless motor production. Channel control through exclusive rehabilitation facility partnerships in Germany and United States integrated delivery networks protects pricing power against Southeast Asian aluminum-frame entrants. For New Entrants and Emerging Players: Sensor fusion firmware with predictive maintenance capabilities offers a technology-first wedge into the telehealth-integrated mobility segment underserved by legacy hardware manufacturers. White-space targets include METI-subsidized smart device procurement in Japan's super-aged demographic and foldable electric wheelchair rental models for German outpatient clinic expansion. Direct sales to mobility clinics bypasses consolidated hospital procurement barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification scarcity meets firmware development bottlenecks, favoring acquisition of embedded systems engineering teams over pure manufacturing assets. Long-term viability over a decade horizon hinges on software-defined control architectures generating recurring telemetry revenue. Watch PMDA fast-track approval velocity for smart mobility devices as inflection indicator for Japanese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Convergence | Enables single manufacturing lines to serve FDA, MDR, and PMDA compliance requirements simultaneously. |
| Telehealth Platform Integration | Opens predictive maintenance subscriptions through embedded IoT sensor diagnostics in rehabilitation facility networks. |
| Lithium-Ion Battery Chemistry Advancement | Extends powered wheelchair range through lithium iron phosphate cells while reducing charging cycle degradation. |
| Reimbursement Strategy Development | Aligns product specifications with Medicare Advantage coding updates and METI subsidy eligibility criteria. |
| Hospital System Partnership | Secures manufacturer-direct contracts with United States integrated delivery networks consolidating vendor lists. |
Research Approach
Direct dialogue with rehabilitation facility procurement directors, biomedical engineers, GPO contracts managers, and durable medical equipment distributors grounded qualitative findings, cross-referenced against FDA 510(k) filings, EU MDR clinical evidence databases, CMS Medicare reimbursement codes, and METI subsidy program disclosures. Bottom-up unit economics from individual device categories and top-down macro demand drivers triangulated market sizing across the analysis window.
Segment-level projections across device type, technology tier, end-user population, and distribution channel fed into analytical framework outputs over the projection horizon. CAGRs derived from regression analysis of historical reimbursement expansion, aging demographic penetration curves, and lithium-ion battery cost decline trajectories. Key inputs included outpatient care transition velocity in Germany, PMDA fast-track approval rates for connected devices, and neodymium magnet price volatility indices.
The model holds under stable regulatory reimbursement frameworks and continued lithium iron phosphate cell supply expansion; deviation in FDA cybersecurity documentation timelines or Chinese rare earth export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
Japan Automotive EPS Market