
 X-By-Wire Systems Market | 2026-2036
X-By-Wire Systems Market Size, Share, and Industry Trends Forecast 2026-2036
X-By-Wire Systems Market Intelligence
German Tier-1 suppliers is pivoting toward integrated x-by-wire module production to serve accelerating OEM demand for chassis electrification. Continental AG leverages its braking and electronics portfolio to anchor full-system contracts across European and North American vehicle programs. Robert Bosch GmbH sustains R&D intensity in redundant actuator architectures for Level 3 and Level 4 autonomous driving platforms. ZF Friedrichshafen AG competes through its integrated chassis division, combining steering, braking, and suspension control into unified domain controllers.
X-by-wire systems replace mechanical linkages with electronic control units, sensors, and electromechanical actuators to transmit driver or autonomous commands to vehicle subsystems, typically operating with signal latency below 10 milliseconds and SIL 2 or ASIL D functional safety ratings. Their primary purpose is to enable precise, software-defined vehicle dynamics while reducing weight and packaging constraints. Brake control modules command the largest installed base among product types, reflecting established production volumes for electronic stability control and regenerative braking integration. Optical sensing technology is gaining traction in aerospace applications where electromagnetic interference resistance outweighs cost premiums. OEMs represent the most concentrated end-user category, as vehicle assemblers internalize system-level validation and calibration responsibilities.
NHTSA mandates FMVSS compliance for electronic control systems in U.S. passenger vehicles, while the EPA enforces emissions thresholds that favor weight-reducing x-by-wire architectures. Germany's KBA enforces UNECE regulations including R79 for steering equipment and R13-H for braking systems, directly shaping product certification requirements for suppliers serving European type approval. Stakeholders must monitor how functional safety standards evolve alongside autonomous driving permitting frameworks across multiple jurisdictions.
Market Dynamics
Chassis electrification is compressing development cycles as OEMs abandon mechanical linkages for software-defined architectures governed by ASIL D safety ratings and sub-10 millisecond latency requirements.
Growth Catalysts
- UNECE R79 and R13-H mandates:Germany's KBA enforces stringent steering and braking equipment standards that accelerate OEM migration to certified x-by-wire platforms for European type approval.
- Autonomous driving readiness:Level 3 and Level 4 vehicle programs demand redundant actuator architectures that only electronic control systems can deliver.
- Commercial vehicle electrification:Fleet operators in long-haul trucking are specifying steer-by-wire and brake-by-wire to optimize packaging for battery-electric powertrains.
Market Restraints
- Silicon carbide supply concentration:Power electronics for high-torque actuators depend on SiC substrates sourced primarily from a narrow supplier base in East Asia.
- Functional safety certification costs:ISO 26262 ASIL D validation for brake and steering modules imposes multi-million-dollar development burdens that exclude smaller Tier-2 suppliers.
- Mechanical fallback requirements:FMVSS provisions in the United States still mandate redundant mechanical pathways in certain vehicle classes, limiting full x-by-wire deployment.
Strategic Opportunities
- Off-highway machinery conversion:Mining and agricultural equipment manufacturers in Australia and Brazil are piloting steer-by-wire for cab-isolation and precision guidance.
- Domain controller integration:Unified chassis control combining steering, braking, and suspension into single ECUs creates service contract opportunities beyond component supply.
- IRA clean vehicle credits:U.S. domestic content thresholds for battery-electric commercial vehicles incentivize local x-by-wire module production.
Industry Challenges
- Embedded systems cybersecurity:ISO/SAE 21434 compliance for connected chassis actuators demands scarce firmware security engineering talent.
- Legacy platform coexistence:Hybrid vehicle programs must integrate electronic and hydraulic braking architectures, doubling validation scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-By-Wire Systems Market |
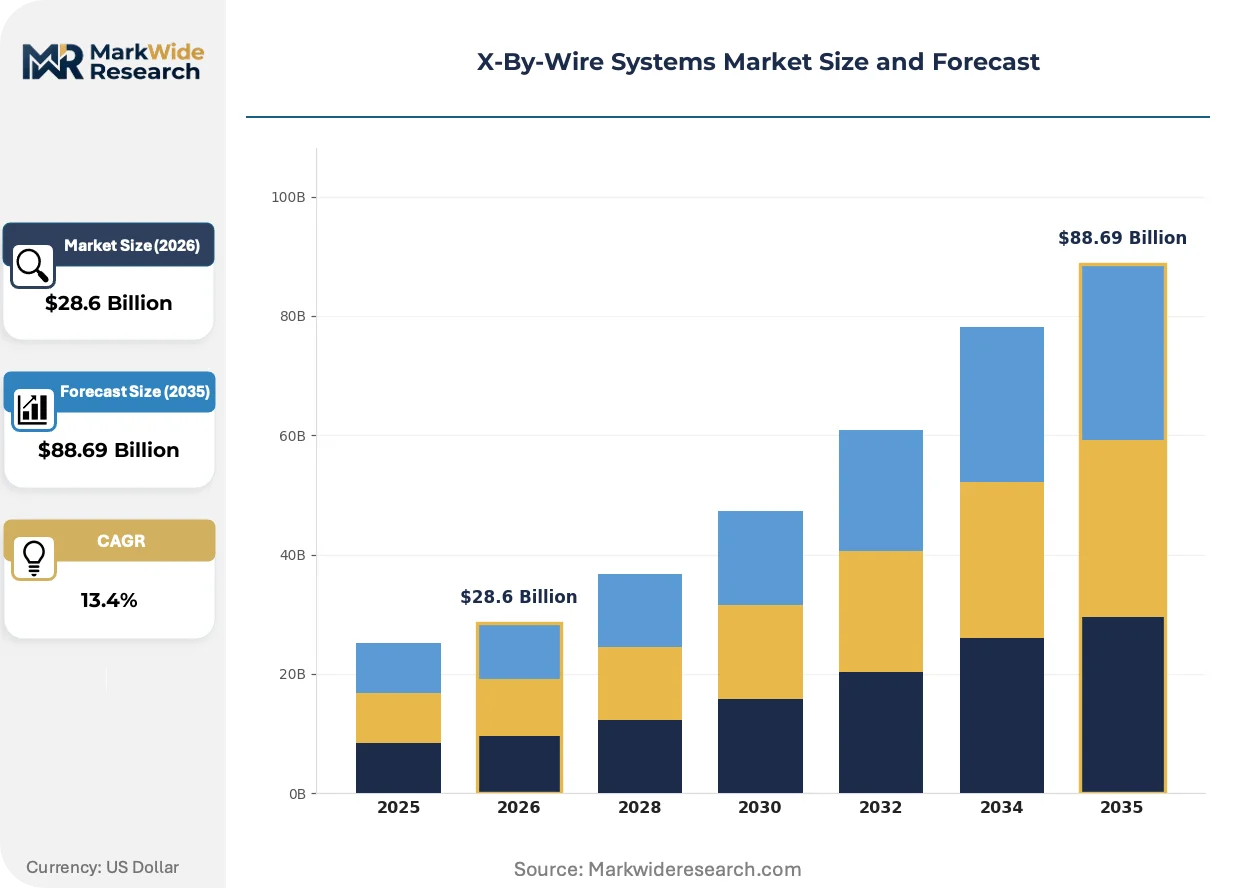
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $88.69 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steering Control, Brake Control, Throttle Control, Shift Control Technology: Electrical, Magnetic, Optical, Hydraulic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Automotive, Aerospace, Marine, Industrial |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Infineon Technologies AG, JTEKT Corp., Aptiv PLC, Nexteer Automotive, Denso, Hitachi Astemo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-By-Wire Systems Market Strategic Shifts & Innovations
Signal processing architectures are replacing mechanical fidelity with computational precision, enabling vehicle dynamics that software updates can modify without hardware changes.
Optical position sensing is rewriting actuator feedback loops in aerospace and defense applications where electromagnetic interference immunity outweighs cost premiums. Boeing and Airbus suppliers are qualifying fiber-optic encoders for flight-critical surfaces. This displacement of magnetic resolvers is compressing the addressable market for traditional sensor suppliers.
NHTSA's updated FMVSS interpretation for electronic control systems is forcing brake-by-wire suppliers to demonstrate fail-operational performance across thermal runaway scenarios. The agency's 2024 guidance documents explicitly reference ASIL D decomposition strategies. Tier-1 suppliers serving U.S. passenger vehicle programs are re-architecting power supply redundancy to satisfy these thresholds.
Long-term service agreements are displacing spot procurement for x-by-wire modules as OEMs transfer lifetime warranty risk to subsystem suppliers. Volkswagen and BMW are negotiating fifteen-year performance contracts covering steering and braking electronics. This shift concentrates purchasing power with chassis integrators capable of assuming residual value risk.
X-By-Wire Systems Market Segmentation
X-by-wire architectures fragment across multiple technical and commercial dimensions. Product specifications, sensing modalities, and customer procurement patterns create distinct competitive arenas with diverging margin profiles and certification burdens.
Product Type:
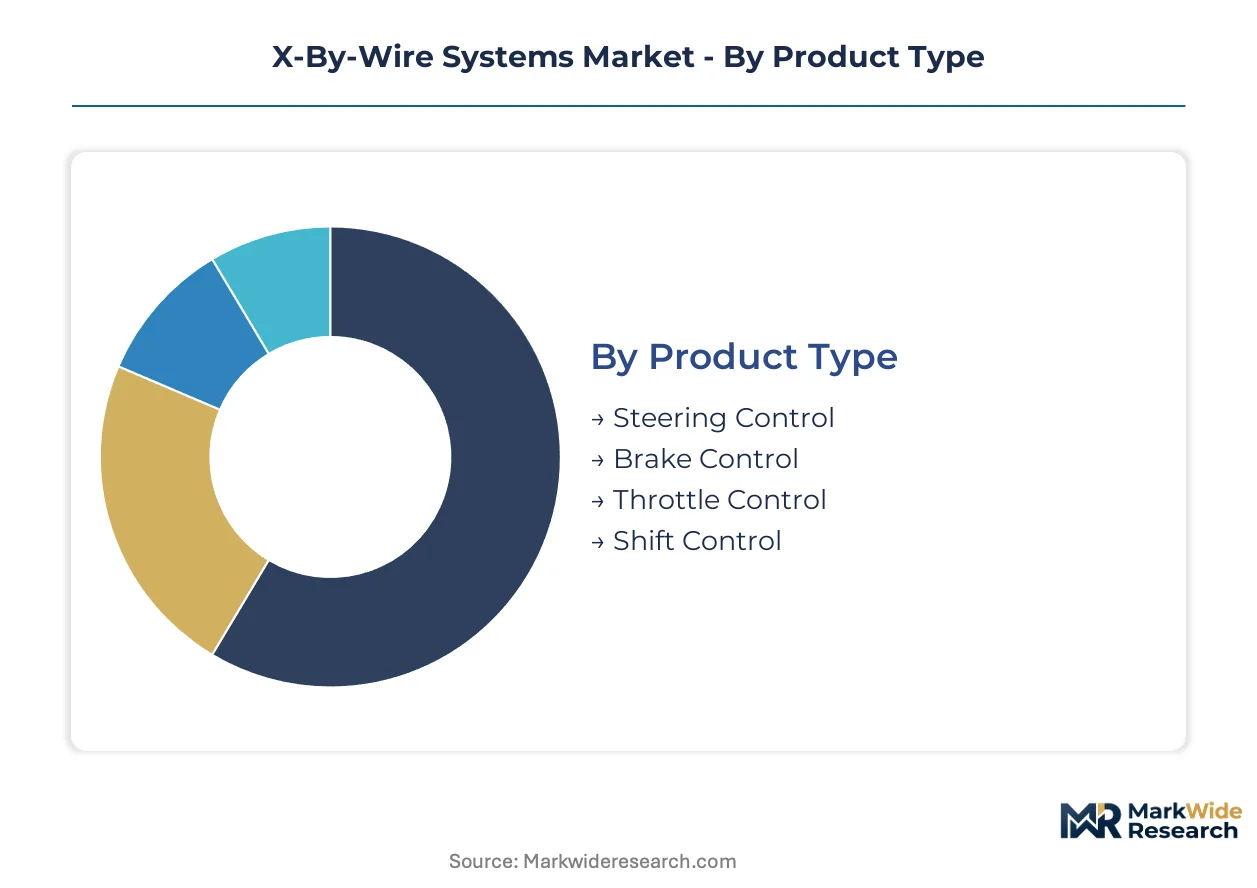
Brake control modules command the largest production volumes, while steering control attracts the steepest safety premiums and longest development cycles.
- Brake Control:Electronic stability control and regenerative braking integration anchor established production lines. Commercial vehicle OEMs in Germany and the United States specify these modules for battery-electric powertrain packaging optimization.
- Steering Control:Redundant actuator architectures enable Level 3 and Level 4 autonomous driving platforms with sub-10 millisecond latency requirements. BMW, Mercedes-Benz, and Volkswagen integrate these systems into next-generation electric vehicle lineups.
- Throttle Control:Drive-by-wire electronic throttle bodies dominate passenger vehicle applications with mature supply chains.
- Shift Control:Transmission control modules support automated manual and dual-clutch architectures in performance vehicle segments.
Mature deployment sits with Brake Control. Newer deployment is concentrated in Steering Control.
Technology:
Electrical sensing dominates automotive cost structures, while optical methods capture aerospace premiums where electromagnetic immunity justifies expense.
- Electrical:Hall-effect and inductive position sensors serve high-volume automotive programs with proven reliability under thermal cycling. Continental AG and Robert Bosch GmbH anchor their chassis portfolios on electrical feedback architectures for European and North American OEM contracts.
- Optical:Fiber-optic encoders eliminate electromagnetic interference vulnerability in flight-critical surfaces. Boeing and Airbus suppliers qualify these systems for aerospace actuation where signal integrity outweighs cost premiums.
- Magnetic:Resolver-based feedback persists in heavy-duty commercial vehicles requiring robustness against contamination.
- Hydraulic:Electro-hydraulic backup systems satisfy FMVSS mechanical fallback mandates in certain U.S. vehicle classes.
Electrical architectures scale fastest in automotive volume programs. Optical deployment is climbing the fastest in aerospace and defense applications.
End User:
System-level validation responsibilities concentrate purchasing power with vehicle assemblers, while Tier-1 suppliers capture module integration value.
- OEMs:Vehicle manufacturers internalize calibration, homologation, and lifetime warranty risk for x-by-wire platforms. Volkswagen and BMW negotiate fifteen-year performance contracts covering steering and braking electronics.
- Tier-1 Suppliers:Chassis integrators assume residual value risk through long-term service agreements. ZF Friedrichshafen AG competes via unified domain controllers combining steering, braking, and suspension control.
- Aftermarket Providers:Replacement modules serve collision repair and retrofit applications with shorter certification cycles.
- Vehicle Assemblers:Contract manufacturers in emerging electric vehicle programs source pre-validated subsystems to compress development timelines.
Procurement authority concentrates with OEMs for new vehicle programs. Aftermarket channels expand most quickly in collision-dense metropolitan fleets.
Application:
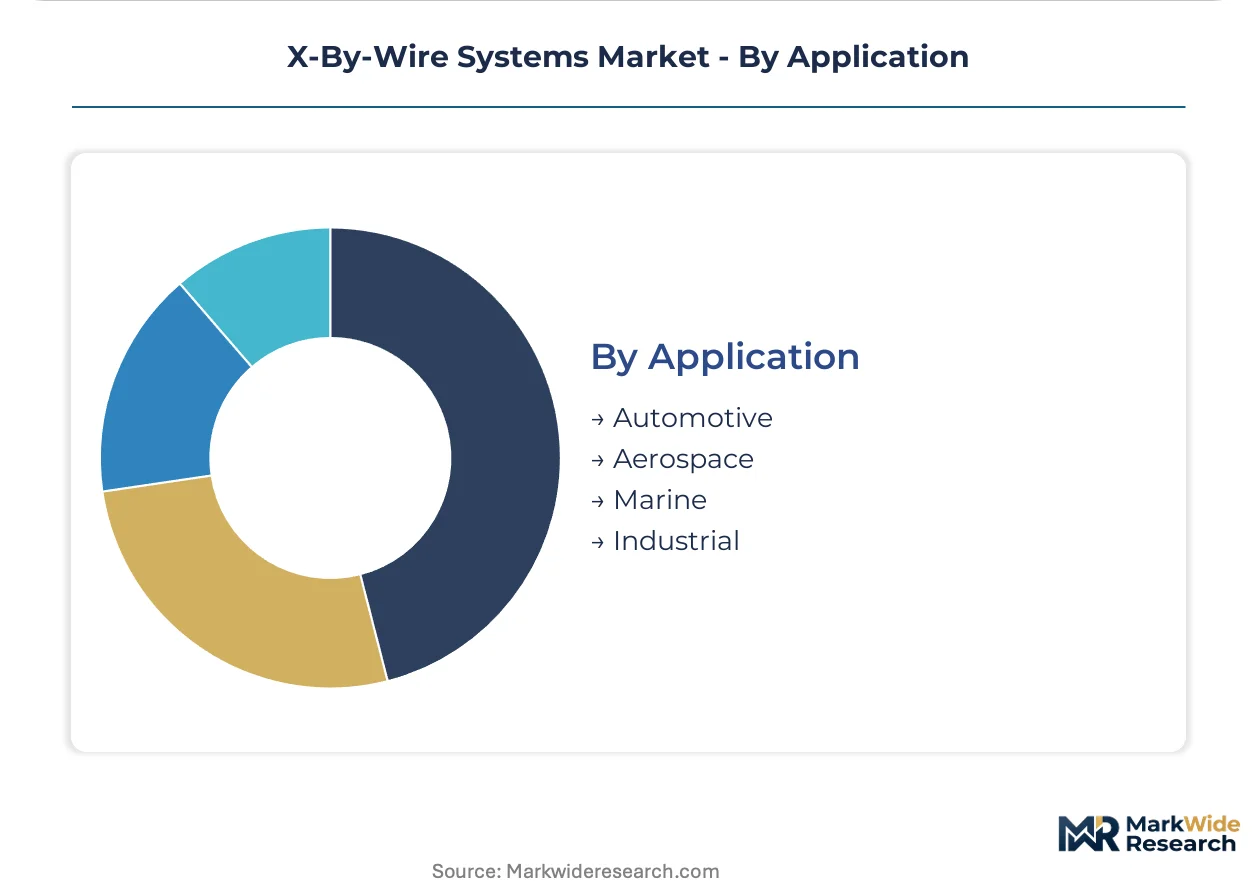
Automotive applications absorb the majority of production capacity, while aerospace and marine segments extract premium pricing for specialized reliability requirements.
- Automotive:Passenger and commercial vehicle chassis electrification drives steer-by-wire and brake-by-wire adoption. EPA emissions thresholds and NHTSA FMVSS compliance shape product specifications for U.S. market entry.
- Aerospace:Flight-critical surface actuation demands fail-operational performance with optical sensing immunity. UNECE regulations do not govern this segment; FAA certification protocols apply instead.
- Marine:Vessel control systems adopt electronic actuation for bridge integration and autonomous navigation support.
- Industrial:Mining and agricultural equipment in Australia and Brazil pilot steer-by-wire for cab isolation and precision guidance.
Automotive represents the established volume base. Industrial applications are gaining share fastest in off-highway machinery conversion programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German silicon carbide substrate processing and U.S. rare earth magnet refining anchor the geographic footprint for x-by-wire actuator components. Supply chain proximity to automotive OEM engineering centers dictates module assembly location decisions across the forecast window.
Germany
BMW, Mercedes-Benz, and Volkswagen integrate steer-by-wire platforms into next-generation electric vehicle lineups with accelerated development cycles. Germany's KBA enforces UNECE R79 and R13-H mandates for steering and braking equipment standards. The Stuttgart engineering corridor concentrates Continental AG and Robert Bosch GmbH chassis development facilities.
United States
Commercial vehicle OEMs specify brake-by-wire architectures to optimize battery-electric powertrain packaging for long-haul trucking applications. NHTSA mandates FMVSS compliance with explicit ASIL D decomposition strategies for electronic control systems. Michigan's automotive supplier corridor hosts validation laboratories serving Detroit Three electrification programs.
Japan
Denso and Hitachi Astemo sustain R&D intensity in redundant actuator architectures for Level 3 autonomous driving platforms. METI industrial policy supports domestic semiconductor substrate production for power electronics. The Nagoya manufacturing belt concentrates precision actuator component fabrication for Asian OEM supply.
China
Domestic electric vehicle assemblers source pre-validated x-by-wire subsystems to compress development timelines for export-ready platforms. MIIT enforces GB standards for automotive electronic control system reliability. The Yangtze River Delta clusters module assembly operations serving BYD and NIO production facilities.
South Korea
Hyundai and Kia integrate brake-by-wire modules into dedicated electric vehicle architectures with regenerative braking optimization. MFDS automotive safety guidelines align with international functional safety certification requirements. The Seoul Capital Area hosts Infineon Technologies AG regional design centers for power electronics.
X-By-Wire Systems Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue domain controller integration and long-term service contract structures. The vendor base concentrates among chassis integrators capable of assuming lifetime warranty risk across fifteen-year performance agreements. Three strategic archetypes dominate: full-system contractors anchoring European and North American OEM programs, redundant actuator specialists serving autonomous driving platforms, and unified domain controller providers combining steering, braking, and suspension control. Competitive moves center on strategic partnerships for silicon carbide substrate security and geographic expansion to satisfy U.S. domestic content thresholds.
Within the full-system contractor tier, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG represent the established European anchor positions. Continental AG exemplifies the braking-electronics portfolio leverage archetype for chassis electrification contracts. Robert Bosch GmbH occupies a position within the redundant architecture development segment for higher-autonomy platforms. ZF Friedrichshafen AG anchors the integrated chassis division approach combining multiple control domains into unified electronic control units.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Infineon Technologies AG |
| JTEKT Corp. |
| Aptiv PLC |
| Nexteer Automotive |
| Denso |
| Hitachi Astemo |
| Others |
Cost & Logistics Intelligence
EPA emissions thresholds and NHTSA functional safety mandates gate qualified supply for premium-tier x-by-wire modules, concentrating pricing power with Tier-1 suppliers holding ASIL D certification and silicon carbide substrate access. Buyers without fifteen-year performance contract structures face margin compression as warranty risk transfers concentrate procurement authority.
Pricing Analysis
Warranty and service bundling separates contract structures in this market, with fifteen-year performance agreements covering steering and braking electronics commanding premium positioning against spot procurement. Three-tier pricing stratifies across ASIL D-certified full-system contractors, redundant actuator specialists for autonomous platforms, and economy-tier aftermarket replacement modules. Price differentiation rests on certification grade and geographic proximity to OEM engineering centers, with German and U.S. domestic content compliance carrying substantial premiums. Cost compression in standard-tier brake control modules is intensifying because commercial vehicle electrification programs are scaling volume expectations without proportional safety rating relaxation.
Supply Chain Analysis
U.S. domestic content thresholds under IRA clean vehicle credits are reshaping sourcing patterns, pressuring module assembly relocation away from established East Asian silicon carbide substrate suppliers. Geographic supply concentrates in Germany for precision actuator engineering, Japan for rare earth magnet refining, and China for substrate processing and module fabrication. Raw material dependencies draw from silicon carbide wafers, rare earth permanent magnets, and high-temperature polymer housings. Single-source vulnerability in SiC substrate supply from East Asia creates structural risk exposure. Distribution runs through Tier-1 chassis integrators assuming lifetime warranty risk for OEM direct supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
X-by-wire module production capacity is supply-constrained by silicon carbide substrate bottlenecks, propping pricing for qualified suppliers with secured substrate offtake.
For Market Incumbents: Deepen backward integration into silicon carbide substrate supply through strategic partnerships with East Asian wafer producers or captive capacity investments in Germany and the United States. Secure ASIL D certification renewal ahead of NHTSA's evolving FMVSS interpretation to defend against emerging domain controller specialists capturing unified chassis contracts. Prioritize long-term service agreement expansion with Volkswagen and BMW to lock in fifteen-year performance contract structures before competitive rebidding cycles accelerate. For New Entrants and Emerging Players: Begin with off-highway machinery conversion programs in Australia and Brazil, where steer-by-wire pilot deployments for mining and agricultural cab-isolation applications face limited incumbent saturation. Target industrial equipment manufacturers with pre-validated subsystem offerings that compress customer development timelines without requiring full OEM homologation investment. Pursue geographic manufacturing footprint establishment in the U.S. Southeast to satisfy IRA domestic content thresholds for battery-electric commercial vehicle credits. For Investors and Strategic Acquirers: NHTSA's 2024 FMVSS guidance explicitly referencing ASIL D decomposition strategies is the leading indicator that redundant actuator architecture specialists will consolidate ahead of Level 3 autonomous vehicle permitting frameworks. Over the medium-term projection horizon, acquisition targets should focus on mid-cap chassis integrators with unified domain controller capabilities combining steering, braking, and suspension control. Monitor Tier-1 supplier announcements of silicon carbide substrate security partnerships as the leading signal of sustained margin positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Security Partnership | Continental AG and Robert Bosch GmbH anchor European supply resilience against East Asian concentration risk. |
| Domain Controller Integration | ZF Friedrichshafen AG combines steering, braking, and suspension into unified ECUs capturing service contract value. |
| Long-Term Performance Contract Negotiation | Volkswagen and BMW transfer fifteen-year warranty risk to subsystem suppliers concentrating purchasing power. |
| Optical Sensing Technology Qualification | Boeing and Airbus suppliers deploy fiber-optic encoders for electromagnetic immunity in flight-critical surfaces. |
| U.S. Domestic Content Manufacturing Footprint | IRA clean vehicle credit thresholds incentivize local module production for battery-electric commercial vehicles. |
Research Approach
Document review covered regulatory filings from NHTSA and EPA, UNECE R79 and R13-H technical standards, and OEM supplier contract disclosures, complemented by interviews with Tier-1 chassis procurement directors, OEM platform engineers, aftermarket distributors, and functional safety certification specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC supplier filings, and customs trade records for silicon carbide substrate flows. Bottom-up module shipment estimates and top-down OEM electrification program scaling were triangulated to anchor projections.
Installed base and revenue outputs across the analysis window reflect segmentation by product type, technology modality, end-user procurement pattern, and regional regulatory cluster. Analytical framework modeling incorporated vehicle class, propulsion architecture, content per vehicle, and OEM tier as core dimensions. CAGRs were derived from production volume trajectories weighted by safety certification tier premiums and substrate cost curve assumptions. Forecast inputs included commercial vehicle electrification fleet specifications and autonomous driving readiness timelines by jurisdiction.
Silicon carbide supply disruption, NHTSA regulatory reinterpretation, and autonomous driving permitting delays are the dominant revision risks to installed base and value projections. Forecasts reflect documented assumptions regarding substrate cost curves and OEM program launch sequencing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
US Automotive EPS Market